LIVEDaily Stock Market Report (Tue 17th Nov 2026) - SOM, DPLM

Good morning!
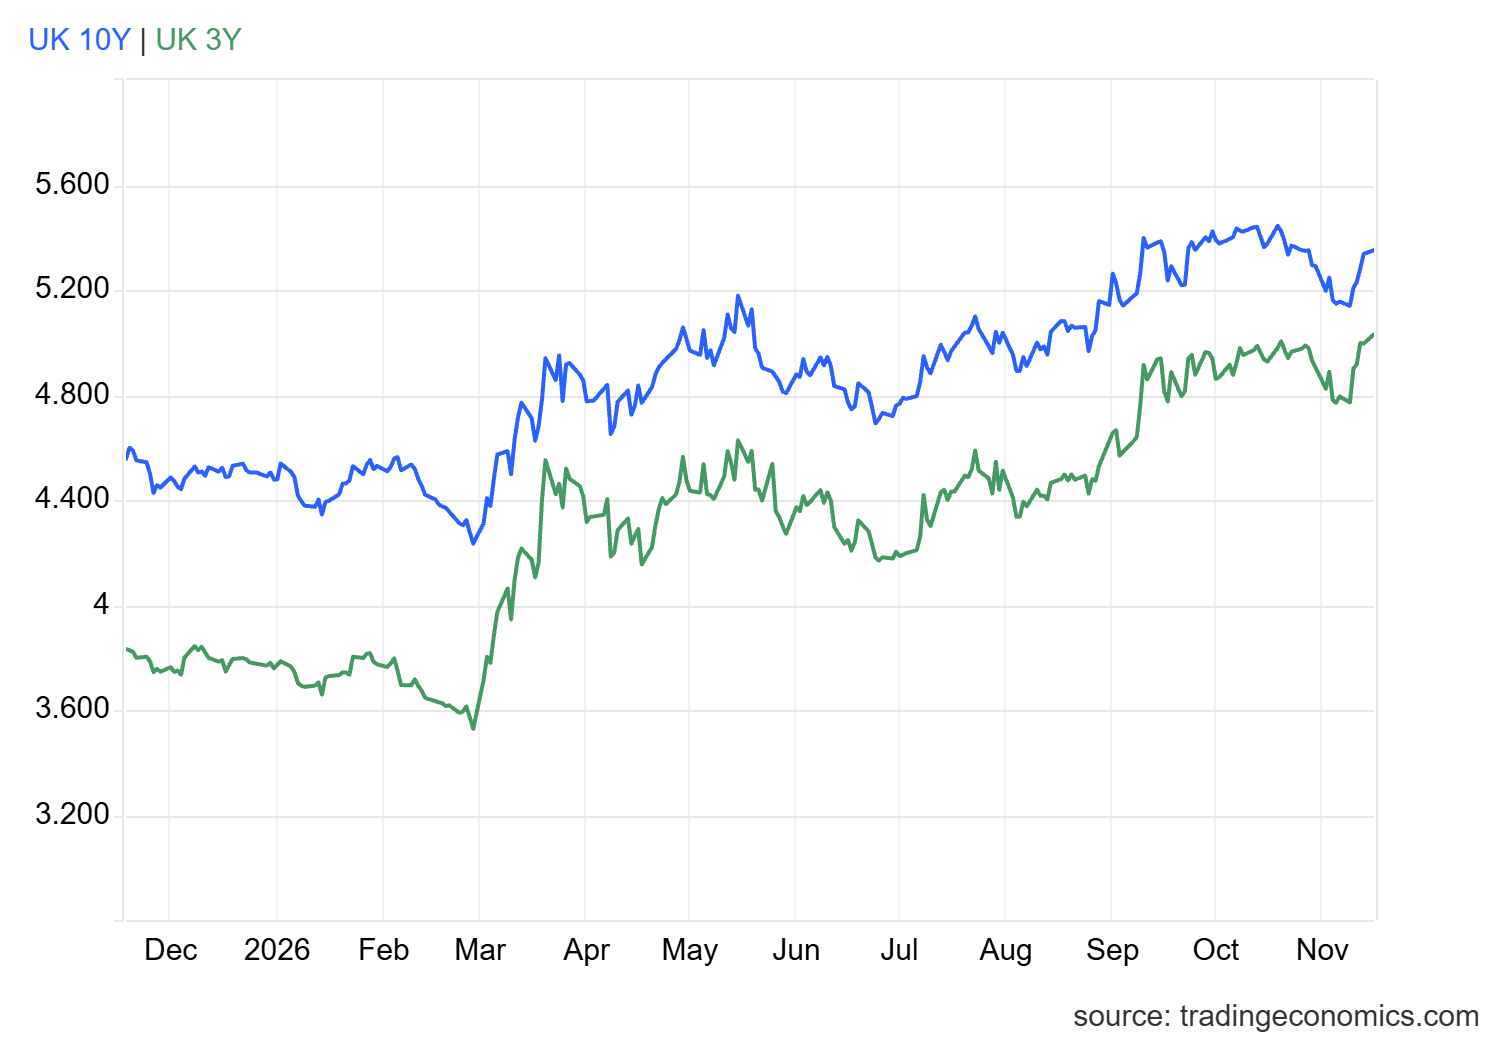
The yield on three-year UK government bonds topped 5% yesterday, outpacing recent growth in the yield on longer-term debt. This appears to be a sign that the market is expecting further interest rate rises to help cool inflation.
Elsewhere, NVIDIA (NSQ:NVDA) is likely to make headlines again today as Jensen Huang's successor, interim CEO Colette Kress, makes her first appearance in front of investors at the chip company's quarterly earnings.
Consensus estimates suggest Nvidia will report a 92% rise in quarterly sales to $109.5bn, with $60bn in net profit. These are staggering numbers and I would guess the longevity of the current AI spending boom is likely to remain a hot topic.
Overnight market movements:
The FTSE is down 0.8% at 10,803
S&P 500 is down 0.2% at 7,404
Brent crude (January) is down 0.6% at $91.92/bbl
Gold is up 0.6% at $3,871/oz
Bitcoin is down 0.7% at $64,393
Ed Sheldon joins me (Roland) today.
The table is now complete.
Name (Mkt Cap) | RNS | AI Summary | Notes |
|---|---|---|---|
Imperial Brands (LON:IMB) (£22.4bn | SR73) | Adjusted operating profit rose 3.7% in the year to Sep 2026, but reported operating profit fell 10.2% after the Delaware settlement and strategy costs. Adjusted earnings per share rose 8.8%, and the dividend rose 4%. Management expects FY27 profit growth “at a similar level”, weighted to the second half. | ||
Diploma (LON:DPLM) (£9.6bn | SR58) | Adjusted earnings per share jumped 45% in the year to September 2026, with adjusted operating profit up 42% to £487.1m on 15% organic growth. Acquisitions lifted revenue 21%. The board expects another strong year ahead of its model, with organic growth easing to 6% and a 25.5% margin. | AMBER/GREEN = (Roland) | |
Zegona Communications (LON:ZEG) (£3.9bn | SR77) | Revenue for the period rose by 2.9% to €1,841m while Group EBITDAaL rose by 3% to €666m. One-off costs associated with refinancing meant that operating profit fell by 50% to €79m. | ||
Firstgroup (LON:FGP) (£1.2bn | SR88) | Adjusted earnings per share fell to 8.4p from 9.9p as £8m of Stirling launch and ramp-up costs offset higher First Bus profit, though management expects to "maintain adjusted EPS in FY 2027". Adjusted operating profit rose 7% to £110.5m, and adjusted net debt was £186.0m at 26 Sep. A further £50m buyback was announced, and the interim dividend rose to 2.3p. | ||
Princes (LON:PRN) (£948m | SR84) | Princes has entered into an agreement with Kraft Foods International Europe Holdings LLC (“Mondelez International”) to acquire Mondelez's French bread substitutes and cereal bars businesses, together comprising three manufacturing facilities and four established brands, Heudebert, Pelletier, Cracotte and Grany. The transaction has an enterprise value of €80 million and the business being acquired generated adj EBITDA of €17.7m in 2025. | ||
Seraphim Space Investment Trust (LON:SSIT) (£665m | SR88) | SSIT portfolio company ICEYE has approved the launch of an all-cash voluntary public tender offer through its indirect wholly-owned Italian subsidiary Iris 2 S.p.A. for all the ordinary shares of Avio, the Italian space launch and propulsion company, with the intention of taking Avio private. ICEYE is offering €41 per share, valuing Avio at c.€2.1bn. The offer represents a 21.3% premium to Avio's closing share price on 16 Nov 26. | ||
Restore (LON:RST) (£398m | SR55) | Full-year adjusted pre-tax profit is expected to be at least in line with consensus of £47.2m, after trading stayed strong in the 10 months to 31 October 2026. Information Management and Technology led further profitable growth. Cash conversion topped 80%, and the group bought back £8.9m of shares at an average 268p under its £20m programme. | ||
Synthomer (LON:SYNT) (£197m | SR91) | Anthony Fitzpatrick has been appointed as CFO and will join the business on 1 April 2027. He joins Synthomer from FTSE 100 group Croda International. | ||
Somero Enterprises (LON:SOM) (£150m | SR95) | Full-year guidance is raised again after continued positive trading. The board now expects revenue of about $100m (previously $95m) and adjusted EBITDA of about $20.5m (previously $19.5m). Year-end net cash is seen at about $34.0m. It remains mindful of tariffs, elevated interest rates and immigration policy. | GREEN = (Ed S) | |
Trifast (LON:TRI) (£120m | SR81) | Guidance has been cut: the board now expects FY27 revenue of £200–205m and underlying EBIT of £14.0–14.5m, against consensus of £214m and £18.2m. In the half, underlying EBIT rose 7.1% to £7.5m on 4.3% lower revenue, but a statutory loss of £3.0m followed £8.4m of one-off transformation costs. Net debt was £15.8m, and the 0.60p interim dividend was held. | PROFIT WARNING (Roland to do) | |
Accesso Technology (LON:ACSO) (£107m | SR89) | A seven-year deal with Premier Parks, North America's second-largest independent attractions operator, is a win for its connected software strategy. It covers ticketing and admissions, food, beverage and retail, with integrated payments and AI-powered decision tools. No contract value is disclosed, and the release does not mention any impact on expectations. | ||
Flowtech Fluidpower (LON:FLO) (£46m | SR67) | Profit expectations are cut as delays hit larger engineering projects. Adjusted EBITDA for 2026 is now expected to be about £8.5m, after flooding on site delayed the bridge projects. Revenue rose 22% in the 10 months to 31 October, and year-end net debt is expected to be about £14.5m. The board does not expect trading conditions to improve soon. | ||
Gear4music (HOLDINGS) (LON:G4M) (£44m | SR89) | Full-year EBITDA guidance is cut to about £11.5m, well below the consensus £16.0m, because paid-search traffic has dropped. Q3 revenue to date is down 13%, though first-half revenue rose 6% to £85.4m. Net bank debt rose to £24.3m, and EBITDA fell to £5.7m. | PROFIT WARNING (Ed to do) | |
Custodian Property Income Reit (LON:CREI) (£413m | SR65) | The 1.5p quarterly dividend was fully covered, in line with the target of at least 6.0p for the year. Rent reviews in the quarter to 30 September 2026 came in 32% ahead of previous passing rent, and the portfolio has a further 15% of rental growth to capture. Net asset value per share edged up to 100.3p from 100.0p. Since quarter end it bought an £11.0m portfolio mostly for new shares. | ||
Restore (LON:RST) (£398m | SR55) | Full-year adjusted pre-tax profit is expected to be at least in line with consensus of £47.2m, after trading stayed strong in the 10 months to 31 October 2026. Information Management and Technology led further profitable growth. Cash conversion topped 80%, and the group bought back £8.9m of shares at an average 268p under its £20m programme. | ||
Iqe (LON:IQE) (£398m | SR24) | Revenue guidance has been raised again, with full-year growth now expected to top 40%. Adjusted EBITDA should reach the mid-teens in £m, ahead of previously upgraded expectations, as optical communications upside for datacentre and AI infrastructure has materialised. It has no bank debt and £41.5m of cash, and says its order book coverage for 2027 is strong. | ||
Origin Enterprises (LON:OGN) (£378m | SR89) | Volumes drove a strong start to the year, with first-quarter revenue up 17% to €569.5m. Agriculture grew 18.7% on higher volumes and fertiliser pricing, while Living Landscapes rose 1.9%. Farmer sentiment stays cautious over input costs. Crop areas are expected to be broadly unchanged. | ||
Ibstock (LON:IBST) (£274m | SR21) | Ibstock has sold its Redhurst calcined clay quarry business to a major global building materials group for a total consideration of £50.1m. | ||
Afentra (LON:AET) (£173m | SR40) | Drilling at Impala-2 is underway, with first oil expected in January 2027, followed by a Pacassa SW sidetrack at the end of Q1. Net production averaged 5,869 bopd over the 10 months to 31 October 2026. Cash was $69.6m against net debt of $0.7m. Production was hit by drilling-related downtime. | ||
Pulsar Helium (LON:PLSR) (£114m | SR15) | The TSX Venture Exchange has given final approval to an $85.5m equipment deal for its Minnesota helium and CO2 plant, with $5.0m already paid from existing cash. The next $8.55m is due on 31 January 2027, which the company intends to fund from cash. The price excludes installation, taxes and tariffs, and the company is still arranging financing for the remaining payments. | ||
Allergy Therapeutics (LON:AGY) (£92m | SR5) | Plans to delist from AIM are on the table, and the two largest holders, with 87.98% between them, have said they back them. If shareholders approve at the 14 December AGM, trading ends on 22 December and the company becomes private. Only about 9% of shares are held by the public, and the board puts listing costs at over £1m a year. A matched bargain facility will offer limited trading afterwards. | ||
Critical Metals (LON:CRTM) (£80m | SR17) | Early testwork on stockpiled ore at Molulu recovered 74% of the copper. The preliminary programme, run with a potential offtake partner, tested about 300kg of ore blended to a 1.43% copper grade. The company stresses these are “early-stage preliminary results” and that further testwork and studies are required. | ||
CML Microsystems (LON:CML) (£50m | SR54) | Revenue rose 34% to £12.3m in the first half, and the board says trading is ahead of its expectations. Adjusted EBITDA jumped 77% to £2.1m, and pre-tax profit before exceptionals was £0.26m, against a £0.89m loss. The order backlog now extends beyond two years, and the board expects a full-year outcome “ahead of current market expectations”. | ||
Batm Advanced Communications (LON:BVC) (£48m | SR52) | The Transaction's closing has been pushed back to 10 December 2026, or earlier if both sides agree. The extra time is to finish "certain outstanding technical matters" and resolve points the Purchaser has raised on the Agreements. It reports no other material change to its earlier announcements on the deal. |
*Summaries are reviewed by our writing team.
Analyst notes
- Diploma (LON:DPLM)
Diploma beats expectations with 45% earnings surge while flagging slower FY27 growth
Today's earnings are slightly ahead of consensus, thanks to with organic revenue up by an impressive 15% last year. Growth looks set to slow in FY27 due to tough comparatives, but my sums suggest that today's guidance is in line with or perhaps slightly ahead of previous consensus. I'm reluctant to downgrade such a high quality business against this backdrop, so I'm leaving our view unchanged today despite the stock's demanding price tag.
- Somero Enterprises (LON:SOM)
Somero Enterprises raises FY26 guidance: now expecting revenue of $100 million
After raising its full-year FY26 guidance in July and September, Somero Enterprises has raised it again today. It now expects revenue of $100 million for the year versus previous guidance of $95 million. Given this increase to guidance, and the high StockRank of 95, I'm happy to leave Somero on a GREEN rating. However, there are some risks around interest rates and a slowdown in the US data centre buildout here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
IG group (LON:IGG)
Following the conversation yesterday, when I ask ii for a quote I'm getting a message saying I can't use an ISA to invest.
This looks like an error to me from what I know, but I'm beginning to wonder if IG group (LON:IGG) have messed up the legals.
A.
Hi
The legal structure of IG changed yesterday so has the ISIN number. Most qualification processes for ISA rely on the ISIN being set as ' qualifying' Therein lies the issue. Ask your provider to update
I'm with Hargreaves Lansdown and it still appears in my ISA account. Contact who you use to trade.
Restore (LON:RST) continues to please... at least in line I will take. Their communication is straight forward and the company has a nice growth platform supplementing organic growth with M&A. Well run and growing but not on a growth multiple leaves runway ahead which sits well looking to 2027.
One of my core holdings now, takeover maybe end game here
Would appreciate Somero Enterprises (LON:SOM) insights. I hold.
Morning David,
Thanks for the suggestion. Ed's working on Somero Enterprises (LON:SOM) as I type!
Roland
A company that once had the world at its feet. Innovative and unique product that had a use in concrete screeds all over the world, but unfortunately a typical US management with a strong parochial attitude that could see no further than the North American market.
Also note that Big Yellow (LON:BYG) reported last night after hours: https://www.investegate.co.uk/announcement/rns/big-yellow-group--byg/interim-results-/9877976
Results look OK but unexciting: another company awaiting the turn of the property market.
timarr
Pretty disastrous update from Gear4music (HOLDINGS) (LON:G4M) with revenue down in Q3 by a shocking -13% so far. What I found interesting is that they blame AI, which could have much wider read across to the whole retail sector:
'Lower paid-search traffic driving weaker trading, partly reflecting more prominent AI-generated results'
So perhaps Gear4music (HOLDINGS) (LON:G4M) is the retail canary in the coal mine.
That said, they also fail to remind the market that Q3 2026 last year was the first full quarter without their previous competitor PMT in the market. So the comparatives are also now tougher. PMT had an annual turnover of £43m so not an insignificant competitor.
deleted
And Tortoise, on some BB,pumped to high heaven in the last 12 months or so
Which one out of interest?
ADVFN, LSE
Seems they are paying Google for sponsered ads and Google AI is sending the customers elsewhere. No doubt things will settle down in time.
Gear4music (HOLDINGS) (LON:G4M)
Seems they are paying Google for sponsered ads and Google AI is sending the customers elsewhere. No doubt things will settle down in time.
perhaps but i think we are right at the peak time of year ref trading ar we not - would anyone presume that its just a blip and it will normalise? it might but could it be first signs ref subtle changes in how you need to act get business through the door. For example i think chat gpt wants traders to sign up and verify themselves - is that sign that they are trying to move stuff away from google.
should they not have been ahead of the events ref AI advertising - seems like they are perhaps reacting - the final line in that section doesnt exactly instill me with confidence.
expected to support recovery over time
If Gear4music (HOLDINGS) (LON:G4M) stuff its "good shit" i would have expected that a trend to more AI searches as we obviously have would help them - eg if their products would stand up well in like for like comparisons - well AI is great for helping you work that out.
It really did look like this company had found its mojo again somehwat and that all seems to have gone in a puff of smoke.
My s worry here would is AI making it cheaper and easier for chinese clones to get similar quality product out there at cheaper prices ?
I dont really know much about seo or their product segment but all i do know is that this update is a bit of a body blow without some real evidence that the blip is anything but short term. I do know some people who have been hit overnight ref online sales er by google rjiggs so i know it does happen and it can be addressed - seems like nightmare if its material hit for them though right here right now.