Somero Enterprises raises FY26 guidance: now expecting revenue of $100 million
Analyst’s view:
After raising its full-year FY26 guidance in July and September, Somero Enterprises has raised it again today. It now expects revenue of $100 million for the year versus previous guidance of $95 million. Given this increase to guidance, and the high StockRank of 95, I'm happy to leave Somero on a GREEN rating. However, there are some risks around interest rates and a slowdown in the US data centre buildout here.
Up 3% at 300p (£154m) - Trading Update
Concrete-levelling equipment specialist Somero Enterprises has today provided us with a brief, yet very encouraging, trading update. It says that trading has continued to be positive since its H1 results in September and that for the full year it is now expecting:
Revenue of approx. $100 million versus previous guidance of $95 million.
Adjusted EBITDA of approx. $20.5 million versus previous guidance of $19.5 million.
Year-end net cash of approx. $34 million, assuming $2.0 million of the additional $6.0 million share repurchase authorisation is executed prior to year-end (previous guidance was $29 million and assumed the full $6.0 million was executed).
It explains that activity has been supported in part by AI-related data centre construction in the US, alongside a stabilisation in other private non-residential construction markets. It adds that customers continue to report healthy levels of activity and good visibility of work into 2027 and that its backlog for November and December remains robust, giving the Board confidence in the outcome for the year.
“Our momentum from the first half has continued into the second, and with customers busy and good visibility over the final weeks of the year, we’re pleased to be raising our guidance again.”
“While the wider market remains uncertain, we are seeing encouraging signs of improvement and continue to make good progress against our strategic priorities. With the business in a strong position, we look ahead to 2027 with measured confidence.”
Ed S’s view:
Back in September, Graham upgraded Somero to GREEN after the company raised its full-year guidance in its H1 results (after raising it in July). That was the right call in hindsight as today we have another upgrade to full-year guidance.
It’s a great example of how operational momentum can persist. When companies are performing well, it’s not unusual to see them continually increase their guidance.
I’m not surprised that Somero has momentum at present. Right now, there is a significant level of data centre construction in the US.
Somero provides the technology to lay the ultra-flat, high-tolerance concrete floors these facilities require. And around 75-80% of its revenues come from the US.
It’s worth noting that there is an element of caution in today’s update. It says:
“The Board remains mindful of continued market uncertainty, with tariffs, elevated interest rates and immigration policy still weighing on the industry, coupled with recent changes to the US political landscape.”
For me, higher interest rates are a risk here. Right now, the 10-year US Treasury yield is above 5% and if yields were to remain high, it could put a brake on US construction activity.
The other big risk is a data centre buildout slowdown. This is a real possibility after the Democrats secured victory in the recent midterms.
In terms of capital allocation, the company tells us today that it’s now only expecting to execute $2.0 million of the additional $6.0 million share repurchase authorisation before year-end. Previously, it was expecting to execute the full $6.0 million.
I like this as it shows that the company is trying to maximise shareholder value and not just blindly repurchasing shares at any price. It suggests that management views the stock as a little expensive right now.
“The Board is reviewing how best to deploy capital to maximize shareholder value. The Company will update the market in due course.”
Zooming in on the valuation, the forward-looking P/E ratio before today’s update was 16. That’s quite a bit higher than it has been in recent years:
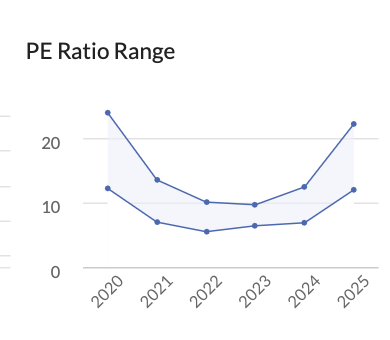
Note that after today’s update, Cavendish has raised its 2026 EPS forecast to 25.2 cents. That puts the stock on a P/E ratio of about 15.7.
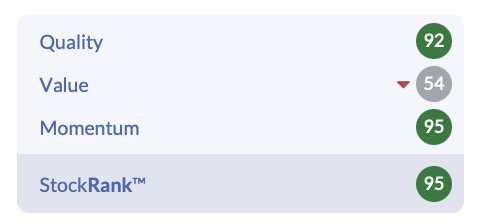
Turning to the StockRank, it’s high overall at 95. That said, the Value score is worth highlighting here – it’s quite low at 54.
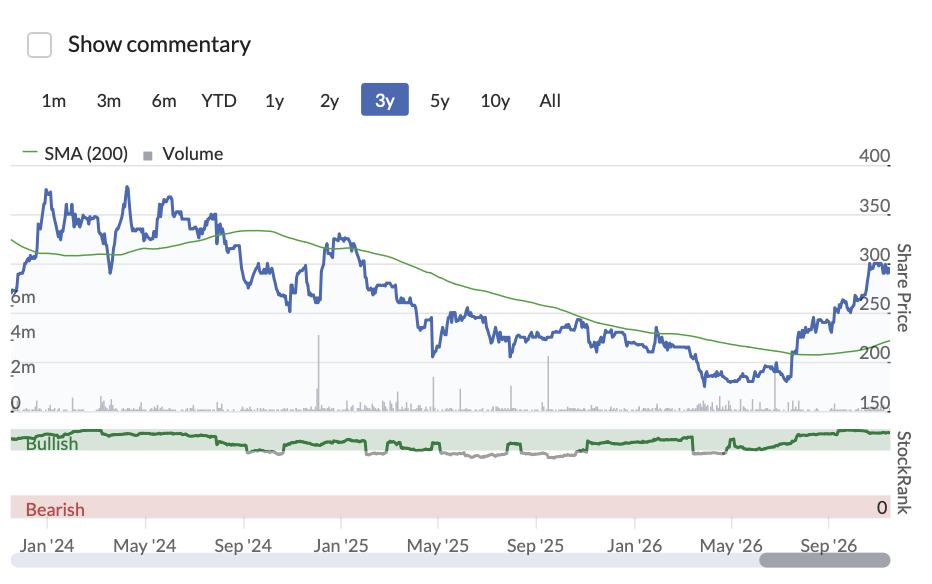
Given the momentum that Somero has at present, and the high StockRank, I’m happy to leave the stock on a GREEN rating. But investors should be mindful that there are some risks around interest rates and the data centre buildout here and there’s no guarantee that the company's strong momentum will last.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Somero Enterprises (3)
Comments here are also visible in the Daily Stock Market Report
Would appreciate Somero Enterprises (LON:SOM) insights. I hold.
Morning David,
Thanks for the suggestion. Ed's working on Somero Enterprises (LON:SOM) as I type!
Roland
A company that once had the world at its feet. Innovative and unique product that had a use in concrete screeds all over the world, but unfortunately a typical US management with a strong parochial attitude that could see no further than the North American market.