Elders: 10 years of growth, but what’s next?

In Elio’s most recent article, he talked about the importance of using screens to find a list of interesting stocks and then doing further research to decide if they are right for you. I have been writing about stocks uncovered by the screen created by Stockopedia contributor Roland Head that looks to mimic the approach that Warren Buffett uses to choose stocks that are likely to be great compounders. The methodology is outlined in Roland’s article titled “Screening for Warren Buffett stocks: the ultimate strategy?”. So far I have covered Universal Store Holdings (ASX:UNI) (read here) and NZE listed Mainfreight (NZE:MFT) (read here) along with Dusk (ASX:DSK) (read here).
Today I am going to delve into agribusiness company Elders (ASX:ELD).
Buffett is focused on companies that have a sustainable competitive edge. This ensures that they will survive the tough times that inevitably come if you own a business for long enough. So far Elders have been around for 184 years. That fact alone provides a fair bit of comfort that they will still be here in 10 years time.
Of course, too much debt can threaten the existence of a company no matter how old it is. That almost eventuated during the global financial crisis when the company was burdened with over $1.4 billion in debt and went on an acquisition spree in a wide range of areas. A new CEO undertook a series of asset sales and brought the company back to a pure play agricultural company. Then Chairman Mark Allison, shifted into the role of CEO in 2014 and steadily rebuilt the company with a disciplined approach to return on investment and executing strategy.
The share price reacted savagely to the news that Allison would retire, when announced last November. $475 million in market value was wiped out just on that day and the share price has continued to slide, down 40% since that point.
Buffett likes to say, “invest in a company that any fool could run, because sooner or later one will.” Whilst the loss of a highly regarded leader is a blow, an orderly transition to a new leader is not necessarily a disaster, especially if the business is in good shape.
The inclusion in Roland Head’s Warren Buffett screener is based purely on the numbers, so let’s take a look at them. The CAGR of EPS over the last five years is 16.3% and book value per share has also grown at 19.8%. ROE has averaged 21.8% and the Greenblatt Return on Capital has averaged 19.8%. Sales have increased at 21.1% and underlying EBIT at 32.6%.
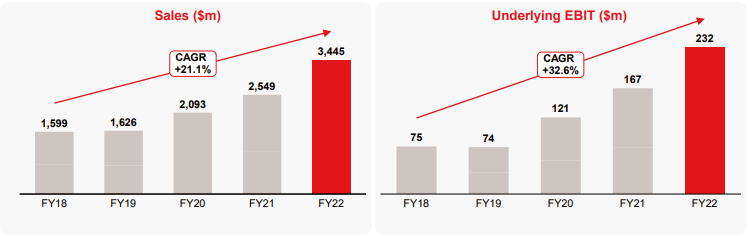
Source: Elders, 2022 Full-Year Results Presentation, 14/11/22
These are impressive numbers. The question is, “Are they sustainable into the future?” One way to try and answer that question is to examine a company’s ability to fund long-term growth from retained earnings.
Stockopedia has an Expected Return metric in the Screen Tool which is calculated by looking at the company's 10 year average ROE and its typical dividend payout ratio. It is then possible to calculate an expected sustainable growth rate, based on retained earnings. Roland Head set a minimum threshold of 6% for this metric in his screen. Elder’s expected return is 30.2%, which is the highest of all the stocks selected by this screen.
In the short-term at least, market analysts do not believe this growth is sustainable. They are forecasting a decline in sales of 7% for FY23 and a more substantial drop in earnings. Note that ELD uses a September financial year end. Their half year FY23 results to the end of March are due to be released to the market on the 15th of May. This will give a good indication of how they are tracking this year.
Like all agribusinesses, Elders profitability is impacted by forces outside of its control. This includes weather events and global prices for agricultural commodities. Australian government forecasting agency ABARES is expecting the record levels of agricultural production to continue in 2022-23 on the back of three years of good rainfall and strong commodity prices. That said, prices for some commodities key to Elders, such as Beef and Sheep have tapered off a bit from their recent highs, but are still at very strong levels.
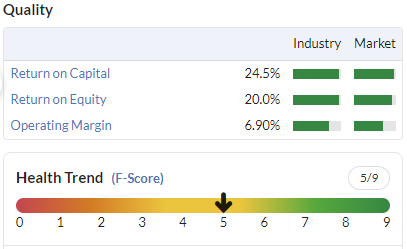
Turning to the Quality score, it is high at 92. We can see that the returns on capital and equity are high and their margins and Health Trend are decent.
The balance sheet is in a healthy state with a net debt to equity ratio of 33.3%. Debt servicing costs are covered by EBITDA by 32.5 times, and they are well clear of all debt covenants.
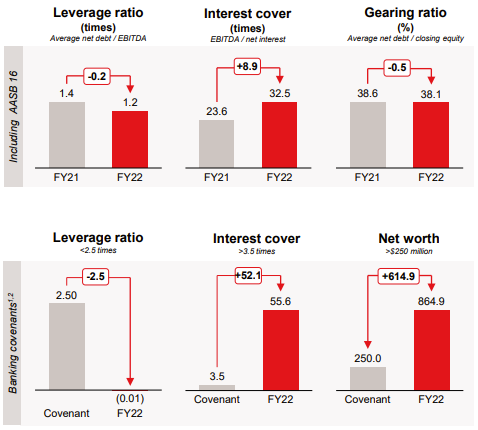
Source: Elders, 2022 Full-Year Results Presentation, 14/11/22
The declining share price has improved the standing of the business from a Value Rank perspective which now sits at 90. The 12 month rolling forecast PE ratio is 9.7 and this is despite a forecast 23% fall in EPS. The historical FY22 PE ratio is down to 7.4 based on the assumption that earnings peaked at that point.
The forecast dividend yield is 5.8%. 2022 dividends were 30% franked. This reflects the fact they have not been paying a full rate of tax due to prior tax losses being utilised. It is expected that these tax losses will be fully utilised by FY24. The payout ratio ranges around 55% - 60%.
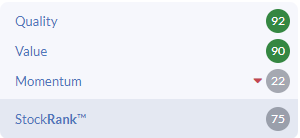
When I loaded Stockopedia this morning it presented the quote “A comfortable investment is rarely a profitable one” by Rob Arnott. Like most of the stocks in this series, Elders is classified as contrarian. That is based on the high scores for quality and value but low score for momentum. Contrarian trades are uncomfortable because you are going against the trend. The share price is falling and analysts’ forecasts are declining, but you are attributing that to short-term influences with the belief that in the long-term the strong fundamentals of the business will shine through and the market will turn around. Contrarian investing can be highly profitable, but it also requires a strong stomach.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?