Gear4music: profit warning bombshell sends share price down 29%
Analyst’s view:
This is a very disappointing update from Gear4Music today. After telling investors in October that it was expecting its FY27 results to be in line with expectations, the company has now told us that EBITDA will be far lower than the figure expected due to AI disruption to its customer acquisition strategy. Given this profit warning, I'm taking the stock down to AMBER/RED.
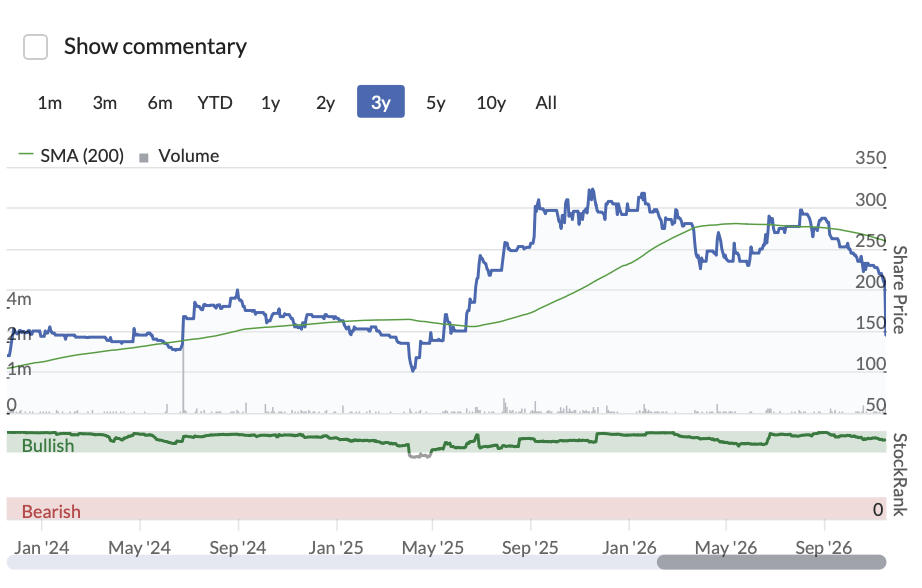
Down 29% at 150p (£31m) - Interim Results
Musical instrument retailer Gear4Music has today posted its H1 FY27 results for the six months ended 30 September. It’s fair to say the market is unimpressed – the G4M share price is down 29% as I write this. So, let’s take a look at what’s going on.
FY27 H1 financial highlights:
Total revenue up 6% to £85.4m.
UK revenue up 3% to £51.0m.
European and ROW revenue up 11% to £85.4m.
EBITDA of £5.7 million (FY26 H1: £6.9m; FY25 H1: £2.9m), includes previously reported setup costs associated with the new automated UK distribution centre.
Operating profit down 38% to £2.1m.
Profit before tax down 63% to £1.0m.
Net bank debt of £24.3m (30 September 2025: £16.0m), up £8.3m year on year, reflecting investment in the new automated UK distribution centre and seasonal inventory build ahead of peak trading.
Outlook:
FY27 Q3 revenue to date down 13% year on year, but 19% ahead of the equivalent period in FY25.
Lower paid-search traffic driving weaker trading, partly reflecting more prominent AI-generated results.
Expanding advertising within AI search and improving website visibility expected to support recovery over time.
FY27 EBITDA now expected to be approximately £11.5m, significantly below current consensus market expectations*.
Phase one of the new automated UK distribution centre operational ahead of peak trading.
The Board remains confident in the Group’s long-term prospects, supported by continued investment in marketing, technology and logistics to drive profitable growth.
* Gear4music believes that current consensus market expectations prior to the release of this update for the year ending 31 March 2027 were revenues of £200.2 million, EBITDA of £16.0 million and profit before tax of £6.0 million.
Ed S’s view:
There are a few things going on here. For a start, on 20 October, the company said:
“With this key part of the year still ahead, the Board continues to expect the Group's financial performance for the year ending 31 March 2027 to be in line with consensus market expectations.”
Less than a month later, it has dropped a profit warning bombshell on us. It now expects EBITDA of approx. £11.5 million – miles below expectations of £16 million.
This tells us that trading has deteriorated rapidly (Q3 revenue to date is down 13% year on year). It also raises some concerns about the company’s internal visibility and forecasting systems.
We then have the AI issues. It says:
“Trading in FY27 Q3 to date has been affected by lower paid-search traffic, which we believe reflects changes in the presentation of search results and evolving customer search habits as AI becomes more prominent.”
Paid-search traffic refers to customers arriving at the company's website by clicking on paid advertisements at the top of search engine results rather than finding the site organically. It seems generative AI-related changes to search engines (e.g. Google’s AI Overviews) are messing with its customer acquisition strategy.
A third issue is that other-brand sales have been affected by sterling’s rapid appreciation against the euro. This has increased short-term pricing pressure from European retailers.
In terms of the financial implications of the profit warning, Progressive Equity Research now expects EPS of 4.1p for FY27. Before today’s print, the consensus forecast was 21.1p so we are potentially looking at much lower earnings than previously expected.
At that new EPS forecast of 4.1p, the stock is trading on a P/E of 37. So, it’s not cheap.
As for the AI issues, changes to Google and other search engines are affecting a lot of companies at the moment. This includes Google itself, which recently told investors that revenues from search were a little soft due to the fact that AI Overviews doesn’t monetise as well as traditional search.
Looking ahead, no one really knows online advertising will evolve at this stage. However, on the plus side, G4M says:
“The expansion of advertising within AI-powered search services is creating additional opportunities to reach customers, and we are making good progress in increasing the visibility of our websites across these platforms, positioning us to benefit as search behaviours continue to evolve.”
I wonder if Gear4Music needs to adapt its customer acquisition strategy and focus more on YouTube – where it’s not so strong (rival Andertons is doing this really well). This is something I mentioned in October.
In October, I downgraded G4M from GREEN to AMBER/GREEN. Today, I’m going to take it down two notches to AMBER/RED.
I do think there’s potential for a recovery here at some point. However, in the short term, taking a cautious view is sensible given the AI disruption.
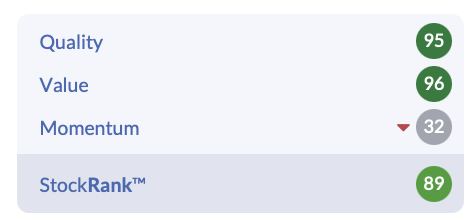
Looking at the StockRank, it is actually pretty high, at 89. However, I would expect it to fall shortly.
Perhaps a takeaway here is that a high Value score can potentially be misleading (especially if Momentum is weak). Sometimes, a low valuation can be a sign of underlying problems.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Gear4music (HOLDINGS) (13)
Comments here are also visible in the Daily Stock Market Report
Gear4music (HOLDINGS) (LON:G4M) I held this some time ago and cut my losses as frankly i lost faith in the management and renewed my concern as to whether, conceptually this was a business worth investing in. A few months back there had been a large Director share sale and I ( wrongly ) did not take this as my cue to exit. This latest profits and trading warning is about par for the course so unless you are trading this for the floor in the price etc- to me any traders should be looking for a price around £1 as an entry point but very DYOR
Nasty price response in Gear4music (HOLDINGS) (LON:G4M) but this is a theme that is emerging in agentic-based price searching. Both the retailers and Google's PPC AdWords are trapped in the same doom loop. Reckon this is another evolution in disruption: just as clicks disrupted bricks, agents are now coming for online retailer margins.
Amazon has been attempting to block Facebook's Muse for exactly these reasons . Jeff Bezos famously said "your margin is our opportunity" - shoe may be on the other foot now. Oddly ironic , by extrapolation, Amazon becomes an even lower margin of fulfillment centre
Gear4music (HOLDINGS) (LON:G4M)
Seems they are paying Google for sponsered ads and Google AI is sending the customers elsewhere. No doubt things will settle down in time.
perhaps but i think we are right at the peak time of year ref trading ar we not - would anyone presume that its just a blip and it will normalise? it might but could it be first signs ref subtle changes in how you need to act get business through the door. For example i think chat gpt wants traders to sign up and verify themselves - is that sign that they are trying to move stuff away from google.
should they not have been ahead of the events ref AI advertising - seems like they are perhaps reacting - the final line in that section doesnt exactly instill me with confidence.
expected to support recovery over time
If Gear4music (HOLDINGS) (LON:G4M) stuff its "good shit" i would have expected that a trend to more AI searches as we obviously have would help them - eg if their products would stand up well in like for like comparisons - well AI is great for helping you work that out.
It really did look like this company had found its mojo again somehwat and that all seems to have gone in a puff of smoke.
My s worry here would is AI making it cheaper and easier for chinese clones to get similar quality product out there at cheaper prices ?
I dont really know much about seo or their product segment but all i do know is that this update is a bit of a body blow without some real evidence that the blip is anything but short term. I do know some people who have been hit overnight ref online sales er by google rjiggs so i know it does happen and it can be addressed - seems like nightmare if its material hit for them though right here right now.
i'd skip learning about SEO then, it's GEOo now and it's one of the deflationary axes of AI - and I mean AI as a broad technology and not chat bots like GPT
It's not that dissimilar - fundamentally, quality references matter.
Pretty disastrous update from Gear4music (HOLDINGS) (LON:G4M) with revenue down in Q3 by a shocking -13% so far. What I found interesting is that they blame AI, which could have much wider read across to the whole retail sector:
'Lower paid-search traffic driving weaker trading, partly reflecting more prominent AI-generated results'
So perhaps Gear4music (HOLDINGS) (LON:G4M) is the retail canary in the coal mine.
That said, they also fail to remind the market that Q3 2026 last year was the first full quarter without their previous competitor PMT in the market. So the comparatives are also now tougher. PMT had an annual turnover of £43m so not an insignificant competitor.
deleted
And Tortoise, on some BB,pumped to high heaven in the last 12 months or so
Which one out of interest?
ADVFN, LSE
Thanks
Seems they are paying Google for sponsered ads and Google AI is sending the customers elsewhere. No doubt things will settle down in time.
Gear4music (HOLDINGS) (LON:G4M)
Seems they are paying Google for sponsered ads and Google AI is sending the customers elsewhere. No doubt things will settle down in time.
perhaps but i think we are right at the peak time of year ref trading ar we not - would anyone presume that its just a blip and it will normalise? it might but could it be first signs ref subtle changes in how you need to act get business through the door. For example i think chat gpt wants traders to sign up and verify themselves - is that sign that they are trying to move stuff away from google.
should they not have been ahead of the events ref AI advertising - seems like they are perhaps reacting - the final line in that section doesnt exactly instill me with confidence.
expected to support recovery over time
If Gear4music (HOLDINGS) (LON:G4M) stuff its "good shit" i would have expected that a trend to more AI searches as we obviously have would help them - eg if their products would stand up well in like for like comparisons - well AI is great for helping you work that out.
It really did look like this company had found its mojo again somehwat and that all seems to have gone in a puff of smoke.
My s worry here would is AI making it cheaper and easier for chinese clones to get similar quality product out there at cheaper prices ?
I dont really know much about seo or their product segment but all i do know is that this update is a bit of a body blow without some real evidence that the blip is anything but short term. I do know some people who have been hit overnight ref online sales er by google rjiggs so i know it does happen and it can be addressed - seems like nightmare if its material hit for them though right here right now.
i'd skip learning about SEO then, it's GEOo now and it's one of the deflationary axes of AI - and I mean AI as a broad technology and not chat bots like GPT
It's not that dissimilar - fundamentally, quality references matter.
Seems an over reliance on Google. if they change their algo or business model then G4M get hit. I sold all at 8am. can’t see this getting better with more AI search results coming through daily.