Hunting: Middle East conflict triggers second profit warning in four months

Analyst’s view:
This is Hunting's second profit warning in four months, with both triggered by the conflict in the Middle East. While this both unsurprising and clearly not the company's fault, the risk of further disruption means that Hunting isn't yet cheap enough to persuade me to upgrade our view.
Down 11% at 377p (£572m) - Q3 2026 Trading Update
While oil exports in the Middle East are said to have recovered in recent weeks, oil and gas drilling activity in the region is still being disrupted. Hunting's business supplying equipment for the energy industry is also being disrupted and today's profit warning is the second in just over three months.
Graham covered August's profit warning, moving our view to AMBER/RED at the time to reflect the lack of visibility on any improvement in trading conditions.
Today's update suggests he was right to be cautious. While Hunting is a very well-respected business, events in the Middle East are continuing to hold back drilling activity in the region:
... the protracted and deepening nature of the conflict in the Middle East has impacted our overall results in Q3 and into Q4, with a deterioration in the short-term trading outlook seen in recent weeks.
August's profit warning was triggered by the Kuwaiti Oil Company's decision to re-run a large tender, delaying its outcome. This re-tender was published on 12 October, with results expected later this year and product shipments expected in H2 2027.
Unfortunately, today's update highlights broader delays to tendering and rig activity:
The Directors believe that there is significant upside within the Middle East once hostilities cease. However, OCTG [Oil Country Tubular Goods] and other product line tender activity across the region remains challenged at present by logistical issues and continued attacks on shipping and regional infrastructure. Rig activity in Saudi Arabia has declined, reducing activity levels in the Jafurah unconventional development, affecting trading within Hunting Titan.
Even the previously reliable North American market appears to be giving some cause for concern. Hunting says that after an improved performance so far this year, "seasonal factors, client budget issues and caution among operators" mean have left management more cautious about Q4.
Revised guidance: Hunting now expects 2026 adjusted EBITDA of $128m to $133m. This is a reduction of c.6% at the mid-point from August's guidance of $138m to $141m.
Broker estimates: as we've noted previously, broker estimates have been softening for some time. Today's downgrade is likely to prompt a further cut to consensus:
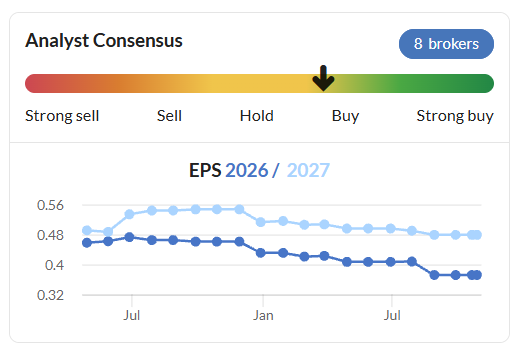
With thanks to Canaccord Genuity for publishing today, we can see that both 2026 and 2027 earnings are now likely to be lower than previously expected:
FY26E adj EPS: $0.31 (-14% vs $0.36 previously)
FY27E adj EPS: $0.50 (-11% vs $0.56 previously)
Roland's view
Hunting is a well-respected business with attractive market share. But it operates in a cyclical sector and trading prospects are currently being affected by difficult geopolitical conditions.
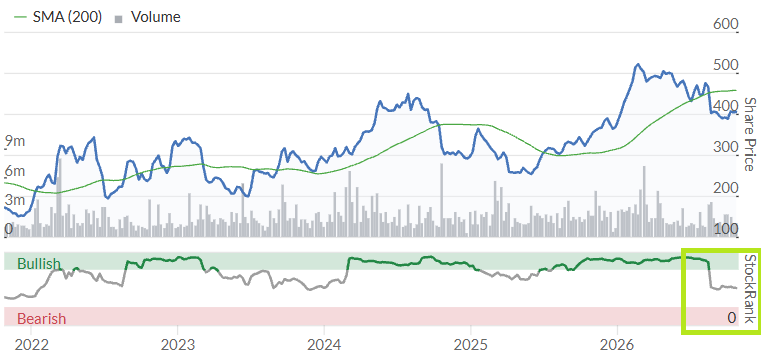
At 376p as I type, the share price has now fallen by more than 30% from its post-pandemic high of c.550p.
Using today's Canaccord forecasts as a guide, that puts Hunting on a FY26E P/E of 16, falling to a P/E of 10 in 2027. That might be an attractive valuation if profits do recover next year.
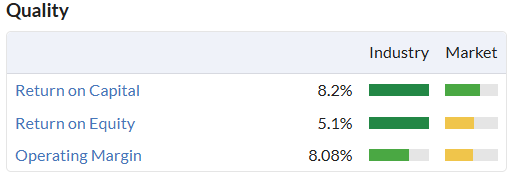
In addition, the shares are also now trading in line with book value.
However, recent rather average profitability suggests that a valuation close to book value may be fair:
I think it's also worth considering the potential risk of further downgrades if the situation in the Middle East doesn't improve soon.
I'm going to leave our broadly negative view unchanged today - a conclusion that's also reflected in the recent sharp fall in Hunting's StockRank, which I've highlighted in the chart above.
It may also be worth remembering that long-time CEO Jim Johnson is due to retire soon. The search for a successor remains underway, but a change in leadership always carries some time, especially after a long incumbency.
While I would guess that Hunting could be an attractive buy at some point, I'm not sure that time is yet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Hunting (3)
Comments here are also visible in the Daily Stock Market Report
Ouch indeed - look at the trading volume - already almost three times daily average.
Hunting (LON:HTG) another over reaction maybe as current situation WW has been known for months - so why so steep today - twice trading volume so far today!
time to spend more, good upside
The price had been coming back up a bit, I think there had been hopes that growth elsewhere would mitigate the Gulf problems. I think that is still true, but it takes time for these effects to work through. I hold.