Is Good Energy a good stock to buy now?

Until recently, I hadn’t really heard much about energy business Good Energy (LON:GOOD), even though it’s been listed on the AIM market since 2012.
But Good Energy is currently sitting near the top of the StockRanks and keeps appearing in my screen results. It recently showed up in some of Ed’s multibagger screens, too.

Good Energy has also put in a notable share price performance recently, doubling since the end of September:
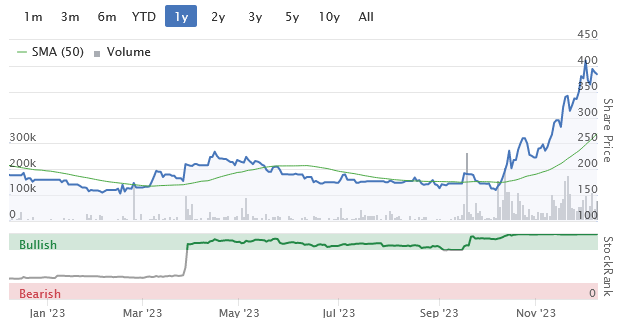
I’m keen to learn more about the story here and find out whether I should start paying more attention to this business.
100% renewable, no greenwash!
Good Energy was founded by Juliet Davenport in 1999 as a green energy supplier. To this end, the company acquired some renewable generating assets of its own, including the Delabole Wind Farm in Cornwall and a number of solar farms.
Good Energy was also instrumental in developing the concept of feed-in tariffs, which pay customers for the electricity they generate. The company has remained one of the market leaders in this area, even after the government’s original Feed-in-Tariff system ended.
This focus on decentralised generation has allowed Good Energy to build up a loyal army of more than 2,000 small-scale generators. These help to supply the company with its renewable electricity needs. Interestingly, the company says that more of its customers now generate their own power than buy it from Good Energy.
However, the profile of the business has changed dramatically over the last couple of years. Although the focus on decentralised generation remains, in 2022, Good Energy sold its own 47.5MWh renewable power portfolio to Bluefield Solar Income Fund (LON:BSIF).
To maintain its ability to guarantee to provide renewable electricity, the company has signed direct power purchase agreements (PPAs) with large renewable generators such as offshore wind operator Ørsted.
While many large corporations now use PPAs, this is apparently an unusual approach for a UK energy supplier. Most buy electricity from the wholesale market (including fossil fuel electricity) and then offset these emissions by buying renewable certificates (REGOs).
Good Energy has campaigned against this “greenwashing” and claims that these certificates are often double-counting renewable energy that has already been consumed elsewhere.
Current operations: from supplier to service provider
The sale of Good Energy’s generating portfolio attracted the ire of its largest shareholder, rival supplier Ecotricity.

The two companies appear to have been locked in a running battle for a while now. This has included Ecotricity making a failed bid to buy Good Energy for 340p per share in 2021 – and more recently attempting to unseat some of its directors.

The cause of Ecotricity’s unhappiness seems to be Good Energy’s decision to reposition itself as an energy services business, following the departure of its founder Juliet Davenport. Electricity and gas are now just seen as one of the services the company can supply.
In fairness, this strategic shift may have been underway before Ms Davenport stepped down. But it’s definitely stepped up a gear since she left. Under chief executive Nigel Pocklington, the company has acquired both a solar panel installer (Wessex EcoEnergy) and a heat pump installation specialist (Igloo Works).
Good Energy is also part-owner of the Zapmap EV charging app and led its Series A funding round in 2022.
Further acquisitions are said to be possible as Mr Pocklington continues to try and expand Good Energy’s footprint in these growing, capital-light markets.

This chart from the 2023 half-year results provides some clues as to why Good Energy may have adopted this strategy and decided to switch away from being a pure generator/energy supplier:

Source: H1 2023 results presentation
Right now, the vast majority of Good Energy’s revenue still comes from its energy supply business. This is expected to change, making the outlook somewhat less certain than it might have been.
In a recent note available on Research Tree, broker Canaccord Genuity noted that its forecasts for later years now reflect “a greater degree of caution on the development of the services businesses”.
My impression is that Good Energy is moving into markets that are increasingly competitive and are also attracting other larger players in this sector.
For example, both E ON SE (ETR:EOAN) and British Gas (part of Centrica (LON:CNA)) now offer solar panel and heat pump installation, plus EV charging solutions. Both groups benefit from having much larger customer bases to which they can market targeted offers.
Recent trading/outlook
Good Energy’s half-year results showed revenue up 45.6% to £156.1m, while operating profit rose to £14.1m (H1 2022: -£0.5m loss). However, the company cautioned that “some of this” profit was expected to unwind in the second half of the year, due to “lagging commodity costs and tariff reductions”.
The company provided this chart to help explain the expected squeeze on margins during the second half of the year:

Good Energy makes use of hedging to reduce the level of commodity price risk it accepts on bought-in energy. But for an outsider, I think it’s quite difficult to understand all of the moving parts behind the group’s costs and revenues.
The unusually high level of feed-in generation from the company’s customer base also seems to make things more complicated. Good Energy has a number of tariffs that are aimed at feed-in customers and is also one of three deep green suppliers with a permanent exemption from the Ofgem price cap.
Modelling all these variables is way beyond my ability or sector knowledge, so I’m reliant on management guidance and broker notes.
Trading update & outlook: fortunately for investors, Good Energy has recently updated its guidance for 2023.
In an update on 28 November, the company said that the forecast loss for H2 2023 is now expected to be reduced, with trading to the end of October “ahead of expectations”.
A mild start to the winter and “stable” renewable generation mean that full-year profit guidance has now been increased:
Good Energy expects to deliver earnings ahead of the Board's expectations for the full year seeing a profit before tax of at least £4m.
Stockopedia’s brilliant consensus trend chart suggests this has resulted in an increase in forecast earnings from 10.5p per share to 19p per share this year, although 2024 forecasts are unchanged:

After the stock’s recent rapid gains, these forecasts put the stock on a 2023 P/E of 18, falling to a FY24 forecast P/E of 13.
I don’t know whether further upgrades (or downgrades) are likely. The UK weather certainly seems to have become more wintry since the end of October, at least where I live.
However, there are a few interesting points I’d like to share from the StockReport that highlight the early impact of the company’s strategic shift.
Profits up, quality up?
We already know that last year’s high energy prices were generally good news for (well run) energy suppliers. Good Energy’s results for the last 18 months seem to reflect this picture, although the numbers are complicated by profits from the generating portfolio disposal.
Strong revenue growth in 2022 and 2023 has been driven by higher energy prices, not by any contribution from its services business. Brokers expect energy services to contribute less than £5m of revenue in 2023.
Note how revenue estimates are slipping lower to reflect falling energy costs, though:

To get a quick snapshot of profits, I’ve opted for the normalised EPS line in the StockReport. As far as I can see, this has been adjusted to exclude gains from disposals last year and is more of a reflection of continuing trading in the business.
Following the recent upgrade, earnings are expected to rise this year and continue rising in 2024 (ignoring the TTM eps figure):

Starting in 2024, broker Canaccord expects the energy services business to make a positive and growing contribution to profit, potentially supporting higher margins.
In the meantime, Good Energy’s balance sheet looks strong to me. Net cash stood at £29m at the end of June, thanks to the cash received from the disposal of its generating portfolio:

Generating electricity is a capital-intensive business that only delivered single-digit returns on capital employed for Good Energy. By moving to a capital-light model where the company buys in the power it needs to supply its customers, profitability has improved dramatically.
Here we can see the reduction in fixed assets resulting from the disposal:

There has also been a consequent increase in profitability, although I think the 2022 figure is more representative than than the TTM figure, given Good Energy’s expected H2 loss:

Capital expenditure requirements have also fallen sharply, which could support stronger levels of free cash flow:

Conclusions
Good Energy’s recent share price gains have pushed down its ValueRank from 95 to 87 over the last month. That’s still a decent score though and I do think the shares could still be reasonably valued if Good Energy’s service-driven growth plan succeeds.
In recent years, the group’s energy supply business seems to have stagnated. As far as I can see, the number of supply customers and the total amount of energy supplied have both flatlined or fallen slightly since 2019.
Given this, I think the move into energy services probably makes sense in terms of providing a more meaningful growth opportunity.
Good Energy’s main differentiators appear to be its focus on greater integrity and accuracy in renewable certification, and its continued focus on decentralised generation and export tariffs.
Combining this brand offering with energy services solutions could be an attractive offering for residential and business customers who are not solely focused on cost and who also appreciate Good Energy’s deep green credentials.
In supermarket terms, I reckon Good Energy should aim to be Waitrose, versus the Tesco (LON:TSCO)-style offering we might expect from British Gas or E.On.
Good Energy’s share price looks up with events to me for now. But if the company continues to deliver on its growth potential over the next few years, I think it could become a significantly more valuable business.
I don’t feel enough conviction to consider buying the shares at the moment. But this is certainly a business I plan to keep an eye on.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Excellent review this company has been on my radar for a while and like others chose not to invest at 170 as it still looked volatile, i am into renewables and would like this in the portfolio will watch and pick the right time to invest think it has a good mileage
Hi Joe, I bought Good Energy (LON:GOOD) this morning because as well as having excellent fundamentals, it has formed a strong positive Bow Tie pattern which suggests it has mileage ahead. Alternatively, you may decide to wait until it might possibly pull back to its support/resistance line which is around 300p. Will GOOD appear in Ed's 2024 NAPS?
David.
Probably not, Centrica (LON:CNA) is the highest Ult. at the moment, OPG Power Ventures (LON:OPG) is also higher but that could be ruled out.
Only one Ult. has been selected in the past but Ults have been one of the best sectors, in the last 2 years, with Yu (LON:YU.) and Centrica (LON:CNA) both doing well.
I heard Juliet Davenport speak many yeas ago, maybe before GE floated, and she came across very well. I was put off the company when I read some years later that it had made a significant investment in a Swansea Bay wave generation project in which her husband was closely involved.
I looked at GE a month or so ago and decided it was not for me. Why - two reasons
Zap map was good a few years ago but it has not really moved forwards and now there are plenty of free apps offering better information on chargers, such as the Electroverse app from Octopus.
I looked at their tariffs and they were not competitive. So this only leaves their heat pump installing arm and it's very difficult to scale up nationwide as an installer.
A few days after I looked, the price almost doubled, so I kicked myself, but it appears to be coming down just as fast now.
I bought a chunk of Good Energy (LON:GOOD) at about 170p a few months ago and just sold at 330p on the basis that 1) when sub 200p, you were paying about £10m for a mature, cash generative business 2) ZapMap is a secret source of future value here, but potentially from 2027-2030 onwards 3) the cash pile is not all available as some is upfront payments under regulatory provisions I believe. In summary, at 275p+, this looks fully valued. I follow it every day and it's extremely volatile. I would buy in lower to trade it, and take a core buy-and-hold position at anything below about 225p,
You sold at the right time Mulberry, not the perfect time, but close enough. I'm not in this, but if I was, based on chart action, I would be selling it now not buying. Never a great idea buying at the top.
I am not buying in at this level. I would buy a 250-270 to trade, and sub 225 to hold longer
That is a great analysis Roland, thank you!
I hold, I bought on the the basis that cash equalled market cap (in early Oct 23) and there appeared to be a viable business attached they can afford to develop. For me the key factor is your Waitrose analogy - it seems entirely possible that, if the offering is well (i.e. better) presented to customers, and greener than green, they could keep growing their business at a reasonable rate, with much better margins and ROCE.
Ultimately I expect it will be difficult to avoid a bid from one of the majors at some point but it could be a fun ride in the meantime.
Octopus are the most obvious direct competitor (100% renewables for electricity, albeit with the certificates you mention above). In my direct experience Octopus are VERY good (other people's experience may vary) and offer all the services described above and more. This strikes me as a scale game and Octopus are MUCH bigger. Would be good get any further insight into how Good Energy can be better/differentiate themselves at any sort of scale. Is it just the certificates?
I know someone with Octopus, he does think very much of them, he said taken on too many new accounts and the service has gone down, is it an overseas call centre?
Good Energy (LON:GOOD) I looked at their tariff, which is quite confusing as different prices for each area, for electricity, not sure which area .I'm in, the prices do vary quite a bit, London is quite cheap compared to some other areas. They are more expensive than most of their rivals, it seems.
Their reviews are good but what matters to many people is the cost.
I'm looking to move from British Gas but I don't want to pay more.
Hi Rusty2, just checking…
I know someone with Octopus, he does think very much of them
Is there a ‘not’ missing?
Yes sorry, the 'not' went missing. I was a bit surprised by his comments last week.
Interesting and probably not surprising given the scale of their growth - I would imagine it feels pretty challenging working for them right now. What I would say as a customer, they are so far managing to hide the pain from me (which is all I care about). I would also say that they understand the value case for investing in tech and so far seem to be making the right choices on average. However, I would imagine some of the systems and data they have taken on are in a very poor shape (almost a given when you takeover failing providers) and getting them on to the Octopus stack will be very challenging.
Hi Rusty2,
My personal experience of Octopus has been good, but I've rarely needed to go beyond the online account management tools, which I think are excellent.
Re. Good Energy (LON:GOOD), I also felt the tariffs seemed complicated and the company's exemption from the price cap rules appears to mean they can charge more than the price cap if needed. I am not sure if this has happened in the past or is likely to happen in the near-term future, but it's another complication for typical users.
In my view, the opportunity for Good Energy is to target more sophisticated customers who want a broader, so-called "deep green" service.
I'm not sure how easy or scalable this will be, but I think that if they try to complete with British Gas etc without any differentiation, it won't go well.
I would also hope that management will be disciplined with the cash pile and not go wild on acquisitions.
Roland
Roland
My personal experience of Octopus has been good, but I've rarely needed to go beyond the online account management tools, which I think are excellent.
Exactly my view. I particularly like the ‘Wheel of Fortune’ aspect where you get a chance to win a discount from you bill after meter reading input. Super consistent ……… zero every time !!!
Hi Robert W,
Thanks for your comment. I am an Octopus customer too and I agree that they seem a good company to deal with and provide excellent services (as far as I have used them).
Your point about differentiation is my main concern with Good Energy (LON:GOOD). Previously, it was clear what they offered (directly generated renewable electricity), although perhaps the ability to scale was limited.
Now that the company has sold its generating assets and switched its focus to services, I feel it's less clear how the business is differentiated.
I am not sure if the decentralised generation (typically small businesses who have small generating assets such as large solar roofs) is really a material part of the business or if it can scale much further.
Hence my Waitrose analogy - I don't think Good Energy can hope to be biggest, so it must demonstrably be better in some way for a subset of customers. I don't know if that will be possible or not.
Roland