Legal & General share price dips as pension transfers miss City estimates

Analyst’s view:
The company remains on track to hit full-year earnings guidance, but the slowdown in pension risk transfer has continued, with new deals falling below market expectations in Q3. Against this backdrop, growing profits from asset optimisation are helping to support earnings. While I have a few niggling concerns, on balance I think this remains a good business at a reasonable price.
Down 2% to 309p (£16.7bn) - Q3 Trading Update
When I covered Legal & General's half-year results in August, I moved our view back up to AMBER/GREEN, commenting that the valuation still looked reasonable and that "upbeat guidance for 2026 and 2027 earnings suggests [a neutral view] may be too cautious".
Legal & General's share price has remained firm since then and is current close to all-time highs:
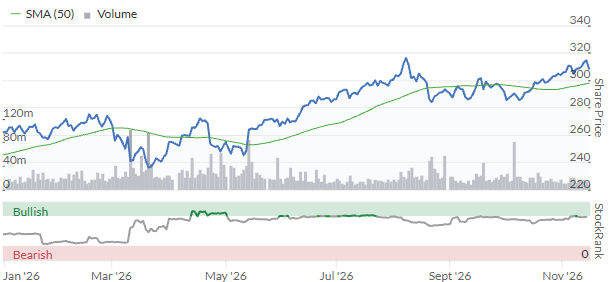
This morning's third-quarter update leads with guidance that the business remains on track to deliver Core Operating EPS growth "above the top end of our 6-9% target range" in 2026.
However, a closer look shows that L&G has missed consensus estimates on some key metrics during the quarter, prompting a mild share price drop this morning. Should shareholders (including me) be concerned?
Here are the key points:
Institutional Retirement: Pension Risk Transfer volumes +54% to £3.7bn, below consensus estimates of £4.6bn. New business margins "ahead of the 4.2% reported at the half year" - consensus was 4.8%, so this might also be a miss.
Asset Management: net outflows of £3bn, ahead of consensus for outflows of £4.5bn. Overall Assets Under Management rise by 4% to £1,230bn, also slightly ahead of consensus of £1,219bn. The only negative in the asset management division was that Annualised Net New Revenue (ANNR) was just £2m for the quarter, well below City estimates of £15.1m. Given that AUM performance was better than expected, my guess is that the lower ANNR figure may reflect a lower-margin asset mix than analysts were expecting.
Retail (annuities and workplace pensions): management say strong momentum from H1 "continued through Q3" and this appears to be borne out in the numbers. Retail annuity sales were flat at £0.5bn, leaving year-to-date volumes up by 25% at £1.5bn. Workplace net inflows were £4.5bn, comfortably ahead of consensus estimates of £3.7bn. This left Workplace Assets under Administration (AUA) 23% at £133.3bn (consensus: £132bn).
Protection (life insurance & similar) sales were also ahead of expectations, up 19% at £80.1m, versus consensus of £69.1m.
Legal & General is a big beast in the pension transfer market, which sees large financial services providers take responsibility for running companies' final salary pension schemes. This business is also one of the few ways the company has to really move the needle on its AUM.
Unfortunately, the value of new PRT deals signed in Q3 is lower than expected, as it also was in H1 this year. In August, the company said that one reason for this was that overall UK market volumes were likely to be lower than expected this year as some deals slipped into 2027. The company reiterates that deal timings remain uncertain today, but says it has signed a further £0.9bn of PRT transactions since the end of September.
I think one more general point about this is that the market for PRT is now more competitive and saturated with capital than it was even a few years ago. In this context, I'm quite pleased to see L&G's continued emphasis on "maintaining our pricing discipline and focus on attractive returns". I wouldn't like to see the company chase margins down.
Balance sheet: the group's main measure of balance sheet strength is the Solvency II coverage ratio (SCR). This measures the amount of surplus capital an insurer has above the regulatory minimum required to absorb a severe stress event.
Legal & General's H1 results showed its SCR fall to 201%, below analysts' expectations. This measure appears to have bounced back in Q3, with the company reporting a SCR of 213% at the end of September (consensus: 212%). I don't see any concerns here.
Cost savings: the company has begun a redundancy programme that's expected to reduce headcount by c.1,000 by the middle of next year. I believe L&G has around 11,000 employees in total, so this is quite a material reduction.
Outlook
Guidance from CEO António Simões is unchanged today:
We are on track to meet or exceed all of the targets we set out in 2024, including core operating EPS growth, which we expect to be above the top-end of our 6-9% target range for 2026.
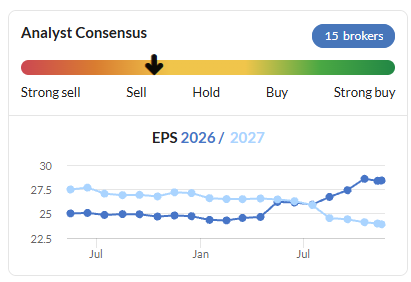
Consensus earnings estimates for the current year have risen since the summer, although estimates for 2027 have been drifting lower:
Roland's view
In my view of the company's half-year numbers, I flagged up the firm's growing dependency on profits from optimising how pension scheme assets are invested rather than new business volumes in PRT. Today's update confirms that profits from asset optimisation are on track to exceed £400m this year, as previously guided.
I'm not certain of the reasons for the decline in earnings forecasts next year, but my guess is that it reflects expectations that slower growth in the PRT market will persist.
While I think the asset optimisation focus may add some risk to the business, I suspect it is a pragmatic strategy against a backdrop of slower growth in PRT.
A reduction in earnings next year would tighten the group's dividend cover, but I don't see this being a particular risk just yet.
Current forecasts continue to support a very attractive dividend yield:
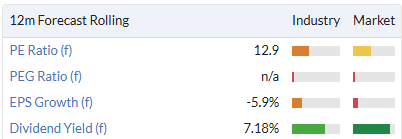
As I commented previously, a 7% yield plus forecast dividend growth of 2% implies a 9% expected return from the stock. I think that's reasonable for a business of this scale, quality and heritage, so I'm leaving my broadly-positive AMBER/GREEN view unchanged today.
Roland owned shares in Legal & General Group at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Legal & General (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?