LIVEDaily Stock Market Report (Mon 16th Nov 2026) - LGEN

Good morning!
I can't help noticing Bitcoin hitting a new low for the current sell-off: it hit $62,500 in the early hours of the morning.
The hack at Binance happened around the end of October, and yet Bitcoin initially seemed to hold up very well. Now, however, the price is down by 21% month-on-month and 32% year-on-year.
Technically, there is something important about this level on the long-term chart:
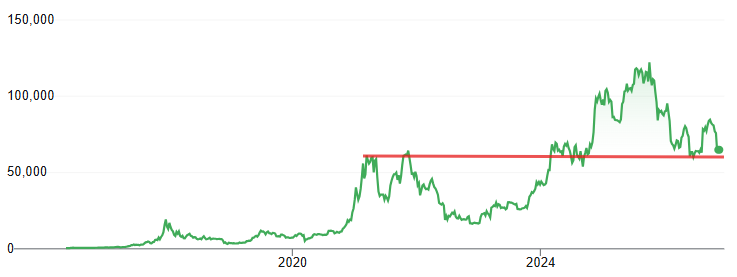
With AI taking up so much investor time and attention, perhaps crypto assets are finding it a little harder to generate the same excitement they did before?
Overnight market movements:
The FTSE is unchanged at 10,915
S&P 500 is down 0.5% at 7,530
Brent crude (January) is up 0.6% at $96.30/bbl
Gold is down 0.9% at $3,850/oz
Bitcoin is down 0.4% at $64,700
Roland Head joins me today.
The table is complete.
Companies Reporting
Name (Mkt Cap) | RNS | AI Summary | Notes |
|---|---|---|---|
AstraZeneca (LON:AZN) (£216.9bn | SR49) | The EU has approved Klygefa, a once-weekly self-injected treatment for adults with generalised myasthenia gravis who are anti-acetylcholine receptor antibody positive. The approval rests on the PREVAIL Phase III trial, which met its primary endpoint on the Myasthenia Gravis Activities of Daily Living score at week 26 versus placebo. It is already approved in the US and Japan, with China under review. No sales impact is given. | ||
Legal & General (LON:LGEN) (£17.0bn | SR73) | Full-year earnings growth is on track to beat the top of its 6–9% target range. Pension risk transfer deals written or exclusive have reached £6.7bn this year, and Workplace net inflows were £4.5bn in the third quarter. The Solvency II ratio rose to 213% from 201% at the half year. Asset management net outflows were £3bn in the quarter. | AMBER/GREEN = (Roland - I hold) | |
IG group (LON:IGG) (£3.3bn | SR74) | Redomiciliation of IG from England and Wales to Jersey. Dealing in the original IG Group shares was suspended on Friday evening. New IG Jersey shares expected to commence trading at the open today. | GN note: I expect zero practical change when it comes to trading IGG shares (I'm long IGG). | |
Ninety One (LON:N91) (£2.0bn | SR49) | Assets under management grew 19% over the year to £181.4bn, but the firm lost £4.2bn in net outflows, against £4.3bn of inflows a year earlier. Adjusted operating profit rose 19% to £117.8m, lifting the margin to 32.5%, and the interim dividend rises 5% to 6.3p. Basic earnings per share fell 8% to 8.2p; the chief executive calls the flow experience “disappointing”. | ||
Grafton (LON:GFTU) (£1.9bn | SR93) | Trading is in line with expectations and full-year guidance is maintained. Like-for-like daily revenue growth improved to 2.0% in the four months to 31 October 2026 from 0.6% in the first half, as Ireland and Iberia offset a 5.2% fall in Great Britain. It still expects adjusted operating profit of £190–200m, against analysts' consensus of about £194.1m. | (Graham to do) | |
Sirius Real Estate (LON:SRE) (£1.6bn | SR78) | Sirius Real Estate - Interim results for six months ended 30 Sept 2026 | The group's funds from operations rose 11.9% to €72.4m, enough for a 26th straight dividend rise, to 3.35c. Profit after tax fell 60.8% to €34.1m, mainly because property values fell by €24.0m against a €14.4m gain last year. Net debt rose to 39.0% of property value, near the board's 40% cap. Trading is "in line with management expectations". | |
Great Portland Estates (LON:GPE) (£1.4bn | SR40) | Completed the sale of 2 Aldermanbury Square to Rothesay Life Plc for a headline price of £422.3 million, reflecting a net initial yield of 5.25%. Net price, after adjustment for outstanding rent frees (value of rent-free periods being deducted), of £368.7 million. Net price is 3% ahead of March 2026 book value and in line with September 2026. The proceeds will initially be used to repay RCF and reinvest into development pipeline. | ||
Victrex (LON:VCT) (£814m | SR88) | New CFO will join in February 2027. He was most recently Vice President Finance, Catalyst Technologies at Honeywell Technologies. | ||
Applied Nutrition (LON:APN) (£789m | SR47) | Revenue +51%. Adjusted EBITDA +40% (£43.3m), in line with upgraded management guidance provided in August 2026. Adjusted PBT +39% (£42m). "Notwithstanding a strong Q1 FY27, given that the financial year is still at an early stage, the Board believes it is prudent to maintain current market expectations for FY27." | (Graham to do) | |
Ceres Power Holdings (LON:CWR) (£550m | SR11) | Ceres Power Holdings - Ceres signs European SOFC manufacturing licence | New manufacturing licence agreement for the production of Ceres EnduraTM proprietary solid oxide fuel cell technology in the EMEA region. Financial terms consistent with previous Ceres manufacturing partnerships of this type. Ceres expects to recognise revenue related to the contract in the year, and therefore full year FY26 revenue to be c.£60m. | GN note: this looks like a useful upgrade against 2026 revenue expectations. Edison published a revenue estimate at the end of September of £58.4m. |
MHA (LON:MHA) (£418m | SR64) | Intends to rebrand as Baker Tilly in the UK from 1 February 2027. The UK rights to the Baker Tilly name are being acquired by Baker Tilly International, of which MHA has been a member firm in the UK since 2014. "Adopting the Baker Tilly name will give MHA the benefit of a recognised international brand and clearly demonstrate its membership of the network." | ||
ME International (LON:MEGP) (£383m | SR54) | Revenue and profit are guided to at least £309m and £66m for FY26. Laundry revenue is expected to rise about 14% on 1,224 net new machines, but photobooth revenue is expected to fall about 4%, with Japan and Germany weak. It returned £37m to shareholders through dividends and buybacks. | (Roland to do) | |
Solid State (LON:SOLI) (£103m | SR86) | Underlying growth has offset a tough comparison from large NATO-agency orders. Half-year revenue is expected above £87.5m and adjusted pre-tax profit above £5.0m, against £85.7m and £4.9m. Net debt was about £2.0m at 30 Sep 2026, but second-half working capital needs may raise it. The board is "confident in meeting its expectations for the full year". | ||
Helix Exploration (LON:HEX) (£80m | SR7) | Its Ross #1 well showed elevated helium while drilling, with peaks of 167ppm in the Souris River and 469ppm in the Red River. The readings were taken against heavy 10.5ppg mud, which the company believes suppressed gas at surface. It plans to test both formations once a workover rig is available, and says the shows cannot yet support any reserve or resource estimate. | ||
Triad (LON:TRD) (£68m | SR69) | Pre-tax profit rose 18% to £0.97m in the first half, but profit after tax fell to £0.74m from £0.88m because last year had a £55k tax credit. Revenue rose 3% to £12.41m. The interim dividend is held at 3p, and the board says it is “optimistic about the Company's prospects”. | ||
CML Microsystems (LON:CML) (£48m | SR54) | New CFO from February 2027. Was previously CFO of Cooke Optics. | ||
Synectics (LON:SNX) (£33m | SR67) | A defence customer has awarded about £2.0m of work: a £1.3m upgrade programme due in the first half of FY27, plus a maintenance extension to March 2030 worth about £0.7m. The company expects further expansion-related orders from the customer in the same period. No reference to any impact on market expectations. | ||
Kavango Resources (LON:KAV) (£27m | SR10) | Kavango Resources - Independent Regional Modelling Across KCB Licences | An independent study has produced a regional 3D model of the prospective D'Kar Formation across its Kalahari Copper Belt licences. It draws on a database of more than 7,600 drill holes and is meant to help prioritise drill targets beneath cover. The model is interpretive and "may not be confirmed by drilling". No drilling dates or funding are given. | |
Kelso group (LON:KLSO) (£23m | SR47) | Net asset value per share is up 68% since the start of the year, reaching an estimated 3.9p at 13 November 2026. Net assets rose to £21.6m from £10.3m, reflecting portfolio gains of about £9.2m and £3.4m of new funds raised. The latest gains came mainly from The Works, whose share price rose 20% since 28 October. | ||
Abingdon Health (LON:ABDX) (£22m | SR13) | Signed a Memorandum of Understanding with Centre for Process Innovation to explore opportunities for collaboration across the MedTech sector. CPI and Abingdon Health will work together to identify opportunities where CPI can support innovators. Programmes can then be transitioned to Abingdon Health for product verification, validation, regulatory support and scalable manufacturing. | ||
Cleantech Lithium (LON:CTL) (£21m | SR20) | Approval of the Laguna Verde lithium operating contract has hit a delay. The Chilean Comptroller returned the CEOL Decree to the Ministry of Economy and Mining on 13 November with observations. The Decree has not been rejected, and the Ministry is working to address them. The company had expected ratification within the government's earlier timetable. | ||
Pathos Communications (LON:NEWS) (£19m | SR30) | Buys podcast hosted by John Lee Dumas. Initial consideration of US$3.0m, payable in cash and funded from existing resources, and up to an additional US$6.0m of deferred, contingent consideration that is payable on achieving incremental financial performance targets for each of the three years from Completion. |
*Summaries are reviewed by our writing team.
Analyst notes
The company remains on track to hit full-year earnings guidance, but the slowdown in pension risk transfer has continued, with new deals falling below market expectations in Q3. Against this backdrop, growing profits from asset optimisation are helping to support earnings. While I have a few niggling concerns, on balance I think this remains a good business at a reasonable price.

At the time of publication, Graham has a long position in IGG shares.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
That’s superb analysis of Legal & General (LON:LGEN) Roland and with so much detail on the various parts of their business. I’ve held for years, so am very grateful to you.
IG group (LON:IGG) Just been informed that these shares can no longer be held in an ISA.
Also not tradeable at the moment so that money has been removed from ISa wrapper and can only go back if you have a flexible ISA . Disgraceful for an already bombing share
On BTC:
In countries with reliable currencies, Bitcoin’s main use is speculation (and, more recently, a “digital gold” store of value held via ETFs). Its main transactional niche has been illicit: darknet purchases and ransomware payments. Outside reliable countries / currencies it has had two genuine uses: paying into difficult jurisdictions (a supplier or contractor in Nigeria, Argentina or Turkey, where bank transfers take days and lose several percent to fees and FX spreads), and holding dollars where you otherwise can’t (residents of countries with high inflation or capital controls). Both often breach local FX or capital-control rules, though not always.
In the last few years stablecoins (USDT, USDC) have taken over both uses. They are cheaper and faster to transact and carry no price risk. They have also become the criminals’ tool of choice: Chainalysis estimates stablecoins were 84% of illicit crypto volume in 2025, with Bitcoin down to about 7%. Bitcoin turned out not to be very anonymous. It is pseudonymous, every transaction is public and traceable, and the privacy coins Monero (XMR) and Zcash (ZEC) do that job better.
Bitcoin also has no cash flows and a large running cost. Miners were paid roughly $17bn in 2025 to keep the network secure, and around 99% of that came from newly issued coins rather than user fees. In effect, holders pay a dilution tax of roughly 0.8% a year. Much of the on-chain volume is transfers between exchanges and speculation, not real payments. And the security bill doesn’t shrink as usage shrinks. The subsidy halves every four years, so either fees must rise to replace it or security falls.
If I’m right that Bitcoin has no moat beyond its brand, and no use that is not undercut / outperformed by an alternative coin, the cost of securing it will fall on a shrinking base of holders and fee-payers. This will not help BTC's price to rise.
Thank you, in other words avoid Bitcoin.
I wouldnt go that far - like TSLA and ANT, BTC is not for me - for what I think are good reasons. But the ability of the market to disagree with me is deeper than my pockets.
In context I have been predicting a house price crash since ~2008 and am still waiting - and do still have a house :)
I just got a message from IG saying that my IG group (LON:IGG) shares are no longer eligible to be held in an ISA and so have been moved to my share dealing account… does anyone know anything about this? Shocker
My ii ISA still has IG group (LON:IGG) in it, with a Corporate Action noted:
"IG Group Holdings
B06QFB7
Event type
Scheme of Arrangement D
Description
Scheme of Arrangement
Effective date: 13th November 2026
Terms: 1 share of Jenkins Topco Plc (to be renamed IG Group Holdings Plc) in exchange for every IG Group Holdings Plc share held
Expected payment date: 16th November 2026
IG Group Holdings Plc is undertaking a Scheme of Arrangement to redomicile the company from England and Wales to Jersey, effective from 13th November 2026.
Under the terms of the Scheme, holders will be issued with 1 share of Jenkins Topco Plc (to be renamed IG Group Holdings Plc, i.e. the companys name will stay the same) in exchange for every IG Group Holdings Plc share held.
The new post-Scheme shares are expected to be issued on 16th November 2026. However, please be aware that new shares resulting from Corporate Actions are not usually issued by the registrar until the afternoon of the payment date, and so there may be a period where the old holding remains on your account showing an incorrect value. Once we receive and post the new shares your account will show correctly."
Maybe holding in an IG ISA is treated differently?
Imagine that - an IG corporate action adding no apparent shareholder value screwing over all shareholders who are clients!
This looks to be due to IGG restructuring - pretty bad form if they didnt let you know in advance. AI recommends to contact them and not sell anything as this could remove it from your ISA wrapper. I think you need to get a formal response from them.
Re: IG group (LON:IGG)
The company has moved domicile to a Jersey today but is still listed on the LSE and is therefore still ISA eligible. Different providers may have different rules for themselves of course, but my shares are still held in my ii ISA.
timarr
As of today they are Jersey domiciled. Surprised that stops the being held in an ISA.
I held for several years and am thinking of buying back in now the valuation is so low, but maybe via my SIPP.
Not a big fan of IG group (LON:IGG) they treated me very poorly over some spread bets.
I had some short positions in companies that stopped trading and went bust.
IG would not close the bet for 3 years, so my money was tied up doing nothing.
Disgusting behaviour
Sirius Real Estate (LON:SRE) (I hold) . Would be grateful if the team has a moment to comment on today’s figures. Well over a decade of dividend increases now has made this a core lockup and leave holding in my portfolio.
I posted this chart on bitcoin a little while back... the current drop is retesting a historical s/r level, but also the 50 month moving average and a long-term channel.
Technically, I do think it is a critical area. A break below would be very bearish, but likewise a bounce from here could be significant.
It's hard to look much further than the $ and DXY making YTD high and 1 year high is a headwind for Bitcoin, Gold, silver and other commodities to be honest. Dollar strength being driven by higher rate expectations after poor CPI data .... could well be short lived if AI Capex is set to fall .... but no sign yet.
For anyone living near Worcester: We have one space left at our monthly Signet Investor meeting, 11am–2pm this Thursday 19 November.
We’re a friendly bunch and meet at Whittington Village Hall, just off Junction 7 (Worcester South) of the M5. Contact Ian for more details on 07813 817712
This month’s agenda is particularly topical:
a. Nvidia – implications?
b. US midterm results – implications?
c. Persisting volatility – tactics: anything from doing nothing to selling up?