Luceco: EV charging boost powers 17% rise in Q3 sales despite sluggish demand for core products

Analyst’s view:
A 220% increase in revenue from EV charging and related services reflects surging EV adoption and suggests to me that Luceco is probably gaining share in this market. Sluggish sales in the group's core business mirror the state of the UK housing market, but I'm happy maintaining a broadly positive view after today's in-line update.
Down 2.4% at 204p (£328m) - Q3 2026 Trading Update
Today's third-quarter update has received a slightly cautious reception, despite this electrical equipment supplier reporting revenue growth of 17% for the period.
I think the underlying reason for this may be that growth is currently concentrated in one product line - EV charging - with very limited growth in the company's core business.
Here's a summary of the key points:
Q3 like-for-like revenue growth of 17%
Q3 Energy Transition revenue up by 220%
Q3 Core Products revenue up by 3.4%
Q3 adjusted operating profit up by 60%, thanks to cost savings and a greater proportion of higher margin products being sold
Net debt leverage reduced to 1.4x EBITDA (H1 26: 1.5x)
"The Board remains confident that full-year 2026 Adjusted Operating Profit will be delivered in line with market expectations" (consensus is said to be £41.8m)
Luceco's Energy Transition business has two main revenue lines - EV Charging products and a Demand Flexibility service. This sees car owners with compatible chargers sign up to Luceco's Sync Energy platform, allowing them them to sell electricity from their cars' batteries into the electricity grid at times of high demand.
Luceco says it now has 31k Demand Flexibility subscribers and sees this as a valuable new long-term revenue stream. I'm hoping to see more financial disclosure around this service with the company's full-year results: it sounds promising but it's not clear to me what kind of numbers might be involved.
Outlook
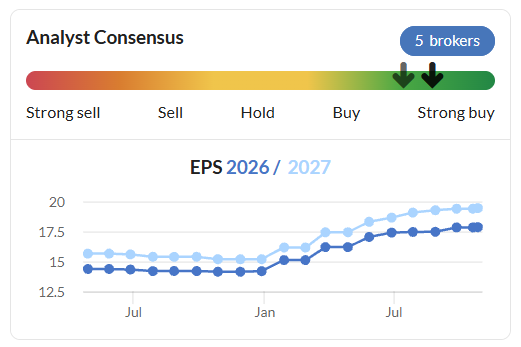
Forecasts from Longspur Research are unchanged today, suggesting FY26 adjusted EPS of 17.7p, broadly in line with Stockopedia's consensus estimate of 17.9p per share.
Estimated have edged higher in recent months, following substantial upgrades earlier this year:
Roland's view
Today's results highlight two trends: strong demand for EV charging and sluggish demand for the group's core wiring products. Both of these reflect underlying market trends in the UK (faster EV adoption and a sluggish housing market).
The company's core products and brand are well established and relatively mature, so I would hope that they are holding market share pending a return to more positive demand conditions.
I'd expect demand for EV charging products to remain strong for the foreseeable future, so there's potentially an opportunity for Luceco to gain the same incumbent status some of its core products enjoy. The pace of revenue growth in the Energy Transition business suggests to me that Luceco could be gaining market share in EV chargers, although I haven't done the research needed to confirm this.
However, while the Demand Flexibility service could help to improve customer stickiness, I would speculate that the company also runs the risk of being squeezed by competition from energy suppliers with much greater scale, who can offer the service as part of their electricity tariffs.
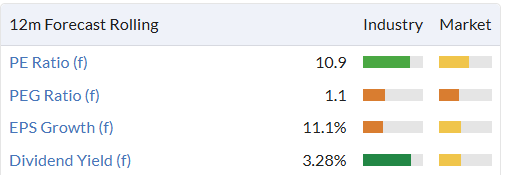
With a largely flat share price and unchanged forecasts today the valuation remains potentially attractive here, as Mark highlighted in September:
Given the positive trend to earnings forecasts and continues double-digit revenue growth, I'm quite comfortable leaving our AMBER/GREEN view unchanged today.
At the time of publication, Roland had a long position in LUCE.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Luceco (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?