ME Group International share price up as 14% laundry growth offsets earnings cut: still too cheap?

Analyst’s view:
The revenue and profit guidance provided for FY26 today are slightly below broker forecasts, but ME's share price has risen, suggesting investors may have been braced for much worse news. While I can see risks relating to regulatory change (photobooths), I think the laundry growth story remains intact and am happy to maintain a broadly positive view at this valuation.
Up 5.9% to 108p (£397m) - Year-end Trading Update
Self-service photobooth and laundry operator ME Group has issued revenue and profit guidance for the year ended 31 October today. The numbers provided appear to be slightly below broker forecasts, but ME's share price has risen, suggesting investors may have been braced for much worse news.
The TL;DR of today's update is that the laundry business is growing strongly, but photos are weaker than expected:
Wash.ME: 1,224 net new laundry machines were installed during the year, resulting in a c.16% increase in the total number in operation. Revenue from Wash.ME rose by c.14%, "despite softer consumer demand for laundry drying services" due to the long, hot summer across Europe.
Photo.ME: trading in most locations remained robust "against a backdrop of softer consumer demand", which management blame on "travel uncertainty" and the Middle East conflict. Germany and Japan are singled out as particularly challenging markets due to regulatory changes to the rules around photo ID in both countries. As a result, Photo.ME revenue in FY26 is expected to be down by c.4%.
Shareholder returns: £37m was paid out as buybacks and dividends during the year, equivalent to just under 10% of the current market cap.
FY26 Guidance
ME Group expects to report revenue of around £309m and adjusted pre-tax profit of not less than approximately £66m.
This revenue number is slightly below the £318m consensus estimate on the StockReport. The profit figure is also slightly below the £69-74m guidance range provided by management in July.
Both numbers are also lower than forecasts published by paid research provider Edison in July, which showed revenue of £319.8m and adjusted pre-tax profit of £69.8m.
Consensus EPS estimates on the StockReport have been cut by 2% to 13.4p today, confirming my view that this is technically a profit warning. I'm not sure it's worth categorising such a small cut as a downgrade though:
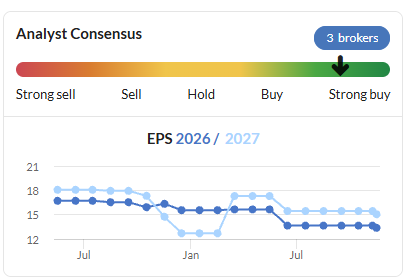
These revised estimates put ME Group on an undemanding FY26E P/E of around 8x, with a potential 7% dividend yield.
Roland's view
ME Group issued a much more material profit warning in June, blaming a travel slowdown. The group has also had to contend with a hot dry summer. When paired with cost of living pressures, this will logically have discouraged people from paying to use tumble dryers. I don't see this as a serious concern; as far as I can tell, the overall growth story for the Wash.ME business remains on track.
For me, what's more concerning is the implicit warning of the impact of changes to photo ID regulations on the performance of the photo business. This was limited to Germany and Japan last year, but who's to say this won't happen in other markets?
The argument is that the laundry business may soon become the group's largest division, reducing its dependency on photobooths. I can see this happening, although I think it's worth remembering that Photo.ME still generated around half group profits last year.
Another potential concern is that 84-year-old founder and CEO Serge Crasnianski tried unsuccessfully to sell the business in 2025, but has not yet felt able to hand over control to the Deputy CEO, who is his son.
The StockRanks view ME Group as a Contrarian situation, with high QualityRank and ValueRank but low momentum:
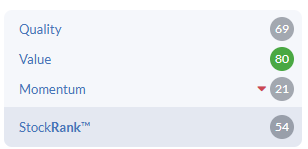
This squares with my own view. I think there are some reasons to be cautious here and perhaps assign a relatively low valuation multiple to the business. But given ME Group's track record of strong cash generation and attractive quality metrics, I suspect there may be an opportunity here.
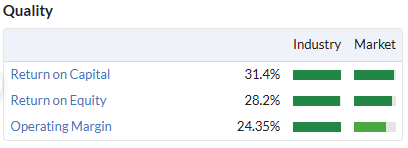
I'm going to leave my AMBER/GREEN view unchanged today. While the valuation might justify a fully positive view, I think the risk factors I've flagged above and the fact that earnings forecasts have technically been cut today precludes me taking a fully positive view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on ME International (5)
Comments here are also visible in the Daily Stock Market Report
ME International (LON:MEGP) is one I think is an exception to the "sell on a profit miss" advice.
Today's results for the FY confirms they will miss broker's forecasts. However, SP had already dropped more than -10% in the last few weeks; news must have leaked. Not great.
Some good buying support today. Including myself - I’ve just bought in a medium-sized position. So the shares are actually up a few % despite the profit miss.
The miss is all due to one-offs. Hot summer weather in Europe dampening dryer use volumes in WashME. This will reverse next year. Or stay the same (can it get dryer and hotter than the summer we’ve had?)
In PhotoME, I have dug deep and think they will see recovery in Germany next year. They now have approval for their next-gen photobooths there that will be eligible for passport photos. Just need to roll-out new equipment (the worry though is that it might be capex intensive). No other markets expecting regulatory changes in the next 1-3 years. So the cash cow plods on.
Things they can control: WashME rollout volumes continue as promised, good.
WashME now more EBITDA than PhotoME. So investors will soon flip their thinking from a legacy “cigar butt” business to a growth business with much runway to go. Instead of 8x PE, this should be 12x+ with yearly EPS growth of 10-20% too. Easily doubling of SP within two years.
I’ll be doing a deeper write-up soon on the reasons why I've bought and the risks left (eg founder is 80+, no one wanted to buy the company last year when it put itself up for sale...!)
(I hold in the Boon Fund)
Thank you for yet another excellent analysis. I have learned to place great store in your judgement. ME International (LON:MEGP) has tested investors' patience over the past few years but I hope that it is now starting to turn the corner. I have held since 2020 but intend to add now that the prospects appear better. The dividend of 8% is also not to be missed.
Hi Boon always value your views , I also hold ME International (LON:MEGP) did well out of it first time round but my second stab at trading it hasn't worked out as well.
Do you think the founder just wanted to high a price when he tried to sell the business ? Schroders were big supporters in the past but they have been reducing their position by a considerable amount over the medium term.
This does still look an attractive share if they can get back to growth as even the high dividend is covered from operating cash flow , but not from free cash flow I notice.
I don't like averaging down but am in two minds if it could be worth chancing at this level.
Regards
Andy
I don’t follow ME International (LON:MEGP) so have no view on plus and minus points.
A question I ask myself when thinking of averaging down, is simply are there better alternatives to go for?
'No other markets expecting regulatory changes in the next 1-3 years'
Given technological change surely we should definitely expect further regulatory as well as behavioural changes in the next 1-3 years? This could potentially work in their favour if governments clamp down on the risk of AI altered photos, but I don't think any govt has done that yet.
There is a risk this share becomes - if it's not already one - a value trap. Personally I'd prefer to get involved once they are trading above expectations or when the photo business is about to become a small rump of revenue and profits.