Mid-cap momentum stocks: QinetiQ & TP ICAP

In my last piece I looked at three big cap FTSE 100 stocks that scored highly in my recent momentum screen. I drew mixed conclusions about the outlook for these businesses. But I believe I’ve found some more promising opportunities among the smaller companies in the results of my momentum screen.
This week I’m going to look at two mid-cap stocks from my screen that I think could do well on a medium-term view. As always, please let me know what you think if these two businesses in the comments below.
Qinetiq (LON:QQ.)
Last week I looked at defence group BAE Systems. This week I’m looking at a smaller company from the UK defence sector, FTSE 250 member QinetiQ (LON: QQ.).
This stock stumbled in October last year when the company revealed a £15m impairment charge due to “technical and supply chain” issues. However, investor confidence has returned quickly, perhaps due to QinetiQ’s solid longer-term track record:

About QinetiQ: This business was spun out of the Defence Evaluation and Research Agency (DERA) when it was privatised in 2001. Historically, QinetiQ was heavily reliant on a handful of MoD contracts to run facilities such as firing ranges and pilot training, but it's been diversifying in recent years.
The company’s focus is on providing services and specialist technology systems. Examples include launch and arrest systems for aircraft carriers, mission training and simulation, cyber security and targets for live-firing exercises.
Today, the business is built around six core areas of expertise:
- Experimentation and technology
- Engineering services and support
- Cyber and information advantage
- Robotics and autonomous systems
- Test and evaluation
- Training and mission rehearsal
QinetiQ still generates 70% of revenue in the UK, but the company is now focused more broadly on the AUKUS markets – the UK, US and Australia. These countries account for more than 90% of revenue, with the remainder coming from a RoW segment:

Source: QinetiQ half-year results presentation (Nov. 2022)
Management believes that all of the group’s markets offer significant growth opportunities, with a total addressable market of at least £20bn.
Financial performance: Revenue growth has been admirably consistent in recent years, and broker forecasts suggest this performance will continue:

However, profit progression has been much weaker:
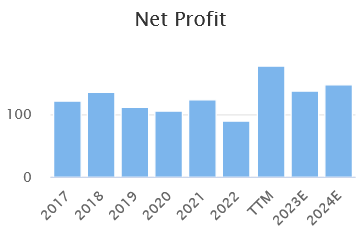
This has led to a disappointing fall in operating margins:

Forecasts for the current year suggest an improved performance. Qinetiq’s half-year results appear to support this more optimistic view, showing a welcome return to double-digit operating margins:

Order intake improved during the period and the business remained strongly cash generative, with a substantial net cash balance:

Overall, QinetiQ scores well for quality and fundamental health, reinforcing my view that the business is in good shape:

Is Momentum still strong? QinetiQ’s MomentumRank of 98 suggests very strong momentum. I think there are good reasons to believe the company’s recent performance could persist for some time yet.

Price Momentum: Key numbers I look for in this chart are positive 6m or 1y relative strength and a share price that’s above its 50d/200d moving averages. Research has shown that these factors are often correlated with medium-term outperformance.

Earnings estimates: Broker estimates have been upgraded on a number of occasions over the last year and show continued earnings growth next year:

Growth outlook: Unsurprisingly, QinetiQ says that it’s seeing “increased demand for our distinctive offerings driven by threat environment”. The company is also continuing to invest in new products and acquisitions to expand its presence in Australia and the USA.
Management is targeting five-year revenue growth of 75%, 12-13% operating margins and a return on capital employed at “the upper end of the 15-20% range”.
My view: QinetiQ’s revenue growth has been strong in recent years, but profitability has suffered and is below the group’s target range. In my view, the acid test for this business over the next few years will be to maintain growth while protecting margins.
The stock’s High Flyer status flags up the risk of a sharp correction of QinetiQ’s performance disappoints. But the shares don’t look overly expensive to me at the moment.
Figures for the last 12 months show an earnings yield (EBIT/EV) of 9%, above the 8% level I tend to associate with value. The stock’s P/E of 14 and thrice-covered dividend yield of 2% also look reasonable, given the group’s improving profitability.
The main risks I can see relate to profitability and acquisitions. If either disappoints, the valuation could fall.
However, on balance, I think QinetiQ looks reasonably priced, with a positive outlook. I’ve recently added the shares to my rules-based SIF folio.
TP Icap (LON:TCAP)
FTSE 250 financial group TP Icap (LON:TCAP) was formed through the merger of London’s two leading interdealer brokers, Tullett Prebon and ICAP. Both companies had well-connected teams of brokers who would work the phones to negotiate complex trades that couldn’t be placed through exchanges.
Voice broking remains a valuable service, but it’s lost market share to electronic trading over the last decade. The combination of ICAP and Tullett in 2016 was intended to combat this decline. However, the group’s turnaround has taken longer than expected and required several more acquisitions.
The business now offers a broader range of broking, electronic trading and data services:

Today, TP ICAP shares trade 50% below the level seen when the two businesses combined at the end of 2016. Indeed, the shares have recently been trading at levels not seen since the 2008 financial crisis.

Encouragingly, the second half of this year has brought improved results and stronger share price momentum.

I’m increasingly inclined to think TP ICAP could offer an opportunity at current levels. Stockopedia’s algorithms seem to agree:


Recent trading: Group revenue rose by 10% to £1,588m during the first nine months of 2022 on a constant currency basis. Including the tailwind from the stronger dollar, reported revenue was up by 15%.
At a divisional level, revenue grew in the core broking division and the agency execution business. Revenue in the energy and commodities business fell by 3% compared to the same period in 2021, reflecting lower volumes.
Full-year results are expected to be in line with expectations. Based on Stockopedia consensus forecasts, this suggests a 14% increase in adjusted earnings, leaving the stock looking potentially very cheap:

Strong momentum? TP ICAP’s MomentumRank of 98 reflects strong technical momentum and an improving outlook for earnings.
Price momentum: The stock’s positive relative strength shows that TP ICAP shares have outperformed the wider market over the last three, six and twelve months.

Looking further down the graphic above, trading volumes appear to have fallen sharply in recent weeks. I think this may relate to asset manager Schroders taking a 10% holding in TP ICAP in October, so it’s not necessarily as negative as it might appear.
Earnings estimates: After a long period of decline, analysts have turned positive on TP ICAP. There have been several minor upgrades to earnings estimates since August, although forecasts are still lower than one year ago:

One of Jim Slater’s rules of thumb was that investors shouldn’t buy into turnarounds until the outlook for earnings turned positive. I’ve found this to be good advice over the years, so I’m encouraged by the improving sentiment implied by the consensus trend.
My view: TP ICAP has benefited from market conditions over the last year. But I think it’s fair to say that the group is now performing much better than it has been in recent years, with a positive outlook across its main divisions.
I don’t think the current valuation reflects the improvements seen already, or the return to growth that’s expected over the next 18 months. In my view, TP ICAP looks very interesting at current levels.
Disclosure: Roland owns shares of QinetiQ.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
I'm not really qualified to say and don't want to seem a cheap critic, but I think readers should perhaps be slightly careful with rushing in to buy TP Icap (LON:TCAP) based solely on it having a lot of green on the stocko page and having "momentum".
e.g. " trading at levels not seen since the 2008 financial crisis." Well, how many shares did it have in 2008? I see it had about 200m in 2013, 500m a couple years ago and now almost 800m. So it's a completely different business. Were the acquisitions good? When Liquidnet announced 2020 shares dropped 15%. A few months ago shares were less than the price of that acquisition...there's litigation, complicated accounts and adjustments. Maybe a great platform business underneath as well but needs a deeper look, no?
The reason for the momentum recently is in part a special situation angle :
phase2partners.egnyte.com/dl/SsSCmrDqHy
City investors press TP Icap for £1.5bn Parameta windfall | Business News | Sky News
which goes unmentioned in the article.
Hi Samscvb,
Thanks for your comment - I agree there's been a lot of dilution since 2008 and TP Icap (LON:TCAP) is a somewhat different business to what it was then.
My comments only represented an initial look at TCAP, due to time and space constraints. I certainly wouldn't suggest that anyone should buy on the strength of a short review. These articles aren't intended to be advice, and are not a substitute for DYOR.
The sale of Parameta would be a material change, but proposals for such corporate breakups often emerge and don't always amount to much. These ideas are sometimes put forward by hedge funds seeking quick returns, which seems to be the case here -- this story first cropped up in the FT in March.
I think the recent share price strength is at least partly due to the improved numbers in August's half-year results and to a more positive, stable outlook for the enlarged business.
Although risks remain, I my feeling is that the outlook is more positive than it's been for a while.
Regards,
Roland
Cheers Roland
As you rightly point out Roland the one thing that has put me off Qinetiq (LON:QQ.) is it's historical falling margins as revenues grow, which I put down to poor governance. TTM looks to paint a different picture on margins, but want to see 'it in the bank' before I change my stance
TP ICAP has over £2bn cash on its balance sheet. Presumably with rising interest rates this will be a handy tailwind to profitability.