Morgan Sindall share price rises as it builds towards a strong 2026 result

Analyst’s view:
We've been mostly GREEN on this stock in 2026 - for example, see my most recent comments in July. Today's statement helps to reassure me that this is the right call for us. Like the traditional housebuilders, it has exposure to the first-time buyer - with all of the affordability and mortgage interest rate concerns associated with that. But unlike the traditional housebuilders, it also has heavy exposure to the commercial market and to a wide range of other sectors, through its Fit Out and Construction sectors. In that sense, it's a truly diversified bet on construction activity in general.
Up 9.5% at £45.32 (£2.2bn) - Trading and Outlook for 2026 & Launch of £75m share buyback
This construction and regeneration group is trading very well. Let's take a look at the key points from today's trading update:
Full year results for 2026 to be slightly ahead of its previous expectations.
Looking at it by division:
Fit-out: slightly ahead of the prior year (operating profit £139.9m).
Construction: significantly ahead of expectations with operating margins at upper end of 3.5% - 4% medium-term target (operating profit last year: £39m).
Infrastructure: double-digit growth on last year's result (£37.2m).
Two of the divisions are a little more complicated:
Partnership Housing: profits below previous expectations (last year: £42m), "reflecting prevailing market conditions of low consumer sentiment and affordability pressures". But poised to benefit from the government's Your First Home scheme.
Mixed Use Partnership: will show a loss similar to last year's loss (£5.3m). Project starts are weighted towards the second half, so that the financial result for the year will reflect their upfront costs.
We also get an outlook statement for 2027:
Despite the prevailing market conditions, the strength and breadth of the Group’s diverse operations, the visibility provided by its high-quality order book for the forthcoming year, and alongside the self-help measures already taken accompanied with the capital allocation discipline in place, the Group remains confident that the outlook for 2027 will be in line with current expectations.
Buyback
Average daily net cash has been £400m in the year-to-date, up from £362m in the same period last year.
Of this amount, only £51m is in JVs or earmarked for payments to suppliers. So there's about £350m of flexibility.
The company provides some helpful insight into how it manages its cash balance. It first uses the lowest net cash position in the year as its reference point (although that exact number is not given today).
It then sees how that lowest net cash position could be used in order to:
Maintain a strong balance sheet
Invest in Partnerships
Provide "ordinary" returns to shareholders
Invest in acquisitions
Special returns to shareholders
With less funds needed for Partnerships going forward, and considering the company's "strong underlying cash flow generation and strong balance sheet position", it has approved a £75m buyback starting today, to be completed towards the end of 2027.
Graham's view
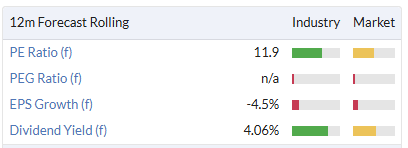
At the current market cap, the buyback will only reduce the share count by about 3.5% - a very mild reduction in my book.
Given that mild reduction, I'm not too stressed about whether or not the company is getting the absolute best value it could from the current share price:
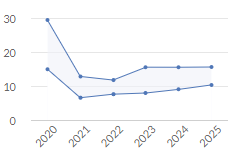
History suggests that the current earnings multiple represents a normal valuation for the company, suggesting that it's neither particularly cheap nor expensive:
We've been mostly GREEN on this stock in 2026 - for example, see my most recent comments in July.
Today's statement helps to reassure me that this is the right call for us.
Even leaving aside the attractions of the business itself, I appreciate any management team who will give us average net cash figures, and help us clearly understand how they prioritise the use of this cash. The fact that Morgan Sindall has accumulated such a large cash balance is a bonus - and helps to demonstrate the health and success of the business.
Like the traditional housebuilders, it has exposure to the first-time buyer - with all of the affordability and mortgage interest rate concerns associated with that. But unlike the traditional housebuilders, it also has heavy exposure to the commercial market and to a wide range of other sectors, through its Fit Out and Construction sectors. In that sense, it's a truly diversified bet on construction activity in general.
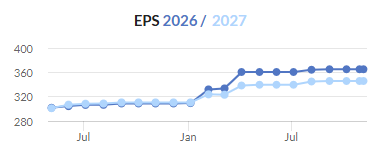
So I continue to like the story here. Its earnings forecasts have been rising through 2026 and while the shares are not a bargain, I see no reason to fight the trend.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Morgan Sindall (2)
Comments here are also visible in the Daily Stock Market Report
But isn't a problem here for Morgan Sindall (LON:MGNS) that it's reiterated estimates for next year which are for lower EPS?
A review of Morgan Sindall (LON:MGNS) if possible please.