Northern Bear to become a very different investment proposition after tender offer

Analyst’s view:
This is going to fundamentally change the risk profile of NTBR shares: rather than a business with more than enough cash than it needs, it will have a "modest" level of net debt. By the time the transaction is done, the share count will have reduced by a massive 50%. On the basis that interest costs are modest and the business remains profitable, this has the potential to transform earnings per share. In that sense, it's an exciting and bold move - but one that also carries plenty of risk. We've been GREEN on Northern Bear, for reasons of its cheap valuation and balance sheet strength. I'm going to remain fully positive on it for the time being but when the tender offer takes place, I should probably revise my stance to a more cautious one.
Up 11% at 130p (£18m) - Interim Results & Proposed Tender Offer
As we noted over the summer, this little group of building services companies has attracted a bit of a following thanks to its dirt-cheap valuation metrics.
I've been fully positive on it since November 2025 (moderately positive before then).
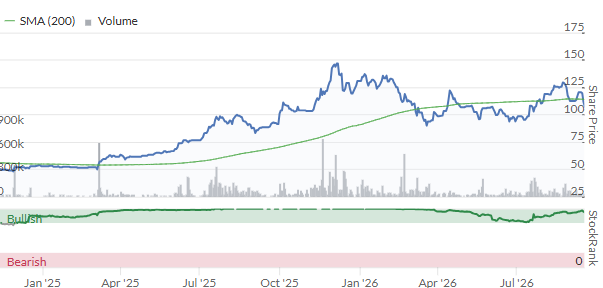
Let's dig in a little into today's interim results.
Management say that first-half revenue and adjusted profits were in line with market and management expectations.
Looking ahead, the full-year result for FY March 2027 is expected to be broadly in line with market expectations.
This outlook is qualified heavily, hinting at the uncertainty that goes hand-in-hand with any investment in this sector. The outlook assumes all of the following:
...that current market conditions do not worsen, there are no further one-off non-recurring losses, the additional investment in operations continues to meet revenue expectations and that there is no major weather-related disruption outside of the weather expected in the Group's geographic areas of operation between the October and March period.
The H1 results, despite being in line with expectations, are not too inspiring:
Revenue down 21% to £38.9m
Operating profit halves to £2.1m
Earnings per share halves to 11.2p
Note however that with a share price of 130p today, and a healthy cash balance supporting the company, we can still get a potentially attractive earnings multiple on the basis of full year earnings.
It's also worth mentioning that the result for H1 last year included a profit of £1.3m that management described as "not expected to recur in future periods". It was some type of one-off, exceptional trading profit, and it makes the comparison against last year very difficult.
On an adjusted basis, excluding that one-off profit from last year, Northern Bear's operating profit in H1 has fallen by 25%, rather than halving.
Estimates: Hybridian published estimates in September suggested that FY27 would see EPS of 18.9p on revenues of £86.9m. The actual H1 result has therefore generated 45% of forecast full-year revenue, and 59% of forecast-full year profits.
Market conditions: these sound quite poor.
Market conditions are largely flat within the geographical areas that the Group operates in and market pressures are starting to affect some of the Group's businesses, specifically those businesses such as Alcor and Arcas which are dependent on private sector clients. The Board does not envisage any market uplift in the foreseeable future, given the macroeconomic situation.
Alcor is Northern Bear's materials handling business, while Arcas is a building contractor.
Cash: net cash of £3.8m is "a snapshot at a particular point in time and can move by up to £1.5m in a matter of days; given the nature, size and variety of contracts that we work on and the related working capital balances." The company very helpfully provides the low point (£2.6m), the high point (£6.6m) and the average (£4.5m). Investors can hardly ask for more than that!
Tender offer: the company is proposing to return a massive (relative to the market cap) £9.1m of cash to shareholders with a tender offer for 6.9 million shares at 132.5p.
That's a really significant premium to the prevailing share price, which should encourage takeup.
How can they afford this? Simple: they are going to move from net cash to net debt.
It sounds as if some shareholders may have had words with management about their desire to sell: "The Tender Offer would remove the prolonged uncertainty that an overhang of shares would create should any significant Shareholders wish to sell their holdings through the market."
Or in more words:
Recognising that funds are unlikely to be required for acquisitions in the short to medium term, and being cognisant of shareholder views regarding the mechanism for capital to be returned to shareholders, the Board has concluded that the Company should undertake a Tender Offer primarily as an event accretive to earnings per share and secondarily as a means for Shareholders who wish to exit their investments to do so in an orderly manner, while still ensuring the Company could secure sufficient funding to pursue its growth strategy if the right opportunity presented itself.
The largest shareholder (owning 23% of the company) has undertaken to tender his entire shareholding.
Graham's view
This is going to fundamentally change the risk profile of NTBR shares: rather than a business with more than enough cash than it needs, it will have a "modest" level of net debt.
By the time the transaction is done, the share count will have reduced by a massive 50%.
On the basis that interest costs are modest and the business remains profitable, this has the potential to transform earnings per share. In that sense, it's an exciting and bold move - but one that also carries plenty of risk. Virgin Money plc will be the main lender providing an RCF.
We've been GREEN on Northern Bear, for reasons of its cheap valuation and balance sheet strength. I'm going to remain fully positive on it for the time being but when the tender offer takes place, I should probably revise my stance to a more cautious one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Northern Bear (1)
Comments here are also visible in the Daily Stock Market Report
Northern Bear (LON:NTBR)
Uber bold move by northern bear to buy back nearly half the share capital of the business - I can’t believe for a second that this will fully be taken up by shareholders - the actual % they will buy back may depend on some of the bigger holders perhaps if they want to accept something close to clean break or sell high %.
Ref actual trading it seems to be a bit anemic ref outlook at present but they have delivered a decent first half so it’s kinda semi steady as you go - results last year were always flagged up at the get go as being one off ref ref high level of profits due to one very profitable contract.
Note this company doesn’t normally over promise so conservative outlook is pretty standard for them.
What % of shares will be tendered - I know not - if I was a guessing man I would be surprised if they got away with much more than 50-60% of the number they have offered to buy back max - perhaps something 25% plus might be expected - it could be anything.
I don’t have an an plans to sell material amounts below 150p whilst is making 2.5 mill plus net profits eos should take nice jump with less shares in issue - I would expect shareprice might settle at 130p today factoring in ability of shareholders to exit at just above that level via share tender.