Rank investors breathe a sigh of relief as tax hike not as bad as feared

Analyst’s view:
While this news is technically a profit warning, markets should have been braced for a Budget impact - and the impact could have been much greater, if the threat to double MGD had been carried out. Instead, we've had a 10% cut to the profit forecast - and the Rank share price rose by 12% on Wednesday, before dropping back a little on Thursday. I was moderately positive on Rank a few months ago at a price of 103p. With the shares now trading at 90p, I am happy to maintain that stance. The stock is offered at a modest earnings multiple for a well-established business where the major near-term risk has now been resolved.
85.9p (£403m) - Autumn Budget Impact (profit warning, released on Thursday 29th October)
It had been heavily rumoured that machine games duty (MGD) might have doubled, from 20% to 40%.
As we have said in this report previously, that would have been an enormous blow for Grosvenor casino owner, Rank Group.
Rank has only recently installed hundreds of new gaming machines, thanks to updated regulations on land-based gambling which massively increased the legal capacity for such machines.
Here is Rank's response to Wednesday's Budget, which announced an increase in MGD from 20% to 25%:
It is anticipated that the annualised impact of this move will be an additional cost of c. £9m, prior to the Group undertaking mitigating actions, with duty costs for the current year (ending 30 June 2027) increasing by c. £2m. The Group remains confident of delivering Group LFL operating profit in line with expectations for the current year.
So there is no major impact for the current year, but there is an impact for future years.
Estimates: Shore Capital have updated their Rank forecasts. Their existing forecasts were based on no change to MGD, and I suspect that was likely to be true of the other brokers covering the stock, too.
While FY June 2027 forecasts are virtually unchanged (ad. PBT £54.7m, earnings per share 9.1p), there are some significant changes to future years.
On a much-reduced revenue growth forecast, the adj. PBT forecast for FY June 2028 falls from £67.8m to £61.2m (down 10%). The corresponding EPS forecast falls from 11.4p to 10.3p. It is envisaged that only a few million pounds of the estimated £9m impact from the tax hike can be mitigated.
Graham's view
While this news is technically a profit warning, markets should have been braced for a Budget impact - and the impact could have been much greater, if the threat to double MGD had been carried out.
Instead, we've had a 10% cut to the profit forecast - and the Rank share price rose by 12% on Wednesday, before dropping back a little on Thursday.
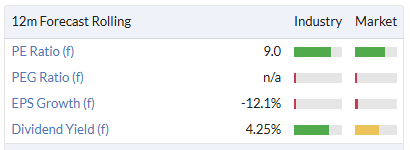
I was moderately positive on Rank a few months ago at a price of 103p. With the shares now trading at 90p, I am happy to maintain that stance. The stock is offered at a modest earnings multiple for a well-established business where the major near-term risk has now been resolved:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Rank (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?