Record: Solid H1 results with revenue up 19% but dividend reduced significantly
Analyst’s view:
A solid update from Record today with revenue up 19% and EPS coming in at 2.84p versus 1.93p a year earlier. The company has managed costs carefully leading to a big jump in its operating margin.
Flat at 46.8p (£93m) - Interim Results
Currency specialist and alternative asset manager Record has today published its Interim Results for the six months ended 30 September 2026 (H1 FY27). Let’s unpack them.
Highlights:
Revenue increased by 19% to £22.8 million (H1 FY26: £19.2 million).
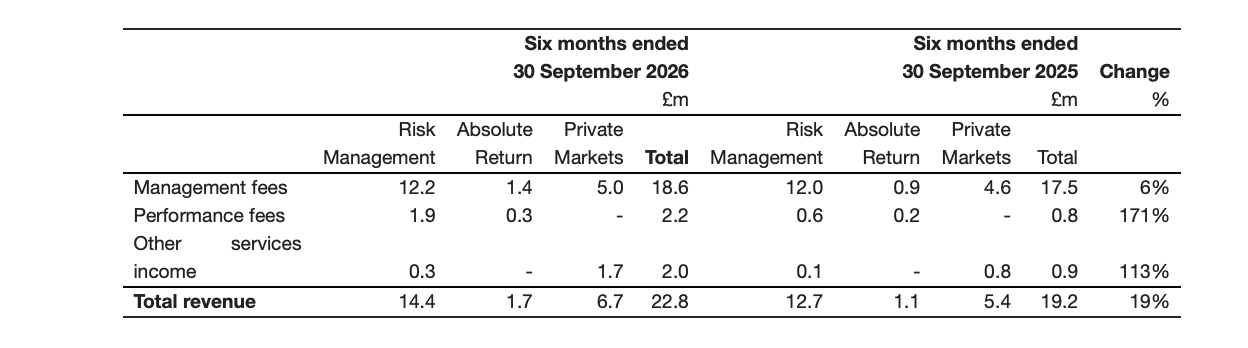
Management fees increased by 6% to £18.6 million (H1 FY26: £17.5 million), with growth across all three product pillars.
Performance fees of £2.2 million (H1 FY26: £0.8 million).
AUM increased to a new high of $130.3 billion (FY26: $114.6 billion), including net inflows of $12.7 billion.
Operating margin increased to 32.3% (H1 FY26: 23.4%) in line with higher-margin growth and continued cost discipline.
Profit after tax attributable to Record plc shareholders increased by 49% to £5.6 million (H1 FY26: £3.7 million).
Basic EPS of 2.84 pence (H1 FY26: 1.93 pence).
"This was a strong first half for the Group, both operationally and financially. We are executing against our strategy and positioning the business for sustainable, long-term growth and an improved quality of earnings. That progress is clear in our results, with record AUM, inflows across all three product pillars and a return to revenue and earnings growth.”
Dividend info:
New dividend policy announced, targeting a 40-60% payout range of annual after tax profits.
Interim dividend declared at 1.00 pence per share (H1 FY26: 2.15 pence per share).
“Our new dividend policy supports our capital allocation framework for the next phase of that strategy, striking the right balance between maintaining balance sheet strength, providing flexibility to invest in growth and delivering sustainable returns to shareholders."
Outlook:
“The progress we have made in the first half of FY27 reinforces my confidence that we are on the right path. With record AUM, strong momentum across all three product pillars and a strengthened leadership team, Record is well positioned to create sustainable long-term value for our clients and shareholders. Performance across the Group continues to support our expectations for the current financial year.”
Ed S’s view:
Record shares took a big hit back in June when the company posted its results for FY26. Those results were pretty weak, with revenue down 4% and basic EPS down 22% (and below expectations).
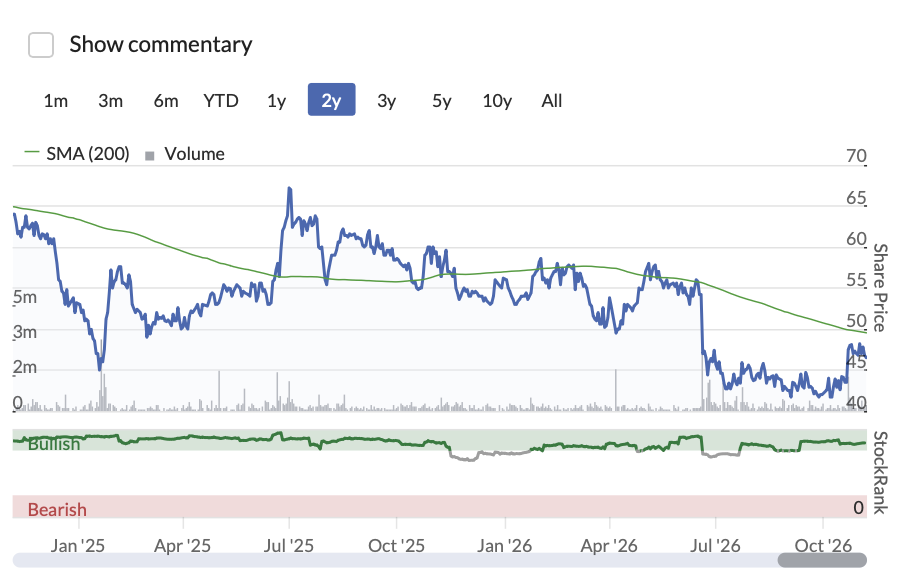
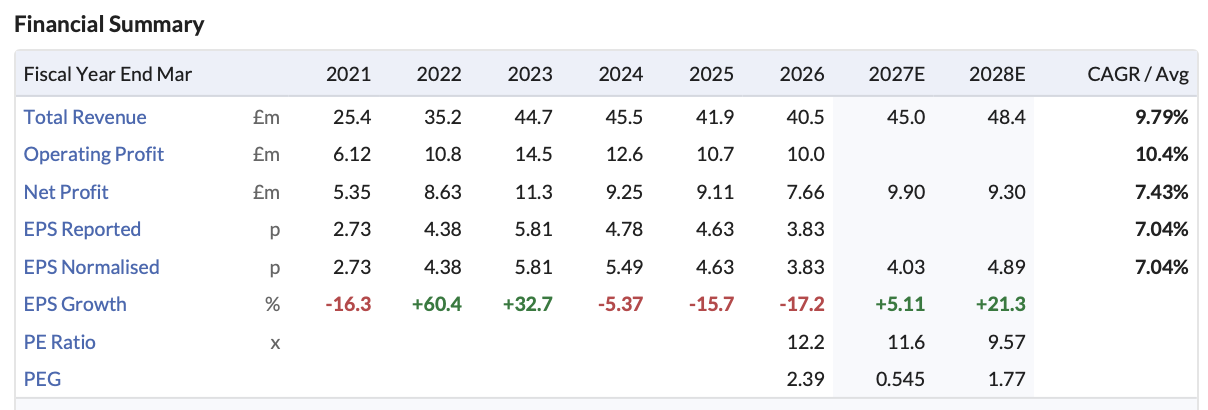
Today’s H1 results for FY27 look far better – revenue for the period was up 19% year on year while operating profit and EPS were up 64% and 47% respectively. Note that with EPS coming in at 2.84p, the company is very much on track to achieve the full-year EPS consensus forecast of 4.03p.
Encouragingly, operating margin was 32.3% versus 23.4% a year earlier. This was the result of the strong increase in revenue coupled with a marginal cost increase (operating costs only increased 3% versus the 19% jump in revenue).
The revenue breakdown can be seen in the table below. Both Absolute Return and Private Markets performed well while revenue also got a nice boost from performance fees (which can be variable).
As a quick explainer:
Risk Management: This comprises its core Passive Hedging and Dynamic Hedging solutions and is a source of stability for the group.
Absolute Return: The Absolute Return strategies extend its hedging expertise into carefully controlled sources of active return.
Private Markets: This offers a range of alternative investment funds and is where the group sees the greatest long-term opportunity as it offers higher-margin, scalable, and long-dated revenues.
I’m a fan of this diversified business model. It means the company has numerous ways to generate revenue and isn’t dependent on one strategy.
I also like the Private Markets exposure. This is an area of the wealth management industry that is growing rapidly as institutional and retail investors are moving to diversify away from stocks and bonds.
“As the fragmented market environment continues to evolve, institutional investors are placing more emphasis on diversification, on actively managing their currency exposures and on finding sources of return that are uncorrelated with traditional assets. These are areas where Record's expertise is particularly relevant, and the new business we have won this half shows that clients increasingly look to us for solutions.”
Today’s results show that the group is managing costs carefully, which is a plus. Total operating costs for the period were £15.2 million, just 3% higher than in H1 FY26.
“Cost control has been a key area of focus over recent years, and we have made consistent progress. Our priority now is to maintain that discipline, while remaining willing to invest where it supports our growth in higher-margin products. Our focus is on ensuring that any increase in costs is outweighed by revenue growth, translating into an improved operating margin over time.”
It has also tweaked its dividend policy to conserve cash. The payout range will now be between 40% and 60% of profit after tax attributable to equity holders.
For the last two years, the group had returned over 90% of earnings through dividends and that wasn’t really sustainable. So, I see the dividend policy change as another plus.
“This strikes the right balance between maintaining balance sheet strength, having a sensible buffer above our regulatory capital, and retaining the flexibility to invest in the business, all whilst delivering a sustainable dividend to shareholders.”
When Graham covered the group’s full-year results in June, he took Record down to an AMBER/RED rating. However, in October, Mark lifted the rating to AMBER on the back of a decent Q2 trading update.
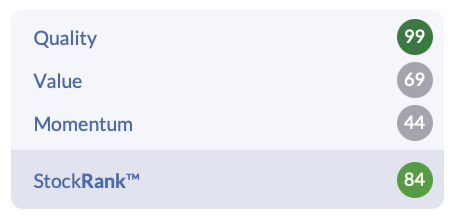
For now, I’m going to leave it on AMBER just because we’ve had some poor results in the recent past. However, if the group can continue to perform well, there could be justification for another upgrade as the valuation here isn’t particularly demanding and the StockRank is solid at 84.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Record (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?