SIF April review: Dividends boost returns from Bloomsbury & Bovis Homes

The market has performed fairly well over the last month, despite the uncertainties facing the UK economy and wider global markets. The SIF fund is showing a gain of about 4% for the month and several holdings have enjoyed a notable boost. I hope your portfolios have done well too.
As it’s the end of the month, it’s time to review any stocks which have been in the portfolio for at least nine months. Two stocks qualify -- both popular names.
Mello 2019: Before I get started, just a quick reminder that the Mello 2019 investor show takes place in mid-May. I’m making the trip down south for the first time, so I hope to be able to put some faces to names and meet some of you.
An impressive line-up of expert speakers and companies have been confirmed for the show, so there should be something of interest for everyone.
Stocks for review
Two companies are up for review this month:
Bovis Homes Group (LON:BVS) - this FTSE 250 housebuilder is performing well, but cyclical and political risks are an ever-present concern.
Bloomsbury (LON:BMY) - Harry Potter publisher Bloomsbury still looks a wizard buy based on its StockRank of 95. But does this well-regarded small cap still pass all of my screening tests?
Here’s how these two firms’ shares have performed during their time in the portfolio:

Bovis Homes Group (LON:BVS)
(Original coverage 11/07/2018)
Housebuilders have been priced like late-stage cyclical stocks for about three years now. But profits have been supported by a gravy train of cheap mortgages, inflationary government subsidies (Help to Buy) and apparently insatiable demand.
Even now, with prices said to be falling in London and the South East (according to the Nationwide House Price Index), builders’ profits appear to be holding up well.
The end result is that shareholders willing to sit on their hands have enjoyed some staggering cash returns. Dividend yields have hit 10% in some cases. This can’t continue forever, but when will things change? I’ve no idea.
Has Bovis delivered? When I added Bovis to the SIF folio last July, the firm was still in turnaround mode after production shortfalls and quality problems hit profits. However, boss Greg Fitzgerald seemed to have a good grip on the situation. My hope was that as margins recovered, improved sentiment would help to protect the shares from cyclical risk.
The company’s 2018 results confirmed a strong recovery. Operating margin rose by 3.9% to 16.4%, contributing to a 47% increase in pre-tax profit. The company also appears to have repaired its relationships with customers. Bovis gained four-star HBF customer satisfaction score last year.
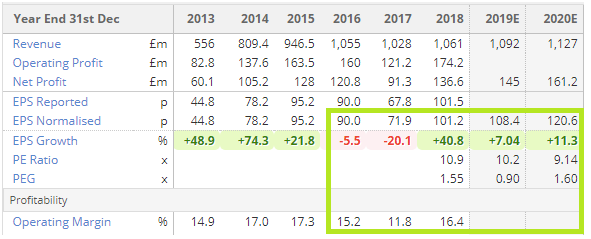
Rising costs are still a concern, but brokers are still expecting a 7% rise in earnings this year and another bumper cash return of 102p per share. This gives the stock a 9.3% forecast yield at current levels.
Does Bovis still pass my tests? Last year’s strong performance hasn’t been reflected in the share price, which has lagged the market by 10% over the last year. This has left the stock with a negative 1-year relative strength reading, failing one of my screening rules.
Slowing earnings growth also means that the stock’s rolling PEG ratio has risen above my maximum of 1.2.
As a result, Bovis no longer passes all of my screening tests and will be sold from the portfolio. It’s worth noting that although the share price is pretty much unchanged, shareholders have qualified for dividends totalling 102p per share during the period. Based on the SIF’s price paid of 1,107p, that would give a dividend yield of 9.2%. That’s a satisfactory return for nine months, in my view.
Verdict: Sell
Total return: +9.5pc
Bloomsbury Publishing (LON:BMY)
(Original coverage 31/07/2018)
This publisher is probably best known as the home of the Harry Potter books. Certainly the schoolboy wizard has made a big contribution to its profits and growth over the last decade or so.
However, Harry Potter isn’t the only game in town, as the firm’s management is keen to point out.
Bloomsbury’s full-year trading update in March led with “strong performance” in the non-consumer academic and professional division, which is said to be delivering organic revenue and margin growth.
Elsewhere, “In the Closet of the Vatican” was apparently an international non-fiction bestseller. The group also reported a number of strong performers in its consumer line up, which includes fiction and non-fiction. There was no mention of the schoolboy wizard.
Management expect to report net cash of £27m at the year end, up from £25.4m last year. But sales and profit are expected to be broadly flat, with forecast earnings of 14.3p per share versus a 2018 figure of 13.9p.
A stronger performance is expected in 2019/20:
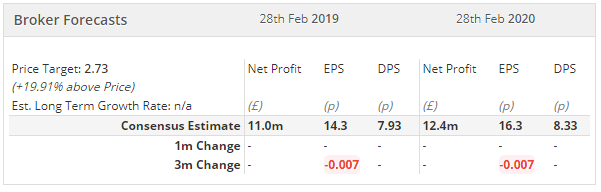
Based on these forecasts, which suggest earnings growth of 14% during the current year, I’d argue that the valuation of 14x forecast earnings is probably about right.
Does Bloomsbury pass my tests? In a long-term portfolio, I’d be very happy to continue holding this company despite its relatively modest profitability:
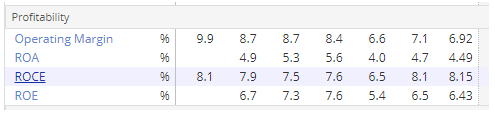
I like the company’s consistency, strong balance sheet and apparent ability to find profitable niches. However, Bloomsbury shares now fail my screening tests on two counts: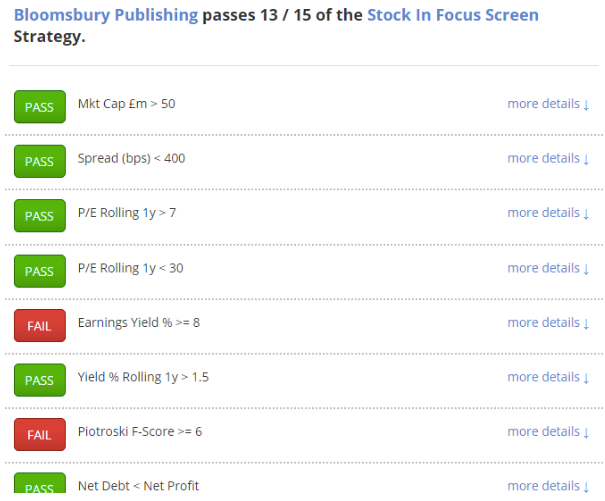
A slight rise in price and fall in trailing profits versus FY18 has reduced the stock’s earnings yield (EBIT/EV) to below my 8% minimum.
This drop in profits has also caused the stock’s Piotroski F-Score to fall.
Both measures are important parts of my system. I wouldn’t consider ignoring either of them. This means that Bloomsbury will also be sold from the SIF portfolio this week.
Verdict: Sell
Total return: +2pc
As usual, I will sell both of these shares from the SIF fund and my own holdings after this article has been published on Stockopedia.
Next week…
I hope to find a new stock to add to the SIF folio next week. However, my screening results are meagre at the moment and don’t currently include any eligible new stocks. So we will see.
As always, thanks for reading and for your valuable contributions.
Disclosure: At the time of publication, Roland owned shares in Bloomsbury Publishing and Bovis Homes Group.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Roland, I hold a small stake in Bloomsbury Publishing (LON:BMY) to and I too have been considering selling. You mention a deterioration in their F Score to 5/9 and indeed there has been, but 3 of the Fail ratios are within a hair’s breath of a Pass, which would make the F Score an attractive 8/9....
Bloomsbury Publishing Details: ROA TTM = 4.62 , ROA Prior TTM = 4.71
Bloomsbury Publishing Details: Gross Mgn % = 51.3 , Gross Mgn % PTTM = 52.2
Bloomsbury Publishing Details: Asset Turnover (Piotroski) TTM = 0.83 , Asset Turnover (Piotroksi), PTTM = 0.84
I see that the finals are due in 3 weeks (21st May), so I have decided to wait for the actuals and their updated outlook, which may enhance broker forecasts.
Hi iwright7,
Thanks for your comment. Some of the F-Scores for Bloomsbury Publishing (LON:BMY) are indeed very close to pass levels.
If I held the shares in a long-term discretionary portfolio, I would be very unlikely to sell them without at least waiting for the results.
My rules-based approach doesn't allow me this latitude, unfortunately.
Regards,
Roland