SIF Portfolio: I add Zulu pick Cambria Automobiles, plus an upgrade for Somero

My view of markets at the moment is that until evidence to the contrary appears, we need to treat UK plc as a going concern in reasonably good health. Ultimately, I expect the outcome of Brexit to be neither as good nor as bad as some pundits are suggesting. Thus the economic reaction may also be fairly middling.
I’d argue that the market reaction to the referendum has only exaggerated trends that were already visible. Weak trading on the high street, a more cautious view on housebuilders and a recovery in commodity stocks were all apparent before we voted to leave.
 One company that was doing well before the referendum and appears to remain in good health today is Cambria Automobiles. The referendum result hit car dealers’ share prices hard. But there’s no reason yet to believe trading has been affected, so this could be a buying opportunity.
Last week’s trading update from Cambria reported strong trading through to the end of June. Results for the year ending 31 August are expected to be in line with expectations. As the Stockopedia graphic below shows, these have risen steadily over the last year:

You could make a case for saying that car dealers are nearing the top of a cyclical market. I’ve questioned this myself. But I believe the post-referendum fall in Cambria’s shares has left them cheap enough to offset this risk, on just 9 times trailing earnings.
I’m also less concerned about cyclical risks than I am with housebuilders. Unlike houses, new cars are more affordable than ever. High levels of new car registrations should be creating a multi-year pipeline of high-margin servicing and warranty work for big dealers.
This is especially true for the many cars bought on personal contract plans, where monthly payments are calculated based on an expected final value. I stand to be corrected, but I’d expect that failure to maintain a main dealer history might result in a reduction in the contractual final value of a car.
I’m also encouraged to see that recent decline has caused Cambria to qualify for the Jim Slater Zulu Principle screen. This popular screen has generated an annualised return of 18.3% since its inception.
Cambria’s StockRank of 92 has also pushed it close to the top of my SIF screen, so I’ve decided to add this stock to the SIF portfolio.
Value where it matters
Regular readers may have noticed that I’m very partial to free cash flow. Indeed, if a stock’s price to free cash flow ratio is attractive, I’m not usually too bothered about the P/E. That’s certainly the case here.
Cambria boasts a trailing P/FCF ratio of 3.8. To be fair, this does seem to be an exceptional result. However, the group’s normalised free cash flow per share has risen by an average of 12.4% since 2010. This is only slightly behind Cambria’s normalised earnings per share growth of 14.7%.
The shares look good value on most metrics, as the ValueRank breakdown below shows:
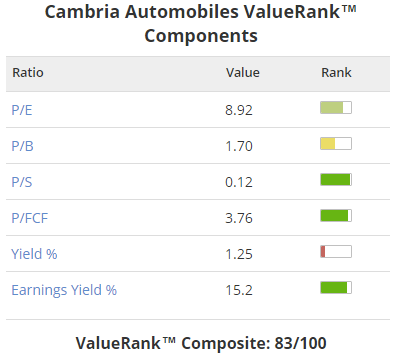
As with Total Produce last week, Cambria demonstrates that companies with low profit margins can still deliver a high earnings yield (EBIT/EV), if the valuation is right. Cambria’s earnings yield of 15% is a big attraction, in my view.
I’ve no concerns about Cambria’s value, other than the medium-term risk of a cyclical downturn.
Understated quality?
Cambria’s growth plan is to buy and turnaround underperforming dealers. The group’s management appears to be fairly adept and has generated a long-term average return on capital of 14.1%, while keeping net debt close to zero.
Cambria’s Piotroski F-Score of 6/9 seems relatively average. But as is often the case, the firm’s ‘fails’ are only marginal. For example, Cambria’s gross margin has fallen from 12.0% to 11.8% over the last year. That’s not a concern, but knocks one point off the stock’s F-Score.
The F-Score is heavily weighted in the QualityRank calculation. In my view, Cambria’s QualityRank of 70 may slightly understate the quality of this business.
Growth & Momentum
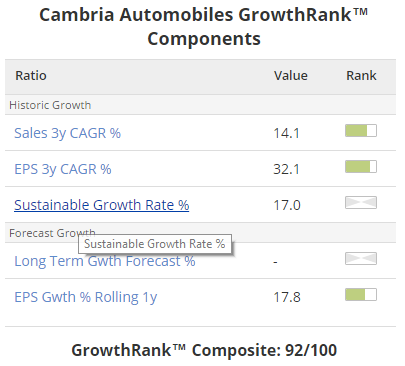
I don’t usually look at GrowthRank, as it isn’t one of the holy trinity of Quality, Value & Momentum which make up the StockRank. But since I’m classing Cambria as a growth pick, it seems to make sense to take a closer look at the stock’s growth credentials.
In this case the signs are positive. Cambria has a GrowthRank of 92, thanks to strong historic and forecast earnings growth:
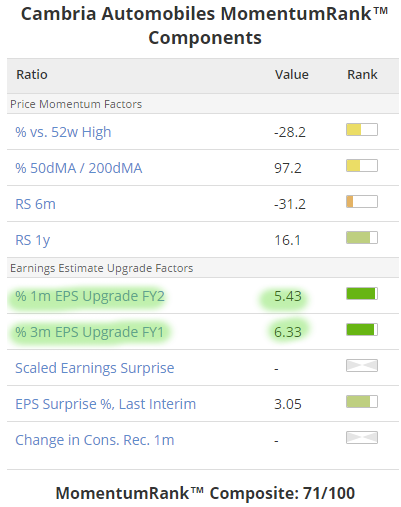
Moving over to momentum, the recent share price slide has made the picture more uncertain:
(You can access these breakdowns from the stock sector pages -- just click on the rank numbers.)
I believe the metrics that really matter in this situation are the earnings estimates. With Cambria trading on a 2016 forecast P/E of just 7.6, I’d expect any further earnings upgrades to lift the shares.
Indeed, the firm’s house broker has recently upgraded its forecasts for both this year and next year. I’m encouraged by this. While broker forecasts are certainly not infallible, not all growth stocks have such a confident outlook.
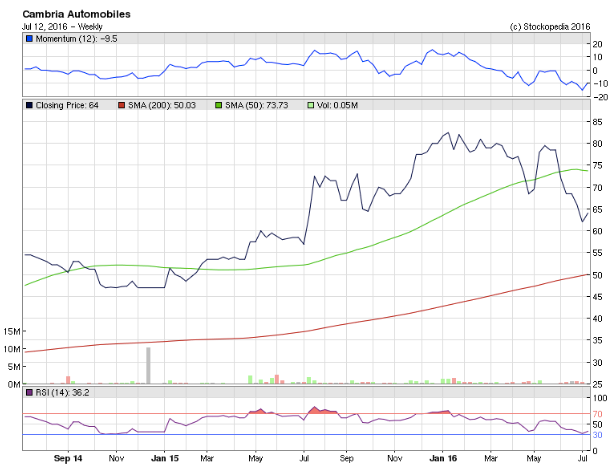
The chart for Cambria also looks encouraging in my opinion. If we zoom out to a two-year view, the recent slide appears no more than a blip in a steady upwards trend. The moving averages remain well separated and are trending higher. You could argue that the shares look oversold:
I’ll be adding Cambria to the SIF portfolio this week, but please remember that this isn’t a stock tip. It’s just my opinion. If you’re investing, then please DYOR.
I’d be very interested to hear your views on this stock and on the outlook for car dealers in general in the comments below.
Somero upgrades profit guidance
I won’t go into Somero’s latest update in detail, as Paul Scott covered it in his report on Tuesday. But in case you missed it, SIF portfolio stock Somero Enterprises said on Tuesday that full-year profits would be slightly ahead of expectations after a strong close to the first half.
Most of Somero’s profits come from North America, where Somero says activity was “particularly strong”. However, what’s perhaps more encouraging is that the group said that China, the Middle East and Europe also contributed to overall growth. Somero’s growth potential, in China in particular, is a key attraction of the stock for me.
The update appears to leave Somero trading on around 9.6 times earnings, or less if you strip out the firm’s net cash balance. The shares have risen by 10% since I added them to the portfolio and remain attractive, in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Had a holding for a while, good visibility of fwd earnings, and management appear to be a capable bunch, two of the criteria I look for
My issue with Cambria Automobiles (LON:CAMB) is the outsize remuneration of Mark Lavery, as a major shareholder himself he should imho bolster the pitiful yield and reduce boardroom pay as currently shareholders are poorly paid for putting capital at risk and he is vastly over paid by comparison.
Good company but wrong balance between exec pay and shareholder returns imho mr Lavery took out £805k in 2015 shareholders got £650k..that makes it uninvestable to me
Interesting analysis. I like the look of Cambria except for one thing - the very wide spread of 770bps. That makes it very difficult to make a profit unless it goes up over 70p again. You have to be very certain of a company to buy with that sort of spread - it has to increase by almost 8% just to break even.
The actual spread today is under 3%, the advertised spread is wider. My broker has Buy @64.9p Sell @63p
Although it does raise an interesting point, could you actually buy 76,000 shares in one go? Some of these small companies it hard to buy even a few 1,000, as I have found out.
Monions,
I agree that care needs to be taken when buying small caps with big spreads. But in the case of Cambria, the spread must have gone up today. My screen includes a test for a spread of no more than 400bps (4%), so Cambria wouldn't have qualified if it always had such a high spread.
Indeed, I've just checked and Cambria has disappeared from the screen today due to failing the spread requirement.
I've checked the two online brokers I use and both are quoting a spread of about 770bps today. But as Herbie suggests, I guess the actual spread on whether you wanted to buy or sell and how many other orders were in the market.
Regards,
Roland
Cambria Automobiles (LON:CAMB) has been my pick of the motor dealerships for a while.
In addition to the good earnings record it also has a strong balance sheet with a number of valuable property free holds and not too high a level of goodwill given their strategy of growth through acquisition.
Also good to see senior management has plenty of skin in the game (CEO Mark Lavery has 40% and NED/Burt family hold a further 4.3% and have been topping up following recent falls).
Last but not least, they don't appear to have any significant VW exposure so limited risk on recalls and impaired used car residuals.
Gus.
Thanks Roland
Hi Tony,
Thanks. In this case the choice between Cambria Automobiles (LON:CAMB) and Vertu Motors (LON:VTU) was simple. Cambria was the only one of the two which appeared in my screen, so was the only choice of stock to add to the portfolio.
My personal view is that there isn't very much to choose between these two car dealers. Both look fairly attractive to me and have similar valuations.
Cambria does appear have a history of higher returns on capital and equity and seems to have stronger earnings momentum. On the other hand, Vertu's scale could be an advantage in a weaker market. Vertu also looks cheaper relative to book value; this could provide more downside protection.
What's clear is that Stockopedia's algorithms favour Cambria, with a StockRank of 91 versus 61 for Vertu.
As always this is only my opinion, certainly not a recommendation.
Regards,
Roland
Hi Roland
Good article would be interested in how you compared them to Vertu Motors ? I hold a very small amount of both but no sure of the 2 which to top up and help would be most welcomed