SIF Portfolio: Why I'm shopping for Total Produce this week

It’s time to move on. I discussed the immediate impact of the UK’s Brexit vote on the SIF stocks last week, together with my view on the near-term outlook. This week I want to get back to building the portfolio.
I firmly believe in the adage that investment returns are a result of time in the market, not timing the market. The UK economic outlook may be more uncertain following our decision to leave the EU, but it’s by no means certain to be bad. In any case, UK-listed stocks provide exposure to a wide range of businesses whose fortunes don’t depend too heavily on the UK economy.
So I’ve got the bit between my teeth. I’m ready to spend some virtual cash. The only problem is that my SIF share screen has not yet recovered from the impact of the Brexit sell-off.
At the time of writing, just eight stocks qualify for the screen. Some of these, like Somero, Macfarlane and BAE are already in the portfolio. Others are unsuitable, mostly because they are cyclical and linked to the UK housing market. I already have enough exposure to this sector through Persimmon and Norcros. As I’ve discussed in recent weeks, my urgent need is for more defensive stocks.
To solve this problem, I’ve decided to loosen one of the screening criteria. I’m not going to change the financial performance requirements, just expand my screen to include dual-listed stocks. I originally used this criteria to filter out suspect overseas stocks, but I’m not sure it’s the best approach. Many of the dodgiest companies of recent years haven’t been dual listed. They’ve only been listed in the UK. I may abandon this criteria permanently and apply a human filter instead.
A focus on food
Food producers are considered defensive businesses. Demand for staples doesn’t tend to change much during recessions or booms.

Removing my restriction on dual-listed stocks means that Irish fresh produce distributor Total Produce now qualifies for my screen. This stock was suggested by a reader a few weeks ago. It’s also a company I’ve considered for my own portfolio over the years. Total Produce hadn’t previously shown up on my screen due to its dual Ireland/UK listing. But apart from this, it meets all of my criteria.
Although Total Produce’s profit margins are slim, it’s expanded successfully through organic growth and acquisitions. Management have not geared up or compromised the strength of the balance sheet to achieve this. While the shares aren’t the bargain they were back in 2012, they don’t seem overly expensive to me.
Total Produce also offers a certain amount of geographic diversity. Produce sold by the group is sourced all over the world and sold throughout Europe. The group’s revenue rose by 10.4% to €3.5bn last year. About 90% of this was generated in Europe, split roughly 50:50 between eurozone and non-eurozone areas.
The remaining 10% of Total’s revenue comes from small but fast-growing operations in North America and India. Sales in these potentially large markets rose by 68% last year. Further expansion is planned.
Happily, Stockopedia also likes Total Produce. The shares have a StockRank of 90 and qualify for three guru screens.
Strong cash generation
One of this stock’s big attractions for me is its strong cash generation. According to Stockopedia, the shares currently trade on a price/free cash flow ratio of just 9.7. Free cash flow last year was €0.13 per share, slightly higher than normalised earnings of €0.11 per share.
Stockopedia’s free cash flow figures are normalised and often exclude some acquisition-related costs. That’s generally fine, as these are usually exceptional and quite lumpy. However, Total Produce is planning further acquisitions. I think it’s useful to see how strong free cash flow was after all acquisition expenses.
In this case, the news is good. Including all acquisition and deferred consideration payments from last year, I calculate free cash flow at €0.091 per share. That equates to a P/FCF ratio of 15.5 and is enough to cover last year’s €0.028 per share dividend three times.
The dividend yield is only 1.9%, but average annual growth since 2010 has been 9.2%. Given the strong cash cover and ongoing dividend growth, I can live with this low yield:
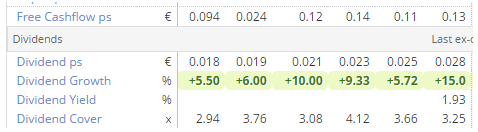
Dividends have been consistently covered by free cash flow and by earnings.
Quality
Operating margins have averaged about 1.8% at Total Produce over the last six years. This isn’t a figure the group brags about in its results and it has worried me in the past. But I don’t think this low margin is as risky as it might appear.
From an operational perspective, the group deals with lots of buyers and sellers. This should mean that the risk of one bad deal causing a significant shortfall in profit is limited. The company’s scale should also help to protect its interests when negotiating new contracts.
Financially, the risk of low margins is offset by a strong balance sheet and a modest valuation. Total Produce trades on a price/sales ratio of 0.15 and had net debt of just €18.1m at the end of last year. A modest valuation and low gearing mean that earnings yield (operating profit/enterprise value) is just over 10%.
This is a good example of why I think earnings yield is very useful. It neutralises the effect of debt and shows how much profit a business is generating relative to its overall valuation. You can then see whether the yield on offer looks attractive.
The stock’s QualityRank is pushed down to 58 by a Piotroski F-Score of 6/9. Although this sounds quite average, the three fails are all fairly marginal and aren’t a cause for concern in my view.
Earnings upgrades
Total Produce’s last market update was a trading statement in May. The company said the first four months of the year had been strong. Full-year earnings guidance was nudged higher.
Total Produce has a MomentumRank of 91. Broker forecasts suggest a consistently improving outlook for the stock. Earnings per share forecasts have risen by 10% over the last year:
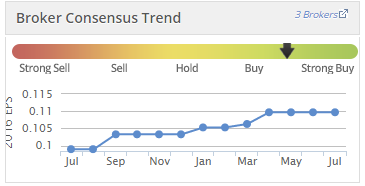
The three brokers covering the stock have an average price target of €1.78, or about 150p. That’s around 25% higher than the current share price. This seems reasonable to me, given the consistent growth of recent years. Although earnings growth is expected to be fairly flat next year, recent history suggests there’s a reasonable chance of further outperformance.
The technical picture also appears positive, with momentum and relative strength recovering after the recent dip:
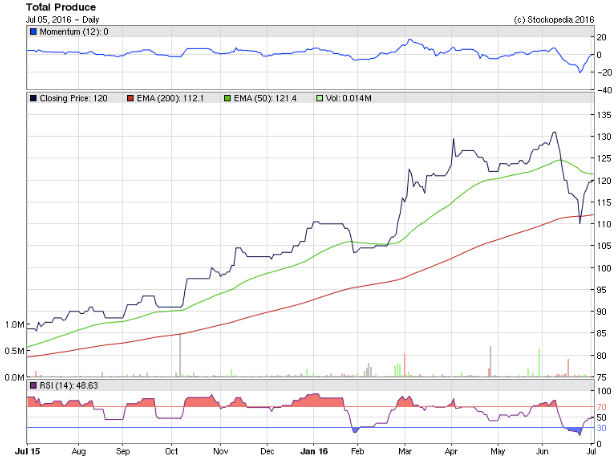
I think that the growth potential and defensive nature of this business should provide useful diversity, so I’m adding it to the SIF portfolio.
Roland owns shares of BAE Systems.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
I'm interested in your view of the low operating margin. Do you think a low margin can be a barrier to entry as it makes the market unattractive to new entrants who have to spend capital and develop the expertise needed to make money in a low margin business?
Compared with high margin business which is attractive to new entrants and invites competition.
If this really worked though I would expect to see a decent return on equity based on efficient use of capital though, whereas the ROE for Total Produce does not look that high and is partly dependent on carrying debt.
Hot Socks,
Thanks for your comment. You could be right. To make a low margin business like Total Produce (LON:TOT) work sustainably needs a lot of scale and efficient management. The main route to above-average growth is through the consolidation of smaller companies, something Total Produce appears to be doing quite well but which also requires good management.
This doesn't look to me like an industry that will readily attract a lot of competitors.
The company's return on equity (ROE) has been consistently in the low-mid teens for a number of years. That seems pretty reasonable to me. Debt is pretty low and has fallen over the last six years.I'm not concerned by this level of leverage.
Regards,
Roland
Roland
I'm heartened that you have examined and subsequently bought Total Produce (LON:TOT), you have added to my own conviction for this investment. Agreeing with the points you have made in your analysis, a factor which prompted me to add to my existing holding is the market spread of £TOTs operations and thus, hopefully over time, some protection against currency issues.
From what I understand it operates in 12 segments in the Europe-Eurozone, 6 segments in the Europe-non-Eurozone, and in an International aggregation segment of five segments within North America and India. I felt in these turbulent times this spread across currencies might offer some extra level of stability to their earnings over time.
I look forward to your next pick write-up.
Regards
Howard