Stock in Focus portfolio: double dipping with GlaxoSmithKline and Somero Enterprises

It’s too soon to say how the Stock in Focus portfolio will perform, but one thing that’s clear at the moment is that the stocks which qualify for my screen are disproportionately weighted in a few sectors.
As I write, 16 of the 20 shares which qualify for my screen are either consumer cyclicals or industrials. There are also two financial stocks, one of which is actually a housebuilder. Finally there’s one basic materials stock (last week’s pick, Pan African Resources) plus one healthcare share.
Luckily, the industrial and consumer cyclical sectors contain a fair variety of sub-sectors, many of which are not obviously correlated. For example both recruitment firms and bus operators are listed within the industrial category. Despite this, it’s clear that I will have to choose stocks carefully if I’m to avoid creating a portfolio that’s a direct proxy for the UK housing market!
An ultra-defensive pick?
My stock screen doesn’t use StockRanks for screening, but the results are ordered by StockRank. The idea is that I’ll add the next highest-ranked stock that meets my diversification criteria. For the final time I’m going to add two new stocks this week.
The first of these is GlaxoSmithKline, a stock I looked at in detail back in February. This article attracted a record number of detailed and perceptive comments, so it’s probably worth taking a look if you missed it the first time round.
As I explained then, in the five years since 2011, Glaxo has provided a dividend return of nearly 40%, plus capital gains. That compares favourably to many big caps, and certainly to the index. In my view, Glaxo’s asset swap deal with Novartis and its improved financial condition have left it well positioned for a new phase of growth.
Although Glaxo’s StockRank of 79 puts it relatively low down my list of potential buys, it is a genuine defensive stock. I believe this pharma giant should add useful income and diversity to the portfolio, along with decent long-term growth potential.
Smooth operator could beat expectations
My second choice is also a company I’ve written about in the past.
Somero Enterprises is the dominant player in the market for using laser-guided screeding machines to produce perfectly flat concrete floors for industrial buildings.
The firm last featured in this column in December, when I raised concerns about the cyclical risks of investing at what might be a relatively late stage in the cycle. Ironically, I’m less concerned about this now than I was then.
There are several reasons for this. Firstly, I’m trying to break out of the classic value investing trap of buying too soon on the way down, and selling too soon on the way up. A second reason for my confidence in Somero is that the firm produced a stonking set of 2015 results along with very confident guidance for the year ahead:
“We see 2016 as an exciting year full of opportunity. We believe we are well positioned to capitalize on expected growth in our core US and other existing markets, extend our global footprint and grow revenues from new products. Most importantly, we look forward to delivering another year of superior results for our shareholders.”
I also gained confidence after reading the transcript of Small Cap Editor Paul Scott’s interview with Somero’s CEO and CFO, which took place in January. This really provides a lot more detail and colour on the firm’s competitive advantage and on how management sees the market opportunity in the US and overseas. It’s well worth a few minutes of your time (as of course is all of Paul’s small cap coverage).
A fine set of figures
Stockopedia continue to rank Somero highly, with a StockRank of 98. Last year’s figures have now been assimilated into the firm’s StockReport. Rather than analyse them from scratch, I’ve decided to compare them to the StockReport I used back in December. What’s changed?
Back in December, Somero traded on a rolling forecast P/E of 8.9. Although the shares have risen by 22% since then, rising earnings guidance means that today’s forecast P/E is almost unchanged at 9.3. Forecast yield is also unchanged, at 3.4%.
Somero’s earnings per share dipped in 2015, but it’s worth noting that operating profit rose strongly. The fall in net profit appears mainly to be the result of Somero spending around $4.2m on new building facilities. These are being funded out of free cash flow, which is currently very strong. Net cash doubled from $6m to $12.6m last year, despite this investment.
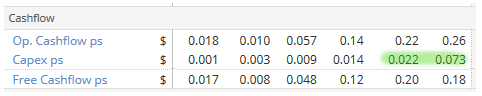
Last year’s rise in capex is nothing to worry about.
Somero’s ValueRank has fallen from 78 to 71 since I last looked at the firm, but I’m not concerned by this small change. The fundamentals remain solid and very appealing, in my view.
Solid quality
Somero’s QualityRank today is 96, a fall of just two points since December. Very little seems to have changed. The operating margin rose from 21.2% to 25.0% in 2015. Return on capital edged up from 42.5% to 44.7%.
Other metrics have also improved. As Somero’s 2009 results have dropped out of the QualityRank calculation period, Somero’s five-year average net margin has risen from 3.7% to 9.1%. The long-term average return on capital has risen from 0.4% to 17%. These numbers show the severity of Somero’s previous debt problems, and the strength of its recovery since then.
As management are keen to explain, a repeat of this calamity should be unlikely. The company’s policy is now to maintain a net cash buffer of $10m at all times, so that when the next recession does come, Somero will be able to ride out the storm in safety.
If you’re wondering why Somero’s QualityRank has fallen at all, I suspect the reason is that the stock’s Piotroski F-Score has fallen from 8 to 7. The reason for this is that last year’s lower post-tax profits resulted in a lower return on assets last year. This is simply the result of the money being spent on new buildings and is absolutely not a concern, in my view.
Big momentum gains
Perhaps the biggest difference between now and December is that Somero’s momentum has improved significantly. The stock’s MomentumRank has risen from 70 to 87.
Broker forecasts for 2016 earnings have risen and the outlook for 2017 suggests further progress is expected. Somero’s cash-backed dividend is also expected to rise and the forecast yield is 3.3% for 2016, rising to 3.6% for 2017. That’s quite high for a small cap.
Somero’s 2015 results made it clear that the firm should be able to deliver material ongoing growth from the US market. Growth elsewhere will be a bonus. In the case of China, it’s a long-term goal where the potential rewards are vast.
I’m happy to add the stock to the portfolio at this time, and look forward to the next trading update in the summer.
Roland owns shares of GlaxoSmithKline.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Having worked for one of the largest fund management firms I can say that not every decision is economically rational in its purest form. Often there are inflows / outflows from clients that mean the PM is forced to add or sell positions, especially if one holding is proving more liquid than another and the PM needs cash to cover a client redemption.
Also as Carcosa correctly states manager change can play a part. I read that small cap fund manager Lucy Marmion has just left BlackRock, maybe the other manager, Roland Arnold has another / differing view ?
There are also the "risk meetings" where the shares have risen in value and are becoming a large part of the portfolio. This is then highlighted by the "risk committee" and one is then encouraged to reduce the position. This decision is not based on pure economic fundamentals, rather on the principle of risk diversification.
So while you may feel it disconcerting that certain managers have been selling it isn't always true that they can see something we cant.
Thanks Vegpatch - interesting - hopefully in this particular case it is one of those examples where one of these things is happening and the little chaps have the advantage over the big firms!
Best regards
My views? I doubt whether my views carry any weight! Often a shareholder will rationalise either positive or negative share prices/news to justify his position. Frequently it seems to me that shareholders come up with a story that seem to fir the facts but in actual fact has little or no relevance to reality.
With the above in mind, my view is that institutional selling particularly of small caps, is not necessarily directly related to the fundamentals of a company. Their reasons can amount to a different manager viewing a company, or more likely a sector differently than his predecessor and positioning himself accordingly. Alternatively some institutions, see themselves as a niche player below/above a certain market cap valuation. So there are reasons that institutional selling/buying is done which may appear totally at odds with how retail investors see the story.
What sometime occurs is that when an institutional is selling shares it puts a cap on what may otherwise be an increasing share price. That appears to be what is happening with Somero. Institutions are selling in an orderly way (rather than dumping shares willy-nilly). The advantage for us retail holders is that it affords us an opportunity to accumulate shares in Somero over an extended period of time despite what is ostensibly a share price that should be climbing week on week. As a consequence I have added to my position.
But there again, I am a shareholder so more likely to rationalise consistent institutional selling to my 'advantage'.
Thanks. Yes, the rationalization process you mention is the reason I was asking, I worry that I am over optimistic on Somero. Well, results on 6th September I hear, almost certain to be at least decent, I wonder whether we might see any change in valuation at that point. Best of luck and thanks again for taking the time to reply.
I was reviewing this years Institutional share sales for Somero Enterprises Inc (LON:SOM) and thought I would share the data here
Ennismore may have completely sold out by now.
Artemis still have ~14.97% holding but seem to be selling ~550,000 shares a month
Blackrock maintain ~ 6.95% but seem to be selling also.
The last institutional buy was Close Asset Management who got 5.27% back in January.
At least the selling appears to be orderly!
Hello Carcosa,
Thanks for posting that, very interesting to see and exposes my naivety on the share because I had no idea of the scale! As a holder, I don't know whether to be worried about the loss of faith the institutions have in Somero, or pleased to have an explanation as to why the share price hasn't risen further. What I would like to ask you is what are your views on this?
Best regards,
Dear Roland
I am going to look at Somero. Thank you for you interesting views above.
Questions:
1) What do you make of the fact that it is a US focused company listed on AIM? Its been there a long time but it feels like an odd situation. I know many other companies do too but in mind it is easier to understand why, say, a resource stock list in UK than this predominantly US domestic revenue stock.
2) What do you estimate will occur during a normal US recession to revenue and earnings. Is the stock priced to weather this now?
Best wishes
Paul
Lavinit, you may be interested in this article, largely about Somero Enterprises Inc (LON:SOM), from Investors Chronicle on July 11:
"Exploiting a pricing anomaly
Another company set to benefit in a major way from the transactional impact on currency movements since the EU referendum is Aim-traded Somero Enterprises (SOM:160p), a Florida-headquartered company that specialises in the design, assembly, and sale of patented, laser-guided concrete levelling equipment for commercial floors. I initiated coverage on Somero's shares at 140p ('On solid foundations', 22 Apr 2015), and reiterated that advice at the current price after the company posted a trading update at the annual meeting that was "comfortably in line with expectations". ('Somero on track for a solid year of growth', 7 Jun 2016.)
The key to the ongoing positive momentum in the business lies in the North American market, which accounts for 70 per cent of Somero's annual sales. In particular, demand from non-residential building construction continues to benefit from customer demand for replacement machines, fleet additions, and product upgrades, too. New product introductions, price increases and a shortage of skilled labour in the concrete contractor industry are all contributing to strong sales in the region, factors that are also driving up margins.
To put this into some perspective, analyst David Buxton at broker finnCap forecasts a rise in full-year revenue from $70.2m (£54.2m) to $75.1m this year to boost pre-tax profit from $17.6m to $18.9m. He notes that the trading update provides "additional confidence to forecasts and augers well for a positive second half". This follows a strong operational performance in the final quarter of 2015, during which time sales hit an all-time high in December. Furthermore, the company reported upbeat news from its European and Chinese markets, both of which account for 8 per cent of revenue.
So not only are segments that represent 85 per cent of annual sales firing, but Somero has lengthy project backlogs for customers in the non-residential construction market that extend well into 2016. Moreover, the impact of the14 per cent fall in sterling against the US dollar, and 12 per cent fall against the euro since my last update ('Somero on track for a solid year of growth', 7 Jun 2016) is to increase EPS estimates from 14.5p to 16.5p for the current financial year. This means that Somero's shares are priced on a modest 9.5 times forward earnings. And even if the shares hit my fair value target of 185p, they would only be trading on the equivalent of 10 times cash-adjusted earnings for 2016, hardly a punchy rating.
That's because, buoyed by robust cash generation, net funds almost doubled to $12.6m in 2015, a sum now worth 17.5p a share, so on a cash-adjusted basis the current forward PE ratio is actually only 8.6. Sterling weakness is also great news for the sterling dividend because analysts at brokerage finnCap predict a rise in the payout per share from 6.9¢ to 7.2¢, equivalent to 5.6p at current exchange rates. That's worth 12 per cent more in sterling terms than a month ago. On this basis, the shares now offer an attractive prospective dividend yield of 3.5 per cent.
According to my models, a fall in sterling to £1:US$1.20, as some currency strategists predicts, would add a further 1.3p a share to the current sterling EPS estimate of 16.5p. Personally I feel that if the Bank of England cut bank base rate and restart printing money, as many economists believe could happen as early as Thursday this week when the central bank's Monetary Policy Committee (MPC) next convenes, then with diminishing yield support sterling could easily fall below this level before finding a floor. According to my models, a fall in sterling to £1:US$1.20 would add a further 1.3p a share to the current sterling EPS estimate of 16.5p.
On a bid-offer spread of 155p to 160p, valuing the company's equity at £86m, and offering 16 per cent upside to my conservative fair value target of 185p, I rate Somero's shares a buy."
http://www.investorschronicle.co.uk/2016/07/11/comment/simon-thompson/profiting-from-sterling-s-plunge-n3PZ7zvVimuU6ZmbxSto9M/article.html?utm_source=http://www.investorschronicle.co.uk/2016/07/11/comment/simon-thompson/profiting-from-sterling-s-plunge-n3PZ7zvVimuU6ZmbxSto9M/article.html
Thank you
Dear Roland
I have had Somero & GSK for a while (for income) so always grateful when a ruler is over shares of interest to me. I suspect the issue with Somero is they were hammered in the recession and have been on a steady recovery since ( 5 year chart quite informative). I expect the pricing reflects past shocks and will continue to be a bit discounted as a result. Paul Scott's interviews and commentarys made a good enough case for me and I would not be surprised if this share broke out a bit but to be honest i will be pleased if it stays fairly steady as an income stock. Also, worth a look for comparison is Tex Holdings (TXH) with a stock rank of 98 which also seems fair value and has done well on divs recently.
Best
Will
Hi Roland
Good article. I seem to recall headline EPS at Somero Enterprises Inc (LON:SOM) in 2015 fell due to the tax charge. However, 2014 results from memory were flattered by a tax rebate, and if you adjust for this EPS increased for 2015.
As you say cash generation even after the capex incurred in 2015 and dividends paid was impressive.
Best wishes,
Imran.