Small Cap Value Report (10 Aug 2015) - NWT, FITB, TERN, GHT

Good morning!
A fairly short report today, mainly because there's not much in the way of news, but also because I have to drive over to my home town of Bournemouth for a family get-together this afternoon. Good thing it's not too hot, as the aircon on my elderly Jaguar doesn't work. Must check my AA membership is up-to-date too, before I set off!
Newmark Security (LON:NWT)
Share price: 4.0p (down 18% today)
No. shares: 460.2m
Market cap: £18.4m
Results y/e 30 Apr 2015 - the first thing that jumps out at me is the lateness of this company's reporting - to be reporting results three months, and ten days after the year end date is slack. Small companies should have tight control over their finances, and should be able to report within a few weeks of the year end. I would hesitate to invest in a company where reporting performance to the owners is treated as a low priority. There was no trading update at the year end date either, so shareholders have been in the dark since the interims were published on 30 Jan 2015. That's far too long a gap.
The results look good - turnover up 19.2% to £22.9m, and EPS on a comparable basis (before an impairment provision made last year) was up from 0.38p to 0.48p, an increase of 26%, and putting the shares on an attractive PER of 8.3.
So why have the shares sold off 18% today? Probably because of the cautious outlook statement, or profit warning, for the current year;
Overall, we believe that the profits of the Group in the current year will be lower than that for the year ended 30 April 2015 whilst we build up new markets and products from which the benefits will be seen in the following year and beyond. The Board remains optimistic about the future with various opportunities in the pipeline and accordingly has increased the proposed dividend for the year by one third.
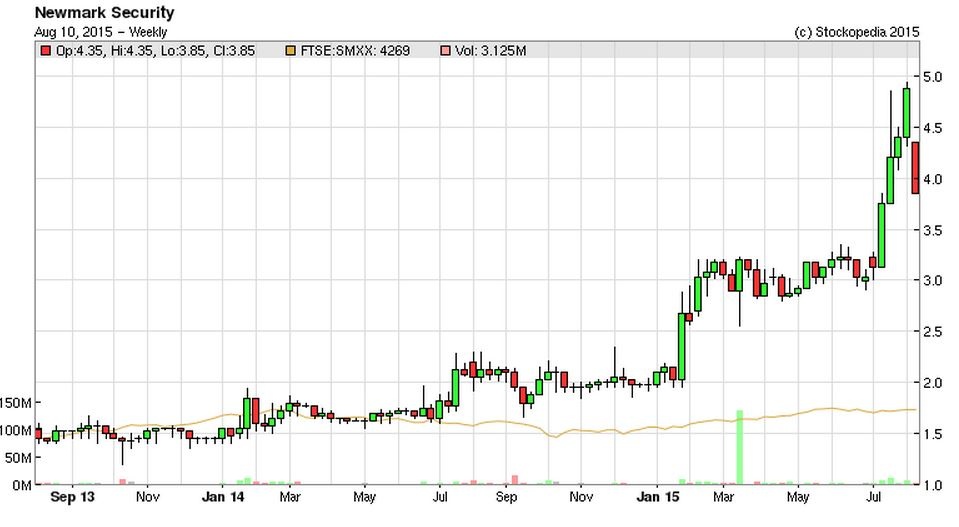
Many market participants want instant gratification, so will sell up and move on, if a company says that it expects to have a slow year. That's probably what's happening today. Well, that and the reality that the Newmark share price probably got ahead of itself (there's a lot of that about at the moment):
Placing - I note that substantial shareholders, the Reid family, Placed 65.6m shares at 2.6p per share in Mar 2015. This was just under half their holding, which reduced from 29.2% to 14.65%, so more-or-less a controlling shareholder at the time of the sale. Therefore they should have a decent idea of what the company is worth, and for them it was 2.6p.
The usual nonsense was trotted out about this sale being "to help satisfy institutional demand". No it wasn't! The sale happened because the owners of the shares wanted to (or had to) sell them, as is always the case. Satisfying institutional demand is a by-product of a major holder wanting to sell.
Anyway, my main point is that when a major, long-standing shareholder dumps half their stock at a particular price, that's usually a fairly good indication that the stock is fully valued at that level (in this case 2.6p). Although it depends on the circumstances. This sale appears to have been connected with the estate of one or more family members, so there's not really any control over price when an estate is being liquidated.
An indication was given in the announcement that the family are not inclined to sell any more shares for the time being.
Lumpy contracts - mention is made of a contract with the Post Office which benefited 2014/15 profits. Likewise there was apparently a contract with a bank, and various other positive factors which are not likely to recur. Hence the anticipated fall in profit for 2015/16.
This raises the question over how appropriate the PER is to value the company? If profits are lumpy, as they are for a project-based company like this, then maybe it's best to take an average of say five years' profits? Was last year a one-off good year, or will more big contracts flow through in due course? I have no idea, so it's very difficult to value. If in doubt, I tend to err on the side of caution.
We can see from the chart above that, after a couple of poor years in 2012 and 2013, the market only valued these shares at around 1.5p, so there's substantial downside if the next couple of years are also lean.
On the upside, the narrative mentions "various opportunities in the pipeline", including a new workforce management terminal for a "major US channel partner" which starts in May 2016. A new office was opened in Hong Kong recently, to drive sales in Asia.
Balance sheet - a thumbs up from me here. Writing off the £8.7m intangibles brings net assets down from £13.6m to £4.9m, which looks perfectly adequate for the size of company.
Working capital looks healthy, with the current ratio at a strong 2.07.
Net cash was £3.9m at 30 Apr 2015, indeed the cashflow was particularly good, with debtors reducing nicely from £4.1m last year to £3.1m this time. Although debtors actually looks unusually low, considering turnover for the year was £22.9m, so I suspect this might be a bit of a one-off having such low debtors this time around - hence net cash could be unusually high in these results perhaps?
It's a nice healthy balance sheet anyway.
Dividends - Newmark only pays a final divi each year, and this has risen by a third to 0.1p. That looks a bit tight to me, considering the strong balance sheet, and give a yield of an unremarkable 2.5%. Bear in mind that the bid/offer spread for a company this small could be more than that, so when you buy the shares you're effectively throwing away your first year's dividend (and possibly more) in the market spread.
My opinion - small companies with lumpy profits should be cheap - so the right sort of price for this kind of company, in my view, is a PER of about 6-7 times average profits. Anything more than that, and your risk:reward starts to go wrong, as if you over-pay when they've had a good year, then you might end up nursing a hefty loss when the tide goes out again.
The opportunity with this type of company is to find one with really top notch management, who are introducing new products that will transform the company's performance over time. It doesn't sound as if that is on the cards here for the time being anyway, but in the longer term, who knows?
Note that whilst the StockRank is 96 at the moment, I think we can anticipate that this is likely to fall - given that the company has effectively warned on profits for 2015/16 today, then broker estimates will soon reduce. Also, share price momentum has conked out for now. Therefore I think caution is needed using StockRanks where a recent results or trading update has not yet fed through into the calculations.
Speculative shares & Balance Sheets
Fitbug Holdings (LON:FITB)
I see the bubble has well and truly burst at Fitbug Holdings (LON:FITB) . I reported on this micro cap in Oct 2014, when I pointed out that the company was insolvent, and was being propped up by loans, therefore it was a racing certainty that it would do a Placing.
Sure enough, two months later, it raised £3.5m at 9p per share, where I commented at the time that the people buying at that price were mugs.
It's raising money again today at 2.5p per share. Dear oh dear.
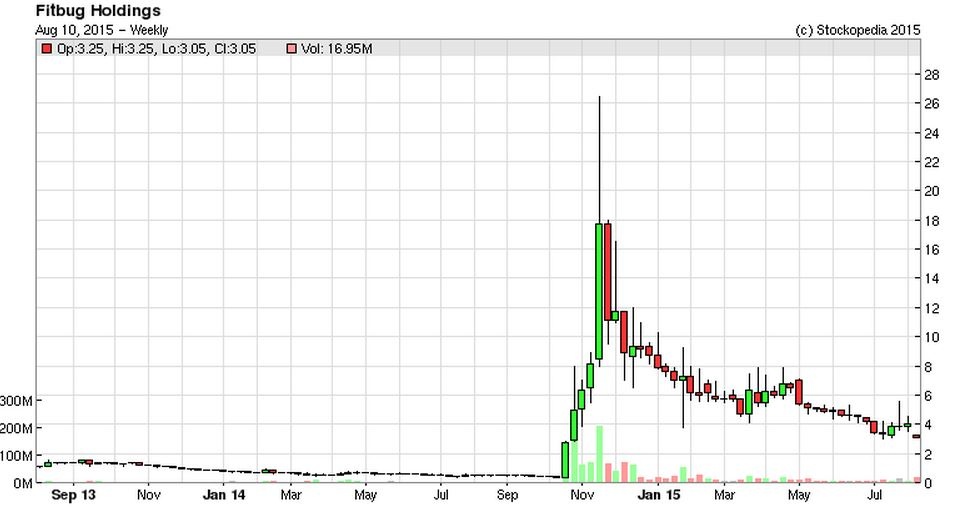
(YES, THIS IS A REAL CHART!)
If people must gamble on wildly speculative stocks like this, then I cannot stress enough the importance of the balance sheet. Fitbug had an obviously insolvent balance sheet, so anyone buying the shares was being reckless in the extreme - but occasionally that works, for a quick in & out.
It's simple enough to work out the rate of cash burn, and how much cash is in the bank. If there is less than a year's worth of cash remaining, then another fundraising is almost certain. So you're going to be diluted, and possibly on crushingly unfavourable terms, if you continue to hold such a speculative stock after it has zoomed up strongly on some contract win news.
Loans - note from today's update that substantial shareholder loans are still outstanding, but the terms have been relaxed. These loans are now quasi-equity in my view, since the company clearly cannot repay them, so it's only a matter of time before these are converted into equity, meaning more dilution.
Trading - encouraging noises are made today about a £265k replenishment order from Sainsburys, and that Argos are including Fitbug Orb and Kiqplan in their 2015 A/W catalogue, plus other customers trialing the products. So it doesn't sound a complete basket case.
My opinion - there might be something here, but the balance sheet is so appalling that it can't be taken seriously as an investment until the full dilution has occurred from the shareholder loans being converted into equity.
Well done to anyone who gambled on it early on, and managed to buy at the bottom and sell at the top, but I bet there aren't many people who actually did that!
Tern (LON:TERN)
Placing - this is another highly speculative share with nothing much on the balance sheet, which I've been highly critical of recently. Surprise, surprise, it's raising more money at a discount, just like Fitbug (although Tern's Bal Sheet is largely empty, rather than insolvent like Fitbug's).
It's raised just £720k (before expenses, which will probably take out a big chunk) today - issuing 6m new shares at 12p each - about half the peak of the recent spike up.
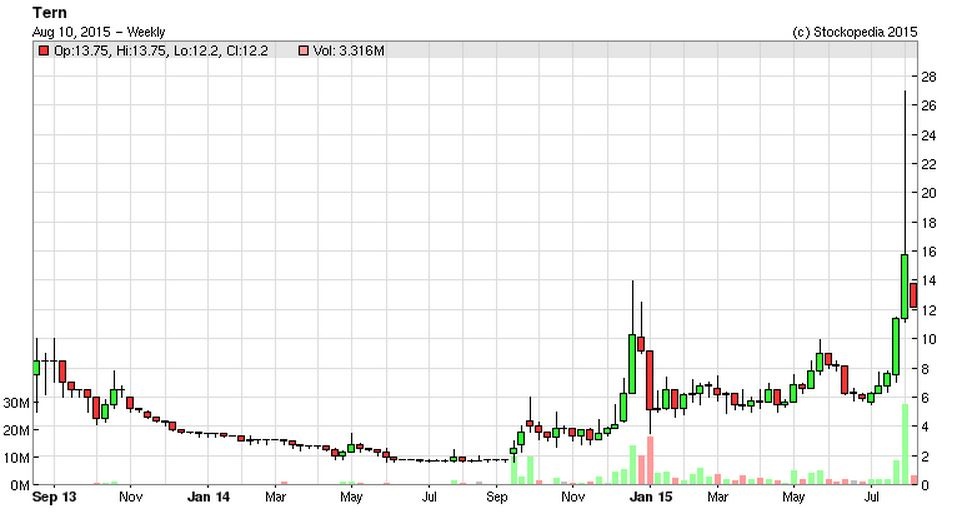
However, note also that 3m more new shares are being issued at just 1.25p each, to convert £37.5k of Convertible Unsecured Loanstock. So it looks to me as if the two individuals concerned are likely to be selling in the market asap (if they've got any sense!), to lock in the profit from the 12p current market price, and the 1.5p they paid for their 3m new shares. Trading in the new shares commences on 17 Aug 2015, but there's nothing to stop people advance selling by opening up a short position on a CFD or spread bet.
My opinion - I remain of the view that there's nothing of any significance here to justify a share price of more than a penny or two.
Overall, shares like FITB and TERN are gamblers' shares. However, if the balance sheet is poor, then Placings will quickly snuff out any speculative gains that people make - which is why the big spikes up quickly evaporate. So in my view, the onus is to grab the money & run, if one finds oneself having unwisely bought something like this, but getting lucky in catching a big (and usually spurious) move up.
Gresham Computing (LON:GHT)
Interim results - for the six months to 30 Jun 2015.
I've had the quickest glance at this company's results, and as usual, I cannot fathom why the market cap is so high (£62.6m at 99p per share). It only made a £647k profit before tax for the half year, up £50k against H1 last year.
Also, note from the cashflow statement that it capitalised £1.4m in development spend in the half year, versus total depreciation & amortisation charges of £392k. So in cash terms, it's actually loss-making.
The market must presumably have high hopes for growth from the CTC product, which is much trumpeted in the narrative.
My opinion - based on the historic figures, the valuation looks a bit bonkers. However, investing is all about the future, so some investors must believe that this company has good prospects.
Right, gotta dash, see you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions.
A fund management company with which Paul is associated may hold positions in companies mentioned.
NB. These reports are just Paul's personal opinions only).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
cig.
Take a look at the Avacta website and you will find a number of video articles on Affimers. You will also see that Moderna Theraputics Inc has also paid $500.000 for exclusive rights to Affimers produced on their behalf and payments when Moderna produces its own Affimers under license. Quote "Moderna will be paying Avacta many tens of millions of dollars".
Camkids (Lon: CAMK) I am surprised Stockopedia gives 99 Value 67 Quality 4 Momentum 57 Ranking.
Could you comment Paul. I agree with everything you say but am puzzled by the rankings.
Thanks for your comments all. However, I do feel that if there is an existing $60bn market for a product and you have a replacement that is proven to knock the existing product into a cocked hat in every respect, I tend to feel a little more optimistic than you appear to be. Nice surprise in 5 years though Cisk!
Do you have a non-company source for the addressable market and "proven" qualities? The entire pharma industry turns over about 1 trillion I think, so this thing, which seems rather specialised, is ~5% of total industry spend?
More generally, this sort of share tends to be priced by the marginal gambler who's happy to pay two or three quid for a 1 in 10 chance of making a tenner...
It would appear the NWT scenario I outlined above is some way off the eps f/c published by Edison yesterday at 2016 e0.27p & 2017 e0.44p.
rumplestiltskin -
re. Avacta (LON:AVCT). Wan is our resident expert who does a splendid job in keeping us posted of all relevant news and analysis.
I have held a small holding in my blue-sky portfolio since the start of the year, but I am under no illusion that all gains could evaporate quicker than summer snow. Definitely a punt, but one that has the potential of being a multi-bagger.
I treat my holding like a lottery ticket, but perhaps with slightly better than the 14m -1 odds!
Regards, Ram
Paul,
If you haven't seen it yet, read the CAMKIDS RNS from today. It's a hoot.
http://www.investegate.co.uk/camkids-group-plc--ca...
Hi Stegrego,
Yes, unfortunately I had turned off my computer & was about to set off for Bou'mth when I read the Camkids (LON:CAMK) announcement. I was almost crying with laughter at its absurdity!
I am limbering up to doing a hatchet job on it in the morning's SCVR!
Regards, Paul.
Hi Paul,
while we are down in the micro caps, I would be interested to know what you think of Avacta (AVCT).
I have been following this company since 2009 and have now invested heavily in it because I am confident that it is about to become a very profitable company. You may even fancy a flutter yourself.
rumplestiltskin,
There is a long-established thread for Avacta (LON:AVCT) here:
http://www.stockopedia.com/content/avacta-exciting-potential-under-the-radar-80614/
Wan has been adding very useful & valued insights into the background and industry within which Avacta (LON:AVCT) operates.
Avacta (LON:AVCT) is a jam tomorrow company, currently loss making, but potentially on the verge of cracking into a multi-billion market. Of course, if this happens, the shares will respond accordingly, but it's high risk (as I'm sure you're aware) so it doesn't really stack up as a GARP share in my view.
I've held a position for quite some time but it's definitely a bottom drawer stock to tuck away and revisit in 5 years.
Above refers to Newmark Secuirity .....that time of day..aplgs.
The share price movement can be volatile for such a share...ie 47.59 % owned by insiders at last details posted. To interest the institutions it is logical for the company to reduce the amount of insider share ownership. Understand Gervais Williams ( Miton ) owns some 8.5% of the company. Edison research note today is positive... hiatus in 2015 growth due to investment required for 2016 for new product areas and temporary contract dip. Time horizon important when investing...for longer term IMO think reaction today overdone.
I see CAMK tanking today! Thank you Paul, I got out a long time ago based on your research and reservations. Phew!
Ta for the response Paul. They have telegraphed earnings decline due to their large Post Office contract coming to an end plus up front costs building out the teams for Asia and US. I understand they are too small for your preferred hunting ground but mkt cap aside they might be worth a look as they are at a very interesting point should they be able to pull off their expansion plans. Am having to sit on my hands today as I watch profits disappear in the short term but personally think this is a feasible scenario: 0.7-0.9p eps over next 2-3 years with an expansion of PE to >15. As ever time will tell, dyor etc.
Newmark and Indigovision should merge as their IP products are complementary.
Re NWT: Is it a profit warning if there are no forecasts for 2016? Not pedantry just wondering to myself about rhetoric. As ever keep up the good work.
Hi Fugwit,
Interesting point. I suppose in the absence of broker forecasts, then most investors would probably have a presumption that next year's profits will be the same, or more than the previous year.
So a company saying that next year's profits will be less, would constitute a profit warning. Although it really depends on what previous guidance (if any) the company had given.
I've not looked back at whether Newmark Security (LON:NWT) had previously indicated that 2015/16 would be a softer year.
I was hesitant about using the term profit warning in this case though, so it's a fair point you raise. Probably would have been best to just describe it as a disappointing outlook.
Regards, Paul.
Hi Paul, I was fortunate enough to buy into this company at 1.65p. So with the 33% increase in the dividend it now yields over 6%, and I expect further dividend rises over the next few years. The SP has basically doubled in the past few months, (before today's correction). I'm not sure I will buy more, but very happy to hold the ones I have. Have a safe trip later.
Hi harry34,
It's always nice when we're sitting on a profit, but the key question is surely - would you buy it now, at the current price? If not, then why are you happy to hold? The market doesn't know, or care, what we paid for our shares after all! It's all about what happens from this point on, not what's happened in the past. I think sitting on a big profit can make me too docile about holding a share, so I really question my own reasons for continuing to hold, with every position in my portfolio.
I've not looked into Newmark Security (LON:NWT) in any great depth, so am not sure what the company's prospects are like.
Regards, Paul.