Small Cap Value Report (10 May 2017) - GAW, VTU, MBH, W7L, Wargamers apology

Good morning, Paul here.
Please note that I added a section on Treatt (LON:TET) (in which I hold a long position) interim results to yesterday's report, which is here.
Apology to Wargamers
Something really strange has happened on Twitter over the last couple of days. My account started to be bombarded with pictures of happy people on their wedding days. Most of the pictures were very nice, but I had no idea why they were being sent to me.
Anyway, it turns out that someone decided to stir up a Twitter storm, by copying some daft, tongue-in-cheek comment that I'd made here (in Jan 2014) describing customers of Games Workshop (LON:GAW) as nerds who never get married!
Now obviously, readers of my blog would understand that I often throw a daft aside into my commentary, just to raise a smile and lighten the mood a little. Also, there was a bit of irony involved, as I've never got married myself! Poking fun at myself, and others, is what I do sometimes. However, in text form, the intention can sometimes be misunderstood by others. So I should have chosen my words more carefully - a good learning point for me.
Taken out of context though, and copied to Twitter into a group reinforcing situation, I can see how people would take umbrage. Therefore I think the decent thing is to apologise.
Apology - on reflection, my comment was ill-considered. It was only intended as a joke, and had no malice behind it whatsoever. However, given that a whole bunch of people on Twitter have decided to take offence, then I retract my comment, with my apologies, and will amend the original article to remove my daft comment once I've finished today's report.
As a general point, I think urging people to spam any Twitter account with which you disagree, is wrong. However, sending pictures of happy marriage scenes is actually quite a nice way to protest! It's better than the abuse that usually pertains on Twitter.
Oh apparently I further put my foot in it, by saying that my favourite comedy is the Big Bang Theory! lol. Just to clarify on that point, I think it was hilarious up to series 4, passable in series 5 & 6, and terrible ever since.
Anyway, if any wargamers want to stick around, you're very welcome here. You could learn a lot about successful small caps investing from me & the gang here! Your input on GAW would be very interesting too, next time I report on it.
Good. On to today's news.
Today I shall be reporting to you on the following;
Vertu Motors (LON:VTU) - results for y/e 28 Feb 2017 - car dealership group
W7L - results for y/e 31 Dec 2016 - recently floated make-up vendor
Michelmersh Brick Holdings (LON:MBH) - AGM trading update - brick manufacturer
Plus anything else of interest that crops up.
Vertu Motors (LON:VTU)
Share price: 48.25p (up 7.2% today)
No. shares: 397.3m
Market cap: £191.7m
Final results - year ended 28 Feb 2017.
This is a car dealership chain. Its website is here. It operates from over 120 sites nationwide, with multiple car brands.
There's a useful results video (8 mins) from the company, courtesy of BRR Media, here.
These numbers look good. The company had previously said that new car sales were down, but used car sales and aftersales (servicing, etc) up. A few key numbers;
Revenues up 16.5% to £2,823m - most of this increase has come from acquiring new sites. Within that figure, organic growth was 4.4%. That looks a good result, considering new car sales were down 6.4% on a LFL basis.
Used car sales were strong - up 7.1% on a LFL basis. It's interesting to how the link between new car sales and profitability, which the stock market usually assumes to be the case, actually isn't the case. Poor new car sales has been compensated for by increased used car, and aftersales, and margin improvements.
Outlook & current trading look surprisingly good. There's a lot of detail in this, and sounds encouraging to me;
In March and April 2017 ("the post year-end period") the Group has continued to trade strongly, with profits ahead of the prior year on a like-for-like and total basis. Margins strengthened and operating expenses on a like-for-like basis were reduced as the cost base was flexed for lower new vehicle sales volumes and cost efficiency programmes delivered.
Used cars continued to see like-for-like volume growth and margin improvement. Service also witnessed growing revenues and stable margins on a like-for-like basis.
The March plate change month saw a record number of new vehicle registrations in the UK according to the SMMT. The 4.4% growth in March new retail UK registrations was aided by an element of pull forward of demand due to increasing vehicle excise duty from 1 April 2017 and the timing of Easter. April, as anticipated, saw a decline in SMMT new retail registrations of 28.4%.
In the post year-end period SMMT new retail registrations declined by 3.5%. The Group saw significant growth in new retail vehicle profit contribution in the post year-end period despite a 9.7% decline in like-for-like new retail volumes. Pricing disciplines and cost control delivered higher margins and profits year on year in new vehicle sales.
The Board is also pleased to report an excellent contribution in the post year-end period from dealerships acquired in the previous financial year.
While the Board is aware of the wider reporting of the UK entering a more cautious consumer environment, trading in the post year-end period has been strong. The Board remains confident about the Group's prospects for the current financial year and in delivering further progress in enlarging the scale of the Group.
Balance sheet - looks alright to me. Although as with all car dealerships, there is a vast amount of working capital tied up - massive inventories, financed mainly with massive trade creditors - i.e. the money owed to the manufacturers & other suppliers.
In this case, NAV is £246.4m, which reduces to NTAV of £150.4m. Therefore about 78% of the market cap is supported with tangible net assets - a fairly secure position, in my view.
Potential problems - one of the reasons car dealers are cheap at the moment, is because of Brexit worries. Could this stifle the importation of cars from Europe? Personally I very much doubt it - why would the Germans allow the EU to cripple their export industries? (the UK apparently takes about 20% of the entire output of Germany's car companies). Although in reality, at this stage, nobody knows. So it's educated guesswork for investors to a certain extent.
The other potential issue is that of possible mis-selling of personal contract hire vehicles. We've seen how the banks were clobbered with mis-selling of PPI, which cost them billions. Could this be a risk for car dealers? I have no idea, but it's being discussed in the press as a possibility, so is bound to weigh on share prices somewhat.
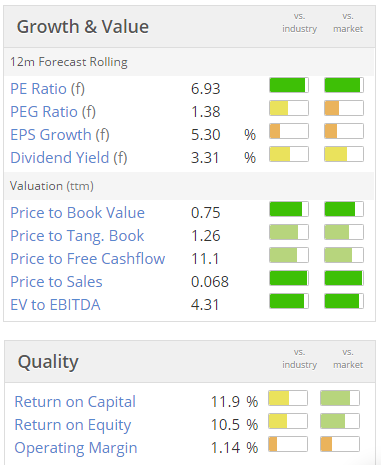
Valuation - as you can see from the Stockopedia graphics below, the share looks dirt cheap - on the most popular valuation metric of forward PER.
My opinion - I like it. It's not one I hold personally at the moment, as I'm focusing more on growth shares. That said, am really tempted to buy back in, as the valuation seems compelling.
It's not often you find a reasonably well financed company, paying divis, which has reported strong results & outlook, and is on a PER of around 6 or 7. There could be upside here, if the various downside worries sort themselves out in due course.
The StockRank is 82, so Stockopedia's computers rather like it too!
Michelmersh Brick Holdings (LON:MBH)
Share price: 68.7p (down 0.4% today)
No. shares: 81.5m
Market cap: £56.0m
AGM statement - this sounds a solid update;
"After a very satisfactory trading performance in 2016, I am pleased to report that the Group has performed well for the first four months of 2017. The Board expects the Group's trading performance for the twelve months to 31 December 2017 to be in line with market expectations.
I reviewed its 2016 results here, if you're interested.
Warpaint London (LON:W7L)
Share price: 224.5p (up 8.2% today)
No. shares: 64.5m
Market cap: £144.8m
Final results - for the year ended 31 Dec 2016. Very late published accounts - why so late?
This is a cosmetics company, including owning the W7 cosmetics brand.
It listed on AIM on 30 Nov 2016. So this is my first time here reporting on it. Although I do recall reviewing the prospectus last year at home, but don't have my notes to hand (if I made any). It looked quite interesting I thought at the time, but not enough to make me want to invest.
The highlights section today looks good, in particular my eye is drawn to the decent growth, and excellent operating profit margin;
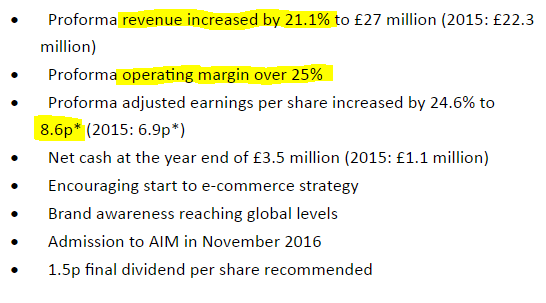
Stockopedia shows a broker consensus forecast of 7.9p, so the 8.6p reported today looks a decent beat.
The PER is 26.1- so it looks fully priced, maybe even a bit toppy? Although that depends entirely on what profit growth is likely in future.
Outlook comments sound alright;
Warpaint enjoyed many years of successful growth prior to joining AIM and we are confident that with increasing awareness of our brands we remain well placed to continue this expansion.
The Company remains at the forefront of developing on trend products for its ever discerning range of customers. Overseas business will continue to be a major driver as we aim to gain a larger share of the global colour cosmetics market.
With a flexible supplier base and a tight control of working capital the business remains inherently cash generative...
...The current year has started well and we look forward to updating shareholders on our progress.
Balance sheet - this looks strong.
There are hardly any fixed assets - so a capital light, highly profitable business - positive attributes.
Working capital is very strong, with a current ratio of 3.97 - therefore this is a well financed business, with no worries at all about solvency.
Also, it has no debt, with only £278k of long term liabilities - so insignificant.
It has £3.5m in cash, and no debt.
So a big thumbs up from me here - this is a solid, well-financed business.
Dividends - 1.5p final divi has been declared. Interim divis prior to the IPO need to be ignored, as circumstances were different then. So I'm not sure what the divi yield is likely to be going forwards - I'm sure broker notes will estimate this, but I haven't looked at any today, as this share doesn't really interest me particularly.
My opinion - these look good figures, but the share price reflects that, being on a fairly high rating.
I know nothing about cosmetics, so have no idea how sustainable the company's bumper profits would be. On the basis of strong figures today, and a sound balance sheet, this share might be worth a closer look. The sector doesn't interest me though, and I wouldn't know how to assess the business model.
Finding out what the target market thinks of the product is key. So a good excuse for readers to ask lots of ladies what they think of the W7 brand make-up, perhaps?
I tend not to trust recent IPOs. So for me, it's one I'll keep on the watch list, as well as asking my niece what she thinks of the W7 product.
That's it for today.
I'm pleased to report that the mobile phone repair shop has managed to fix my iPhone, after its encounter with a synthetic fibres (well, I do my clothes shopping mainly in Primark, so lots of polyester) 1400 rpm spin cycle over the weekend. So if your smartphone suffers a similar watery death, then my advice is to rush it to a decent mobile repair shop immediately, before it rusts, and they might be able to fix it.
You see - small cap shares analysis & views, wargaming controversy, and practical consumer advice - my reports here really are a one-stop-shop for everything you could wish for! ;-)
Kind Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Self-driving cars? You'll never get me in one, on the open road, or in town for that matter. Death traps. Or more like immobile objects, as teenagers walk in front of your self-driving car, laughing, as you're forced to make emergency stops, repeatedly.
Elon Musk & all his wide-eyed, cash-burning awe, won't make it through the next recession.
Personally, I can't wait for the lease to expire on my internet-enabled, totally incomprehensible Merc C200!
Then I'll go back to a proper car - one that doesn't even know what the internet is, and so can't be hacked. One where I can change the spark plugs myself!
PP.
Ed - That's interesting and gives me some food for thought. I suppose you can look at it two ways. One is to think brand recognition is low in their target market and that is bearish or you can think there is scope to improve brand recognition in future and therefore profits. Ultimately though, I will do what I always do and let the price action determine whether I buy more or even sell.
And on the theme of cosmetics, another company that is showing a lot of momentum and growth in Revenues and Profits is Innovaderma. I have shares in this one too and have averaged up recently as the price has shown a lot of momentum.
These are my notes on buying Warpaint a few months ago
Warpaint 158p. £100M.
BUY Has a PE of 17 and EV/EBITDA of 17 also. Hence, as you would expect, the net cash position is neutral. In fact it has slight net cash of £1.5M. Nice revenue growth CAGR but not much growth in profit historically though its forecast to grow EPS by 20% next 2 years. Nice operating margin of 25%. Very high ROE/ROCE (34% and 54%). Nice Operating CF ps. Capex is only 3.7% of OCFPS. So lots of FCFPS. P/FCF ratio is 26.2. A- Magic score. Earnings manipulation risk is high. Low gearing - looks like very strong balance sheet. Net cash. Good quick and current ratio. So a good company. Probably fairly valued but worth an investment. The intangible of course is how strong a competitive advantage do they have. The OM and high ROE would indicate quite a strong one. Most of the reviews of their products on Amazon and elsewhere are very positive. BUY.
The last bit is I think important. I looked at the reviews of their products on Amazon and the reviews are universally good. Am thinking of averaging up but I never like to do that too soon. Chart shows an exponential rise which can be a bad entry point thought its well supported on volume.
Sharesurfer - Warpaint keeps coming up on my screens. It's my daughter's 17th birthday today and she has some girlfriends over so I asked them if they knew about W7.
One asked if it was a London postcode, which of course it is, but that's probably not the answer that Warpaint investors would want to be hearing !
Another after a bit of prompting, and querying for context, suddenly clicked and said "oh yes they make colour palettes", further adding to one of her friends "they basically make clones of Naked palettes". (Naked is another cosmetic brand).
So at the lower end of their targeted 16-30 age group they seem to be lacking in brand awareness.
The numbers do look interesting though.
Hi Ed,
I always ask friends to ask what the target audience think of it.
Other mates of mine said their daughters were not impressed with W7 - poor quality, tacky, were the comments.
Bottom line, that doesn't matter in the long run, if the financial results keep soaring. However, I'm very, very suspicious of recent floats. A lot of companies seem to be buffed up for a float, then the figures go horribly wrong some time later, once profits have been banked by founders & advisers.
So I'll keep an open mind on Warpaint.
Regards, Paul.
Great post 1942. Year you were born?! I remember scoffing about ASOS when it launched-as I thought it was another Dotcom. You learn most from mistakes and missed opportunities. So I learnt my lesson and now a big holder of BOO from well below 30p. Another one springs to mind -think I bought some ARM in 2003 at around 70p-no doubt sold for a handsome profit. What a mug I was.
You may be right about W7 I just felt people preferred to shop for these products.
Hi Paul, I think you are missing a trick with W7L. which is targeting a similar female market to BOO and look how that has progressed.. I listen to my grand children and thus bought Keyword Studios some three years ago.. You don't necessarily have to understand the business , I don't either but get talking to teenagers and follow the trend
Every year a huge number of people reluctantly decide to give up driving because of slowing reaction times, faiing vision etc. These old folks will be the natural adopters of driverless vehicles, and with enthusiam, because it will prevent the closing in of their lives that otherwise comes with giving up the car. Bring it on!
Tick, tick, tick...
http://www.bbc.co.uk/news/busi...
Si,
one day my grandfather was driving home from work when a neighbour waved him down.
He pulled over to be told to be careful as she had seen a car drive through the village a few days earlier.
Si,
one day my grandfather was driving home from work when a neighbour waved him down. He pulled over to be told to be careful as she had seen a car drive through the village a few days earlier.Nice anecdote. I'll counter that with the fact that none of my grandparents ever learned to drive or owned a car.
Please don't paint me as some kind of luddite! I am not saying autonomous vehicles will never happen, only that the timescales being predicted are completely wrong. In the meantime many investors who believe the hype are going to lose money on rubbish blue sky stocks promising huge returns from technology related to this industry. As the great poet Chuck D once wrote "Don't believe the hype".
All the best, Si
I love the twitter attack of happy wedding pictures !!! Just goes to show what nice people gamers are, and that they can laugh at themselves a bit too ! Thanks for the lovely story, and good of you to apologise,
Of course the whole thing could have been resolved with a polite email, however this way was funnier, and so British !!!
As others have noted there are pleasures to be had from car ownership which people are prepared to pay for, prestige (for some cars), enjoyment of driving, sense of freedom, not having the previous passenger's mess in the car, etc. Even if using a shared self driving car saves you money not everyone will choose it for these reasons unless compelled to by government. Fine to take a short trip in a self driving shared car as an alternative to today's taxis but not as a substitute for all driving in my view.
Regarding the cost I can quite envisage the costs being much higher than predicted. Governments would feel the need to replace the vehicle licence fee, fuel duty, VAT on fuel duty, car insurance premium tax, etc with something else. Travelling on public transport these days can be really very expensive so I'm sure sitting in a self driving car will be even more so.
Heard an interesting piece on Radio 4 recently about 'mileage correction' companies prospering as more people take out PCP deals with low annual mileage clauses to get the cheapest offer. Anecdotal evidence suggests mileage is being 'corrected' to just below the annual limit each year to keep within the terms of the deal. So potentially if this is a widespread problem in three years when the car is sold on it could have significantly more miles on the clock than the odometer suggests. The impact on resale prices of used cars could be seriously impacted if this becomes a big enough issue. Remember that clocking is much harder after three years when the MOT is enforced and mileage is recorded and available for public scrutiny.
Self-driving vehicles will be a transition. Will start probably with goods vehicles going depot to depot, then maybe expanding into delivery, coaches, taxis. It will take a generation for them to take over, but take over they will.
Another data point: fewer people are taking driving tests, even as the population expands. Expect that trend to rapidly accelerate once autonomous vehicles are on the road, even if widespread availability is still years ahead.
As for self-driving cars, I think it's a ridiculous idea!
Many of us love driving, it's a pleasure. Almost like playing a video game. There's no way I would get into a self-driving car - forget it!
I think self-driving cars would just turn town centres into pedestrian zones. We would walk in front of them with complete impunity, knowing they would stop. We would laugh at the google & apple cars, jump on them, even turn them over! It would be chaos.
So nothing to worry about for now.
Regards. Paul.
Millennials are lazy ;) People used to like riding horses too.
Thanks Paul.
Hi Paul,if the price you pay for wit,satire and irony in your writing is the occasional apology to a group of sanctimonious,self important people suffering from humour by-pass syndrome so be it. Some people need to get a life! I am a Man Utd supporter from Dorset and if I had a pound for every time Ive been called a "plastic Manc" I would be living in Monte Carlo ..........as opposed to Monaco where I currently reside. There! wit! satire! and irony! from one of your readers.LOL. I await the opprobrium from the angry brigade.
Hi Cojode,
Shush! I've only just calmed it all down lol!
All a bit of a misunderstanding, and all sorted now.
As a general point, personally, I think if you can laugh off insults, then it's best.
I've absorbed, and in a strange way, quite enjoyed, tirades of abuse from numerous people. The best one from a troll that I had, was when he called me a "fat, short, salad-dodging, useless alcoholic". It brought the house down, and made him look a complete fool, when I replied with faux outrage at being called short! (well, it was funny at the time anyway)
Generally though, a smile & an apology is a good way to de-fuse most problems in life :-)
Best wishes, Paul.
Apart from his investing brilliance, it's Paul's wonderfully ego-free character that keeps me reading what he's got to say every day. So, kudos for attempting to make up with people after making a throwaway put-down. Being able to say sorry is cool, not a sign of weakness, in my book.
Interesting to talk about Tesla in the context of driverless vehicles. Reading the occasional FT article on Tesla they are quite fond of pointing that various alleged Tesla inconvenient truths such as: settlements appear to have been made with people who have crashed using some of the current Tesla software, and having been tied into strict Confidentiality agreements, so that not that much is heard about them.
Also, Tesla apparently using unaware drivers as live source of data on Beta releases of software, rather than extensive pre-testing, allegedly.
There is also the arcane financing structure of Tesla, which they also seem to query.
.
The comments so far tend to confirm my belief that private investors are more interested in wargames and cars than they are in bricks! However, I would note that MIchelmersh has seen a remarkable rise (for a brickmaker) in share price since March and I can't help wondering if there is more than the good financial performance involved here. I note that in the most recent results the joint founder/chairman says he is retiring from the board and that he "started [the company] as little more than a hobby for Martin and myself." He also retains a 28% stake according to the company's web site. I wonder if he might be interested in cashing in that stake now that he is stepping back from his hobby? If so, a sale of the company would be one possible route to take and I wonder if any of the recent share price rise is reflecting this?
Peterthegreat. Maybe you are right, but I think that £MBH's recent stock price performance is not out of line with either Ibstock (LON:IBST) or Forterra (LON:FORT).
There's only one main reason to be concerned short / medium term with low margin car retailers - availability of credit. There have been noises for a while now of PCP misselling. It is ludicrously easy to go and buy a stupidly expensive car for not much a month. If you couple this with potential interest rate rises against increasing inflation + stagnating wages, suddenly PCPs become significantly less attractive.
Paul,
As a wargamer (and very content shareholder of Games Workshop) I've seen a few times those in the hobby becoming quite articulate at politely spamming on Twitter, the PETA fur incident earlier this year brought out some truly great in-jokes, though I do agree it's not a practice to be condoned.
As an aside, the learning point you could take is that Games Workshop is maturing as a company, from an angst ridden adolescent prone to childish outbursts under Tom Kirby, into a producer of quality content through miniatures, through novels and computer games etc and so becoming a credible supplier of fun sci-fi for us middle aged Twitter savvy (and even married) folks to re-engage with. Credit to Kevin Rountree and the team for this.
I push models around a tabletop regularly with with a bunch of friends, all 30s-40s with great jobs, wives and families, it's just a fun way to blow off some steam after a long week at work. Notably, we all had some connection to the hobby in our teens, left it behind from university and throughout our 20's when girls and life happened, then after settling down acquiring mortgages and families we ended up dropping back in and catching the bug again. So long as the company keeps on pushing out stuff we like, we'll keep on buying it, hence why you won't get much change from £10/share these days.
Thank you for your regular thoughts, my own and my daughter's ISA's are much the healthier for your input - it really is appreciated.
Regards
Stuart
Paul, you ought not apologise to these supposedly "offended" idiots . If they are so dense that humour and irony escape them, then that's their problem.
Apologising only feeds the inane sense of self-satisfied (but false) empowerment the perpetually-ready-to-be-offended mob thrive on. You know, the "fury as.................." and the "outrage as................." mob, the "twitter meltdown as........." and the "twitter storm as........." mob.
They need to get a life and grow up to be adults.
Best wishes,
Jane.
Jane,
Yes I agree, but in this case I didn't want any of them to put a spell on me LOL!! ;-)
Regards, Paul.
I think the more imminent potential disrupter, is the arrival of the new "affordable" Tesla - no dealerships involved. When combined with a scrappage scheme for diesel vehicles and the lack of intellectual protection of its design its only a matter of time before ellectric cars are common place and as they have few moving parts and require little maintenance this will impact on a significant revenue stream for current dealerships.
I've held Vertu Motors (LON:VTU) for a couple of months now. New car sales are very low margin and dealers make more money from finance products and servicing associated with the sale. A couple of points from the very clearly written RNS:
The forecast is for new sales to fall but profit still to increase as high margin service add ons and financing increase. And yes I believe PCP is more of a risk than Brexit. The car manufacturers based in UK may suffer trying moving parts across borders, but companies will still supply completed cars to the UK market even if they're no longer built here.
Cheers
Glen
"New car sales are very low margin" and probably used car sales as well.
I have recently bought a (high end) used car and don't think the dealer made much on the sale itself - in fact they had the car in stock a while and probably broke even at best due to depreciation. However they did sell me a warranty and offered me financing, gap insurance and a protective coating on the paintwork, all of which I declined. These areas are where I think they make most money on a used car transaction.
No need to apologise so profusely to nerdy warmers. Many people take offence too easily nowadays. Different opinions are after all the strength of democracy. Please Paul just carry on. Your fun comments are essential to your blog.
Lennart
Nothing can top Gerald Ratner's light hearted joke about their products being "total crap". It cost him his job, the company quickly lost £122m of its market value and led to the closure of over 100 of its jewelry stores. I don't think they ever recovered.
Accountant - 'not married' ; obviously done a cost benefit analysis.
I think with PCP's they appear "cheap" because financing is cheap, and because manufacturers push for volume, with large volume bonuses.
Now, a potential problem may be that as more people "buy" a car this way, the used market will eventually have more 2/3 year old cars available, which impacts used values, and thus the PCP/finance costs will increase, as the monthly cost is based on the used value 2/3 years down the line.
But will 'more' people actually buy cars this way - financing is not always going to be cheap.
More to the point if used prices were suppressed then is really too much of an issue for the dealers? Sure they'll be getting their x% on a smaller number, but their cost of sales will move down in line - and potentially volumes will move up in that space.
My bigger general macro concern is that consumer spending slow down, hence I'm shying away from most "discretionary" retail. Not sure though if car dealers quite fall into this category; in fact if as Paul alludes the margins in 2nd hand are good a slowdown could create a shift to the benefit of the dealers?
Certainly going to have a good look at Vertu Motors (LON:VTU) - so thanks Paul for the heads up.
Another cloud hanging over car dealerships at present (and certainly the one that deters me from investing in any) is the potential disruption from the arrival of autonomous vehicles.
Although many projections have the transition to self-driving vehicles occurring over several decades, my own view is that this change is going to occur much faster than many analysts expect. I'm not the only one either - just a few days ago San Francisco think tank RethinkX released a new report:
"Rethinking Transportation 2020-2030: The Disruption of Transportation and the Collapse of the ICE Vehicle and Oil Industries."
Press release
From the bullet points on page 8 of the report:
"Demand for new vehicles will plummet: 70% fewer passenger cars and trucks will be manufactured each year. This could result in total disruption of the car value chain, with car dealers, maintenance and insurance companies suffering almost complete destruction."
Just one view amongst many of course, but certainly food for thought. And for anyone who believes I'm looking at the world through rose-tinted spectacles, it's worth watching some of the recent presentations on YouTube by those who are intimately familiar with the tech:
Johann Jungwirth, Chief Digital Officer, Volkswagen
Amnon Shashua - Co-founder, CTO and Chairman of Mobileye (bought for $15bn by Intel in March 2017)
Another cloud hanging over car dealerships at present (and certainly the one that deters me from investing in any) is the potential disruption from the arrival of autonomous vehicles.
Luthrin,
I guess your intended holding period for shares must be a lot longer than mine! This is sci-fi stuff and unlikely to happen in the next 10 years at least. You always hear these "technology evangelists" saying how an existing industry will be wiped out. Of course, they're talking their own book and they are always wrong.
I think the car dealers will have a lot more to worry about in the next 18 months than being put out of business by autonomous vehicles. Given the paper thin operating margins they "enjoy" it will not take a lot to tip them over the edge. New car sales have gone down, if Used sales decrease as well, it's goodnight Vienna...
All the best, Si
"This is sci-fi stuff and unlikely to happen in the next 10 years at least. You always hear these "technology evangelists" saying how an existing industry will be wiped out. Of course, they're talking their own book and they are always wrong."
You mean like they were with their forecasts for the impact of the Internet on society? Or of smartphones?
In any case, it's not just 'technology evangelists' who are now increasingly expecting this sea change, but the car execs themselves (evidence). I would also add that even if such a technological shift is unlikely to happen in the next 10 years, that doesn't mean to say that equity investors won't reprice businesses (and even start shorting them) based on market trends and future expectations.
To me it seems logical that if there's a reasonable possibility that the motor trade will be severely disrupted by a shift to autonomous vehicles over the next 15 years, car dealerships could be a value trap at present. Vertu Motors (LON:VTU) currently has a Stockopedia value rank of 96, Marshall Motor Holdings (LON:MMH) is 97, Cambria Automobiles (LON:CAMB) is 87, Pendragon (LON:PDG) is 95 etc. I'm sure I'm not the only one who is steering clear of these stocks for the reason I've cited (pun intended).
"You mean like they were with their forecasts for the impact of the Internet on society? Or of smartphones?"
I'm sure Si can answer for himself, but for my part I would say absolutely yes.
Funnily enough, despite the internet we still have 'bricks and mortar' shops - certainly they have been impacted, but if you remember the hype - "shops" should have become extinct over a decade ago.
Likewise, smartphones vs Newspapers, books, TV, CDs, Vinyl (I certainly didn't see that comeback happening!)
Back in the 90s I used to do the rounds presenting at Telco industry conferences and I recall one analyst putting up a graph of the global growth in mobile handsets and how it had consistently exceeded industry forecasts year on year.
He then proceeded to put up a slide with his company's very bullish (and ultimately overly so) forecast for the next few years and then capped it off with the statement "of course that's just a forecast and the only thing we can guarantee is that the reality will be higher".
I couldn't help but have a little chuckle at that at the time - I used to try to name check earlier speakers when it came to my slot, but I thought that one would be cruel!
I have been looking at EV cars, I think something is going to have to change for most people to buy them. 1) Price they are still about 2x the price of an equivalent petrol engine model. 2) Range many small cars only have a range of about 100 miles on full charge on a good day, cold days will be less. 3) Charging points, needs to be far more.
How do you charge at home if you have to park in the street?
Also where does the electricity come from given our lack of spare generating capacity, and then how does it get to the vehicles because once there are more than a few cars charging in residential streets the local distribution network will blow a fuse because it was never designed to deliver that sort of power to homes.
You mean like they were with their forecasts for the impact of the Internet on society? Or of smartphones?
Yes, this is exactly my point!! People were proved correct (eventually) but everyone was absolutely years out with the timing of widespread adoption. Smartphones and profitable commercial use of the internet took far longer than people were predicting at the height of the Dotcom boom - how quickly people forget, and it was only 17 years ago!
I have worked in technology for 35 years and so have seen it all many times over. I have never seen a technology that did not take far longer to gain acceptance than everyone predicted and most just died a death because they never found a real-world application.
The key problem with driverless cars that will greatly delay its widespread adoption that people seem to be completely missing and which makes it so completely different to smartphones or the internet etc. is that if something goes wrong with the technology you can't just hit the reset button. No, if something goes wrong people will die!! This makes it a completely different kettle of fish to all other consumer technologies and will mean I am unlikely to ever get in an autonomous vehicle (other than the shuttle at Stansted Airport) in my lifetime.
All the best, Si
"The key problem with driverless cars that will greatly delay its widespread adoption that people seem to be completely missing and which makes it so completely different to smartphones or the internet etc. is that if something goes wrong with the technology you can't just hit the reset button. No, if something goes wrong people will die!!"
..........................................
Well that hasn't stopped people driving cars. Or smoking.
But you may have a point. The astronauts had to fight to have manual control to land Apollo 9 on the moon. Even so, the legendary Yeager viewed them as "spam in a can". Nearly 50 years later - we still have pilots.
Well that hasn't stopped people driving cars. Or smoking.
But you may have a point. The astronauts had to fight to have manual control to land Apollo 9 on the moon. Even so, the legendary Yeager viewed them as "spam in a can". Nearly 50 years later - we still have pilots.
But that's people killing people, so that's OK. Mankind has been doing that since the beginning of time. Machines killing people is completely different and creates all kinds of complexities because in our society someone has to be held responsible in law. Who is responsible if two autonomous vehicles collide injuring and/or killing people?
What people miss is that what will prevent the adoption of autonomous vehicles well into the distant future is that it will require governments to pass legislation and it will create all manner of philosophical, legal and insurance issues. I'm not sure our society is ready for it and there are far bigger hurdles to jump than simply developing the technology to a point where it works - that's the easy bit!
All the best, Si
But all the signs are that California (the largest marker for cars in the US) is going to allow testing of self driving cars without human back up on public roads by the end of this year.
Isn't the really easy bit the insurance?
Isn't the really easy bit the insurance?
This is the USA you're talking about, right? Is there a more litigious country on the planet? It will be interesting to see what happens, especially when other drivers discover how to "hack" the driverless vehicles.
All the best, Si
Well let's hope they have improved: https://www.theguardian.com/technology/2016/jun/30/tesla-autopilot-death-self-driving-car-elon-musk
Seems the sensors could not distinguish between a white trailer and a cloud. I hope the navigating will be better than some satnavs which take people into rivers.
Yes as I posted before hacking can be a real problem:
https://www.ft.com/content/8eff8fbe-d6f0-11e6-944b-e7eb37a6aa8e
I think there is some way to go yet.
Well let's hope they have improved: https://www.theguardian.com/technology/2016/jun/30...
Seems the sensors could not distinguish between a white trailer and a cloud. I hope the navigating will be better than some satnavs which take people into rivers.
A number of the companies developing AV systems are very unhappy with the way Tesla has been promoting its Autopilot system, and this crash demonstrated why. Autopilot is an advanced driver assistance feature, not a fully autonomous system. It requires the driver to pay attention to the road at all times and be prepared to take action to avoid crashes, but many Tesla drivers have been engaging it and then concentrating on other things (watching videos on an iPad for instance).
Autopilot wasn't designed to handle a situation like the one that caused the fatality, and the investigation by the US National Highway Traffic Safety Administration concluded:
"NHTSA’s examination did not identify any defects in the design or performance of the AEB or Autopilot systems of the subject vehicles nor any incidents in which the systems did not perform as designed. AEB systems used in the automotive industry through MY 2016 are rear-end collision avoidance technologies that are not designed to reliably perform in all crash modes, including crossing path collisions."
This is why many of the developers feel that a leap to full autonomy is the only real path for this technology. The current situation where driver assistance features are being incrementally added to vehicles has the danger of creating complacency amongst drivers, with undue confidence in systems that have not been designed to handle all road situations.
Yes self driving cars will kill people, but the bar to improve on the status quo is not particularly high: they just need to kill fewer people than human drivers, who´re not particularly good at driving safely on average. No doubt it will still take a while though. I expect them to appear first to rebalance car sharing pools (e.g. have the car do 2-3 rounds of commutes by going back on the low-load leg themselves, while still leaving the option for the passenger to drive if they're a luddite).
I can't see it happening for at least 10 years. Why will the car dealership go, surely people will still be buying different models from different dealers? Why will there be 70% fewer vehicles?
Herbie 47
The argument (if it is correct or not) is that instead of individual car ownership, we will move to using cars as a service - so the car fleet will be much more efficiently utilised - reducing the number of vehicles in the car fleet. Also in such a world, you could imagine cars are owned by large companies (Uber like or maybe OEMs themselves) therefore disintermediating the dealerships.
Thanks, yes I have read up on it a bit more now, still can't see it happening for a long time yet, maybe it will work in London. There will still be lots of cars because people will want them at peak times. I can also see some resistance to this, some people will stillwant to own their own cars. So really it will be like a taxi service?
As someone once said, we always overestimate the change that will occur in the next two years and underestimate the change that will occur in the next ten.
That Rethinkx report is an interesting read. I think it's spot on in highlighting the role of economic incentives as the driving force that will lead to widescale adoption of what they call 'Transport as a Service'.
If you can save on average $5,600 per year by using TaaS instead of owning your own car, you have to really want to own your own car if you're happy to pay that sort of premium each and every year. Most people will just migrate over to the new technology once it becomes viable and cheap enough. People were fond of horses once upon a time but that did little to stop the motor car disrupting the horse and cart industry.
I think car dealerships may suffer from PCP issues in the medium term and will suffer from the adoption of autonomous/electric vehicles in the long term. There is probably money to be made in the shorter term but this is the proverbial picking up pennies in front of the steamroller. I’ve made money in Cambria Automobiles (LON:CAMB) in the past but if I bought into any of the car dealerships at this point I wouldn’t trust myself to pick the right exit point so I’m going to stay clear.
Not sure about that, things usually take longer to happen than many predict, how long have electric cars been around? Internet took a long time to get going, it's only fairly recently having an impact on shopping, even now most shopping is still done by going to a shop. I remember being told computers in an office would replace all paper that was about 40 years ago. Electric cars may come in the next 10 years but driverless ones replacing most car ownership I don't think so. We better start building more power stations, it's already in short supply.
Just to be clear I don't own any shares in any car dealers, I sold my Cambria Automobiles (LON:CAMB) after Brexit.
Well no one can precisely predict the future, but the point I was really making was about the force of economic incentives in driving change. From that perspective, if you try and strip away the hype that always accompanies new technology, it could be argued the examples you cite about online shopping and the paperless office actually back up that point.
In the context of the average household annual budget, it's difficult to envisage how you could save $5,600 per annum by migrating your shopping from bricks and mortar retail to online e-tail. Sure a few big ticket items might add up to those sort of sums, but every year? The economic incentives to changing behaviour are therefore lower and the decline of the high street has consequently been relatively gradual.
Likewise taking into account the cost of paper, storage and archiving relative to the cost of PC hardware, monitors, servers and running an IT department means the benefits of the paperless office are simply not great enough to have pushed people towards going fully paperless. The incentives aren’t big enough.
Coming back to vehicles, transport costs constitute a big chunk of the average household annual budget. If people can realise annual savings of $5.6k by going autonomous/electric, that’s a massive incentive pushing people towards going autonomous/electric.
Not everyone will. Some will be happy to pay a premium to own their own car and the Rethinkx report suggests 60% of the vehicle fleet will still be internal combustion-based by 2030, but those vehicles will provide only 5% of the total passenger-miles (I think they are US-focused). The key point however is that the bigger the economic incentives, the bigger the push towards behaviour change and the quicker adoption of the new technology will be.
I don't know whether it will come within 10 years or not, but I bet when the ball starts to gain momentum (probably when the regulators approve widespread use of autonomous vehicles on public roads), the uptake will be rapid if those savings figures are anywhere near accurate.
Well it's difficult to envisage saving $5,600 a year by not owning a car as that is more than I spent each year running a car, are you then saying all my trips by car will be free? I really can't see the savings being that large, if you right then the price of oil will fall, electric cost is rising and probably rise even more as demand increases. It may well happen but in 20-30 years time. People already pay a premium to own flash cars, can't see that changing for a while. I think there will be problems with driverless cars.
Typical car ownership is an expensive business with most of the cars costs being depreciation. There is already a big push into ‘non car ownership’ with PCP and leasing deals which are what is already driving up sales of new cars to record levels. The chances are electric cars will be the future, they are way faster, quieter, more reliable, less moving parts, negligible servicing, arguably greener and eventually be cheaper to run, build & buy than ICE. (have you seen how complex a modern ICE car is which its high pressure fuel pumps, injectors & turbochargers) The change will be fast and dramatic. Once electric and autonomous cars are established, its then a small step to rent the car for individual trips which I can see becoming more popular as road side car charging is awkward and slow.
A staggering 1 million+ people die each year on the roads and a large percentage of that is due to human error. (1600 kids in the USA alone EVERY YEAR!! - incredible figures) The south Koreans are taking autonomous cars seriously:
https://www.autocar.co.uk/car-news/industry/south-korean-autonomous-car-testing-city-open-october
There are comparing Taas with a typical new car in the US, it's also per household not per car. I don't buy new cars so my depreciation is less. There are are some pretty wild claims in that report "As fewer cars travel more miles, the number of passenger vehicles on American roads will drop from 247 million in 2020 to 44 million in 2030." 247 to 44, really, can't see that, what about at peak times, there won't be enough cars. Also I can't see any mention of costs for a TaaS trip, the companies that own them will want profits and to recoup all the development costs. There is also the problem with hackers, seems it could be an issue with driverless cars: https://www.wired.com/2017/04/ubers-former-top-hac...
Many deaths on the roads are from motorbikes, certainly in Asia.
The assumptions behind the savings figures are set out in the report - it's US-based remember, so 1.9 cars per household and don't forget depreciation charges. And yes, they also make the point that the price of oil will fall and they set out the implications for electricity demand and generation.
As someone once said, we always overestimate the change that will occur in the next two years and underestimate the change that will occur in the next ten.
Not seen the specific quote before so can't say who said it, but I really feel that the later figure is probably more like 20 years than 10. I've already cited some of the dot-com era predictions that are over a decade late and I could go further back and cite some (more back office) techy telco things that are probably later. The list is really quite extensive - one obvious add would be the "paperless office" but you could also go back and watch a few back issues of "Tomorrow's world".
Everyone will have a view on this, but for me I'm quite happy to make money investing in "obsolete" industries.
I think part of this disjoint is that the tech advocates fail to understand the pysche of the general public.
To me this statement is a classic example of that :
If you can save on average $5,600 per year by using TaaS instead of owning your own car, you have to really want to own your own car if you're happy to pay that sort of premium each and every year.
But that's it - people really do want to own their own car - they want to forget to take their bag / phone/ keys / shopping out of the car and go back and get them later.
They want all of their foibles (mirror position, cup holders, emergency mars bar in the glove box etc ) to be present exactly as they expect them.
They want to be able to dink the bumper whilst making some obscure manoeuvre in the certain knowledge that it doesn't really matter as they are going to keep the car for 5 years + anyway. (Hands up anyone that doesn't drive more conservatively when driving a hire / courtesy car!)
Sure I think a kind of "shared-ownership" / lease model to increase utilisation will gain some traction, but the idea that there will be a 90% uptake of this model in the next decade (or even to be frank in my lifetime) is fanciful.
Don't get me wrong; I think disruptive businesses can be a great investment opportunity, but so can the businesses that get marked down because hey are apparently going to become victims of that disruption.
I may have mis-remembered the exact quote so the specific 10 year figure may be wrong, the point is that we tend to overestimate change in the short term and underestimate it in the long term.
I'm not disputing that people really do want to own their own car, I'm simply questioning whether they are prepared to pay a premium of $5.6k per year to have their cup holders set just the right way. Over a typical 5-year ownership period that's $28k. As I said in my last post, it's the economic incentives that will drive the changes in behaviour and for the average household those sort of figures amount to massive incentives.
I think Mercedes supply the UK from a factory in South Africa. So presumably whether we are inside or outside the EU will not significantly affect that particular supply chain.
Well given that all UK trade deals are currently organised via the EU, that means that the UK shall not actually have a trade deal with SA post Brexit, so yes it will affect that particular supply chain. In fact the UK shall not have a trade deal with anybody, those deals shall need to be re-organised and if you think the idiots in charge of the wheel will be able to sort that out quickly you are in dream land.
Paul, I think I might need to spam you with links to better comedy shows...
Paul,
The other potential issue is that of possible mis-selling of personal contract hire vehicles. We've seen how the banks were clobbered with mis-selling of PPI, which cost them billions. Could this be a risk for car dealers? I have no idea, but it's being discussed in the press as a possibility, so is bound to weigh on share prices somewhat.
This would not surprise me in the least. I see too many people riding around in new Mercs who would never ever have the means to buy one, and that includes my other half's relatives. I don't believe in tooth fairies, and so something is not right somewhere.
My opinion - I like it. It's not one I hold personally at the moment, as I'm focusing more on growth shares. That said, am really tempted to buy back in, as the valuation seems compelling.
I would wait and see what insiders do first because no-one knows better than them how things look. It would be interesting to see how many directors of all the listed car dealers have bought shares in the market in the past 6 months - I bet it will be a very low number. I'm very much in the "do as they do" camp at this point regardless of what the valuation is telling me.
All the best, Si
The concerns around PCP seem to be that personal borrowing is rising and it's largely due to PCP.
But the link from that to saying there must be mis-selling is unclear to me.
The reason I avoid it is being hooked in to repeat deals with the same dealer or manufacturer at the end of the PCP period unlexss you pay the balloon payment and either keep the car or go elsewhere to trade it in.
I go for a straight personal lease so I just hand it back after two or three years and by being flexible in my car choices I have had some great deals that way, plus the investment returns on the money that would otherwise have been tied up in the car have covered the lease costs.
Of course it's been relatively easy to achieve that in this bull market and your mileage and mine may well vary in future.
The concerns around PCP seem to be that personal borrowing is rising and it's largely due to PCP. But the link from that to saying there must be mis-selling is unclear to me.
Sorry John but it was Paul suggesting this, not me - I only stated that I would not be surprised. I claim no special insight into how PCP works, especially being as old-fashioned as I am and buying everything I own outright (apart from a small mortgage).
All I do know is that there are loads of new cars on the roads funded by these deals and that there are people driving flash new motors that I know for a fact don't have two beans to rub together in their bank account. Whatever it is that's happening, it's clearly not sustainable, but I have no idea who will be picking up the bill when it goes "tits up" or what will trigger it - although I'd guess an increase in interest rates might do it.
On the plus side, what I do know is that any fallout will not directly affect any of my holdings.
All the best, Si
paul if you was a share in the stock market you would be down by 11.5% after the twitter incident lol.
Hi Paul.
Wonder if you care to comment on On The Beach (LON:OTB) acquisition of Sunshine.co.uk this morning? Adds a further 200,000 subscribers to their existing £1.2m customer base and is claimed to be earnings accretive in the first year. Market seems quite happy with shares up over 5% so far continuing a decent run so far in 2017. I originally bought in after the past Brexit dip last summer and so far so good although as ever this specialist online travel agent remains subject to the usual vagaries of Brexit implementation, terrorism threats and general down turn in consumer discretionary expenditure.
http://www.investegate.co.uk/on-the-beach-group--otb-/rns/acquisition-of-sunshine-co-uk-limited/201705100700096656E/
Best,
Gus.
you have become a brand Paul, that has its pros and cons especially when you are in the business of (informed) opinions. Social media has really empowered even the smallest of tribes: they can mobilise and respond with great effect.
Hi Paul,
There's been a good trading update from Vitec (LON:VTC) this morning saying they are ahead of market expectations. I don't think you or Graham have covered the company before but I would be interested to here your views.
Kind Regards.
So far as the wargamers are concerned Paul, maybe there's a learning point, maybe not. There's a prevalent culture of readily taking offence. But at least you've had the decency not to apologise! And I speak as an avid, and unmarried, boardgamer.
Hi Stockpot,
Yes I agree with you on the culture of taking offence. I think people actually enjoy taking offence at things, as it gives them an outlet for some general anger & frustration.
I'm a bit confused by your other comment;
But at least you've had the decency not to apologise!
Was this a typo? As I did apologise!
All good fun anyway, in the overall scheme of things. And it will be an amusing anecdote to put in my eventual autobiography!
Regards, Paul.
I've actually recently been totally geeking out on games. Bought D&D again... and some of the top games on https://boardgamegeek.com/
Have now invented a Stock Market Board Game with some quite cool mechanics. Prototyping. Production beckons.
Careful Paul - loads of geeks on this site ! :-D
ex AD&D man as well , big fan of Gary Gygax in my youth