Small Cap Value Report (Mon 20 Mar 2017) - TUNE, TAP, PEBL, FIF, MBH, MAI

Good morning!
I note from the comments that one or two readers get confused about who is writing each report here, either me or Graham. I'm not sure how to say this without sounding sarcastic. The clue is that the relevant author's name, and a massive photo of their head, appears at the top of each article.
Today I intend writing about;
Focusrite (LON:TUNE) - positive trading update
Taptica International (LON:TAP) - strong results
Pebble Beach Systems (LON:PEB) - final settlement from disposal.
I've now done the above sections, but have to catch a train from London back to Hove. So I'll aim to complete the following bits later today (probably early evening):
Finsbury Food (LON:FIF) - interim results
Michelmersh Brick Holdings (LON:MBH) - 2016 results
Right, those are done now. Sorry I didn't get round to looking at Maintel Holdings (LON:MAI) results, ran out of time. There's a very brief comment right at the end.
Focusrite (LON:TUNE)
Share price: 215p (up 5.9% today)
No. shares: 58.1m
Market cap: £124.9m
Trading update - this company makes musical & audio equipment. It looks an excellent company, demonstrating consistent growth, and decent profit margins.
Its year end is 31 Aug 2017, so today's update covers H1, the 6 months to 28 Feb 2017.
The key section says;
...pleased to report that in the first half of the year good progress was made in both the Focusrite and Novation divisions and in all three reported regions, particularly in our important US market.
As a result, revenue is expected to be approximately £32.0 million for the six months ended 28 February 2017, up from £25.9 million in the same period last year. This represents an increase of around 12% on a constant currency basis.
Cash conversion was also strong during the period and as at 28 February 2017 net cash was £9.4 million, compared with £4.0 million on 29 February 2016.
The trouble is, no mention is made anywhere in the announcement about profitability. That's a glaring omisson, because the whole point of trading updates is to let the market know how a company is trading versus market expectations. In this case, we are left to assume that the "good progress" remark is, by implication, saying that progress must be at least in line with expectations.
Still, it's frustrating to have to interpret wording, when these things really should be announced in a clear, and simple way. The company should have included a line saying that it's trading in line with expectations, or above, or whatever. Why wasn't that included?
I don't think there's anything to worry about though, because the Directorspeak reinforces the positive tone;
"The business has continued to perform well in the first half of the current financial year with strong sales from our key Focusrite products globally. Additionally, sales of our Launchpad products from Novation have also shown significant growth against the comparable period. I look forward to updating investors in more detail at the time of our Interim Results announcement."
So it sounds as if everything is going well. That's been reflected in a 5.9% increase in share price today.
So we now have to look at what the brokers are doing to their forecasts, since they usually get a more accurate steer from the company than anyone else does. What a ridiculous system, but that's just the way it is.
Broker updates - we were discussing last week where I get broker reports from. My broker emails me stuff, as I'm classified as a professional investor. Also, PR companies send me them, to help with writing these reports. Plus, for speed, I also subscribe to Research Tree, which is a quick & easy way to look up which of the reporting brokers which make their reports available through the platform have published updates.
Edison (free to access through their own website) has put out a note today, saying that it's leaving forecasts unchanged at the moment, but that "risk to market forecasts is now to the upside" - which has always struck me as a peculiar phrase! When you see that phrase, it's often a really good time to buy a share, as it means that the company's almost certainly out-performing.
Panmure has also left its forecasts unchanged, by suggests there is "excellent scope" for the forecasts to be raised in early May, when interims are announced. It's interesting to note that their forecasts assume 15% top line growth. So the 23.6% revenue growth announced today is usefully ahead, and providing margins are strong, that should provide an operationally geared boost to profits. There is clearly a big forex boost too, as the 23.6% reported top line growth is a lot higher than the 12% constant currency figure reported.
As you can see from the Stockopedia graphic below (which is incredibly useful, and I think is worth the subscription fee alone), broker expectations have already risen a fair bit over the last 12 months, and look set to go higher again. I'm paying much more attention to broker forecast upgrades now, as it's proving a very good hunting ground for overlooked growth companies, in this bull market.
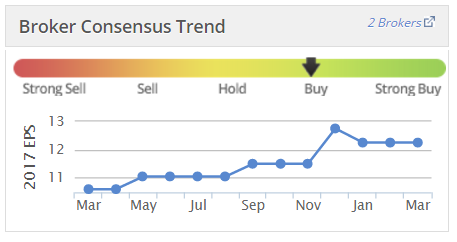
As an aside, personally I completely ignore broker recommendations & target prices, as they're fairly meaningless & unreliable. However, the narrative usually contains useful background about the company. Also, the forecasts (i.e. the numbers) are a useful starting point in predicting the future. I tend to look for situations where the broker is either being too pessimistic, or too optimistic, as that's where share price anomalies can appear. This situation looks to be one where the broker forecasts are probably now too pessimistic, so it could be a buying opportunity perhaps?
Valuation - reading between the lines, I reckon EPS this year might come out between say 13-15p. Based on the current share price of 215p, that gives a current year PER of between 14.3 and 16.5. That doesn't seem expensive to me, given the decent growth track record, and accelerating growth this year (assisted by favourable forex movements).
Given that the company also has a strong balance sheet, with decent net cash of £9.4m reported today (being 7.5% of the market cap). So there's scope for a special divi, or maybe a bolt-on acquisition, to enhance earnings.
My opinion - as you've probably gathered, I really like this company, and have written about it here before in a positive vein. My only worry is whether profits & growth are sustainable? The danger is that the company may not be able to keep innovating, with new products, enough to keep the competition at bay. I need to do some research on that, before buying in any size.
Although based on what I've read today, and my previous research on the numbers, I've decided to make a small initial purchase, then do some more work on it when time permits. Generally I like to scale into positions, over time, as my understanding of the company improves.
I'm keen to hear reader views on this, especially from anyone who is bearish. Considering the bear case is probably more important than hearing views that just reinforce my thinking.
Taptica International (LON:TAP)
Share price: 295p (up 0.9% today)
No. shares: 60.4m
Market cap: £178.2m
Full year results - for the year ended 31 Dec 2016.
This is an Israeli company, listed on AIM. That's normally enough to make me close the tab, and move on to something else. However, it came up on one of my screens a few weeks ago, due to a series of enormous increases in broker forecasts.
The highlights can only be described as spectacularly good. I've highlighted a few things that caught my eye. Also, opinions may differ on this, but I quite like the little summary comment on the left of the numbers.
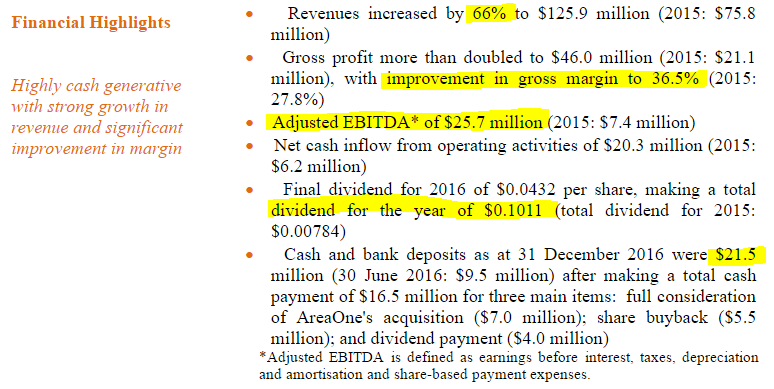
This share reminds me a lot of XLMedia (LON:XLM) - an astonishingly profitable & cash generative business, but that always leaves me wondering what's the catch? Other people seem to think along the same lines, as both XLM and TAP are priced sceptically by the market (i.e. a low PER, considering the growth).
TAP seems a more broadly-based mobile advertising business, whereas XLM is heavily reliant on income from promoting gambling websites (although it is also diversifying into other areas). I'm impressed with the big name clients which Taptica has on its website.
Doing a quick review of the numbers from TAP today, I can't see anything wrong with them. Everything looks fine, I'd say the profit is real, and the cashflow is also excellent. This view is reinforced by generous divis. Note that the company also paid out a special divi during 2016, a very good sign.
None of the telltale signs of aggressive, or false accounting are present, as far as I can see.
Basic EPS is up from 3.3 US cents in 2015, to 26.27 US cents in 2016, a staggering rise of 696%. Although note that Stockopedia shows expected EPS of 29 US cents this year, so the basic figure is below that. Although the difference could be the amortisation charge - brokers often reverse this out, to forecast adjusted EPS.
Outlook - this also sounds positive;
Taptica entered 2017 at a run rate significantly higher than at the equivalent period last year as it continues to benefit from the investment being made into mobile advertising by corporates and advertising agencies.
The strength of its offer lies in the Company's proprietary platform and ability to collect accurate data which enables the delivery of efficient and effective campaigns, which the Company will continue to do for all of its clients.
With consumers continuing to increase the use of apps and accessing the internet on their mobile most of the time, the Company anticipates existing clients growing their ad spend with Taptica as well as new advertisers entering this market.
The Company also expects to receive increasing demand from the Asia-Pacific region with demand from US and Europe set to continue.
As a result, the Board remains confident of delivering strong year-on-year revenue growth ahead in the year ahead.
It's worth noting that the company refers to revenue growth in the last sentence, and not profit growth. So I wonder if margins might be coming under pressure? They'e very high indeed at the moment, but is that sustainable?
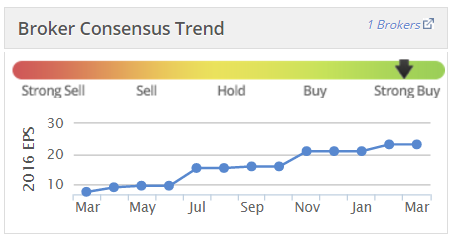
Broker forecasts - I haven't got anything specific at the moment. Stockopedia shows a consensus of 32 US cents for 2017, so much slower growth is expected. A dollar is about 81p at the moment, so that converts to 25.9p. So at 295p currently, the 2017 forecast PER is 11.4 - which looks remarkably low for a company that's just demonstrated explosive profit growth.
Also, note from my favourite graph, that previous forecasts have proven wildly pessimistic. A year ago the company was forecast to deliver on 7.7 US cents profit, and has now just reported over 3 times that figure. Acquisitions may have helped, but the total number of shares in issue has not risen by much, so existing shareholders have reaped the benefit of acquisitions, instead of being heavily diluted;
My opinion - every fibre of my being says to me don't touch this. However, the figures are just so good, that it's tempting to buy back in. As mentioned here in my report of 25 Jan 2017, I'd taken a position in it due to the remarkable rise in forecast profitability, However, I sold them late last week, as the price shot up unexpectedly. So banking a gain on a share that I was very uncomfortable holding (AIM + overseas, I usually avoid like the plague) was too tempting.
Actually, I didn't realise the company was reporting its 2016 figures today. Reading these numbers & positive outlook, it's very tempting to hold my nose, and buy back in.
Pebble Beach Systems (LON:PEB)
Share price: 6.125p (up 2.1% today)
No. shares: 124.6m
Market cap: £7.6m
Final settlement of VCS consideration - this company (formerly Vislink) is below my usual cut-off point of £10m market cap. However, it's been an interesting situation, so is worth following up on.
It's been like pulling teeth, but it seems that agreement has finally been reached between the parties, and the deal has completed. XG seems to have used every trick in the book to wriggle out of paying in full, instead renegotiating the deal to reduce the cash payments it originally was supposed to make. This didn't come as a surprise to anyone who looked at xG's accounts, which are diabolical.
Bank situation - this deal was supposed to get rid of PEB's problem bank debt. Remember this involved selling off its entire legacy business - what was originally quite a good business, but has since gone to pot in recent years.
The trouble is, the bank situation is still looking precarious;
As a result of the receipt of $2.125 million referred to above, and the previous arrangements where part of the Deferred Consideration due from xG was settled by xG settling VCS creditors which remained with the Company, the Company has been able to reduce its net debt from £17 million to approximately £12 million.
The Board remains in regular dialogue with its bank, who remain supportive.
Generally, when people say the bank is supportive, it means that the level of debt is problematic. From my business experience (back in the 1990s), I discovered that banks can instantly become extremely unsupportive, if someone at regional office decides to over-rule the relationship manager. So good relationships with the bank are not worth tuppence.
So where are we with Pebble Beach? There was a positive-sounding RNS in Oct 2016, saying that the company had received significant new orders at a show in Sep 2016. Although looking back at the interim results, it mentions strong orders/pipeline, but lower than expected revenues in Q2. So this looks to me like it's possibly the last chance saloon for this company - it's got to produce decent full year numbers, or the bank could push for a trade sale of PEB as well.
The risk is that, if the company is forced to sell off the remaining business, that there could be nothing left for shareholders, if a sale can only be achieved at a low price.
My opinion - overall then, I think this share is way too risky to contemplate a purchase. It all hinges on what you think of Pebble Beach - is the business any good? I don't know. There's then the issue of the remaining £12m bank debt. Remember that the bank ranks ahead of shareholders, so they have to be paid off in full before shareholders get anything, in a disposal or insolvency.
The bank debt + market cap (i.e. enterprise value) is now £19.6m. So if you think Pebble Beach (a tiny software company) is worth more than that, then the share might be of interest. If you are not sure about that, then the share looks best avoided, in my view.
John Hawkins has left a trail of destruction behind him, as well as plundering this company for excessive personal remuneration during his tenture (since ended). Therefore I'm inclined to expect more bad news, rather than any upside surprises. Hence for me, this share holds no appeal at all, but considerable risk.
OK, I have to stop now (12:53), as I need to get back to Hove by train (from London), well before rush hour. I'll try to finish this report later today, once I'm back home.
20:03 - good, I'm back home now, and stopped off en route to visit all 3 of my roll-outs in Brighton - pizza at Franco Manca (the main chain of Fulham Shore (LON:FUL) ) which was superb. Then 2-for-1 mojitos at the old-style Revolution Bar in Brighton (which was also impressive - fantastic staff, as I also found in one of their Reading branches, and a nice atmosphere), then finally a pot of tea & slice of gateau at Patisserie Holdings (LON:CAKE) .
Anyway, back to work now.
Finsbury Food (LON:FIF)
Share price: 111p (down 1.8% today)
No. shares: 130.4m
Market cap: £144.7m
Interim results - for the 26 weeks to 31 Dec 2016.
This is a speciality bakery, selling products to retailers and "foodservice" companies (e.g. coffee shops).
As you can see from the highlights below, there is only modest growth in profitability versus last year;
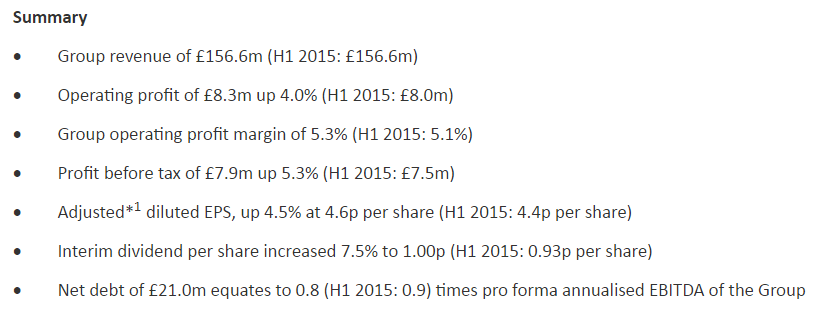
I can't get excited about anything there.
Outlook - nothing exciting here either;
The Group has delivered a strong first half performance and the business is demonstrating the benefits of the investment and strategy implemented over prior years.
Our balance sheet remains strong allowing us to continue to invest in our businesses in order to deliver our stated growth strategy. The broader channel, customer and product diversification achieved has created a solid platform for the business and will continue to benefit us given our access to higher growth opportunities such as the faster growing foodservice channel.
The UK grocery market continues to be challenging even though the wider economic environment is improving slowly.
As previously noted, increasing commodity prices, the adverse impact on USD and Euro exchange rates and the National Living wage means the Group is working hard to mitigate input cost inflation through continued operational efficiency, investment in automation and, inevitably, price increases; all of which are ongoing. Whilst we are cognisant of the price recovery process, we expect the Group's steady performance to continue into the second half of the financial year.
This seems an ill-thought through statement. At the start, it tells us that H1 performance was strong. Then at the end it says that steady performance is likely to continue. I'd say performance falls more into the steady category, and isn't really strong - EPS up 4.5% isn't a strong performance, is it?
Next, the company claims above that its balance sheet is strong, which it isn't particularly (in my view). I see the balance sheet as OK-ish, but certainly not strong.
Note there is a pension deficit too. It's not big, at £6.5m, and requires annual cash contributions by the company of £366k. Worth noting.
It then contradicts itself in note 1, where the company basically admits that it has a weak working capital position, and is reliant on bank funding;
It should be noted that current liabilities exceed current assets. Having reviewed the Group's short and medium term plans and available financial facilities, the Board has reasonable expectations that the Group has adequate resources to continue in operational existence for the foreseeable future.
The Group has stayed within its banking facilities during the year, meeting covenant requirements. The Group has the continued support of its banks with facilities of £50.9m. In addition, the Group has a strong asset backing and strong trade debtor book. Accordingly, the Board continues to adopt the going concern basis in preparing the Financial Statements.
I'm not saying there is any reason for concern - but I've found that companies which claim to have a strong balance sheet, often don't! That's confirmed here. I looked in the last Annual Report, and it does have £10.2m on the balance sheet in land & buildings, but no further details are given. So I don't know whether that is freehold property, or not, nor whether it might be worth more than book value, or not.
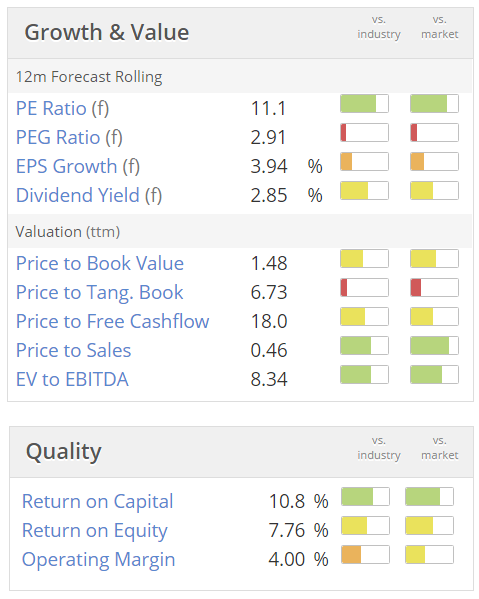
Valuation - it looks set to do about 10p EPS this year, and a little more next year (if those cost pressures can be absorbed). So the PER of 11, for a company with debt, and little prospect of earnings growth, doesn't strike me as particularly attractive;
My opinion - in a word, underwhelmed.
We're in a bull market, where the shares that are going up, are companies which are delivering decent growth. As I recall from the late 1990s, as the TMT boom & bust was building up, what happened is that boring, mature businesses with little growth potential just drifted downwards, as people sold them to put money into more exciting tech stories.
I think there's a bit of that happening now, and potentially more in future. When the TMT boom finally burst in 2000, value, (i.e. pedestrian growth type companies) shares had in some cases got down to PERs as low as 5 or 4. So buying something today like FIF, on a PER of 11, could turn out to be unwise, if the price continues to drift down. There's been some of that going on already, as you can see from the 12-month chart below;
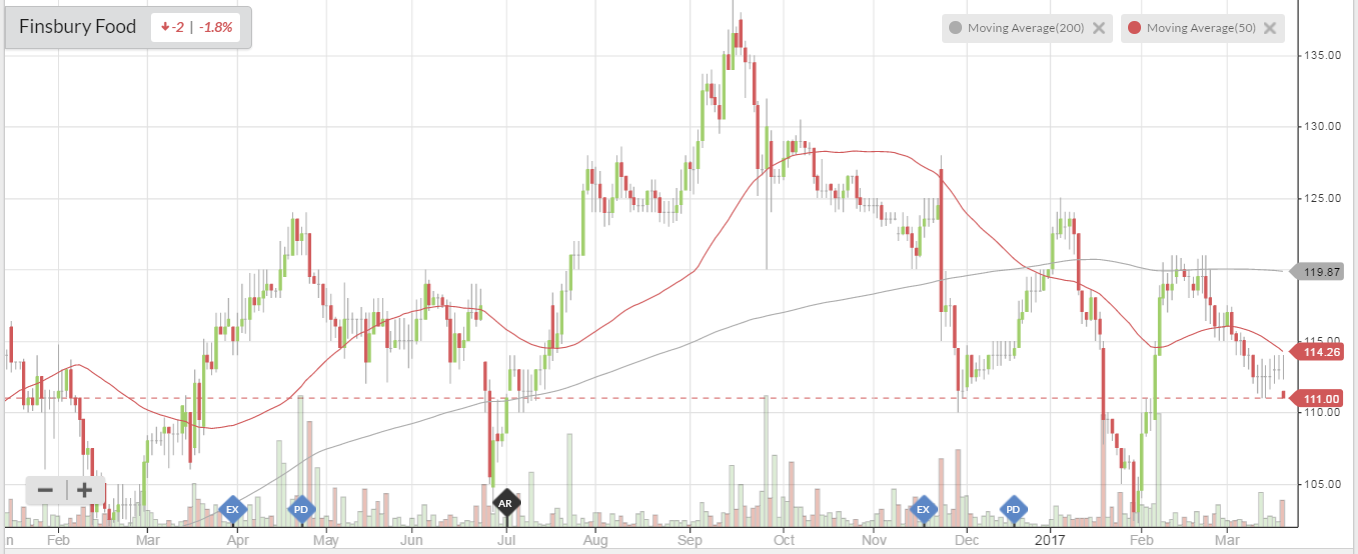
The red line is the 50-day moving average, and grey line is 200-day. As you can see, the share price of 111p is below both lines, which combined with fairly lacklustre (or rather, steady) results today doesn't seem to inspire much confidence. I can't see a lot of upside from here, unless there's a takeover bid.
It's also interesting that whilst profits have increased from acquisition(s), EPS hasn't really moved up much. So I question whether acquisitions have really added any shareholder value?
On the upside, FIF winning the cake licensing rights for national treasure Mary Berry, could give results a boost when that new cake range launches in H2.
Michelmersh Brick Holdings (LON:MBH)
Share price: 61p (up 6.6% today)
No. shares: 81.5m
Market cap: £49.7m
Final results - for the year ended 31 Dec 2016.
These figures are in line with the last trading update on 16 Jan 2017, which indicated that 2016 profits would be "at or around a similar level" to 2015. So the outcome of £4.6m profit before tax is the same as 2015. Strangely, the highlights bit refers to £4.5m in 2016 and 2015 for profit before tax, whereas the P&L itself says £4.6m in both years.
Operating profit was actually down 3.4% to £4,551k in 2016, but a £171k favourable movement in finance income/(expense) levelled up the profit before tax figures to almost identical between 2015 and 2016.
As the narrative explains, there were operational problems in 2016, which impacted the results, and have now been resolved. So maybe 2017 might show some improvement on 2016, as a result of this?
Diluted EPS was 4.36p for 2016. That represents a PER of 14.0.
Balance sheet - this looks very strong, and contains property assets, including a site that is being sold post year end for £2.7m.
There's no bank debt, and overall cash of £4.7m, plus the proceeds mentioned above of £2.7m, so that means it should have £7.4m net cash, just under 15% of the market cap - so pretty significant. I'm not sure what other property assets are in the books, but that is important to research if you're trying to value the share.
The group doesn't seem to have any issues with pension deficits. The only mention I can find is of defined contribution pensions, which can't go into deficit, unlike defined benefit pensions - which are the ones that cause problems. So that looks fine.
Dividends - this looks to be the issue which might have pleased investors today. The word "dividend" is used 20 times in today's RNS, and this section reads very well;
In 2015 the Group paid its first, albeit modest, dividend since 2008 which was doubled in 2016. The Board are pleased to announce that they will propose a dividend of 2 pence per share in respect of the year to 31 December 2016 (2015: 1 pence).
Having restored the Group's positive cash balance, this represents a commitment to shareholders to provide a meaningful return on their investment.
In addition, the Board has decided to commence payment of an interim as well as a final dividend in respect of 2017 in December and June respectively.
The dividend represents over 40% of earnings and, whilst the Group is trading favourably, it is the Board's intention that this level of distribution is maintained.
Sounds pretty good to me.
Outlook - this sounds positive, I think, although it's light on detail;
The positive indicators and market fundamentals look set to continue.
There is a widely accepted need and publicised government drive for delivering new housing. We believe this backdrop presents significant opportunities for the Group in not only new builds, but also in RMI where we are particularly strong.
During 2017 the Group will improve efficiency and promote new innovative and contemporary products to the market. Through the course of the year the market may see brick demand rise to meet current mid-term UK output capacity, however, the significant uncertainties surrounding the impact of Brexit continue to prevail.
My opinion - it's an interesting company, that seems to be doing alright. It's not clear how much 2016 financials were impacted by operational problems, so I'm not entirely sure what 2017 might look like.
From my point of view, this probably sits in the "too difficult to value without doing loads more work" category. It's not really the type of thing I'm looking to buy at the moment, so will move on.
Maintel Holdings (LON:MAI) - quick comment on its 2016 results, out today. I'm not interested in this sector. I was put off by the way profit warnings seem to occur, and future earnings streams can be unpredictable, or not be sustainable. Alternative Networks was bought out for a rather disappointing multiple a few months ago. Technology is moving on so fast, that it could make companies like this obsolete. I don't like the balance sheet at Maintel - it's taken on a lot of debt for a big acquisition, leaving NTAV now significantly negative. That said, the market seems to like the results, as the share price has risen 8.1% to 1040p. It's not for me anyway.
See you in the morning!
Regards, Paul.
(these reports are just one person's review of the day's results & trading updates. They are not tips, or advice, they are just a personal opinion on each share, which will sometimes be right, and sometimes wrong.
I don't want to tell people what to do - as I only get blamed when things go wrong! So please do your own research, as I may have missed important things, since I cover 500+ companies, so cannot possibly go through things in complete detail.
I'm an active investor, so frequently hold positions in companies mentioned. I disclose where I hold a position. Obviously I hold positions in the companies that I like the most. I reserve the right, and am perfectly entitled, to change my mind on any share at any time without notice, and to buy or sell my shares whenever I want. My views here are subject to change, but are always my honestly held view at that particular point in time).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Focusrite
I am very familiar with a lot of their products, Launchpad is a great piece of kit. At the moment there is a boom in people setting up commercial music studios that has been going on for sometime now, so many have popped up in Bristol where I live over the last 4 years and Focusrite and Novation are both very well known and respected for studio hardware and software. I really like the idea of them releasing Launchpad as an app, I am going to get it myself.
Well placed for growth IMO, I hold.
Hi Paul,
ref to: Focusrite (LON:TUNE). Looking at the cash flow stat. I noticed that the FCF from op activities is reducing on yr bases. Cash from op. activities for 2015: 6,2mil, in 2016: 3,9Mil and in the last stat. company said its down to 0,4Mil (half yr) putting it down to extending payment terms to one client and also noticed that the inventory increasing substantially. That makes me to hold back and keep it on my watch list.
Many thanks for your reports. Regards from Prague.
Jan
I looked into Focusrite (LON:TUNE) a couple of months ago and concluded that I liked it but not at £2
What stops it being worth £2 IMO is a) capitalised development costs and, b) the volume of sales that are new products.
I can't access the report right now but I remember them quoting the amount of sales that were made up from recently released products. They made it sound like a good thing but my concern is that they will have to keep innovating and churning out new products to keep sales up. I could be wrong on this. I had hoped the price might drift down to 180 or so but no luck. I haven't fully shaken off my value instincts, although I am starting to pay more for growth.
I looked at XP Power (LON:XPP) at the same time and bought some at £18, hoping to add more on any weakness. they're now £20 and I'm left with a small position. C'est la vie. Lots of uncertainty in the market to come so I might get another chance. I, like Paul, prefer to build up a position. Sometimes you can buy more at a better price, or at a higher price with more up to date, and improved figures to work from. Sometimes the market moves up and you're left with a rump holding of a good business.
Doug
P.S. please keep it to one report, it's not that difficult.
Are not a lot of these "new products" just rebadged with minor upgrades or are they actually brand new products? I know with hifi many companies like Marantz will bring out a "new" cd player every year, except it's just the same as the old one with a different number and a few minor tweaks.
Focusrite (LON:TUNE)
That is possible Herbie I didn't dig that deep, I just took it at face value.
They do have a decent R & D spend though, not ridiculous but enough to make me think they need to run quite hard to maintain sales.
I think they do need to spend a fair amount as technology is always changing. Also I believe they are expanding their range into new areas, ie going from more pro music to more consumer market. You are probably right there is quite a bit of competition.
You're presumably referring to this statement in the last annual report:
"We spend over 6% of revenue on product development and seek to achieve about a third of our revenue from products launched within the last 12 months. The result: in FY16 we launched 16 new products."
With a product lifespan of between 3 and 6 years, something like 75%+ of sales must be from products released within the last 3 years.
Yes that sounds like it thanks.
That's a high churn rate of replacement products, I liked TUNE every other way, and this wasn't enough for me not to like it, but it was enough for me to not want to pay over £2 for them. Especially at a time when I preferred XPP.
Volvere (LON:VLE) issued a positive trading update at 3pm this afternoon, leading to a 6% increase in price.
anyone have any thoughts on AB Science seems to have come out with a good report today?
Paul,
Thanks for your thoughts on Taptica International (LON:TAP). Before taking an opening position some weeks ago (having missed the initial RNS) in January I looked as far as I could for any problems in the accounts bearing in mind your earlier comments about Israeli companies and XLMedia (LON:XLM) in particular .In fact there is more information about Taptica International (LON:TAP) than XLMedia (LON:XLM) which provides some comfort I guess. With what looks like expansion into various geographies we must continue to expect cost related to expansion. Not exactly a retail roll out but you get the drift.
Topped up today.
Re Focusrite (LON:TUNE) this appears to be a lovechild of the founder, and this gives us comfort that even if it is pedestrian (?) nothing stupid will be done to upset it. Dived in with an opening position today
Paul, please continue to be sceptical. It helps us all sleep.
Steve
"risk to market forecasts is now to the upside" Paul, yours is one interpretation of the phrase, but another could just as easily be that whatever the forecast is we are now less confident of it! The English language provides plenty of ways to write in a way that expresses clearly what is meant. Politicians use confusing language so that we all read what we want to hear into what is said. When companies do it I tend to think they are trying to mislead - a bad sign.
I own a Focusrite prosumer product (LON:TUNE) which I bought to help my podcasts sound better. The feedback on Amazon and elsewhere on their products is universally excellent. Their products command excellent prices on the second hand market. I had occasion to call their helpline with a tech query - the response, from a polite and well-informed human, was exemplary. They even followed up, unsolicited, a few days later to make sure my problem had been addressed.
You find their products also in music and production showrooms - these are very very busy places, packed with kids buying kit to make music, many of them accompanied by their parents and their credit cards. I share Paul's enthusiasm and having missed the boat on Gear For Music I am also tempted to take a small position, based both on Scotty's comments and my personal experiences.
Hi Paul, re TUNE, I was looking at a presentation on the company's website and they have capitalized £2.7m of R&D the last two years, and like you I prefer to see that written off for prudence, so if you adjust fully for that, the rating is north of 23x. They didn't split out amort from depreciation (£2.6m in total), so not sure what the precise net figure would be. There is a positive tax effect from the R&D spend as well so they only paid 12.2% tax last year, so again how sustainable is that? Gross margins fell last year from 38.8% to 38.4%, but not clear if that is a trend. Keep up the good work!
From the last annual report (note 18), the amortisation charge on development costs was £1.963m last year and £1.816m the previous year, so if development costs were written off as incurred, last year's operating profit would have reduced from £7.14m to £6.387m and the previous year's operating profit would have reduced from £6.32m to £5.469m.
I'm personally more relaxed about capitalisation of development spend where the circumstances are right and if you can trust management not to play silly buggers - if there is a direct link between the development spend and the products for sale which are created by that development spend, then I think it can actually make sense to capitalise as the spend is then matched in the same period against the resulting revenues.
£TUNE amortise development spend over three years and say that a typical product life is between three and six years, so it could be argued they are actually being conservative in only amortising the spend over three years.
On gross margins, starting in 2012 their gross margins each year have been: 38.4%, 39.6%, 38.8%, 38.8%, 38.4% which looks reasonably stable to me.
Hi Bestace, I hadn't got to the annual report yet, so thanks for providing the net amortisation charge on dev costs. That all looks reasonable, especially in light of the conservative 3 year write-off policy. Looks like an interesting investment- with only c11% of the addressable market there could be a big growth opportunity still to come-but who are the biggest competitors and how fragmented is the space?
Having skimmmed through the IPO prospectus this morning, I can give you an answer on that!
Under section 6.3 ("Competitive landscape") they say this:
"Focusrite operates in a number of segments across its product range. The Directors believe that the market in most segments is fragmented with a wide range of competitors. The Directors believe Focusrite’s key competitors across its product ranges are: AKAI Professional LP, Ableton AG, Apogee Electronics Corp., Avid Technology Inc., Native Instruments GmbH, inMusic Brands, Inc. (M-Audio), Presonus and Yamaha Commercial Audio Systems Inc"
They seem to be growing a lot quicker than the overall addressable market, but as with most technology companies, there is an element of 'running to stand still' in that continual development spend is required to stay relevant.
On the other hand, their demonstrated ability to successfully bring new products to market on a regular basis could be seen as a moat.
At IPO they spoke of a development pipeline of 40 products; it's a shame they don't seem to refer as much to their pipeline in their post-IPO announcements.
Very helpful, many thanks.
're XL MEDIA (XLM). I note your sense of caution, but wonder if the recent large purchase by a director and the latest company acquisition might offer some basis for optimism ?
Paul, thanks for the update on Taptica International (LON:TAP). I stumbled on it last May when looking for tech stocks to add to my watchlist. As a mobile app developer, the name ringed a bell from somewhere. That and mobile advertising being a hot industry, I decided to pick some up. I'm confident it's legit. Having said that, as it's Israeli, I have a tighter stop than normal.
After an initial flurry at the bell, the response from the market is underwhelming with it flat now. I tend to agree that margins are unsustainably high. Perhaps that's put some people off? My personal hunch is a buyout or a move to NASDAQ will happen within the next year.
Paul - some news about Purplebricks (LON:PURP) from the Australian Financial Review: http://www.afr.com/real-estate/residential/purplebricks-hits-400-sales-expands-into-perth-20170317-gv0hjg
It's already completed 435 sales in its first six months in Australia which sounds very promising. It says "Purplebricks is expanding at a faster rate in Australia than it did when it launched in the UK three years ago."
RE: Focusrite: I had a look at this company this morning.
Is the age of the chairmain (who owns c.52%) of the company a concern? at 66 surely he'll be heading for retirement in the near future?
I personally like to see larger shareholdings by directors and see at as a real positive. And surely 60 is the new 40 (being closer to 60 than 50 I hope so! :-)) and a chairman in his 60's and a small free float did no harm in the case of Avesco (LON:AVS) !! Indeed it might be a reason to buy because of the possibility of a takeover.
I don't hold but Paul's comments on Focusrite (LON:TUNE) will certainly make me investigate further as for me it ticks all the right boxes.
Excellent report as always Graham....
Excellent report as always Graham....
LOL! Good one!! :-D
P.
Paul, are you saying there will now be a separate report from you and from Graham. I think in the past that's where the confusion was, your head was at the top but part of the report was written by Graham, also the emails that go out always have your name on them even if Graham does them.
Hi Herbie.
Looking at Friday's report from Graham as an example, his name & picture are at the top of the report.
If I email him a section to include in his report, then that section is clearly marked as having been written by me. So I don't really understand where the confusion arises? The email header is just a generic one.
What we're generally trying to avoid, is producing more than one report per day, because readers made it clear they find that displeasing. Although on the busiest days, it's unavoidable, so we do 2 reports, perhaps once per week. On other days it's either me or Graham, with the occasion section added from the other. Graham generally does Fridays now.
Perhaps I can just ask people to dwell briefly on the author's name & photo, at the top of each article, to reinforce who has written the report, before continuing.
Regards, Paul.
Re: Boohoo.Com (LON:BOO) - Hi Paul , just noticd that you've sold out of the bulk of your holding in BooHoo this morning in your Beam Me Up Scotty fantasy portfolio and wondered if you'd like to share your reasoning?
Hi Laughton,
just noticd that you've sold out of the bulk of your holding in BooHoo this morning in your Beam Me Up Scotty fantasy portfolio and wondered if you'd like to share your reasoning?
Sure, happy to do so.
I needed to raise some cash to put some Focusrite (LON:TUNE) into BMUS. As mentioned in today's report, I like TUNE. It may not have explosive upside, but if the current strong performance continues, then it's feasible that there might be say 50% upside on it. Especially as it looks as if broker forecasts are likely to be raised in May.
I didn't want to sell anything else, so decided to ditch most of the remaining BOO. I've left a small amount of BOO in the fantasy portfolio, just so that I can continue to enjoy looking at the +502% statistic next to BooHoo in the list of stocks, lol!
Regards, Paul.
Bit confused - but then realised that it's because I think you've "added" the wrong stock to BMUS - you have it down as Fulham Shore (LON:FUL) - Stock Rank of 17!!!
Or maybe that's an additional addition.
Hi Laughton,
Yes, I've also added some Fulham Shore (LON:FUL) to BMUS today. No particular reason - it was meant to be in there originally, as it's a stock I hold personally & am keen on, but it was overlooked. I just update BMUS when I remember, so sometimes things get overlooked. But it broadly mirrors my personal portfolio, in terms of my conviction buy/holds & position sizes. Although I've got a long tail of smaller positions personally too - should probably have a cull actually, as it can get unmanageable if you have too many things hanging around.
Regards, Paul.
As an ex audio professional I can say the reputation of Focusrite in the industry is solid. Although more recently they have offered 'prosumer' type products they have traditionally been a premium, very high quality brand with prices to match. I would guess their products have a high profit margin though this could possibly have softened in recent years as they chase the bigger volume prosumer market.
I would second what you say about their reputation and their market is more pro music equipment such as studios I don't think their customers will be that fickle. They want quality products they know are going to do the job at a reasonable price, so their products will be more likely found in G4M than in your local HiFi shop. Not sure about profit margin, it tends to be quite low compared to Hifi equipment. Would be interested to know what proportion is in the US market?
Agreed... my experience of them is their Pro Studio equipment costing £2k+. Granted they don't sell many of these but it helps support the brand which hopefully translates into sales of the higher volume prosumer / hobbyist studio kit. I see from their site they offer a big rage of C £100 boxes these days. US market is most likely their biggest I would have guessed but would be interested in actual numbers.
Small thing, but is it just me that finds it a bit off-putting when companies like Focusrite (LON:TUNE) , Patisserie Holdings (LON:CAKE) and Snoozebox Holdings (LON:ZZZ) have 'novelty' tickers rather than the more usual ones?
(I did read somewhere that men who have personalised number plates on their cars are subconsciously making up for a deficiency elsewhere. :-) )
I quite like it, it easy to remember what they are, I mean tickers not number plates.
Better than just PTH or something that you often have to check what it is. Also some are very similar so it's easy to get them mixed up, at least CAKE and TUNE stand out. Only problem is on a screen or portfolio in alpha order they don't always appear where you expect.
I think the novelty tickers are great fun ! :-]
Plexus would seem to have a particularly apt novelty ticker.