Small Cap Value Report (11 Mar 2016) - SGI, TPOP, CMBN

Good afternoon!
Something funny has happened with the formatting of today's article. Please bear with me, as I try to resolve this problem.
I'm walking wounded today, after a most convivial time was had last night - every 3 months I get together with my best investing friends, and we have a fascinating afternoon swapping share ideas & experiences, followed by a lovely meal, accompanied with copious wine. Not good on a school night. So I'm in the mood for a good rant, and won't be taking any prisoners.
Stanley Gibbons (LON:SGI)
Share price: 22.5p (down 39.6% today)
No. shares: 47.1m
Market cap: £ 10.6m (pre-dilution)
Funding update - delays in fundraisings are ALWAYS bad news. ALWAYS. It means they're struggling to raise fresh money, and the buyers will usually demand a deep discount. I've been involved in distressed fundraisings before, and the way they work is that the key Institutions just name their price. Existing holders get shafted.
SGI has been such a well-publicised train wreck, that there's really no excuse for PIs holding this share, other than obstinacy, or sheer stupidity.
As with any small cap, Institutions are high & dry, with (usually) inadequate liquidity to get out of a significant shareholding, but we small private investors have the wonderful advantage of being able to sell up at any point. So it stuns me that people refuse to admit to their mistakes, and continue holding a share that is very obviously in the process of collapsing in value.
Nobody likes a smart-arse, but I couldn't have been more stark in my warnings about this share here on 13 Jan 2016 when things were so bad that SGI went on the Bargepole List at 59.5p, again here on 23 Feb 2016 at 43.5p, and most recently here on 4 Mar 2016 when I speculated that a discounted fundraising as low as 20-25p was probably imminent.
It's even worse than that! There is so little appetite for a fundraising, that today the company announces that the emergency fundraising (to bail out the bank, again) will be at just 10p! That values the existing equity (47.1m shares) at just £4.7m. That's probably £4.7m too much. Personally I would only have put in fresh money for a pre-pack Administration.
Further to the announcement made on 4 March 2016, the Group confirms that it is very close to concluding the terms of an equity fundraising of approximately £13 million by the issue of new ordinary shares at a price of 10p. A further announcement will be made in due course.
To raise £13m at 10p per share means that 130m new shares will need to be issued. So that's massive dilution for hapless existing shareholders. This represents an enlargement of the existing issued equity from 47.1m shares, to 177.1m shares, so existing shareholders will only hold 26.6% of the enlarged equity. Costs will be high, probably about £1m at a guess.
On 4 Mar 2016 the company used this vague form of words regarding pre-emption rights;
As previously announced, the Board intends that the fundraising will be executed in a manner that recognises the pre-emption rights of existing shareholders insofar as is possible.
What does that mean? Weasel words in my opinion.
The share price has fallen today to 22p, I'm amazed it is at a premium to the 10p fundraising. I expect that discount to narrow further, as people putting fresh money into the fundraising will flip the stock for an instant profit, if they've got any sense (that's another question).
What happens next? No doubt there will be a gigantic inventories write-down, as reality dawns that tiny pieces of paper are really not worth millions of pounds, once the fools that buy them stop bidding up the prices against each other.
Sometimes people lose money on shares through entirely unforeseen circumstances. People who have lost money here were just plain stupid. So absolutely zero sympathy from me.
The Peoples Operator (TPOP)
Share price: 34.4p (down 15% today)
No. shares: 77.1m
Market cap: £ 26.5m
From one pile of junk to another. I remember when this share was being floated, I read the prospectus and was almost rolling around on the floor laughing. Ridiculous is not the word. The valuation was even more ridiculous. They had to discount it from the initial ludicrous valuation to get the fundraising away, but even then it was blindingly obvious that this share would collapse, it was only a matter of time.
I've repeatedly tried to short it, but sadly there is no borrow on the share.
I have no idea why it's falling in value today, other than that it's a terrible company with little to no chance of commercial success. When will people learn?
Cambian (CMBN)
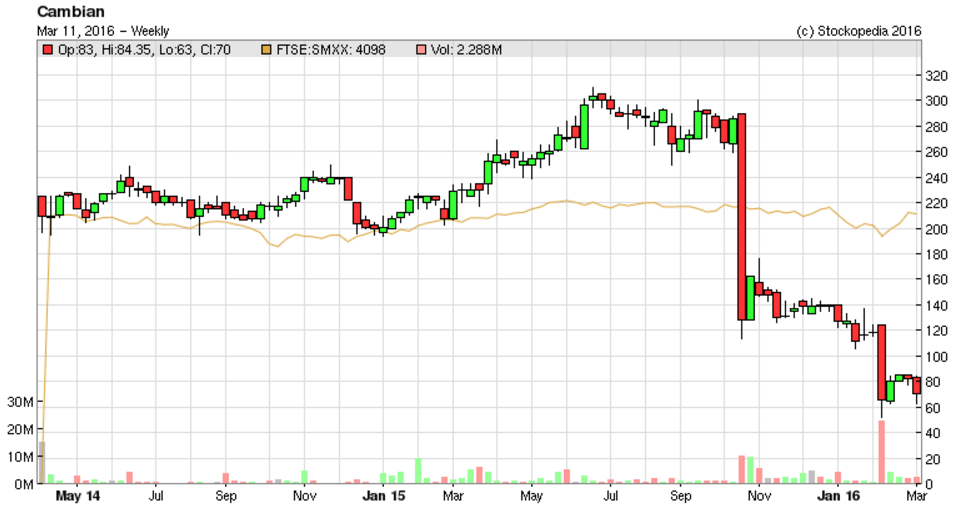
Share price: 69.75p (down 15% today)
No. shares: 184.2m
Market cap: £ 128.5m
Temporary waiver of banking covenants - I had a good rummage through this company's accounts here on 9 Feb 2016, when its share plunged on a profit warning and clear indications of financial distress (it was very close to breaching banking covenants).
Today's update indicates that things have got a little worse (quelle surprise!) and that the banking covenants will indeed be breached, but the bank has given a temporary waiver until 26 Apr 2016;
The Board now believes that it is likely that, in light of the ongoing finalisation of costs and the completion of its audit in respect of the financial year ended 31 December 2015, results for the year will be slightly lower than previous guidance. As a result, it is likely that Cambian will not be in compliance with its financial covenants for the period ended 31 December 2015.
Cambian has however agreed a temporary waiver with its lending banks to cover this possibility and to facilitate the continuing discussions with them, which are aimed at agreeing amendments to the existing facility, including resetting covenant levels. Cambian hopes to conclude these discussions before 26 April 2016, which is the expected date of the preliminary announcement of Cambian's results for the financial year ended 31 December 2015. Accordingly, it has been agreed that the waiver will expire on that date.
This is an interesting situation, as Cambian actually has quite a strong balance sheet, stuffed full of freeholds. Banks like lending against freeholds. Although the special purpose properties which it owns are difficult to value, and ultimately the valuations depend on what profits can be earned from each site - something that can change dramatically if public sector clients refuse to agree price rises - look at what happened to Southern Cross Healthcare a few years ago - it went bust when LAs refused to countenance fee increases.
I think it's likely that Cambian will survive, but the banks may force the company to do an equity fundraising, which as we've seen with SGI today, can be a massive discount if providers of fresh financing decide to screw existing holders - which is the commercially sensible thing to do.
Again, I can't see any reason to get involved here. I might take a fresh look at it once the company has properly sorted out its financing, and in all likelihood the shares might be cheaper then.
Shares in this type of company nearly always go wrong. Absolutely minefield for investors, so again, why get involved?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
RNS this morning to the effect that Stanley Gibbons (LON:SGI) is selling its Mayfair premises and has sub-let a part of its NY office as well as a new NED appointment from its principal shareholder Hendersons. Proceeds being applied to reduce debt. Relatively small numbers but in the context of a bombed out market cap of £25m a good start to the rationalisation process. Still awaiting visibility on the realisable value of the substantial inventory.
http://www.investegate.co.uk/stanley-gibbons-grp--sgi-/rns/sale-of-premises---board-appointments/201605240700120680Z/
Gus.
A series of RNS this week disclose that Hendersons fund management and Richard Griffiths have increased their combined stake in Stanley Gibbons (LON:SGI) to something like 43%. Not clear how much was done through the recent placement (presumably most of it looking at daily trading volumes) and how much through open market purchases. Likewise not clear if they're acting in concert or not - tho' at 43% you would expect the Takeover Panel to have an interest if they are. Either way, the share price has been edging up to about 18p offered. Worst case, there are now a couple of big ticket parties with an interest in shaking Stanley Gibbons (LON:SGI) down; best case maybe a public to private bid in the offing? Watching with interest and now have taken a small stake.
Gus.
Maybe on reflection, worst case is a big overhang of placement shares with brokers and these two parties that will continually flood the market on any rise! We'll see
Re. Stanley Gibbons (LON:SGI), the company has now completed its £13m placing and the new director has come on board with a view to shaking down the recent acquisitions and hopefully applying a bit of financial discipline to the ongoing business. The RNS suggests the placing was 220% subscribed which is a pretty good vote of confidence (desperation if you're a cynic). Share price seems to be levelling out at about 15p, i.e. still a 50% premium to the placement price.
Not sure whether still too early to re-visit but maybe worth watching as a potential recovery play, especially if there is some visibility provided on the liquidation value of the inventory.
Gus.
You said it straight paul, the directors on LTIPs are stealing the company and being expected to be paid twice
anyway the vislink rougues had their comeuppance with the share price diving. Note, I am an ex-holder.
Re Stanley Gibbons (LON:SGI) On reflection I am staying out. This is no longer in the realm of rational behaviour.
Where are the latest SCVPs? 11 March is the most recent that I can find!
That seems to be the most recent one Paul has done.
Hi Brackendale - I have no interest in Stanley Gibbons (LON:SGI) but after reading your note and doing a fag-packet calc. I come up with the following:
- current Book Value = £82m
- current Tangible Book Value = £43m
- current TBV less say 50% of the value of inventory = £15.5m
And the market value after today's drop in sp = £8.5m
So if you are right and the inventory is not inflated this is a really good opportunity. And even if you are partially right, with a 50% haircut of the inventory, it still looks a good opportunity. Only if I can trust the management not to drive this company straight into a river.
Worth a small punt? Maybe. I will sleep on it.
I previously commented on Stanley Gibbons last year pointing out that they had gone on an ill thought out acquisition binge using debt and that NTA's were highly suspect at best - even though several commentators were keen to do the maths assuming that stock was correctly valued (it is not). I buy and sell stamps at auction, the market at the top end is fine, but trying to sell stamps as an alternative investment to non philatelists was always going to end in tears as was the acquisition of multiple auction houses where there is no IP and the brand and value does not transfer on purchase. Poor management, pure and simple, as is so often the case. This has been on my barge pole list for about 3 years despite the hype in the Investors Chronicle. I will stop now, Paul is clearly on the warpath today!
Was just wondering whether you've shorted many on your bargepole-list as you would be a zillionaire by now if you had.
Re TPOP I am a customer and I am fairly impressed despite teething problems it had to begin with. It is unbelievably cheap - I pay £11.99 a month for 6000 minutes, unlimited texts, and 6GB of data. No other phone company can touch that. The downsides are they do not currently offer new phones, only SIM-only contracts, which will limit their customer base. However, there seem to be fewer innovations with new phones so more people (like me) are probably happy with their phone of 2+ years but just want a cheaper contract.
Whether or not it's a good investment is a different Q and I haven't done the research, but I post the above for interest and background on its service. I see the market cap is only £20m now which doesn't sound particularly high if it was growing quickly (which I am not sure it is) but I also don't know what it's profit margins are like given the deals are so cheap. Also, at some stage in the next 2+ years I will probably need/want a new phone at which point I can't continue to TPOP. High customer turnover may therefore be a feature and a problem of their business model.
Details of Stanley Gibbons (LON:SGI) fundraising RNS. Increased to £13m and fully underwritten by Finncap. Some element of rights pre emotion to existing shareholders.
http://www.investegate.co.uk/stanley-gibbons-grp--sgi-/rns/fundraising-and-notice-of-egm/201603140700089191R/
Gus.
MA does appear to be a very talented retailer, but the problem for SPD is that he also appears happy to be self-indulgent and make impulsive decisions. Mostly, it seems, they have paid off for SPD but they could also go very wrong. So there's a double reason for the shares to be at a discount to its peers - the fact that many investors won't invest in a company managed by MA and the fact that the risks of things going wrong are higher. So, the shares are quite likely to fall heavily if there's any hint of disappointment as people try to pass the parcel. A third, more conventional, reason is that it is a bit of a hotchpotch, and it is not clear how successful any successor would be in managing or rationalising the business.
I noticed that an Stanley Gibbons (LON:SGI) director bought £52k worth of shares in April 2015 at 238p. In retrospect, it all looks a bit of a PR exercise.
Having said that, I have occasionally bought on directors purchases, and generally done quite well out of them. I think that part of the key to it is to retain a healthy scepticism about director purchases, and buy into situations which you think are obviously cheap, and where directors show obvious confidence. I'd be looking to something in the region of at least £100k.
.
Sorry Paul I inadvertently gave your rant a thumb down whilst trying to approve its sentiments!
I was reading Terry Smith in a collection of his articles and he alluded to IBM having a 2 billion dollar error on its balance sheet that eluded all other analysts , including possibly those at Berkshire Hathaway that was just becoming IBMs largest shareholder!
Enjoy your weekend
Oh bloody hell, did I really write the above? Yes. It's too late to delete it. Vodka intervened I'm afraid.
Although turning back to the issue of womens' clothing, I do feel that they get more options, in terms of colours, styles, fabrics, etc. Whereas mens clothing is so boring - grey, or blue, and that's pretty much it. Although I am so pleased to be male, in that our shoes are flat, so it's easy to walk.
Compare & contrast that with womens' shoes, which are designed to lift up and tilt them forwards, thus projecting bottoms & boobs outwards, accentuating the curvature, and hence sexual desirability of their profile.
I should probably stop typing now. Alarm bells are beginning to ring.
Regards, Paul.
Hi Paul -
"Compare & contrast that with women's shoes, which are designed to lift up and tilt them forwards, thus projecting bottoms & boobs outwards, accentuating the curvature, and hence sexual desirability of their profile."
Well, if someone can design shoes for men that turn beery stomachs into flat six-packs, firm up the derriere and accentuate the manhood part, believe me I would be first in the queue.
I don't own Stanley Gibbons (LON:SGI) and probably don't intend to any time soon, but the contrarian in me wonders if I am missing a trick.
Clearly problems with the bail out fundraising and massive dilution for the existing shareholders, but at face value there is a £10m market cap company with a dominant market position and IP expertise in stamp and coin collectibles, a definitive global client list and inventory last valued at more than £50m - about 1 1/2 year's turnover. I don't think the Strand property is freehold but worth a closer look.
Not clear from the accounts on what basis the inventory is valued. They have a smallish (£1m) reference portfolio that was last externally appraised in 2011 but I suspect the main inventory is probably valued at cost, i.e. what SGI paid for it, which is presumably the bid side of a market with a pretty wide spread. Presumably the inventory doesn't depreciate over time - it's value is simply a function of what the market will pay for it from time to time. If the current fundraising buys them time to avoid being a forced short term seller there might be significant upside from a steady realisation of assets over time for anyone buying in at the discounted 10p level. My big reservation, apart from the obvious deep doody they're currently in with their debt profile, is the recent resignation of their auditors and the reasons behind this which don't seem to have come out yet.
Not sure I'm brave enough to dip a toe at this point, but interested to watch from the sidelines and see how it plays out.
Gus.
As Paul said before the inventory is small pieces of paper. Do you know anyone who collects stamps any more? Especially I suspect that no one does so under the age of 30.
The inventory could potentially depreciate to zero value over time!
Its the big value stamps that will always be bought as an investment because they are rare, its not really about boys collecting stamps. The value of the big ticket items has dropped because of China, investors there are not buying much now with the problems in the stock market. But they still are selling some, a Penny Red sold for £ 500,000 this week. I don't how much they had that valued at or how much they paid for it. So its hard to say what the inventory is worth.
Hello Gus,
I am a late reading all this but this is a really fascinating one to watch, and I am of a similar opinion. Seems to me the problems are in how the management has handled expansion, debt and cash control, not the two key things people have been saying (1. that people don't want stamps anymore, especially China, and 2. that the inventory is valued by SGI and is therefore probably overstated).
I phoned round stamp dealers a few weeks ago and they were all telling me that Chinese demand was never huge, that the industry itself is in fine health, that the SGI brands are very strong and in their view the problems were more about management cock ups.
What if the inventory IS fairly valued (and by the way no-one doubted this until the share price crashed)? In that case, as you say, there is significant value there. And by its nature it does not spoil or lose value over time (quite the opposite). So I think it is interesting. And incidentally, several bits of the business are doing well.
Having said all that, I agree with many of Paul's points above, and the proof of the pudding seems to be the way they have raised money - really badly done.
Thanks Brackendale
Your analysis on SGI looks spot on. How many boards of directors will do a "Mea Culpa" when they can blame market conditions. SGI have run out of money because:
* they have spent a lot of money on a (so far unsuccessful) development of an online stamp trading platform
* they have gone on an acquisition spree, buying up companies that trade in collectives and antiques and, in the process, running up debts
* buying up large collections of stamps that cannot be sold quickly enough
So are these small bits of paper inherently without worth? Yes, of course. Stamps are only worth what people are willing to pay for them. How different is that from share certificates - inherently worthless except for what people are willing to pay for them plus the future dividend streams that may dry up at any time.
Worth a punt?
* yes, because the underlying market for rare stamps is still there, which makes the assets saleable, though perhaps not quickly
* no, until the large institutional investors develop some cojones and get rid of the board of directors
* not until the share price drops closer to the placing price
I was a naughty boy when I had to do the management accounts in the 1990s - I took a packet of Marlboro Lights into work with me, and bombed a wrap of speed, and before you know it, the mangement accounts were done in a jiffy LOL!!
PP.
.... and I once went down into the warehouse, and started trying on womens clothes!! It was strangely liberating actually. I thought I was a size 12, well forget that! Split seams.14 or more.
Anyway, silver things were in vogue at the time. So I squeezed myself into a boob tube the seams burst, and Kate Bush continued warbling!
Imagine yourself being let loose in a warehouse full of womens clothes! I enjoyed it and tried on a few things. So what?! It was fun!
Cheese! PP,
Prepayments, accruals, you name it!
My motto - continuous improvement. I looked at the old spreadsheets on SuperCalc (DOS based spreadsheet! Anyone remember it?! It was bloody marvellous!
I said this - each month end has to be the same as a year end. I want everything balanced, reconciled to the PENNY! Within an inch of it life! Zero tolerance for errors. Everything is balanced up. I did MANUAL bank reconciliations - cross-ticking thousands of transactions. If you took your eye off the ball, the whole thing fell apart & you had to start again.
So when someone did sloppy work, and didn't take pride in their work, they're out. I only had to sack 2 people, and that was horrible, but it had to be done.
You've got to get the numbers right. FDs who can't even be bothered to check their own numbers, and put out a correction RNS - shame on you! It's pathetic. A £20k accruals clerk would get those figures righ. cross cast them, etc. Some overpaid idiot who is drunk on an LTIP, and not even doing the basics right. Do me a favour. It's pathetic.
Most Directors of UK Listed companies are overpaid buffoons. They're not worth £300k pa plus their VCP, LTIP, or bonuses. Most of them are worth under £100k p.a..
Shareholders need to step up, and kick the managerial class in the nuts, and say - Right. You. Tell me why I shouldn't fire you? Err, well, err, shareholder value, blah blah blah!
The people running listed companies in the Uk are low calibre, and massively overpaid, in my view. Let's start putting a rocket under them. You want a VCP? Umm hmm. Umm hmm. YOU'RE FIRED. GET OUT. Seriously, that's what I would do. You want paying twice, or three times? You want a salary. You want a bonus too? You want to steal 10% of the company from me too with share options? GET OUT! YOU'RE FIRED.
When I worked as a trainee accountant, I always insisted on getting everything down to the last penny. There was another guy who started at roughly the same time as me, and he was willing to let the odd few pennies slip by. Consequently, he was faster than me.
And I think appreciated by the firm more.
Absolute ruthless honesty @paulypilot i have been reading your articals here for 3 years eveyday! And do love it when you dont hold back! Keep up the good work :)
Paul Scott 3 Prisoners 0
Agree with above, when a company is as bad as SGI then hard truth's is the best medicine (especially when management are being paid handsomely to preside over the downfall).
Keep up the good work & have a great weekend all investors.
Paul
When I was writing the above your post stopped at the end of peoples operator.
Your views on this are appreciated.
Paul
I see that Cambian released an RNS this morning saying amongst other things that
"The Board now believes that it is likely that, in light of the ongoing finalisation of costs and the completion of its audit in respect of the financial year ended 31 December 2015, results for the year will be slightly lower than previous guidance. As a result, it is likely that Cambian will not be in compliance with its financial covenants for the period ended 31 December 2015."
This follows on from the guidance (downgrade) issued on 9 February 2016.
Given that profit warnings quite often come along in three's (or more) do you think we have seen the last of bad news from Cambrian.
By the way - I hold shares in the company.
Excellent report today Paul!
IMHO far better being opinionated than having no opinion at all. So please carry on with the no-holds-barred reports, makes for far more interesting reading than the majority of dry, timid drivel turned out by much of the financial press.
Re: Stanley Gibbons (LON:SGI) - I wonder if they own their premises on the Strand - if they do (probably unlikely) it would be worth far more than the stack of useless paper they keep in their vaults.
Thanks Cisk,
I think it's fine to be opinionated, if you've thought things through, and what you're saying actually makes sense.
I don't think there is anything intrinsically good about having an opinionated, but wrong, view on things, and propogating it. Actually, that could be very damaging for a real business, employing people.
So I think we should all be careful before we commit words to the internet.
I've got 5,000 readers per day here, who will (rightly) rip me to shreds if I post rubbish, or make any mistake. As a former FD, I had to scrutinise my own work - I had to do the management accounts, do the VAT returns, everything myself. There was nobody to review it. I had to do the work, and check it, and it had to be 100% right.
If my CEO looked at the figures, and spotted an error, he ripped my balls off, publicly.
Rightly so.
You make damn sure that you get things right next time in that scenario.
Regards, Paul.
Paul, you are exactly right and make a very good point about these businesses we all talk about on a daily basis employing real people, who have families to support.
And it's sometimes hard separating the public persona of a company - often embodied in a colourful CEO - from the rest of the organisation.
For example, I'm no fan of Mike Ashley - obviously the guy has abilities - but if you read the Guardian etc and the stories about the working practices and conditions are to be believed, then clearly not all of the 1000s of employees of his companies are treated as you or I would like to be treated.
Likewise there are CEOs that bend the law, and certainly tweet and comment publicly by saying things that are best ramping, and sometime down right lies. These guys deserve to be called out - they have no business running a public company, and quite often seem to be in it purely to separate shareholders from their cash. Anyone reading this will know these types, just by reading a few of Tom Winnifrith's postings.
And then there are CEOs who do break the law, and ultimately bring down the company, and everyone loses (apart from them). Everyone hates a full-scale loss on their investments, but like a would that heals, you recover from them but there's still a scar there, serving as a reminder to avoid that particular kind of company / CEO in the future.
So now I try and steer well away from any CEO type who falls into any of the aforementioned, as there are better places to invest.
I've rambled enough and forgotten the point I was making. Your comments about the warehouse and ladies clothing did bring a smile to my face this morning...
Hi Cisk,
I think a lot of the criticism of Mike Ashley and SPD is well-deserved (I am heavily long of SPD, despite him being basically an appalling loose cannon - but he's also a brilliant nuts & bolts retailer, and it pays to back people like that, long term). Although being obese, and very stressed (him, not me!) , does make you wonder how long he'll be around for? Pot & kettle, but I don't like investing in companies with very unhealthy-looking key people. I recall back in the 1990s, my chain-smoking, obese payroll manager, who was permanently irate - I looked at him and thought to myself, you're a heart attack waiting to happen. So I recruited a deputy with enough skill to take over if the worst thing happened. Just in the nick of time. 3 months later, he had a heart attack. Fully recovered now thank goodness. The HR woman came to me some time later, and said about docking his pay - how callous! I totally ignored everything she said - I paid him full salary for 6 months until he got back on his feet. That's the beauty of controlling the IT - especially the banking software - I decide who gets paid what. People soon get that, and fall into line. People can send me emails and memos, but I've always regarded them as no more than advisory. I control the money, and I decide what happens. It's always well thought through. So people back off. Anyway, enough reminiscing, down memory lane.
But some of it is nonsense. The Guardian has an agenda. They made a big issue about bag searches for warehouse staff. It's a standard procedure, which is necessary because if you DON'T do bag searches, the warehouse staff nick the stock!
Only a Guardian reader would think that the virtuous warehouse staff have angelic morals, and the very idea of searching their bag when leaving the premises is an appalling invasion of privacy.
The same Guardian readers I might add, who are stuffing their own handbags full of stolen stationery, that they're nicking from their own employer - the Council - whilst knocking off at 3pm on a Friday afternoon on flexitime, and looking forward to final salary pension scheme that the rest of us who pay for it, can only dream of.
Bottom line, SPD has an amazing bonus scheme for the key drivers of profits - store managers. They have been paid massive bonuses, and good for Ashley for doing this.
Anyway, there we go.
PP.