Small Cap Value Report (16 Jan 2017) - WAND, VLK, REDS, TAX, MBH, SQS, ASHM, OMI

Good morning!
Today there will be one report. I'm (Paul) writing most of it, but Graham is likely to add a couple more sections later this afternoon. We often add more sections in the afternoon & evenings, so it's worth checking the previous day's report to see if there's anything that you've missed. The quickest way to do that is to bookmark the SCVR landing page, then glance down at the tickers, in the blue boxes, to see if any are of interest.
There's been more fun & games with forex over the weekend. I see that sterling briefly dipped below $1.20 first thing. Now that the uncertainty is out of the way over hard Brexit, it wouldn't surprise me to see sterling rally somewhat. Once people have certainty, they can plan accordingly. It's uncertainty that markets dislike the most.
Anyway, we're used to the drill by now. Weak sterling is good for the FTSE100, good for exporters & UK companies with overseas earnings. It's bad for importers. So as long as our portfolios reflect this, then we should be doing well. Also of course all the UK indices are at or near new highs, so everyone should be doing well. How long that will carry on for, who knows? It does all feel a bit toppy to me, but as long as companies are reporting positive trading updates, then I'm happy to run with them.
WANdisco (LON:WAND)
Share price: 269p (up 20% today)
No. shares: 35.1m
Market cap: £94.4m
(at the time of writing, I hold a long position in this share)
Trading update - this former glamour tech stock has had a rough couple of years. That's because top line growth stalled, and heavy losses made it look as if the writing was on the wall. However, perhaps surprisingly, investors continued to pour money into it, in several fundraisings. Overheads were cut considerably last year.
So, as I mentioned in my last report (Oct 2016), the key to survival is to start generating some decent top line growth. Today's update delivers strong growth. It's the first genuinely positive statement I can remember from this company. Hence why I've dipped my toe in, with a smallish very speculative purchase this morning. If the facts change, I change my mind. Mind you, I can never really be sure with this company what are facts, and what is spin!
Given the false dawns in the past, I can understand most people being highly sceptical, and wanting more confirmation that things really have turned a corner.
There's lots of detail in today's announcement, but it all seems to read positively, with meaningful growth, and reduced cash burn;
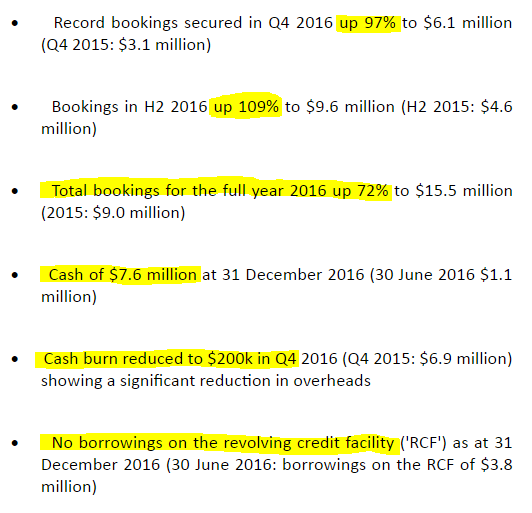
A couple of comments on the above;
Sales bookings were up 36% in H1, so the rise to +109% in H2 is a big sequential improvement in growth.
Revenue seems to lag behind bookings, so that's important to factor into forecasts.
Cash burn - it seems to have burned about $4m cash in H2, by my calculations (net debt of $2.8m at 30 Jun 2016, plus $14.3m new equity funding net of fees, less closing net cash of $7.6m at 31 Dec 2016 = $3.9m cash burn). I hope that's right - it's not clear from today's RNS if the $7.6m is net or gross cash.
Q4 was close to cash breakeven, but I am told this is the best quarter for cash collection, so may not be typical of future cash burn.
Outlook comments - as follows;
Strong order book and sales pipeline continues to underpin medium term growth expectations...
We have begun 2017 with a strong new business pipeline and a significantly reduced cost base, which together, will further our progress towards profitability.
So it's still loss-making, albeit at a reduced level. I'm usually wary of companies that refer to the medium term being positive, as it hints that the short term isn't so good!
My opinion - historic performance has been lamentable, and I was convinced this company was heading for the knackers yard. However, deep cost-cutting last year, and very strong top line growth in H2 2016 have dramatically improved the outlook, in my view.
I imagine another fundraising will be needed at some point, but that's not a problem once the share price is roaring up, and good news is flowing.
This share has been a big tech favourite in the past, and I suspect it might become so again, if the positive newsflow keeps coming.
It's clearly only of interest to growth investors. Value investors will understandably shudder in horror that a serial under-performer, and cash burner like this is valued at nearly £100m.
However, the big name contract wins & positive sales momentum developing now are exactly what tech growth investors look for. They can chase up valuations to eye-watering levels in this kind of market. That's why it's starting to look interesting, in my view.
Obviously if the sales momentum konks out, then the share price would crash back down again. So it all hinges on whether that decent growth reported today can be maintained, or not. So a high risk, but potentially interesting situation, in my view.
Vislink (LON:VLK)
Share price: 16p (down 7.9% today)
No. shares: 124.6m
Market cap: £19.9m
Update on proposed disposal - this is a very concerning announcement, which would make the share an instant sell for me, if I held any.
It looks to me as if the buyer of Vislink's legacy business hasn't got enough cash to complete the deal. Instead of paying $16m in one go, it has now renegotiated terms to pay $6.5m up-front, and the $9.5m balance 45 days later.
The buyer, called xG, is issuing secured loan notes to Vislink, which are secured on the business being disposed of. So I suppose if xG were to default, then Vislink could recover the disposed of business, and presumably keep the $6.5m initial payment?
I've done a bit of digging on xG, and it turns out to be a tiny (only $16m mkt cap) NASDAQ listed company. It raised $10m to part-fund the Vislink acquisition recently. I've had a look at xG's financials, and they're diabolical. It's been heavily loss-making, and seems to be a blue sky type of company, with negligible sales.
Overall then, I would not be confident that this deal will actually complete. Vislink has been reassured that the initial $6.5m is in transit, but who knows?
It all looks pretty dodgy to me, and I would treat Vislink as a bargepole job, as if this deal doesn't complete, then Vislink is in a dire position itself due to excessive bank debt run up by the idiot in charge (Hawkins), who has run this company into the ground.
Very high risk. This looks potentially very bad to me. Why take the risk, when you don't have to? My main question is, where does xG expect to get the rest of the dosh from? It doesn't seem to have the cash on hand to redeem the loan notes. It might all turn out fine, but serious questions need to be asked about what's going on, and how likely this deal is to actually complete.
Mello Beckenham
Due to issues with trains, etc, the monthly investor evening in Beckenham tonight has been cancelled. I know a lot of regulars read this report, so just wanted to make sure that everyone got the message & don't have a wasted journey.
Tax Systems (LON:TAX)
Share price: 67p (down 5.0% today)
No. shares: 76.0m
Market cap: £50.9m
Trading update - for the year ended 31 Dec 2016. Funnily enough, this company cropped up yesterday, when I was doing some research to familiarise myself with new issues. This share joined AIM in July 2016, reversing into a shell which you might remember - the failed Eco City Vehicles business.
MXC Capital were behind this deal, and still hold 20%. Given their actions at Redcentric (selling out just before accounting misstatements were announced), I would watch very carefully indeed for any RNSs showing them selling their TAX shares!
There are some interesting shrewdies on the shareholder list, namely Nigel Wray at 7.1%, Henderson at 16.8%, Harwood Capital (Christopher Mills's outfit), and Hargreave Hale at 5.8%. Those (and other) concentrated holdings could make the share illiquid.
The new business is a profitable software company - providing corporation tax software to accountants. I am told by a friend who is a tax professional, that the software is excellent, and that revenues are likely to be very sticky.
Today's trading update is in line;
The Company has performed as budgeted at the time of re-admission to AIM in July 2016 ("Admission") and trading and net debt for the year ended 31 December 2016 are in line with market expectations.
Since Admission, the Company has strengthened its management team with a number of new appointments to drive organic and acquisitive growth while supporting the Company's valued existing customer base.
Interim results to 30 Jun 2016 are no use, as that pre-dates the acquisition & fundraising.
There's a more useful announcement here, issued on 1 July 2016, which explains the acquisition of Tax Computer Systems Ltd, which is the business which was reversed into the cash shell.
My main concern is that a considerable amount of debt was used to part-fund the acquisition. £45m was raised in an equity fundraising, but another £30m in debt has been used to fund the £73m enterprise value of the acquisition (the £2m balance probably being fees).
New debt facilities of £30 million comprising £9 million term loan and £11 million revolving credit facility with HSBC Bank plc in addition to £10 million unsecured loan notes issued to the Business Growth Fund plc
So the danger is that investors might buy this share on the basis of an apparently reasonable forward PER, without realising that there's also a big pile of debt that, at some point, will have to be repaid.
My opinion - it's a nicely profitable niche, but I don't see much room for growth. Personally I prefer companies with a very big potential market, giving scope for considerable growth. Sure, this company could diversify, and also move into complementary areas, but that often ends in disaster.
I think it would make sense to wait for the full 2016 results, to get a proper handle on the figures. The other issue is how much development spend is being capitalised? I note the company likes to talk about EBITDA, as many software companies do, but of course that is a meaningless number because it ignores development spending (both cash cost, and amortisation).
The high level of debt might limit the dividend yield. This type of business would only interest me if it were largely debt-free, and paying a c.5% dividend yield. So it's not for me, but I'll review the 2016 figures anyway when they're published. As always, I reserve the right to change my mind, if the figures subsequently appeal to me.
As a general point, it's good to see some better quality companies floating on AIM. Maybe the broker community is finally grasping that many investors actually want profitable, dividend paying companies to invest in, not speculative trash. That is particularly true of AIM IHT portfolios, which are blossoming due to the excellent tax relief available.
Michelmersh Brick Holdings (LON:MBH)
Share price: 50p (up 1% today)
No. shares: 81.5m
Market cap: £40.8m
Trading update & property disposal - there's no change in the guidance for this brick maker, and property owner;
In October 2016, the Group announced that it expected its financial performance for 2016 to be at or around a similar level to that reported for the full year 2015 and the Board confirms that expectation.
Cash generation was particularly pleasing with year-end cash balances exceeding forecast.
There's also more cash in the pipeline, since a surplus property is being disposed of for £2.68m. That will generate a surplus over book value (after all costs) of over £1m. Whilst that's not a huge amount, it's a nice bonus. I wonder if there are other property assets in the books at below market value?
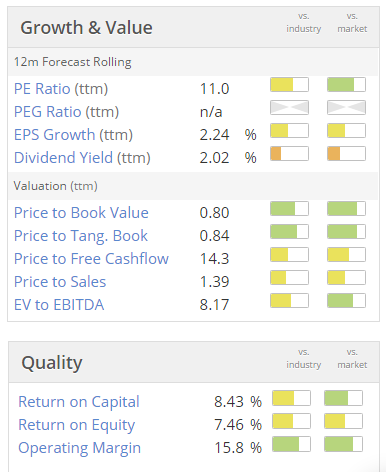
Valuation - looks probably about right to me:
Redstoneconnect (LON:REDS)
Share price: 1.65p (up 15.8% today)
No. shares: 1,633.2 (taken from RNS dated 29 Apr 2016)
Market cap: £26.9m
(at the time of writing, I hold a long position in this share)
Contract to deliver in-building cellular - I don't normally comment on contract wins, as so many of this type of announcement is spurious. However, this looks quite interesting.
Reading between the lines, it sounds as if the client might be Google's new London HQ, a campus being built near King's Cross station. You can't really get a better reference site than that. Therefore, this contract could be a catalyst to enable REDS to win much more business.
As everyone is using smartphones these days, having top notch In-building mobile phone signals is becoming increasingly important. So I can clearly see how this could become a big market. So I like the potential for this.
Regular readers here will know that I visited this company late last year, and was impressed with new management. I try not to buy immediately after meetings, because it's too easy to get swept up in the moment. It's usually better to have a cooling off period, and consider it more carefully, taking one's time.
The strategy seems much more clear, and they have already got some high quality relationships with blue chip clients. So cross-selling is a real possibility. The company also has some potentially interesting in-house developed software for managing hot-desking.
All in all, I think this share is potentially interesting, and hence have dipped my toe in with a small opening long position. I'll wait to see what the next set of results are like before deciding whether to fully commit to it, or not.
A couple of quickies to round off.
SQS Software Quality Systems AG (LON:SQS) - trading update for Dec 2016 year end. Profit is in line with expectations.
Outlook comments sound encouraging though, with news of some big new orders.
Year end net debt looks reasonable, at E12m.
I don't understand this company, but a quick review of the numbers on Stockopedia suggests to me that this may well be worth a closer look. The company seems to have a good track record of earnings growth. The valuation looks reasonable too, and it pays a divi. Not bad at all, given the upbeat outlook comments today. Have any readers looked at this company?
That's me done for the day.
I will now hand over to Graham, who may want to add some additional sections below.
Regards, Paul.
Graham here with two quick comments:
Ashmore (LON:ASHM)
Share price: 302p (+6.6%)
No. shares: 713m
Market cap: £2,010m
This is a lot bigger than we usually cover in SCVR, but I'm covering it for two reasons:
1) Financials are a sector I'm particularly comfortable with;
2) Trends at the fund management companies can tell us a lot about broader financial and economic trends.
With that out of the way, here is today's RNS:
Trading Statement - Second Quarter Assets under Management
I'll tag today's numbers onto a table I previously created to show the recent trend here:
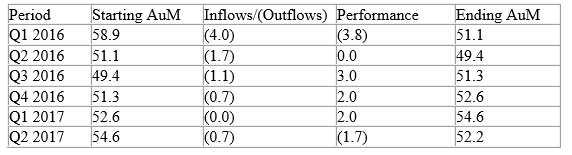
Despite lower market levels, Ashmore's investment performance relative to benchmarks remained very strong throughout the quarter across all fixed income and equities investment themes.
During these times of increased indexing, outperforming benchmarks has never been so important.
And then, after mentioning various problems during Q2 (strong dollar, US election, steepening yield curve):
While these factors interrupted the improvement in sentiment towards Emerging Markets, the effect proved to be short-lived with asset prices strengthening in December and continuing into the new year. The combination of attractive absolute and relative returns, accelerating GDP growth, and low allocations all support the expectation of further strong performance in 2017 and a return to the improving flow trend seen for most of 2016.
So it sounds like the CEO thinks we could get another 5%+ growth in AuM during this calendar year, up again from the low reached 12 months ago.
They aren't "exciting", but I like fund management companies as a sector because a) they generate a lot of cash (and the Ashmore dividend yield is currently about 5.9%); b) their customers can be surprisingly "sticky", and c) they are capital-light.
Counter-balancing that, they can be cyclical, and subject to macro trends beyond their control.
Ashmore is a prime example of this - it cannot do anything to determine overall emerging market and currency performance, but these factors will have a big impact on its results. The only thing Ashmore can do is try to beat its benchmarks (at the last results, it was disclosed that 73% of funds under management were beating benchmark over 5 years).
So I remain interested in Ashmore. This is the sort of stock I might put in a sleepy retirement portfolio, for income (though I don't currently have a position).
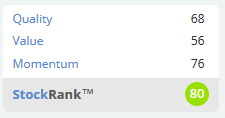
Stockopedia Stockranks are fairly positive on it at the moment, too. It could be worth researching in greater detail.
Orosur Mining Inc (LON:OMI)
Share price: 16.75p (+9%)
No. shares: 100m
Market cap: £17m
From the very large to the rather small, this South American gold miner had an update I'll briefly mention:
I very rarely look at this sector these days. The original reason I noticed Orosur was due to an extraordinary cash flow multiple.
My impression has been that this company is extraordinarily well run, relative to the sector. It has tightly controlled costs, decent margins (cash operating costs of $914/oz) and very clear forward guidance from management, which is usually achieved.
Multiples remain attractive today with $8 million in net cash generated from operations.
I have not had a position here for some time, however, since I came to the conclusion that the company would not fulfill the pledge made several years ago to commence the payment of dividends.
While the company's operational performance has been very good, I remain secure in my belief that significant dividends will not be forthcoming for the foreseeable future. $7 million of cash was used in investing activities during the latest quarter, as it explores and begins work on new mines, and extends the life of old mines, where resources will not last forever. Unfortunately, it does not keep investors up-to-date with total resources, which for me is the most important number.
So it's an interesting speculative share and a decent company against its peers in the sector, but I think there is a risk that the mine life is not long enough, and so therefore a very strong risk that dividends will not be sufficient to make this a successful investment (for buy-and-hold investors).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
I notice WANdisco (LON:WAND) is up 33% today on no news.
Have held SQS for a number of yrs - approximately 15% of rev's are UK generated, 55% of rev's are Euro denominated. Co is focusing on US expansion with 2 recent acquisitions, early days but signs are positive. They are conservatively managed (German) & modestly rated, 14.7x for FY17, brokers are bullish, most recent - Singer 865p, Panmure 771p. Always been a little bit off the radar but worth a look imo.
As I just said to smallcappy:
I really don't understand the fall in share price following the full year results. What's happening to SQS Software Quality Systems AG (LON:SQS) ?
I have no position, but this looks like a buy to me.
Absolutely but criticising every move just grinds my gears that's all. Needed to get it off my chest. As an aside to this I'm a youngish 'investor'/'gambler'. Never read a book just a few forums. Couldn't tell you what a company does that I Invest in most of the time let alone it's PEG, PE RATIO or its net gearing etc. Not a Danny la rue. never read a rns, annual report or anything else. I'm 9 years or so into my first real investment life (relative pennies to most of you guys I'm sure) but have returned over 9% p.a. To date. I have no rhyme nor reason to shares I buy. I've never sold as the shares will be for the kids if they behave themselves but only when I'm gone. Lucky maybe in a rising market but I think I'm proof that investing doesn't need to be difficult or as complicated as people like to make out. No one knows what'll happen tomorrow so I see little point in guessing. Far better things to do although being out of work i should probably be doing more than watching the racing ( I don't sign on before anyone asks or take benefits )! Keep up the good work.
Re Ashmore I much prefer a relative tiddler Impax Asset Management (LON:IPX) , cheaper on many metrics but more importantly growing AUM rapidly 12% in the last quarter http://www.investegate.co.uk/impax-asset-mngmnt--ipx-/rns/aum-update/201701100700087292T/ in an interesting sector ,
Thx for the supplementary commentary
Ashmore (LON:ASHM) had roughly twice the ROCE and ROE in September 2013 compared with today (I have just checked the history on Stockopedia). Why has it reduced so much? The total share numbers are about the same.
It always amazes me that people criticise this blog because they think it's the writers prerogative to reason everything they do and say. Imagine spending your own time writing something for nowt day in day out. Beggars belief.
Hi ds,
Thanks, but I do get paid a modest fee for writing these articles. Mind you, I mainly do it because it's enjoyable, and mentally stimulating. Also because writing down & publishing my thoughts about shares & thus opening them up to public scrutiny, really makes me think a lot harder about everything. Plus the reader comments are invaluable at filling in the gaps, and sometimes making me change my mind.
So it's all good! Even better now I have Graham helping out too, sharing some of the workload & letting me have guilt-free duvet days most Fridays :-)
Regards, Paul.
I looked at Tax Systems (LON:TAX) in August. They make AlphaTax, which seems to be more or less a standard at larger accountancy firms. My wife used to work in one and used AlphaTax daily. She said it's pretty good. Big companies don't use e.g. Sage because you can't trace where a calculation has gone wrong, or deal with more complex situations.
My notes from August show 90% recurring revenue, which tallies with what my wife told me: that they get software updates every year to cope with the latest changes in the UK tax code. I was concerned that revenue growth looked to have stalled over the preceding 3 years, which suggested to me that everyone who was likely to buy it already had. Another yellow flag was: admin staff when from 4 to 7 in 2015, but support and development staff (presumably programmers) and - crucially - sales staff reduced over the prior 3 years. Again, that felt to me like a mature company with not much growth left in it. Like you, Paul, I didn't like the capital structure (debt, warrants and deferred shares).
The only bright spot I could see was the involvement of Gavin Lyons (formerly Accumuli, which was sold to NCC) coming on board. He seems to have a buy-and-build track record, but I noted at the time that his options on 3% didn't feel like much skin in the game.
I don't hold.
Paul,
I am quite bullish on WAND, I bought a decent position when you called it a dog that needs to be put down and the SP dropped below 100p. I believed and still do that their products for big data is head and body above the rest.
TAX, bought in last week in anticipation of better than expected statement but was quite disappointed with the rns. Again I think their products are very good, the fundamentals look compelling to me, low per, high recurring revenue of 90%, customer retainment of 95%, and profit margin of over 50%. Also the business growth fund, the guys behind VCP STY SAT have 10 million quid invested.
Good update from RhythmOne (LON:RTHM) today and up 9% on the day (used to be called Blinkx until Sheriff Edelman blew the whistle on it,,,, much water under that bridge and the road to redemption)
this is almost a 3 bagger for me so far but reckon it has a way to run yet, I still reckon it makes a good takeover candidate
Hi ricky65,
Maybe you should ask him to write some sort of explanation for his views on stocks. Something that includes trading updates, links to previous things he's written, discussion of cash burn, revenue recognition, future outlook followed up with a clear opinion.
Perhaps some sort of daily small cap value report or something? I mean, he owes us that much...
Warmly,
J
WAND: Peeps need to be very aware that bookings figures can be very deceptive. A company that books a 3 yr contract for $3m earns a $1m per year. A company that books £10m contract over 5 years only earns $2m per year. Given WAND product great care needs to be taken on relating bookings and revenue without sufficient detail.
So in October Paul thought WANdisco was a bargepole and in January, just 3 months later, he likes it enough to take a long position. Am I the only one who thinks that such a big change in sentiment comes across as fickle?
So in October Paul thought WANdisco was a bargepole and in January, just 3 months later, he likes it enough to take a long position. Am I the only one who thinks that such a big change in sentiment comes across as fickle?
No, it comes across as being flexible which all good investors need to be IMHO. When the facts change so should your opinion of any investment. Paul made it quite clear that he has taken a small speculative position only. What's the problem with that?
All the best, Si
Good reply,
If the person who made the 'fickle' comment reads this please take this idea into consideration. You are unlikely ever to make consistent profits in the stockmarket if you follow other peoples' opinions. 'Stockopedia' provides tools to make your own judgement..
That would depend on what features caused it to be bargepoled and whether those features have changed in this update.
"So in October Paul thought WANdisco was a bargepole and in January, just 3 months later, he likes it enough to take a long position. Am I the only one who thinks that such a big change in sentiment comes across as fickle?"
Stick around for long enough and you will discover Paul trades in and out of shares all of the time. Judging by his fantasy portfolio it works for him but for us mortals it may not be as profitable. Whether buying WAN meets with his New Year plan to keep away from low-StockRank/speculative stocks is difficult to say. It's all very confusing -- these days the SCVRs read more like SCGRs.
Judging by his fantasy portfolio it works for him but for us mortals it may not be as profitable. Whether buying WAN meets with his New Year plan to keep away from low-StockRank/speculative stocks is difficult to say. It's all very confusing -- these days the SCVRs read more like SCGRs.
The investment in WAN aside, what other companies was Paul meant to write about today? I looked at the RNS at 7am this morning and was back asleep by 7.05. Nothing of interest whatsoever in terms of small cap GARP and Value shares. Does Paul simply not write a report on such days?
Personally, I'm always interested to read Paul's thoughts even if he discusses and invests in companies I would not touch even if we all joined our bargepoles together!!
All the best, Si
I would have suggested the Small Cap Momentum Report :)
Also, I think there also has to be a certain irony that the stocks that Paul holds/held that are perceived to be value in his portfolio (SpaceAndPeople, Fairpoint, French Connection, etc) are those that have probably held back his performance if anything!
Hi Tabhair,
Also, I think there also has to be a certain irony that the stocks that Paul holds/held that are perceived to be value in his portfolio (SpaceAndPeople, Fairpoint, French Connection, etc) are those that have probably held back his performance if anything!
Exactly! Standard value investing really hasn't worked at all well in the last few years. In most cases, when you search for low PER, high yielding stocks, you usually end up buying something rubbish, which then goes on to disappoint repeatedly. So it wasn't actually "value" at all. It was a business in decline, and the forecasts were too optimistic.
I'm only interested in making money from the market, not rigidly sticking to a strategy that isn't working! Hence why I'm currently putting much more emphasis on growth stocks. As we've seen with Boohoo.Com (LON:BOO) and G4M, these have been fantastically profitable investments (both 5-baggers to date). I'm delighted that many readers of this column have enjoyed the big gains from these stocks which I flagged up here.
The trick has been to spot shares which are on track to beat market expectations on growth & earnings. This has led to enormous share price rises - from the double benefit of rapidly rising earnings (above forecasts, repeatedly), and expansion of the PE rating too. A beautiful combination!
When the current bull market tops out, I'll ditch my growth stocks, and move into cash.
Then when the next bear market bottoms out, I'll go value hunting again.
In my view, it's good to be flexible in your approach, if you want to maximise your portfolio returns in various market conditions. Right now, the market is going crazy for decent growth companies, with big potential upside. So that's what I'm focusing on, and it's working rather well! (for now, anyway).
I appreciate that WAND is more speculative than anything else I've gone for, and usually I wouldn't touch a loss-making company. However, as explained in the article, the big increase in bookings, and the big name clients, suggest to me that this could now be a good turnaround. Time will tell! It raised money quite easily last time, so that tells me the Instis buy the story. So it should be able to raise more money fairly easily again in 2017.
I think everyone secretly likes to have a little excitement in their portfolios, and why not, if you pick sensibly?!
Regards, Paul.
ricky65,
I changed my view on WANdisco (LON:WAND) today because the company's fundamentals have changed dramatically for the better. I explained why in the article.
My stance on shares has nothing whatsoever to do with "sentiment". I base my opinions on facts, figures, and outlook. So when those dramatically improve, then my stance on the share will also change.
Hope that clarifies.
Paul.
Fair enough. I can see the appeal to short term traders (I note the chart breakout). Personally I don't see this succeeding long term. I don't see it turning a profit; its going to take a lot more than a breakeven Q4. WAND has been a serial disappointer for 5 years so I think it's odds on that it will continue to disappoint. Having said that I wish you and all holders good luck!
Hi ricky65,
I think WANdisco (LON:WAND) is displaying signs that it might have turned - the chart (which of course measures market sentiment) is looking positive now. The fundamentals (as reported today) are improving considerably (although it's still loss-making & cash-burning).
So personally my approach with this is to take a long position now, and see how things develop. It's in an up-trend now, on improving fundamentals, so I'm going to just run with it now, for the foreseeable future. If the fundamentals and/or the chart break down, then I'll ditch it.
So it could be a short term, or a long term holding, depending on how things develop.
I don't see any significant risk of it going bust now. Whereas people buying sub 100p were just gambling that it would be able to survive, despite appalling fundamentals. I think it's a much more sensible proposition now, for growth investors, not value investors.
Just to emphasise, it's only 2% of my fantasy portfolio, and my real portfolio. So not a conviction buy, more a speculative starting position.
Regards, Paul.
Paul, thank you for the replies. It makes more sense to me now. I can see the advantage of being fluid in one's opinion on a stock rather than rigidly sticking to one position. As you said, I think most of us secretly like a little speculative excitement. You've warmed me to it - who's to say it couldn't go on a great run back up to 1500p for a 5-bagger? I hope I didn't offend using the word "fickle" in my original comment. I think I misunderstood your idea of a bargepole stock as "never investable".
Hi Ricky,
Thanks for your reply. No offence taken!
Just to reinforce the point, my views on all stocks are based on all the information I have to hand about that company, at that particular point in time.
So when new information comes out (especially trading updates and results statements) that significantly changes the outlook for a company, then I change my view on it.
Based on its historic figures, WAND was a total crock. Very much a bargepole stock that looked like it would go bust when investors tired of pumping cash into it.
However, it looks as if things are changing now, based on today's update. I take the point of another reader above, that sales bookings will be higher than actual revenues. Nonetheless, WAND is at least starting to look like it could become viable. Indeed, if revenues are entering a strong period of growth, then it could become highly profitable, who knows?
Therefore, my stance on it has changed. It's no longer a bargepole stock, due to the positive update today, and the likelihood that it will be able to raise a bit more cash to make it to breakeven possibly?
I'll ask my broker to send me the updated broker notes.
Still speculative, and the market cap is very high in the short term. It's been a dismal performer in the past, so a degree of caution is needed, I think.
Regards, Paul.
Referring to purpleski's original post he refers to our top ten exports relying on importing goods that become part of the product then exported. The fall in the pound will remain of great advantage in these cases and should provide additional profit margin. That will perhaps be eroded in due course by additional wages and other costs but the overall effect should remain beneficial.
Depreciation also means that we're importing inflation. Eg the UK imports approx. 40% of its food from overseas. A 30% increase in imported foodstuffs is a material cost and hits the poorest hardest.
The "poorest" in the UK now have amongst the highest living standards of the "poorest" anywhere in the world and at any time in history.
Those who choose to be permanently unemployed will have standards of living considerably above those of working people in many countries in the world and above what the average worker here enjoyed a century ago in our own country.
Looking forward, once we have burnt all the gas that's near to hand and allowed the world population to swell by a billion or 2 more, both food and energy costs will go up substantially. Incidentally, the government is borrowing irresponsibly to pay existing bills, so making it more difficult in the future.
It's not going to get any easier unless people work hard and we haver smart economic policies.
Those policies need to encourage work, investment and our own wealth creation. So you need low taxes and some kind of income gradient to actually reward work & enterprise.
Right now, there is so much taxation & welfare, many of our jobs are filled by incomers, whilst others intend to remain on the dole.
Since we are already running a large balance of trade deficit, the economy seems not to be competitive. Hence devaluations.
Transferring more money to those who are not helping the economy to be competitive is really not going to solve the problem.
I notice that Vislink (LON:VLK) has an average ROCE of -4.4%. So Paul's point that this has been managed poorly is well-taken.
I found today's trading update from Michelmersh Brick Holdings (LON:MBH) very poorly written as it was not clear whether the reiteration of the October guidance for a similar to 2015 financial performance was after taking account of the write-up on the Chesham site or not.
Nevertheless, I hold the stock and think it is cheap on the basis of: 1) prospect of higher dividends, based on strong cashflow and net cash position; 2) fall in sterling leading to reduction in competiveness for Belgian and Dutch imports; 3) despite no improvement in pricing in H2 2017, which led to the October profit warning by Michelmersh, both Forterra (LON:FORT) and Ibstock (LON:IBST) have made fairly upbeat statements in the last few days about declining inventories among stockists; 4) valuation below book value; 5) government wants to encourage housebuilding which should support medium-term demand.
I must admit I found this statement confusing, I don't understand why they report a 'falling output' when there is supposed to be a housing shortage? Either they are not a preferred supplier or the pent up demand in house building hasn't really materialised yet?
They also commented back in July it was a 'flat market'
Although they do comment the order book 'remains strong 5% ahead of last year'.
It seems relatively stable, though maybe this is for the longer term?
Sean
Minor whinge: it would be so much more helpful if posters would say which share they're talking about rather than refer to a post 2 pages earlier, especially in a 'cold' thread.
Thanks
Purpleski & Graham,
I'm pleased you're enjoying the morning notes from Mark Brumby at Langton Capital.
I also very much enjoy them, and they're incredibly useful too - I've made good money from his smart & expert guidance on the leisure & pubs sector.
Here is the link again, for anyone else who wants to sign up to his daily email morning note.
They're often hilarious too, as well as informative. Who says financial stuff has to be dull?!
http://www.langtoncapital.co.uk/daily-notes/
Regards, Paul.
Gattaca (LON:GATC) is up nicely today on v large volume so perhaps a large buyer there. I don't know if anyone is aware of any wider recruitment news out today? (I know the SCVR doesn't comment on daily swings in prices).
Last Friday the Telegraph reported positive comments on the employment outlook from Michael Saunders, an external member of the BoE Monetary Policy Committee. See
http://www.telegraph.co.uk/business/2017/01/13/britains-jobs-market-stay-strong-2017-bank-england-expert-says/
I see some recruiters Staffline (LON:STAF) and Gattaca (LON:GATC) are well up today, 7% and 13% respectfully. I presume this is to do with the Michael Saunders report?
Gattaca (LON:GATC) is up nicely today on v large volume so perhaps a large buyer there. I don't know if anyone is aware of any wider recruitment news out today? (I know the SCVR doesn't comment on daily swings in prices).
Yes, very large volume today compared to the 3 month daily average but Empresaria (LON:EMR) and Staffline (LON:STAF) are also up nicely today so seems part of a slight rebound in recruitment stocks. Obviously nothing to do with me backing up a transit van to pick up some Gattaca (LON:GATC) last week at 271p :)
All the best, Si
Gattaca (LON:GATC) was tipped in a couple of places over the last two days. The 24-hour charty people have also come out today saying it has hit an uptrend. No complaints here!
Paul
#SQS smashing little company. I have held shares for donkeys years. Not planning on selling any time soon.
Best
SC
I really don't understand the fall in share price following the full year results. What's happening to SQS Software Quality Systems AG (LON:SQS) ?
I have no position, but this looks like a buy to me.
'afternoon Paul,I second thanks for the Link to Mark Brumby's newsletter,it is very good.
I don't agree with you that the fall in sterling is primarily about uncertainty Paul. At the beginning of July 2014 sterling was at 1.71 dollars to the pound. That was when Cameron first set out the objectives of his renegotiation process with the EU. Since then the greater the certainty of a greater separation from the EU the greater the fall in sterling, so it is now 30% lower.
The uncertainty over the degree of separation - in effect the hope that we may retain some degree of inclusion in the single market or at least the customs union - is what has slowed the fall, not what has caused it. Bottom line is the currency market thinks the UK is worth a third less outside the EU than it is within it. The market might be wrong but that's the view of the market and there's no hiding from it.
Hi HotSocks,
A depreciation in the exchange rate is a beneficial thing, in that it enables a country which has become uncompetitive, to become competitive again. The price we have to pay is a burst of higher inflation of course, just like happened in 2008.
In the past, countries have tried to competitively devalue, in order to stimulate their export industries.
So for me, the exchange rate is doing exactly what it should be doing - bolstering the UK's competitiveness just at the exact time we need it. This causes problems for some companies (importers), but great opportunities for others. It also means that businesses worried about Brexit are far more likely to stay in the UK, as their UK cost base just got a whole lot cheaper.
Anyway, there's not a lot we can do about it! As investors we just have to adapt to whatever prevailing economic conditions are.
Regards, Paul.
I'm clearly in a very grumpy mood today Paul as I'm about to disagree with you again. Depreciation means we just dropped our prices by 30%. That has some beneficial effects but its not necessarily overall "a beneficial thing".
Like you say though, as investors we just try and make money out of whatever reality is. Other people can wear themselves out with the thankless task of trying to change it. So 100% agree with you there!!
As many UK companies operate in a global supply chain it is increasingly difficult to use currency as a benefit. Small changes work. but larger changes do result in significant price variances that suppliers cannot support. As you say in your write up businesses do not like uncertainty. Which is why more B2B transactions are being written in non UK currencies. Mainly US$. This is particularly true of exporters who sell in $ and need to know that their supply chain will not increase prices within planning periods. I have no idea as to what % change is ongoing but working in electronics and It I have noticed more and more business moving to a US$ contract. Absolutely a pre-Brexit effect but IMHO increasing.
I run a small import business, we bring in various items from the Far East, and £/$ has obviously been a headache recently. Luckily, quite a few of our largest clients (7 out of our top 10) pay us in $, because over the last 5 years they have wanted to make the relationship more 'lean' and one of the ways for us to give them a better price was for them to take the currency risk and us to take a bit less margin.
Last year (and right now) I'm having quite a few meetings where a buyer asks me to explain why none of their other (domestic) suppliers are putting their prices up, but we are 'putting ours up by over 15%'. It doesn't tend to go down particularly well when I explain that their predecessor in the role wanted to take on the currency risk and actually we're keeping our ($) prices the same this year...
I think generally, buyers have become increasingly greedy/pressured into eating away at margin every year, which leaves them no contingency when events go the wrong way.
Aside from that though, we're actually looking at it fairly positively. Yes, prices will go up, but they haven't gone up much at all for years (lots of our large clients actually paid less (for pre-Brexit orders) in 2016 than 2015, 14 etc). Importantly, everyone knows prices are going up, so it gives us a chance to get a foot back in the door with potential customers where perhaps over the last few years we have struggled against a competitor (who are normally much smaller than us an don't do any hedging). If previously we were dismissed as overpriced etc, at least now everyone is doing a reassessment exercise, which gives us a lot of business potential, everyone still needs to buy the things we sell.
At the beginning of July 2014 the Euro was worth $1.36 today it is worth $1.06.
Bottom line is the currency market thinks the EU is worth 22% less without the UK!
Perhaps those on both sides negotiating our exit from the EU will take cognisance.
Bonitabeach
Interesting point.
Perhaps the concern extends to the increased risk of a breakup of the EU as a trading bloc? I expect most would view the EU's value as more than the sum of its parts.
No strong opinion; just thinking aloud.
Hi Paul, re WanDisco there are some very useful audio recordings of interim and full year results presentations on their website. I did some work on it late 2015 and had a small investment for a while. There seems to be validation through partnerships with key players that was starting to show back then and further demonstrated today.
I didn't hang on to my holding in the end as there was other stuff that I knew better and so used the money elsewhere. It worried me a little bit that even at the rock bottom prices that were reached none of the directors wanted to put their own money into it despite large salaries and David Richards having sold down large amounts of his shares at higher prices. Difficult to know how much weight to attach to that.
Also recently David Richards was reappointed and several board members stood down as a no confidence (in him) measure. That's perhaps important to bear in mind.
Regards
Andrew
Carey,
Thank you. I've sent the message.
regards,
JakNife
Paul,
Could I ask you a question on Advanced Oncotherapy (£AVO) please? I see that you queried the stock rank score for AO last week and as I look at the Value Rank for AVO I'm left with many questions as to why its value rank is 54. As I look at its metrics both the Price to Sales ratio and operating margin look totally wrong and could be contributing.
I'd email Stockopedia direct but don't have an email address. Could you share an email address or forward my question please?
JakNife
Hi JakNife,
If you open the Stockreport and follow the "BreadCrumb" at the top back to the "Healthcare Equipment and Supplies" sector list then you can click on the value rank number for Advanced Oncotherapy (LON:AVO) and see what its made up of. The ValueRank is high because of a Price/Sales number of -1414.
No idea if this number is right or wrong but it doesn't seem right.
I think you can use the little green floating "conversations" icon in the bottom right corner of the screen (at least it is on my iPad) to open a conversation with Stockopedia help.
cheers
Carey
If you want to talk to stockopedia just click on the little green circle with a white square and smile on it. It's a direct line to open a dialogue.
Morning Paul
I am just coming back here to thank you for the link to Mark Brumby's daily newsletter. It is just excellent and I think should be required reading for all PI's.
On xrates I just think that on a macro level the sinking xrate is just negative for the uk. If you look at uk top ten exports most rely on importing something and transforming them with expensive labour, our energy will cost more and all our imports will cost 15% 20% 25% more which will lead to inflation which will lead to rising interests rates which will lead higher wage demands. That's my opinion anyway. The 1970's all over which I, unfortunately, can remember.