Small Cap Value Report (16 May 2016) - AVN, EVRH, SEE

Good morning!
I'm back in the UK, having flown back Sat/Sun on the "red eye" overnight BA flight. I used most of my Avios points to upgrade to a flatbed, thus enduring somewhat mitigated discomfort. The brand new Dreamliner 787 really was impressive though. Twin-engined, wide-bodied, and very much a step-change downwards in terms of engine roar. I was impressed with the push in the back acceleration on take-off, but with so little engine noise, did have an anxious few moments wondering whether the pilot had put his foot down enough to achieve lift-off. I need not have worried of course.
24 hour airport operation must surely only be a matter of time. Tough luck to the NIMBYs who bought houses under the flight path, in the full knowledge that planes make a loud noise. I like seeing planes take off & land, so would happily live under the flight path. Something like a 787 glides in almost silently, like a giant, graceful eagle, so anyone who objects to that should move elsewhere.
I'm going back to Abu Dhabi in early Dec 2016, to the same hotel, the Yas Viceroy. I've stayed in lots of top hotels, but have never before experienced such an astonishingly high level of service. Nothing was too much trouble, and the staff were all so courteous and happy.
I only paid for a standard room, but 2 upgrades later, I was in the Presidential Suite, on the 1st floor, directly overlooking the slow corner of the F1 track. Where else can you conduct your ablutions in pole position?
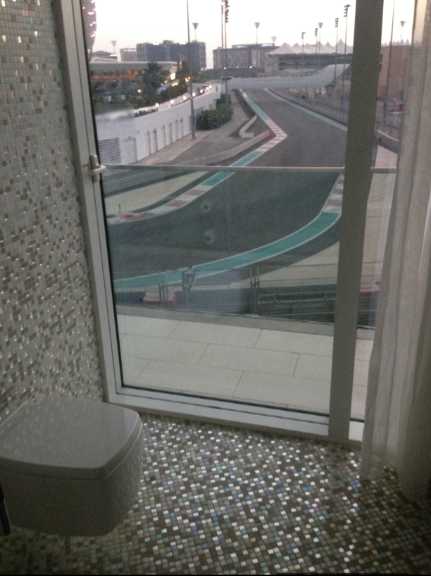
Every now & then, one would hear a blast of high octane exhaust gases, and I could raid the minibar and enjoy myself watching fast cars roar past. The Manager told me that our suite was booked by the same customer every December, for the Grand Prix, and he pays a £5-figure sum for the peak 4 days. All the furniture is removed, and it is used as a hospitality area for his friends.
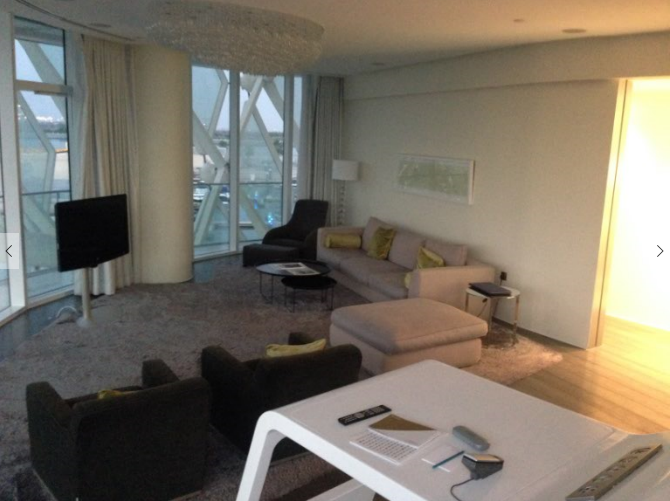
So it was a remarkable treat for me, paying next-to-nothing to enjoy the same suite. Here's half of the living room, that doesn't overlook the F1 circuit:
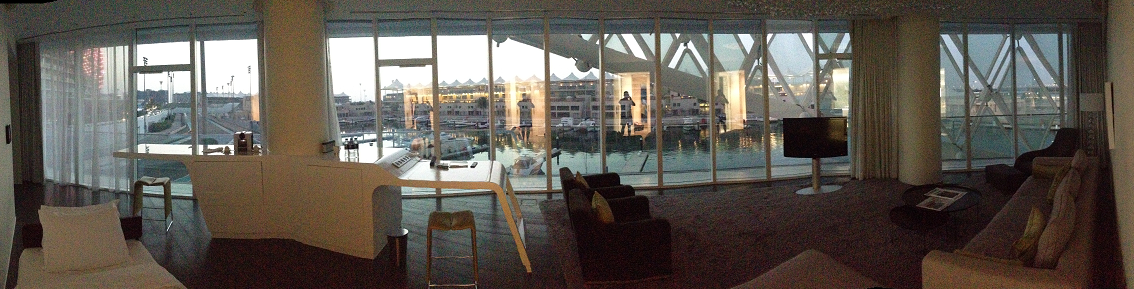
Here's a panoramic shot of 180o of the living room. See the F1 racetrack on the left:
Sadly, I missed Eurovision, but will crack open the duty-free vodka and "enjoy" it with friends later this week, on catch-up.
Late report for Thu 12 May 2016
A sense of nagging guilt about having a duvet day on Thursday last week overcame me last night. So I filled in the gap by writing a SCVR for Thu 12 May 2016 here. It threw up 2 lousy companies, and 1 potentially interesting one - XLMedia (LON:XLM) .
I have an aversion to overseas companies which list on AIM, as so many have something wrong. However, XLM looks quite interesting, and it's going on my watch list. Mind you, I would only ever risk a small amount of capital on an Israeli AIM-listed company - position sizing is everything.
Avanti Communications (LON:AVN)
Share price: 88.9p (up 3.9% today)
No. shares: 147.4m
Market cap: £131.0m
Q3 2016 trading update - looking at this highlights here, one could be forgiven for thinking that things are going well at this satellite operator:
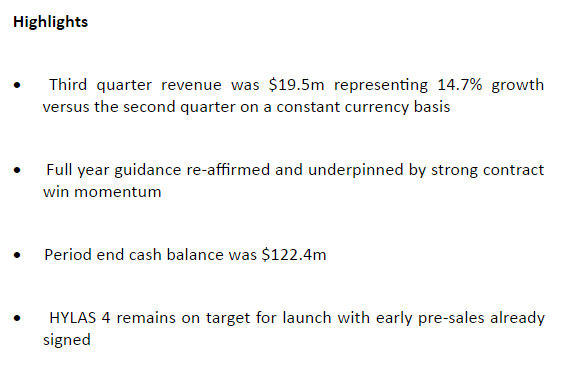
I'm suspicious that the company refers to sequential quarter-on-quarter growth, and not the more usual comparison with the prior year. So I'm going to check to see what the company said this time last year.
By deduction, I calculate that Q3 turnover last year was $17.8m (taking the Q3 2014/15 YTD figure of $48.9m, and deducting the 2014/15 H1 turnover of $31.1m). So this year's Q3 turnover figure is up 9.6% on the prior year Q3.
That's a lousy result, because the company desperately needs to increase revenue hugely, in order to get anywhere near breakeven.
Outlook - as always with this company, it's more jam tomorrow:
Guidance for approximately 50% growth in continuing business revenue on a constant currency basis in the full 2016 financial year is re-affirmed. This guidance is underpinned by the strong and ongoing contract win momentum, with an element of revenue that we had expected to be recognised in the third quarter, moving into Q4.
EBITDA - last year, the company reported positive Q3 EBITDA of $1.6m.
This year, the company reports a fall in Q3 EBITDA to only $0.4m, yet it reports this as if it's an improvement (and omits to mention the deterioration against last year!) How misleading:
EBITDA was $0.4m due to the growth in revenue above the Group's largely fixed cash cost base.
In fact, the entire announcement seems completely delusional. The elephant in the room is debt - Avanti is clearly heading for disaster, due to its extremely expensive debt mountain.
Balance sheet - Avanti has financed its satellites through very expensive junk bonds, of $645m, yielding 10%. So the interest bill on that is obviously $64.5m p.a. The problem is, that the company is not generating any cash to service those interest payments. Q3 EBITDA was negligible, at $0.4m.
Therefore, unless there is a dramatic increase in revenue & profit, this company will inevitably go bust. As things stand, the equity is clearly worth nothing, and it looks an absolute slam-dunk short. The trouble is, funny things can happen - shorting this share is a very crowded trade, and you can get horrendous spikes up with heavily shorted shares.
My opinion - it seems almost inevitable that the bondholders will end up owning this company. It is not generating any cash, and hence will not be able to service the interest on its debt mountain, let alone repay any capital, due in 2019. So this is a zombie company. There might perhaps be a debt for equity swap at some point, all but wiping out existing equity holders, as happened at Afren for example, shortly before it went bust.
I was talking recently to the CEO of a company which re-sells satellite capacity, and he told me that there is relentless downward pressure on pricing. Therefore, companies like Avanti are seeing greater usage of their satellites, but the unit price is falling, largely negating the benefit of increased usage. This is confirmed from Avanti's own figures - although of course they don't flag this point, because their announcements are just PR puffery, designed to mislead, not inform, in my view.
You only have to look at the capacity usage stats - Avanti says it is within the 25-30% range in Q3 this year. The same stat last year was "at the upper end of the 15% to 20% band in Q3 2015, having increased from the 10% to 15% range in the same period in the prior year."
So, despite a big increase in usage, Q3 revenue only grew 9.6% Y-on-Y. The reason has to be a big fall in the price charged, not mentioned today of course by the company. I seem to recall the CEO of the satellite services reseller mentioned above telling me that prices are falling something like 20% p.a.. So Avanti has to grow its volumes by a considerable amount, in order to just stand still.
Avanti needs a massive step change upwards in revenues, to get anywhere near being a viable business.
Overall, this looks a total dud. Insolvency looks inevitable, it's only a matter of time before it runs out of cash, and the bondholders wipe out equity holders.
You would have to be completely out of your mind to buy this share, in my view. The company is the living dead - due to its insurmountable debt pile. This is not mentioned in today's announcement. Instead the company makes this appallingly misleading comment:
Balance sheet
Period end cash was $122.4m. Avanti has additional consented credit capacity of $71.0m. As planned, the Group has made good progress towards securing additional liquidity. Several different facilities have been offered and the most attractive is in documentation.
No mention at all of the $645m 10% bonds!
The company does indicate that revenue is likely to rise considerably:
We are intensely focused on increasing utilisation of our existing capacity and driving sales on HYLAS 4, such that we will see a very significant growth in revenue in the medium-term with a de minimis increase in Avanti's cash cost base."
That's great, but turnover needs to go up by a colossal amount, to start generating enough cash to service the interest on its debt. With price deflation ongoing, and technology rapidly advancing, this is a terrible business model - huge up-front costs, to put a satellite into orbit, which will probably be obsolete in a few years' time. No cashflow, and an ever-growing debt mountain. This is probably the worst share on the UK market, and that's saying something.
I see that two of the worst companies on AIM have had their listings cancelled today. So good riddance to both Phorm, and Litebulb. Both were absolutely terrible companies.
Phorm in particular destroyed a remarkable amount of shareholder value - the accumulated deficit on the P&L was over $317m in the last accounts published.
Only a few hundred more terrible companies to go, and AIM might start to look more sensible. It's a pity that so much junk has been floated on AIM, because it dilutes the perception of the several hundred good companies on the market.
£EVRH
A new listing on AIM today. This company is a "creator of virtual reality content".
I wonder how long it will be before they run out of cash?
Seeing Machines (LON:SEE)
Announces a deal to develop its technology for automotive use, with a separately funded company.
No financial details are given. The excerpt below suggests to me that SEE is probably only going to have a minority stake in the newco. Still, at least this approach mitigates cash burn. Presumably the newco will be accounted for as an associate:
...signed a term sheet with a US-based investment firm with extensive experience in automotive technologies, for investment into a separately funded company solely focused on commercialising Seeing Machines' technology in the automotive market. Seeing Machines would retain a significant equity stake in the new company.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
XLMedia (LON:XLM) is not my type of stock and am very happy to sit out from the side lines. But interestingly Leon Boros likes (liked?) it see his interview with Paul at http://qualitysmallcaps.co.uk/investor-interviews/leon-boros-9-oct-2015/ with transcript at https://docs.google.com/document/d/13l8lH_GOR9FaA7hVQvjAT8Kfljs03mjuLXenmVXbB4k/edit.
Also John Rosier over at JIC (http://johnsinvestmentchronicle.com/category/xlmedia/) has a small stake.
Neither should be ignored even if one decides not to invest.
Afternoon Paul
Thanks for the update on XLMedia (LON:XLM) It is, quite frankly, the "type" of company that I'd normally run a mile from rather than invest. However, occasionally I have a brain explosion and have a punt on something like this. So, for the record, I've had a minuscule punt here. It is clearly not one for widows and orphans nor one to go too heavily in to IMHO.
Anyway......you mentioned that you hadn't seen any forecasts, I believe. Apologies if this has been posted before but there are numbers out there for 2016 and '17, available online if you are interested......
http://tools.morningstar.co.uk/uk/stockreport/default.aspx?SecurityToken=0P00012HNS]3]0]E0WWE$$ALL
.....where they suggest EPS of 7.54p and 7.68p and dividend of 3.81p and 4.22p respectively. So a PE ratio of about 8 and yield of about 6% FWIW. I can also confirm that the forecasts are from Cenkos and dated 12/5/2016, so very recent and after the "review is concluded" announcement. They ARE the NOMAD and joint broker so you either assume they know what they are talking about, or that they are talking their own book :-)
Cheers
@entrustTMF
Worst UK share ? What about GSR,LGO,AVM,JSI.,AFRI,OUT ?
PP,
That standard of service is "the norm" around Middle East and Asia at any of the decent hotels - Mandarin,Hyatt, Peninsula,
If you;re ever in Thailand - Bangkok, you might want to try the Sukhothai. It'll be right up your strasse so to speak.Very querky as well..couple of superb restaurants.
Dear Paul
Concorde gave a real kick in the back! We went to NY for our 25th Anniversary.
Next week it's our 45th and it's a party on a yacht and then the Ermanno Palace terrace on the 8th floor for the Monaco Grand Prix - you can see 75% of the circuit from there.
Pretentious - moi? No, it's the advantage of age. But I enjoy reading your comments to make sure I can fund the next trip - many thanks.
Hello Paul,
Why the hell should I be interested in details on your hotel bedroom in Abu Dabhi? Actually, it turned out very interesting, wot with your ablutions in pole position. It also illustrated how bargains are there for the taking, if you know how.
Avanti arrived in my portfolio and departed again ages ago at quite a profit in the rocket blast of initial enthusiasm. I really appreciated your straightforward comments on the company. I had just seen the debt figure elsewhere when I read your piece, and you certainly confirmed my own opinions.
Keep up the good work! Your reports don't take prisoners - and nor should they. Thank you.
I've never considered going to Abu Dhabi but if I could be sure I'd get the Presidential Suite I'd jump at the chance.
Thanks for the glimpse of luxury Paul
mark
note that you said, "only 63% of clients are short " - on ig
that seems quite a high percentage - i think i m misunderstanding something ( or showing my ignorance )
could you amplify please?
john
Hi John,
I wouldn't say it is small (most spreadbetters are long biased) but it is not overwhelmingly one way or another. If it was say 95% short and had bigger funds short who had taken up the borrow then it may be worth someone trying to squeeze weaker hands.
I see that IG have just gone unborrowable though so maybe stock is tighter than I expect.
If my analysis is correct then shorts will be able to close into an equity raising. If I'm wrong I still think a large debt trading at c.20% YTM will provide a large drag on company performance in the medium term. (If you are a large fund who thinks that the equity has value and the debt will be refinanced without a problem then you can get an equity like upside without the risk by buying the bonds, why risk the equity?) I also always position myself so that I can ride out a short term doubling of a position as 'noise'.
HTH,
Mark
Have you seen the line in Edisons report this morning " Our own capped DCF still returns a fair value of 427p per share". I seem to recall one of Evel Kenivel's contacts saying the stock will go to zero.
How unfortunate and arrogant
Tough luck to the NIMBYs who bought houses under the flight path, in the full knowledge that planes make a loud noise.
Perhaps they were bought when there were no overnight flights
Hi Paul,
I think I spotted a typo.
You wrote "Sadly, I missed Eurovision" when surely you meant to write "Fortunately, I missed Eurovision". Fortunately, I did too. I'll be honest, I didn't even know it was on.
:-) All the best, Si
PS. How can you ever trust financial results from a company specialising in "virtual reality"?
Its a comedy, not to be taken seriously, I can imagine after a few glasses or bottles of wine its great entertainment. The scoring near the end was quite good, Australia must have been gutted but when was Australia in Europe? As for music, hmmm, pass on that.
Its a comedy, not to be taken seriously
Trouble is I don't find it funny but mainly because:
1. It's got Graham Norton in it.
2. I don't want to waste all of a Saturday night watching it when there are far more useful and entertaining ways of spending time.
3. It only serves to illustrate how totally screwed up Europe is... and Australia!
On another note. Decent results from Braemar Shipping Services (LON:BMS) today. Dividend held and business not too bad considering the poor state of shipping markets and the O&G industry.
All the best, Si
Yes I'm not a Graham Norton fan although I don't find him as bad as I used to. I only watched some of the scoring.
Paul,
I fully agree with your Avanti Communications (LON:AVN) analysis.
I think best case is that they raise a very large amount of equity very soon.
The mistake Afren (LON:AFR) made was waiting too long. If they had raised equity when things started to go wrong at £1/50p level they may have survived.
A short squeeze is always a risk with these sort of things but I wonder how crowded the trade is in reality? I received very little feedback when I did a write up on here:
http://www.stockopedia.com/content/can-avanti-comm...
And there's no disclosable shorts from the bigger funds:
http://shorttracker.co.uk/company/GB00B1VCNQ84/al
You can still take a short position on IG and only 63% of clients are short.
As for the $40m cash burn in Q3 I expect it to be even bigger in Q4. They had guided for $100-110m capex for FY16 so even if we assume the $40m cash burn was all capex then they still have $23-33m left to fund. I believe the semi-annual bond interest payments are made in Q2 & Q4 so that will be $32m outflow too. They had a $25.5m increase in trade payables in H1 which should reverse. This is partially offset by a trade receivables increase of $8.7m so if these both normalise you have an additional outflow of $16.8m.
This means the current $122m cash becomes $40-50m + Q4 OCF.
Their FY guidance means that they are expecting Q4 revenue of $39.7 in 3 months vs $50.5m revenue that they did in the other 9 months of the year. Even if we take that as achievable and on normal commercial terms those sort of increases often suck in working capital rather than being cash generative in the short term.
If as I expect cash looks around the $40-50m level (adjusting for any abnormal trade receivables) then this would be less than the debt interest for next year. Do you think in this case they get the Y/E accounts signed off as a going concern?
Even with the $71m consented facility they couldn't cover the debt interest and their $70m guided 2017 satellite CAPEX. And there is some doubt over how committed this $71m is, with some suggesting the consent means simply that bondholders have said they won't object the them raising up to $71m of bank debt that is subordinated the bondholders and that this isn't actually committed by any lenders. Given that the current YTM of the 2019 bonds is c.20% then they would have to pay greater than 20% for subordinated debt.
In my opinion if they are to survive to see their additional satellites launched then they don't need more debt but a lot more equity, and the sooner they raise it the better price they will get.
Mark
Very much agree on the timing, Mark. The longer you leave an equity fundraising, the clearer it is you have no other option the more likely that existing shareholders will be heavily diluted or even wiped out.
The chairman, Paul Walsh, has just bought an additional 25,000 shares although it's hard to see that it will make a difference to people's perceptions...
Avanti Communications (LON:AVN) - Directors share purchases. A drop in the ocean compared to the number of shares that the Government of Singapore is dumping in the market.
The usual pattern after an announcement is a big spike up then reality slowly dawns and the price starts slipping. The share price action today is not much help for a company which really needs to raise somewhere around twice it's current market cap or more. A couple of token director buys haven't done the trick.
Mark,
Great summary, thanks for putting that together. I'm slightly concerned at how much I enjoyed it, maybe I need to get out more!
Graham
Nice upgrade! Yes service levels seem very high if you go from bunk beds to Royal suite! Good work fella
Avanti Communications (LON:AVN) had $162.6m in cash at the half year 2016 against $122.4 now. In other words it has burnt through just over $40m in 3 months.
That is despite telling us, at H/Y 2016, that "The working capital outflow during the period is expected to largely reverse in the second half as cash payments relating to invoices sent towards the end of the first half are paid."
Equity is toast here. Just a matter of how long. I'm short Avanti Communications (LON:AVN).
Hi Paul,
I thought this sentence from you was rather unfortunate.
"Where else can you conduct your ablutions in pole position?"
Sorry to lower the tone.