Small Cap Value Report (Mon 2 July 2018) - TRAK, PLA, ZOO, KMK, AVAP, PLUS

Good morning! Today we have announcements from:
- Trakm8 Holdings (LON:TRAK) - final results
- Plastics Capital (LON:PLA) - final results
- Zoo Digital (LON:ZOO) - final results
- Kromek (LON:KMK) - final results
- Avation (LON:AVAP) - interim statement
- Plus500 (LON:PLUS) - trading update
- Quartix Holdings (LON:QTX) - trading statement
- Filtronic (LON:FTC) - trading update
It's a lot of news - let's see how I get along covering it.
4.30pm: I made it as far as Plus500. The Quartix statement was in line with expectations while Filtronic was "broadly in line", i.e. a slight miss. So it's not worth reporting on them today.
Trakm8 Holdings (LON:TRAK)
- Share price: 94p (-10.5%)
- No. of shares: 35.9 million
- Market cap: £34 million
This company has previously proven to be controversial, due to the rather high rating it enjoyed, compared to its limited cash generation.
Most of the optimism has by now been squeezed out of the share price.
Back in late 2015, it was trading almost at 400p:
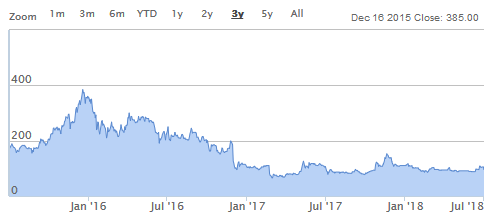
Recently, I used the Stocko comparison tool to show a side-by-side comparison of Trakm8 with Quartix, another telematics stock. Quartix has consistently been the more impressive of the two, from a quantitative point of view.
Another resource worth mentioning is today's article by "blondeamon", who owns shares in Trakm8 and is bullish on the stock.
I've read both positive and negative reactions to today's results already.
Let's have a look at what they actually say.
Financial highlights:
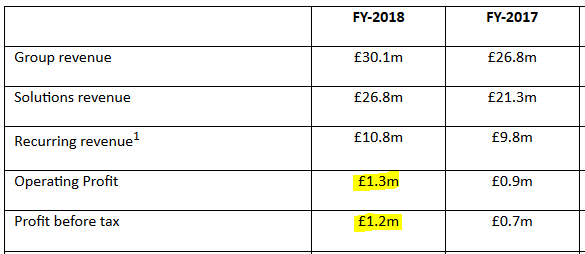
So it's a healthy upward move in many of the headline numbers.
Net debt has reduced by £0.5 million to £3.3 million, while cash generated from operations is up very significantly to £4.7 million.
Certain overhead expenses have been reduced while R&D spending is maintained and sales and marketing spend is increased. Manufacturing and distribution facilities are being expanded.
Outlook
First sentence of the outlook statement:
Due to customer inventory build-up in Q4-FY2018 and the terminated CEM activities, revenue and profit for the first half of FY-2019 is expected to be below the figure reported at H1-2018; although the full year result is anticipated to be in line with market expectations and higher than FY-2018
Customer inventory build-up: what does this mean - that customers have received more units than they need, so orders will be slower in the short-term? I'm not sure why this is better than a normal sales warning.
That, plus the planned exit from Contract Electronics Manufacturing ("CEM") leaves investors facing an H2-weighting already.
We are used to seeing forecast H2-weightings result in profit warnings, and the Trakm8 share price today appears to have priced in a profit warning for later in the year.
Balance sheet
Most of the equity on the balance sheet can be attributed to goodwill of £10.4 million and capitalised development costs of £5.3 million. So to me, the balance sheet at first glance neither looks distressed nor does it offer much in terms of anchor value.
Cash flow
The company generated £4.7 million of net cash from operations, and spent £3.7 million on investing activities, so the free cash flow generated is £1 million.
That's not a bad conversion of profits to cash flow.
But there are some weird things happening in cash.
For example, the company benefited from £1.6 million in R&D-related tax credits. Without that, free cash flow would have been negative.
There were also some large movements in the components of working capital, although they netted out at about even.
Creating and amortising intangible assets
The company amortised £1.5 million of intangible assets to calculate its net income, while capitalising £3.4 million of development costs and including £236k of purchased software as an investing activity (rather than expensing these two items items and putting them through the income statement).
It clearly believes that it is creating value with these expenditures, but the income statement would have shown an operating loss if it was not for this creation and amortisation of intangible assets.
Bulls might argue that I am ignoring the "exceptional costs" of £1.4 million. These exceptional costs freed up £2 million of overhead to be spent on other things.
Conclusion
I think your view of this company's performance depends a lot on how you view its R&D spend. If you think it's creating more value than its using up, then you can use the numbers presented by the company with confidence.
If you're not sure about how much value is being created by R&D spend (admittedly, I am in this position), then you are looking at a company which does not appear to be generating much cash, at least not without the help of tax credits.
If the intangible assets already on the balance sheet don't have a lot of value, and if the intangible assets being created don't have a lot of value, then the company as a whole has not created much value and could even be interpreted to be running at an underlying loss.
That is admittedly a harsh way of looking at it. That's just what the numbers say to me.
Plastics Capital (LON:PLA)
- Share price: 109p (-1%)
- No. of shares: 39 million
- Market cap: £43 million
Paul and I have rarely had much positive to say about this group. It's a collection of niche plastics businesses - packaging, food pouches, sacks and bags, etc.
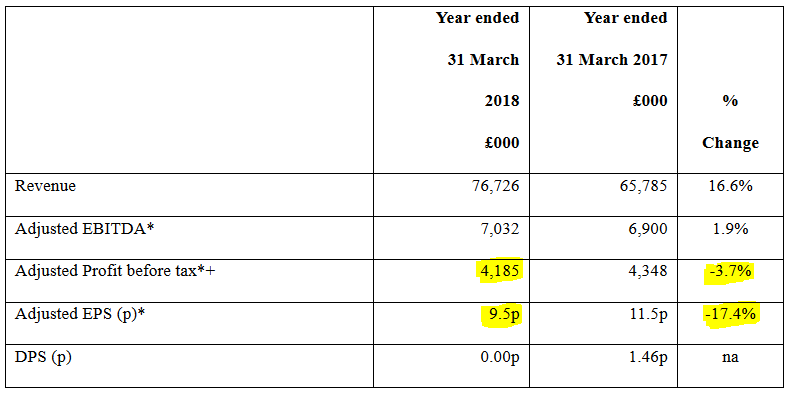
Revenues are up strongly but adjusted PBT and adjusted EPS are both down.
See how the EPS is down much worse than PBT. When I first saw this, my instinct was to check the share count for dilution. Plastics has historically carried quite a lot of debt, so I figured there might have been a placing.
My instinct were wrong. This is the company's explanation for falling EPS:
Our tax charge has increased as we now exceed 500 employees, which is the limit for attaining the maximum benefit from the government's R&D tax credit scheme. As a result, adjusted EPS decreased by 2.0p or 17.4% over the prior year.
An important similarity with Trakm8: R&D tax credits had been boosting the numbers at Plastics. As that bonus is reduced, profitability falls, too.
We need to be wary of companies benefiting in a substantial way from government subsidies or other policies - these subsidies can and do change all the time. In the case of Plastics, the policy hasn't even changed, but its own eligibility to benefit from the policy has reduced.
Another similarity with Trakm8 is the use of exceptional costs. £1.5 million is recorded in relation to the value of an acquisition, transaction costs related to an acquisition and restructuring costs.
Restructuring costs include:
"business-wide restructuring of production operations within the Industrial Divisions"
Doesn't this sound rather vague? I would welcome clarity on what this relates to. It sounds like one of those buckets that a collection of miscellaneous costs could be lumped into.
Net debt is now £15.1 million.
Balance sheet
Yet another similarity with Trakm8: most of the balance sheet equity (£31 million) can be attributed to intangible assets of £27 million. This includes goodwill of £20 million and distributor and customer relationships valued at £5 million.
My view
I don't want to delve into this in any further detail. It always seems really ugly whenever I look into it, and I wholeheartedly agree with it having a single-digit P/E ratio.
Zoo Digital (LON:ZOO)
- Share price: 94p (unch.)
- No. of shares: 73.8 million
- Market cap: £69 million
ZOO Digital Group plc, the provider of cloud-based localisation and digital distribution services for the global entertainment industry, today announces its audited financial results for the year ended 31 March 2018.
This company's share price zoomed up 10x from June last year to April this year. Well done to anybody holding it! I like to think that this company does for TV and movies (subtitling and dubbing) what Keywords Studios (LON:KWS) does for video games (localisation).
The strategy in a nutshell:
ZOO's software enables the Company to collaborate with a worldwide network of thousands of freelance workers, such as translators, voice actors and dubbing directors, and to significantly reduce the human capital requirements of service fulfilment, enabling the Company to scale its capacity efficiently as demand increases.
The numbers
The market loves a rapidly-growing top line, especially if it is organic. Zoo has delivered that with 73% growth in revenues to $28.6 million. The growth was primarily in subtitling. Dubbing services grew strongly in H2 and are set to be a bigger part of the business in future.
Gross margin has reduced by 10%, to 35%.
Margins were low in dubbing and this is explained as follows:
...our imperative to provide clients with services of the highest quality has led to higher costs from extensive verification and quality control while the software is being refined. We fully expect these margins to improve as the software is proven and new features continue to be added.
That sounds reasonable to me. There was also a decline in gross margin in some other services provided by the group. Overall, not a great picture in gross margin but the company has expressed a lot of confidence that it will improve,
Operating expenses increased by nearly $2 million, "as we continue to build up the business".
The sales team is bigger, the R&D team is bigger, IT expenditure is up, and and marketing spend is up.
After taking all of that into account, operating profit for the year increases only marginally to $600k.
Finance costs
There were also some unusual finance costs this year. The company has a convertible loan note outstanding, convertible at 48p. Given the soaring share price, the right to convert the loan note is now worth several million dollars. That gets included on the income statement.
Finance costs such as the above are rather weird and unusual so let's put it to one side and focus on the operating profit line: £600k.
Customer concentration has reduced but the top two clients still accounted for 59% of sales. I guess this is due to the nature of the media industry and the media giants who dominate it.
Balance sheet - shows negative net tangible assets. Outstanding debt is in the form of the convertible loan note, which matures in 2020. We can presume that the note will be converted by its holders (if the share price is high enough), or else that the company will use operational cash flow or a fundraising to pay it off.
My view
The organic growth in revenues is not to be sniffed at. We also need to bear in mind that significant further growth in revenues is likely, given the H2 performance of dubbing.
I suppose the big questions are
1) how big is the growth runway in subtitling and dubbing? Is it endless, for our intents and purposes? It appears to be a fantastic space to be in, from a demand point of view. And Zoo should be able to beat its very cautious consensus revenue forecasts for FY 2019.
2) will the promised growth in margins materialise? I am inclined to believe that it will, but I suppose it can't be guaranteed.
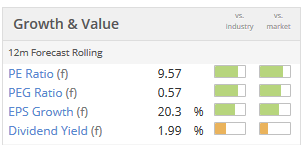
The valuation is too racy for my investment style, so personally I would only be a buyer at much lower levels. But it's good to see a growing company which appears to be creating value and innovating in an exciting sector of the global economy.
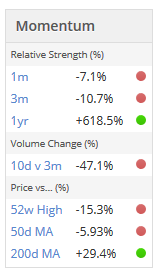
See how momentum remains very strong on a 1-year or 200-day view, bu is weak in the short-term. If I had to guess, I would see the share price waiting now for the company to grow into this valuation:
Kromek (LON:KMK)
- Share price: 24p (+1%)
- No. of shares: 260.4 million
- Market cap: £62 million
Kromek (AIM: KMK), a radiation detection technology company focusing on the medical, security screening and nuclear markets, announces its final audited results for the year ended 30 April 2018.
This is a jam-tomorrow type of share. Today it has reported its first little piece of jam: positive EBITDA.
- Revenues increased 32% to £11.8 million.
- EBITDA* was £0.5m profit (2017/2017: £1.5m loss)
The trailing price to sales valuation multiple for the stock is still in the region of 5x.
That metric doesn't look so bad if you take into account the company's net cash balance and rising sales forecast this year.
Commissioned researchers in a note this morning pointed out that the EV/Sales ratio for Kromek is cheaper than some of its peers, despite Kromek having higher forecast sales growth than the average of these companies.
A small and unprofitable business probably should be cheap, however. It's probably riskier, so it needs to be priced in such a way that if it succeeds, then investors will be richly rewarded.
With regard to the potential for future success, today's outlook statement is in line with expectations. Management are confident:
The momentum of the 2017/18 financial year has been sustained into the current financial year as Kromek's products continue to gain traction in all its business segments from the increasing adoption of CZT-based technology and other products.
(CZT is cadmium zinc telluride, the high-performance material Kromek uses.)
In FY 2018, Kromek used up £4.6 million of cash in operating activities and £5.6 million in investing activities (of which £3.5 million is capitalised development costs). The total decrease in cash, excluding an investment the company made in a money market account, was £9.1 million.
Taking into account the speed with which cash has been used up, I think we have to assume there will be another equity placing. This company had significant share issuance in FY 2016 and FY 2017. There was none in FY 2018. I would guess there will be another one before too long.
The company may perhaps have exciting technologies, and be poised for long-term success. It is just too early-stage for me.
Avation (LON:AVAP)
- Share price: 230p (+2%)
- No. of shares: 62.8 million
- Market cap: £143 million
Background
We have another strong reader contribution on a stock, this time from Carcosa. Here is the link to his article, published today. It is very detailed and essential reading for anyone who is interested in this stock.
Avation is an aircraft leasing company, headquartered in Singapore.
In this case, I didn't think there is any risk in relation to the foreign headquarters. It is a real company doing real business, and Singapore is probably a great place to have the company headquarters. It just so happens to mostly have British shareholders.
Aircraft leasing is a financial activity: you deploy capital to buy planes, and then you generate yield on them by hiring them out. Your costs are mostly interest on your borrowings and the depreciation expense as the aircraft age.
Since it's a financial-type business, this share should primarily be measured against its book value.
At the half-year results, book value per share was $3.32, or 253p at today's exchange rate.
Carcosa estimates that book value per share is now 258p, excluding cash.
So the current share price likely offers a material discount to BV.
Note that balance sheet leverage was last recorded to be greater than 5x. This means that leverage is a key element determining the returns ultimately enjoyed by investors!
Interim management statement
Today's update says that things are in line with expectations. Management are growing the company's fleet with a view to diversifying its customer base. The fleet has grown by 40% and revenues by 15%.
It's an issuer of high yield (junk) bonds, recently issuing $300 million of medium-term notes.
There has been some positive movement on its credit rating, a positive omen for future borrowing costs. I suppose there must be some negative refinancing risk, too, should general borrowing conditions worsen.
My view
I retain my overall positive impression of this company.
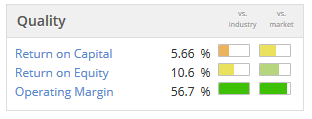
Carcosa says today that ROE will "hopefully" remain above 10%.
For the last couple of years, it has traded between 10%-12%.
Based on continued strong execution and ROE staying within that range, I reckon that this stock should be trading around book value.
Plus500 (LON:PLUS)
- Share price: 1766p (+9%)
- No. of shares: 114 million
- Market cap: £2,011 million
4th JULY UPDATE: Plus500's PR agent, and indeed readers in the comments section, have corrected me that Plus does not make money from client losses. I am happy to accept correction on this point, and retract my statement that Plus500 directly profits from client losses.
Please see my latest commentary for updated analysis.
Plus500, a leading online service provider for trading CFDs internationally is pleased to announce that due to a strong Q2, the Board has again materially increased its expectations for the Group's financial performance for the year ending 31 December 2018.
Plus500's market cap has increased by c. £170 million today. Not bad!
Only about a week ago, it successfully transitioned away from AIM and onto the Main Market of the London Stock Exchange. That is likely to have calmed a few nerves in relation to corporate governance.
Geopolitical events have increased market volatility beyond expected levels, boosting Plus500's performance.
Trading volumes and customer acquisition, on the other hand, returned to "more normal levels".
So it's not necessarily the case that many more trades were placed with Plus500 than expected. What's more likely is that customer trades were more unprofitable than usual, because of the increased volatility. Since Plus500 is, I think, a bucket shop that takes the opposite side of customer trading, it profits directly from customer losses.
Regulatory update
Plus500 now offers some insight in relation to the upcoming ESMA restrictions on retail trading: it says 12% of EEA customers "may be eligible" for professional status, and these contribute approximately 75% of EEA revenue.
This is admittedly much better than I had expected.
I still find it hard to believe.
IG Group (LON:IGG), a rival company in which I own shares, has guided that 50% of its UK and EU revenue will be generated by professional clients.
IG tends to have sophisticated and wealthy clients who have traded for years, whereas Plus500, by my estimation, targets the most unsophisticated clients who are completely new to trading.
That is the basis on which I expected IG to generate a greater proportion of its UK and EU revenues from professional clients than Plus500.
We shall see.
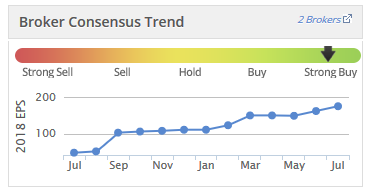
I continue to view Plus500 shares as extremely risky, and am steering far away from it. But I must admit that it does appear to have huge momentum at present. EPS estimates will be upgraded again and the StockRank is an incredible 98.
All done for today - cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Trakm8 Holdings (LON:TRAK)
When this article was written (2-July-18 with the share price at 94p) Graham wrote :
Roll on to today 16-Nov-18, the profits warning duly arrived, but with the shareprice down 62% on the day to 22,5p (down 75% from the July price) I think we can safely say that the profit warning was not previously priced in.
Something I have learnt over time is that it is a dangerous game to suppose that the bad news is "all in then price" (I don't mean to suggest that was what Graham meant in this case). Often times the news may be worse than presumed (as was the case here) or that having digested the expected bad news the market will proceed to price in further bad news.
I am losing count of the number of "H2 weighting" predictions that have failed to transpire.
Part of the growth story of Plus 500 is supposed to lie with trading Cytprocurrencies like Bitcoin but that should apply to its rivals who as others note trade on much lower valuations.
I'd heard of this ESMA regulation, but hadn't looked into it until reading here today reminded me. I'm not an 'expert' investor, but don't like being restricted or told what to do with MY money.
Off-topic - whilst looking into ESMA with AJ Bell, I learned that whereas I'd needed a W8-BEN form (with previous broker) to trade USA stocks, this is not needed within their SIPP - something learned !
I do not pass any of the 3 FCA requirements (as per leoleo73 post #18), but AJ Bell do have an online test. I completed this, answering what I expected them to require, as opposed to 'true' answers, and am now allowed to trade these professional-only investments IF I want :o)
It appears that companies are just covering their backs, in case of future claims.
p.s. As mentioned a while ago (and by others since), doing a great job Graham, but do feel you're stretching yourself thinly when I see the list of companies you're aiming to cover. As I've seen on SCVR in the past - covering fewer companies indepth, with one-line summaries for the rest may be a compromise - Your post #22 being an example.
Thanks for the feedback DJCP
The majority of PLUS revenues are not from client losses. 89% are dealing spreads and the rest is from overnight charges.
Ian, it would be helpful if you could let us know the source of that information.
https://www.plus500.com/Docs/Plus500UK/Prospectus.pdf
"In 2017, approximately 89 per cent. of the Group’s revenue was generated from
the dealing spread charged on its trades, approximately 11 per cent. was generated from overnight
charges and there were no net revenues from mark-to-market profit and loss."
Other useful points:
PLUS have 4282 professional clients as of 20th June.
IGG last reported around 3800 in late May.
I find the huge valuation different between PLUS and their peers a bit of a mystery. Still a long way to go for PLUS to be on a similar valuation rating. Client base is essentially the same between all CFD providers. The more people you get in the higher the chance of acquiring another high value client. And PLUS are streets ahead of their peers when it comes to bringing users in.
Not to mention PLUS having optimised the CFD model so their costs are on a different scale to the others while their platform is arguably the best.
Plus500 announced this morning that analysis of its client base shows a large proportion of its revenues come from clients able to be categorised professional.
Hopefully that will help Graham retract his previously bearish stance on this issue and cease referring to this growth company as a bucket shop.
Hi, I am impressed/surprised by the 75% number (from 12% of clients). If that turns out to be true, then hats off to Plus500.
That makes no difference as to whether or not it is a bucket shop - a place where bets are made, but the underlying asset is in many cases never bought or sold, either by the customer or his counterparty.
Read the Prospectus. Last year spread revenues were 109% of revenues. They internalise almost all risk, so one customer nets off against another. They were set up in 2008 to do this, because it's so much more cost effective to do so, and to offer, now, about 1200 instruments, than to hedge in the market as IG mostly does, while offering almost 10x the number of instruments.
12%=75% is an EEA number, rather than being for the whole company.
Apologies if I have missed this conversation elsewhere on this thread, but I am somewhat concerned at the ease with which people are being classified as professional investors for ESMA. In the short term, this should mean limited impact on the bottom-line of IG Group (LON:IGG) and Plus500 (LON:PLUS). But in the long-term, if the intention is to limit the losses of reckless gamblers then I would expect their profits to be hit eventually. Or perhaps I am being naive in thinking that there is any intention beyond providing the spread-betters with some legal defense? I'm sure that there is a definition of the term 'professional investor' somewhere and I'm sure that they are all complying with it legally. But many of the so-called 'professional investors' I come across in the city are anything but while many of the small, private investors on this site are true professionals based upon my observations. The spread-betters really don't want what I call professional (i.e. successful) investors but seem happy to categorise anyone as 'professional' on the basis of some meaningless questions. As I said, apologies if this is old territory.
Mammyoko,
The precise FCA requirements for an elective professional client are that at least two of the following criteria are satisfied:
(a) the client has carried out transactions, in significant size, on the relevant market at an average frequency of 10 per quarter over the previous four quarters;
(b) the size of the client's financial instrument portfolio, defined as including cash deposits and financial instruments, exceeds EUR 500,000;
(c) the client works or has worked in the financial sector for at least one year in a professional position, which requires knowledge of the transactions or services envisaged;
(source: https://www.handbook.fca.org.uk/handbook/COBS/3/5.html)
Now (a) Is very vague. IG were defining a large transaction as £20k for equities and £50k for others, but it was never clear what they meant by that and I can't find that advice now. Do all equity derivatives count as equities and "other" means things like FX/Cryptos? Does buying options on £20k (or £50k) of underlying count? Selling options? Buying/selling with a guaranteed stop loss? Buying/selling with a hedge or covering option in place? Why wouldn't twice the frequency at half the size count?
(b) is the only one even close to qualitative and objective. But the figure could depend on your relative ISA / SIPP holdings (the same amount of money in an SIPP cost you less to put there than the same amount in an ISA, yet presumably they count for the same), how much you have given to and manage on behalf of your spouse and children (any amounts presumably doesn't count), and most obviously, how much debt you have (as presumably loans would not be subtracted from even cash in a broker account, ISA or SIPP).
(c) again, open to interpretation.
In my opinion somebody who only just meets the criteria (b) (or worse, relies on (c)), who is making 40x £20k/£50k trades a year may well be over trading and/or being reckless, but they are also probably particularly profitable for the spreadbetting company. Personally I think that a better indication of a "professional client" would be somebody with a track record demonstrating they are trading in proportion to their wealth, but there we are.
As an aside, I currently don't think we need worry too much about the impact of this on share prices as people are forced to liquidate - small/illiquid shares are already margined around 25% with IG and so the new 20% limit does not affect them. Heavily shorted mid-caps might be impacted somewhat.
Looking forward to Graham's update on PLUS. Trading update today is similar to the last one only a few weeks ago, but has given the share price a good lift.
I sold out after the last update at about the current price and for fast 60% gain from March buy price partly because of the uncertainty about the negative effects ESMA measures (from 1st August) will have on PLUS and also because of these comments from Graham last time:-
" As previously announced in the 1 May 2018 trading update, the full impact of the ESMA measures, which are now confirmed to take effect from 1 August 2018, are difficult to assess. Similarly, the Group's performance could also be impacted by the rate at which customers request to be reclassified, and are accepted, as elective professional clients.
I expect that very few Plus500 customers should qualify as professional clients. When you consider Plus500's enormous churn rates, you have to conclude that Plus500 serves the least knowledgeable, most amateur traders who are sucked in by an internet ad and quickly lose their entire account."
Am wondering whether selling was a mistake as market discounts known bad news and has known about the ESMA uncertainties for a while but also because of the exceptionally good quality metrics. 99 for quality and astonishing 114% return on capital (1st out of 342 companies) and 110% Return on equity (3rd out of 339) and good operating margin of 59% along with singe figure PE and 6.5% dividend.
btw (probably my limited computer skills so missing the way to do it) but I can only tick Graham and Paul's updates and subsequent reader comments on our main computer. Can't do it on my Ipad.
Hi Graham - just wanted to say that I am really loving your forensic approach to analysing accounts and high-lighting the key issues for investors
Thank you, mammyoko!
Ref Tesla Bit off topic but its a laugh a minute with this share (Giants Tents / Farting Unicorns / Sabotage / Conspiracy theories / Employee data theft / debatable announcements / Numerous top bods leaving / rocket powered car upgrades / record production / 9% of staff fired / blah de blah)
Anyway only owned this share 4 weeks and it's almost as much fun as QPP or Globo at the peak Hysteria time.
As i am long hopefully it will be 6 months of silence with some decent profits posted H2 - although anything is possible- Mr Musk being the most glass full dude in history. Anyways Musks 7000 cars 7 days tweet proves he isn't god but it looks like this will keep the shorters at bay for another day or two. I did like Ford's tweeted response - "7000 cars circa 4 hours team Ford" - so thats no doubt Musks next 5 year plan "8k cars in 3.5 hours"
Strong growth in revenue and CEO optimism today from Zoo Digital (LON:ZOO) - the "Momentum Trap" digital subtitling firm. Maybe they will grow into their valuation but I'm not tempted to invest.
Not a request for a write-up but just a note as Carclo (LON:CAR) have been discussed here before.
The story (in brief) so far.
Carclo (LON:CAR) shares declined from a high of £1.80 back in Jul-17 to around 80p in January on the back of a second profits warning, indicating that the future growth was again postponed (they have form here). Although briefly recovering to c. £1.00 the shares had fallen back recently to 80p.
In short, if the growth prospects come good this price would look very cheap, but with little visibility and a history of disappointment, I was waiting to see some evidence of recovery/growth before considering investing.
Anyway this morning we have the news that Consort Medical (LON:CSRT) put an offer to the Carlco directors of £1.16 per share ( a 43% premium on the price low) at the start of June (to be fulfilled with Consort shares rather than cash).
Carclo's Board rejected the offer and have rebuffed further discussions, so Consort Medical (LON:CSRT) have gone public this morning.
There are potential synergies between parts of the Carclo business and Consort and :
Despite the synergies, it seems to me quite an opportunistic bid and the market reaction (shares up 17% as I write to 94.8p) suggests a less than 50% chance that this will suceed (or even be increased).
No position.
Graham
Mercia Technologies (LON:MERC) has released its full year figures today (I hold). They seem to be growing, profitable and to have an experienced management team and a strong balance sheet. The market has marked them down 7% today.
I would welcome your views if you have time.
Martyn
Apologies, I don't have time for Mercia Technologies (LON:MERC) today. Thanks for mentioning it, anyway.
Hi Martyn
I took a look at LON:MERC as I met them at Mello. I think the start up space is interesting (and obviously very high risk) and what interested me is that they have a good network from which to source investments. Unlike say IP Group i hoped that Mercia would NOT be sourcing the majority of start up ideas from universities. Thats almost the last place i want to get start up investments as 1) Universities tend to breed research boffins who are out to solve theoretical problems rather than innovators looking to solve real world problems and make money and 2) university people rely on funding so there is always a reluctance to "kill" start ups if the investors controlling the purse strings are also from universities. Mercia does have university tie ups but many of their start up investments come from real world entrepreneurs.
I was a bit underwhelmed by the results today. NAV has only risen from 40.4p to 40.7p. This is despite third party funds rising to £400m. The fees earned from these funds are used to pay the running costs of the business and allow the balance sheet investments to feed into the Group NAV.
Part of the problems is that there is too much cash on the Group balance sheet (aka "cash drag"). I applaud the Group for being disciplined with shareholders money but at the same time the Group needs to invest in the starts ups of the future,
At a 30% discount to NAV I can see the business looking on the cheaper side but I would want to see a set of results where the NAV starts to rise strongly and the drivers of the growth are broad based, as happened with Draper Esprit, as a sign that the investments are maturing nicely.
One to watch for me rather than go in feet first.
Graham, I see you intend to cover Avation (LON:AVAP). I wrote something about them today.
One issue I have a huge problem with is forecast EPS. Maybe you have access to an alternative source? All I see is $0.27 ish and I reckon it'll be $0.40 or more!
Super update again Carcosa.
I have been for a long time long and continue to be so with Aviation.
Probably won't be enough for me to retire but I agree on the long term upside followed by it being a potential acquisition some time in the future
Hello mate, thanks for the valuable input on Avation (LON:AVAP).
I too can only see forecasts around that level, from a single broker, who last updated their forecast in May.
Hi Graham,
Any chance of a ramble on either Filtronic (LON:FTC) or Avation (LON:AVAP) thanks
Morning - will see if I can include them. G
Hiya, Filtronic (LON:FTC) was just a very short update, "broadly in line" = slight miss, I haven't got anything else to say on that for now. Cheers! G
The fact that it was so short though was quite intriguing I thought.
Last years trading statement contained a similar short paragraph on FY performance, as this year it helpfully quoted expected numbers for key metrics.
But whereas this years update ends there, last years update went on to give a short outlook view for each of Filtronic Wireless and Filtronic Broadband - both were moderately positive.
So why I wonder was there nothing this year?
I'm more inclined to be negative about such an omission (although they have played a fairly straight bat in the past about how concentrated, lumpy and hard to predict their business can be).
I suppose on the other hand they could be restricted by NDA from saying something about a big 5G project (5G is the potential upside catalyst here), but you would think they could at least say something bland than go for total silence.
It's a bit of a puzzle to me - I'll continue to watch from the side lines for now.
Hi Graham,
One hell of a marathon effort from out of interest how long does it take you to dissect a company to get say an 80% feeling if its worth a further look or discarding ?
Thanks again for your efforts
Andy
Hi Andy.... no probs! It takes a while, I can study a company from scratch and have an initial view within an hour. It takes about eight further hours on that stock to make an initial buy decision.
Trakm8 Holdings (LON:TRAK) good results, cash problems now gone and substantial progress in all fronts. Wrote an article about it as well https://www.stockopedia.com/content/20189-a-year-of-massive-growth-in-the-cards-378939/
Please cover if you get the time.
Thanks for the tip off - planning to prioritise Trakm8 Holdings (LON:TRAK) today. G
Intentin to float announcement from Nucleus ( https://investegate.co.uk/nucleus-financial-gp/rns/intention-to-float/201807020700061595T/ ). Looks similar to IntegraFin Holdings (LON:IHP)
My morning smallcap tweet: eve kicks CEO out of bed.
eve Sleep (LON:EVE), £7DIG, Filtronic (LON:FTC), SRT Marine Systems (LON:SRT), Trakm8 Holdings (LON:TRAK)
eve Sleep (EVE) H1 trading. Rev up 61%, 'short of expectations'. Curtailing global expansion. CEO resigns. Adds Dreams' 193 shops to resellers.
7digital Group (7DIG) suspended - FY results miss deadline "because of the rapid growth of 7digital in the last 18 months a complex audit process with new auditors." Six months? What bollx!
Filtronic (FTC) H2 trading broadly in line with market guidance. Guides rev £24m (£35.4m), operating profit £1.8m (£1.7m) and EBITA £1.9m (£1.8m).
SRT Marine Systems (SRT) Japan Radio Corporation to sell SRT AIS kit under own brand. It's "one of the world's leading commercial marine electronics companies". No numbers. I hold.
Trakm8 (TRAK) FY. Warns H1'19 rev and profit down but still guides FY19 in line.