Small Cap Value Report (Thur 5 July 2018) - PLUS, MWG, GLE, PURP, SDRY

Plus500 (LON:PLUS) - Correction
In response to my article on Monday, Plus500's PR agent, and indeed readers in the comments section, corrected me that Plus does not make money directly from client losses.
I am only human, and I get things wrong. So I am happy to accept correction on this point, and retract my statement that Plus500 directly profits from client losses.
My belief that it did was based on my understanding that the company rarely uses an external hedge to protect itself against the net position of clients.
How Plus500 manages risk
I still believe that the company rarely uses an external hedge.
According to the presentation forwarded to me by the company's PR agent, under Risk Management, the company says "hedging would be undertaken if market movement breach the Group's risk appetite limits".
In other words, Plus500 does have risk appetite when it comes to taking on client net positions. It would hedge if client net positions became too extreme.
Profit from client net positions is listed explicitly as a source of revenue by the company, though it claims to have generated no revenues from this source for the past three financial years.
The company presentation also refers to "monitoring of instrument level correlations and volatility".
What that says to me is that the company is willing to take on a net long position in one instrument, so long as it also has a net short position in a correlated instrument.
For any single instrument, ignoring its correlations with other instruments, the only way that Plus500 could have a zero exposure in the absence of an external hedge is if the client book perfectly balanced itself. Needless to say, this is unlikely.
At a normal CFD provider, the external hedge is how the broker protects itself from an imbalanced client book.
At Plus500, it is doing two things to balance its client book, whose importance I did not appreciate:
- Using correlations of instruments to manage its overall exposure
- Blocking client trades when the net position gets too large
Consequences of using these techniques
The first technique relies on correlations remaining within some kind of normal range in order for it to work.
The second technique risks creating unhappy clients. The company presentation says "when limits are reached, no further trades accepted."
This chimes with certain comments by customers and indeed with the company's own FAQs.
For example:
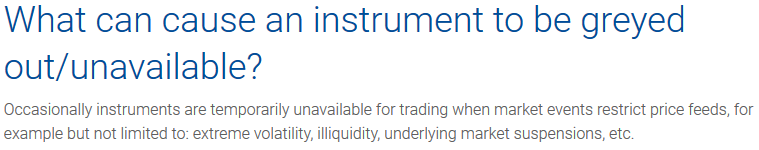
This means: we can prevent you from trading for any reason.
Another example:
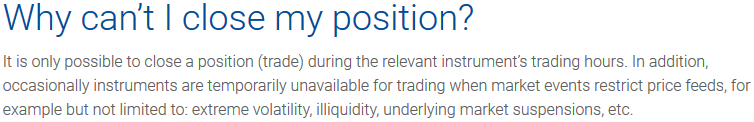
This means: we can prevent you from closing a trade for any reason.
Other CFD providers reserve the right to block trades too, of course.
But Plus500's need to block trades can be expected to be much more severe than its rivals.
Professional and sophisticated traders tend to be intolerant when it comes to being prevented from trading without a good explanation. Plus500's customers probably aren't too excited about it either.
In March, the following was reported (the bolding is mine):
A lawsuit filed Sunday in Israel alleges that Plus500 Ltd., a London-listed financial trading company, selectively paused service customers in order to prevent them from selling options they had purchased...
Mr. Torgeman’s lawsuit claims that in the correspondence from Plus500, the company admitted to having deliberately paused trading in his account and in that of other users...
If the court accepts Mr.Torgmen’s claim, the case will come to include all Plus500 customers whose trading was deliberately halted in the past seven years.
There is also an EU law firm seeking to file a class action law suit against Plus500. It alleges the following (the bolding is mine):
Plus500 engaged in an intensive advertising campaign aimed at delivering misinformation to new clients, exaggerating the size and reputation of its platform, publishing fake testimonials boosting the company and paying affiliate marketers to create websites with fake reviews.
...Novice investors are deliberately targeted to ensure that the individual is unaware of normal practice in the markets and therefore will not challenge the unreliable broker when using the platform results in losses.
In summary, I am happy to retract my statement that Plus500 profits from client losses. It claims not to have made any revenues from principal gains on customers' trading positions from FY 2015 to FY 2017, and I am happy to take it at its word.
Instead of profiting from client losses, Plus500 profits primarily from the spread it applies to the prices offered to customers.
Risk control is achieved by monitoring the correlations of clients' net positioning, and by occasionally preventing them from trading.
Is it a bucket shop?
Some people feel that it is unfair to refer to the second largest CFD provider in the UK as a bucket shop.
I do not mean to say that the company is small or unregulated. It is big and regulated.
The definition of a bucket shop refers to how it works, not how large it is:
...an establishment, nominally for the transaction of a stock exchange business, or business of similar character, but really for the registration of bets, or wagers, usually for small amounts, on the rise or fall of the prices of stocks, grain, oil, etc., there being no transfer or delivery of the stock or commodities nominally dealt in
Except for those unusual cases when Plus500 might occasionally hedge, when its risk appetite is breached, there is no transfer or delivery of the underlying assets nominally being traded.
That makes it a bucket shop, albeit probably the largest bucket shop in the history of finance.
Let's take a look at today's news:
- MJ Gleeson (LON:GLE) - trading update
- Purplebricks (LON:PURP) - final results
- Superdry (LON:SDRY) - final results
Modern Water (LON:MWG) has also issued a couple of updates over the past few days. I have no opinion on this stock but am happy to recommend comment #14 in the thread below.
MJ Gleeson (LON:GLE)
- Share price: 782p (-2%)
- No. of shares: 54.6 million
- Market cap: £427 million
MJ Gleeson plc (GLE.L), the urban regeneration and strategic land specialist, is today issuing a trading update following the end of its financial year on 30 June 2018....
I last covered this Northern house builder in February, at its half-year report.
Looking at it again today, I am struck again by the big premium to book value in the share price. Evidently, it is being valued on its earnings prospects and not on existing value.
Its volumes have grown strongly. Home unit sales for the year are up 21% versus FY 2017.
It looks like growth in H2 this year was a bit calmer than the growth in H2 last year.
I calculate unit sales as follows:
- 2017 H1: 435, H2: 562
- 2018 H1: 593, H2: 632
There was a big jump in H2 last year. The growth since then has been at a smoother pace.
Progress is in line with Gleeson's strategic plans:
The division is comfortably on track towards achieving its 2017 stated target of doubling housebuilding volumes to 2,000 new homes per year within 5 years.
Still a long way to go to achieve this, but it is going in the right direction. Owned and conditionally purchased plots are up almost 11% to 12,852.
Potential plots in the Strategic Land division (the division that seeks planning consent for land) are up too, from 21,400 plots at December 2017 to 22,838 plots at June 2018. It also has land that could be used commercially.
Valuation: The shares are priced beyond the levels where I could consider buying them, seeing as NAV was last reported for December 2017 at 318p. Note that the shares traded below NAV during the 2008-2013 period.
That said, the company is executing well and making hay while the sun shines. NAV is increasing and dividends are being paid.
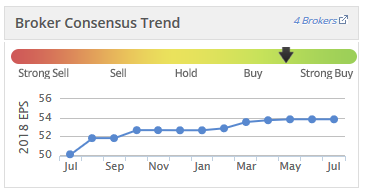
Earnings momentum has been strong:
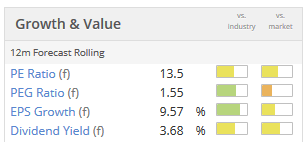
And the P/E multiple isn't too stretching, so if you think that earnings are sustainable through the medium-term then the shares don't look too expensive:
Purplebricks (LON:PURP)
- Share price: 311.3p (-2%)
- No. of shares: 302 million
- Market cap: £940 million
This hybrid estate agent is another stock which doesn't fit within our normal limits for small-cap coverage. It remains an interesting story, and has received plenty of commentary on this website, including from myself. See the archives.
Today's results show the UK breaking into meaningful profitability, converting £78 million of revenue to £6.5 million of adjusted operating profit:
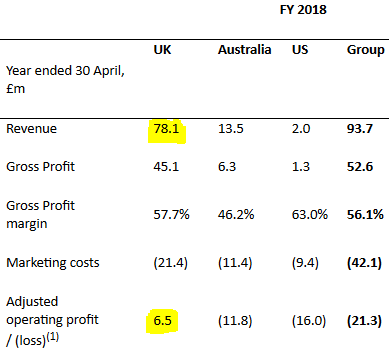
Key employees received £2.4 million of share-based payments in relation to the UK operation, so the operating profit achieved before adjustment was £4.2 million.
Worth noting that £1.7 million of costs slipped from cost of sales to interest payable, for technical reasons. If they hadn't, then I'm guessing that the operating profit for the UK would have been £2.5 million.
Of course, this is a rather small number in the context of Purplebricks' market cap - investors are anticipating serious growth, both in the UK and overseas.
H1 UK revenues (for the six months to October 2017) had been £39.9 million, so the H2 revenues are slightly reduced in comparison.
People don't like to move house around Christmas, so seasonality might be a reasonable excuse for this reduction.
The loss for the year is enormous, at £27 million.
Or if we ignore issuance of £102 million of shares, the cash outflow was about £20 million.
Thanks to share issuance, the company was left with a vast cash balance of £153 million as of April 2018.
As a result, I wouldn't consider shorting Purplebricks. The balance sheet is too strong - it will take at least a few years for it to work its way through that cash, I think. And the share price could go anywhere in the meanwhile.
With regards to operational performance, the company commissioned some analysis which concluded that it had "the highest level of conversion to sale of the top 10 estate agency brands in the UK", sells properties faster than this group and completes faster.
I do think that the Purplebricks approach is probably suitable for some properties, but I don't know if it's as high as the 10% market share being sought by the company in the medium term.
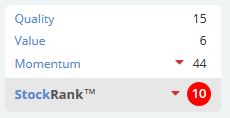
In the meanwhile, profitability in the core UK market is dwarfed by its market cap, and the international expansion is speculative. So I agree with its classification as a Sucker Stock. It might work out well for investors at this valuation, but probably not:
Superdry (LON:SDRY) issued results today, and might be worth a look a forward P/E ratio of c. 11.5x.
It has traditionally had a very strong balance sheet, and flexes its financial muscle by declaring a 25p special dividend, on top of the full-year ordinary dividend of 21.9p. Just thought I would mention it in passing.
I'm going to call it a day there - thank you for dropping by.
Kind regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Plus, IG,CMC and all the rest, these are great businesses for making money from the market and clients.
How can that be?
Relatively easy if your algorithms constantly see all the buys, all the sells, all the stops, and the underlying prices and move your bid /offer/settlement arround accordingly, add in actually halting trading....easy.
I Know this space well, 15 years in derivatives exchanges working with matching algorithm logic. The spreadbetters effectively trade their own book, it’s a form of front running, if you are a client of an exchange its illegal.
Someday I am sure this will come out, when they get into the actual detail of the matching engine, or maybe not, Flash Boys anyone?
Graham, either way I am with you on this.
That said I have owned them in the past and might again, afterall you gotta be dumb not to profit when you can front run your customer orders.
'That said I have owned them in the past and might again, after all you gotta be dumb not to profit when you can front run your customer orders.'
Not dumb but immoral...
I would not want to be a part-owner of any company that behaves this way with its customers, even if that is just an allegation.
Great analysis of Plus500 (LON:PLUS) Graham, if ever I felt inclined to short a share it is certainly now based on this. The lock out of trading for periods just brings flashbacks to the time of WorldSpreads. I was caught out by that one even after Robbie Burns openly talked of his trading issues with that site and I believe MF Global (?) also another one to hit the wall.
Whilst I was hit with WorldSpreads it was a small amount and I was fully compensated (like with the Icelandic bank IceSave) due to the government compensation scheme. With Plus500 being registered abroad I'm not sure on their licence and if people who use their service have the same compensation rights as I had with WorldSpreads and IceSave?
Whenever the subject of PLUS500 comes up and is analysed by a city insider it suffers - its a bucket shop, it doesn't hedge ....... Most also compare to IG Group as the pinnacle of what it should aspire to.
I keep on going back to the Swiss Franc debacle. PLUS500's customers lost their deposits, IG's customers lost their houses in certain cases.
No doubt someone will put me right on this.
Whether Plus500 or conventional brokers most of us have cash and shareholdings held on our behalf, indeed it is compulsory for ISAs.
Like many on these boards I have read of the problems at Beaufort and the little-known rule 135 which allows administrators to help themselves to "ring fenced" money and investments.
There is now a petition - it has passed 1,000 signatures but needs 10,000 for a reply.
You can sign here: https://petition.parliament.uk/petitions/222801
More details here: http://moneyforums.citywire.co.uk/yaf_postst5859_Protect-your-ISA-and-SIPP---sign-this-petition-now.aspx?re=56292&ea=137699
Another attack on PLUS.
I'm not quite sure why Graham is so against PLUS while holding IGG when IGG operate in exactly the same way as PLUS. Quote from IG "IG takes market risk for the purpose of facilitating instant execution of client trades. The business manages this market risk by internalising client flow (allowing clients’ trades to offset each other) and hedging when the residual exposures reach defined limits. The Group’s real-time market position-monitoring system allows it to monitor its market exposure against its market risk limits continuously. If exposures exceed pre-determined limits, hedging is undertaken to bring the exposure back to the limit."
IGG aslo often block trading in instruments and while I don't know how they compare on this I doubt the difference is much. The only time I took notice was the massive run in crypto near the end of last year. PLUS never completely closed their markets (instead taking the proactive measures of lowering available sizes and increasing spreads) while IGG closed their crypto markets for weeks.
Aside from the crypto example we also know from the past history that when the Swiss franc lost its peg PLUS didn't suffer but IGG had a large hit.
Anyway everyone should DYOR and come to your own conclusions. But taking Graham's word that PLUS are the worst of the worst while IGG are fine is something that is rather misleading.
Benjamin Graham on the "new" airline industry
It was clear in the early days that the industry would experience dramatic growth. Yet, it’s been absolutely terrible for investors.
and... Black Tulips, Tech Bubble , CFD Investing ?
Graham,
eventually they will blow up and we all know it and they know it too but why not milk it til it lasts. At that point you could always say " I told you".
As a holder of Plus500 (LON:PLUS) I appreciate all the comments and research. I have done very well out of Plus500 (LON:PLUS) so far and pay close attention to my stop. The biggest risk then is the gap down if it all goes pear shaped.
Thanks for the retraction on Plus500 (LON:PLUS) - great explanation of how the "largest bucket shop in the history of finance" makes money.
I think you are going to get more Financial PRs from other companies phoning you up now.
Keep up the good work.
Hi Graham,
Great research as always into PLUS (can someone please remind of the correct format to link epic)
I'm certainly unable to correlate 12% of professional investors producing 75% of European revenues with the massive fall off in revenue from long standing customers (who would presumably be more likely to be the professional ones) ie 47% of revenue comes from customers of 12 months or less.
This warning from Giambrone Law about using a 'bucket shop' to trade CFDs might be relevant to this discussion:
https://www.giambronelaw.com/site/library/articles/thinking-of-trading-cfds-beware-of-bucket-shops
Graham,
I agree with your analysis of Plus500 (LON:PLUS). As a novice CFD investor (gambler?) I was caught out by some of the trading issues you highlight. In a previous comment relating to Roland Head’s SIF Portfolio review of Plus500 (LON:PLUS) I explained my own experience as follows:
“I think your comment (Roland’s) ‘Plus500 (LON:PLUS) business model does seem to be dependent on a constant supply of new customers each year. Presumably this is because many customers lose money and stop trading after an initial period of enthusiasm’ hits the nail on the head! From my personal experience Plus500 (LON:PLUS) is basically a CFD gambling site and I was caught out trying to hedge a 'smallish' long position in a metals ETF (clearly outside my area of expertise!) when the price spiked hugely and they halted trading in the instrument. When they restarted trading a few days later the price opened way above my stop-loss, the position closed and I lost considerably more than my stop-loss. 'Caveat Emptor' on my part but I suspect that Plus500 (LON:PLUS) are doing so well because c. 80% of customers lose money on their transactions. As a past holder of the stock making a decent profit with various sales in 2014/15, before selling the final tranche when the share bombed in 2Q 2015 (c. 50% fall - regulatory issues) I should have kept the shares and steered well clear of the product!
I think you are right to view this with trepidation - the financials look too good to be true, regulatory risk is high, the business HQ is in Israel and the Crypto bubble must surely burst. Good luck with this one in the SIF portfolio.”
I haven’t changed my view since these comments and Graham is correct to point out some of the issues. Holders who have held the stock through the many ups and downs have done very well but I still feel it is an accident waiting to happen even though it still qualifies in Ed’s NAPs portfolio! Perhaps I should join the class action to recover my losses!!
Hi Graham,
Genuine question, would you also view the other major spreadbet / CFD providers as "bucket shops" e.g. IG, CMC, etc. ? I would be very surprised if they fully hedged their clients positions.
Presumably when IG were offering binary bets, you'd have defined that as "bucket shop" activity? Note that Plus didn't offer such a product.
It seems to me that IG & Plus are not as different as some people would like to think.
Morning Graham
2 recent bits of news from Modern Water (LON:MWG) who presented recently at Mello Derby might be worth covering:
https://www.investegate.co.uk/modern-water-plc/rns/chinese-joint-venture-and-equity-issue/201807050715046922T/
https://www.investegate.co.uk/modern-water-plc/rns/brine-treatment-plant-opened/201807040700055066T/
This is a micro-cap tiddler and has been loss making since IPO back in 2007. They have some great technology, however, and finally now seem to be close to breakeven with sales improving in both their Monitoring and Membranes divisions. The new AMBC plant in India is their first full scale commercial plant and produces ZLD (zero liquid discharge) - ZLD is becoming driven by regulation now more and more and this showcase plant will not only attract further customers in India but also China etc.
On top of that they are close to being awarded the main contract works for a new Wastewater Treatment Plant at Europa Point in Gibraltar - their technology is being used as unusually 'the Rock' uses saline (sea) water for WC flushing and hence the treatment plant needs to be able to deal with saline wastewater. This £22m contract should deliver of circa £1.5 - £1.8m profits (by my estimates) for MWG but will be a one off.
The news today of Sunup (China) planning to take a 5% stake in the company and to JV with them re: a roll out of their membrane technology across China is very good news and also assists with their cash situation which was / is very fragile. The equity raise at a premium (11p) is interesting and they are doing a 1 for 10 open offer to existing holders too.
I have been invested on and off since 2013 and like the management despite the poor track record of commercialising their technology (not helped by their previous Chairman) - new(ish) chairman is Alan Wilson from PRES.
SP up 20% this morning on the news.
Any reader comments also welcome!
What concerns me most about Plus500 (LON:PLUS) is that in all the discussions I've had with other investors / traders / spreadbetters both online and in real life, I've never come across anyone that actually uses them. I find this a bit odd for a such a big player in the market.
Hi Graham
MJ Gleeson (LON:GLE) put out a positive trading update this morning. Not as glamorous or controversial as Plus500 (LON:PLUS) in which I have no interest as an investment proposition. However I am happy to own the former and would value your thoughts.
Jonno
Thanks jonno, I've put together a few thoughts on MJ Gleeson (LON:GLE). Would be pleased to hear your views on it, too. G
Standing up for Plus500 (LON:PLUS) is a bit like admitting you voted for Brexit, you can expect trouble, but here's my 2p's worth.
Firstly there's always been a significant amount of misinformation and attempts to short this company so it's inevitable Graham picked up on some of that and got his facts wrong. He's definitely not a fan, though. I don't think for a second it was a deliberate smear or attempt to peddle a bit of fake news. From memory Graham does hold rival IG Group (LON:IGG) which I think it may have been advisable to mention here. (If that's not the case then I've got my facts wrong.) As far as apologies go, it's not the prettiest. I imagine Ed insisted on a retraction after being contacted and that didn't sit well and emotion seems to be getting in the way. The usual admirable balance is lacking here. I got to the point where law firm Giambrone were mentioned and stopped taking it seriously. If you decide to trawl the net for dirt you might want to take the take the time to dig a little deeper.
I think there are concerns with Plus but the ones being targeted here are not the key ones. Recent director sells are more concerning to me. I bought and sold PLUS last year in the belief that there was an opportunity created by the relentless negative reporting and it was my best trade ever and life-changing in a small way. Who knows what the future holds but to compare performance of the big two over the last 52 weeks: IG Group (LON:IGG) has risen from 554p to 851p, whereas Plus500 (LON:PLUS) has gone from 543p to 1751p, accompanied by generous dividends. At the end of the day it's about risk and reward. Incidentally with IG unless you choose a restricted account your losses can infinitely exceed your deposit, this is not the case with PLUS.
As Graham Fraser has stated if Plus500 (LON:PLUS) don't fully hedge then they do make money from client losses. It is not a case of "an external hedge" it is a case of directly covering the position. If a client goes long in XYZ stock then Plus is covered if they buy the shares. If they don't buy the shares then they aren't covered.
The above commentary makes careful use of the word "directly." I.e. Plus doesn't directly profit if a client loses money. That is just semantics. They either do profit or they don't. They either have a policy of hedging 100% or they don't. These things are very black and white. The fact that Plus appears to have an aggressive PR firm and an aggressive law firm is not a positive sign.
Thanks Graham. Interesting discussion but the Company PR response seems to be semantics rather than substance.
Using correlation trading is great in “normal” market conditions when market liquidity, counter-party risk and spreads are in the bounds of historic experience but goes completely t**ts up when the market blows up. Used to work close to a group of Quants on a City trading desk that built a sizeable “hedged” book based on correlation trading of Asian equities. Made an arbitraged fortune “risk free” for a while the blew up in spectacular fashion in the 2008 crash. Lost 10’s of millions. No doubt it will be different this time ....
Gus.
Good morning Graham, a great commentary on Plus 500. Thanks. I don't understand why you had to retract your comment that they make money when a client loses money. That is exactly how they make most of their money !
As they say, they only hedge when their risk appetite is exceeded.
Therefore one can safely assume that the vast majority of clients' trades are not directly hedged.
Let them prove otherwise if they can !
Cheers,
Graham
you don't get it, either. You are only looking at one side. Their clients also win 50% of the time....
Thanks Graham for the great Plus500 (LON:PLUS) commentary, most useful - I stay away in fear of it all ending in tears!
My morning smallcap tweet: Non-linear BS paradigm
Elecosoft (LON:ELCO), Boxhill Technologies (LON:BOX), Utilitywise (LON:UTW)
Elecosoft (ELCO) acquires Shire Systems for £6.3m cash. Shire Systems 2017 rev £1.9m, profit before tax £0.7m. Will be earnings enhancing in H2.
Boxhill Technologies (BOX) warns - "a substantial decline in certain payment processing revenues during May and June due to a requirement by particular banks to change the nature of transactions they are willing to deal with following regulatory changes. The Company are progressing a number of actions to address the issues." So they were aware of the issue in May!
Utilitywise (UTW) Strategy Update. Adds 2 new financial targets. "Underlying Free Cash Flow of the Group of at least £10m in FY21; and Group net cash position by 31 July 2021, with the path to that position being non-linear to allow for, in particular, investments during the year ended 31 July 2019." Non-linear = don't expect much improvement soon. Expect to see inflexion point, tangential, exponential and other words from the Dummies Guide to Clever Sounding Bullshit in due course.
Good morning everyone. Good if small news from Seeing Machines (LON:SEE) this morning, 'the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety, has signed a five-year contract with US based John Christner Trucking to install its fleet of 850 trucks with Guardian, the Company's fatigue and distraction prevention technology for commercial fleets.' The contracts keep coming and I am holding for a takeover but would love to hear the bull/bear case. Paul sold out a while back wondering if they could make it big, I bet he's sad he did but it's more important in the long run to maintain discipline in your stock-picking technique. I am worried about one of the big boys duplicating the tech, but also hopeful they might buy it for spare change, so my position is moderate.
runthejoules,
Seeing Machines (LON:SEE) is not a "Small Cap Value" share and while its announcement today doesn't mention revenue, as far as I can see it isn't material. Therefore I wouldn't normally discuss it here. However, it doesn't take much to get me started :)
The question in my mind is why they released such minor news as an RNS. I suspect the reason is remind the market that there is more to their business than (indirect) sales to car manufacturers (OEMs). While this is legitimate I then wonder whether this implies they are not expecting an imminent material announcement on the OEM side and don't want to go too quiet.
Whatever the reason, the share price is heavily dependent on newsflow and rumour, dropping back at the slightest lull. This makes makes them inherently risky to hold, especially over holiday periods when business decisions are less likely to be made. Versarien (LON:VRS) is a more extreme case of the same phenomenon.
It also makes SEE risky to not hold (or be short) as an apparently major announcement could cause a big price movement at almost any time. The fact that it has been possible to buy at a good price in reasonable quantity in the morning of previous big announcements may provide some reassurance here, but may also increase the speed of future spikes.
Notice that I have said nothing about fundamentals? That is because they currently provide no support. Certainly I can (and have) extrapolated a future scenario where the current valuation (and much more) is supported by fundamentals, but unless / until this firms up it is a highly speculative investment / punt and I would urge extreme caution.
Finally, there is some not entirely one-sided and not entirely banal discussion on the London South-East board, and especially in the absence of any material news I feel that is probably a better place to get a feel for the drivers of the share price than here.
The question in my mind is why they released such minor news as an RNS.
They didn't - they issued it as an RNS-Reach which is for non-regulatory information see:
https://www.londonstockexchang...
The problem is that on most systems delivering RNS the difference is not obvious. On investegate it is indicated by a dark grey rather than black background to the white letters RNS and that may or may not be visible depending on your screen quality/size/contrast. Here on Stocko there is no indication at all. The only obvious place is LSE itself:
https://www.londonstockexchang...
Hi Graham
Thanks for that opening response on Plus500 (LON:PLUS) - very informative.
I had a follow-up query I was hoping you, or anyone else, might be able to provide, regarding a profitable trading days graph published by the company last year.
Graph below for convenience (and LINK here if you'd like to see the whole presentation - the graph is on page 21):
Based on what you've said I'm surprised to see the large (crypto-related) loss days towards the end of 2017.
The first spike of -$4m in October might make sense, but one would think Plus500 (LON:PLUS) wouldn't allow themselves to be so exposed afterwards.
However, I see several -$3m days in December. Based on what you've said, I don't understand how this makes sense (or perhaps I'm just not understanding it). Surely Plus wouldn't have allowed themselves to be in a position to make such extreme losses...unless they do take on risk?
Thoughts, from anyone, appreciated.
A
Graham
I agree that Plus500 do seem to block opening trades sometimes when their positions are too large (not sure if that is the case with closing). But I don't see how that is covered in their wording as it only says that they can stop trading when "market events restrict price feeds" in various different ways. It doesn't say they can stop it for other reasons. So I'm not sure how you see in their wording that they can stop trading for any reason.
Are you sure you want to use Giambrone to help make your case?
Great commentary Graham..it’s good to get the facts out in the public domain..