Small Cap Value Report (2 Mar 2015) - DIA, NBU, COMS, SEE, THT

Good morning!
Dialight (LON:DIA)
Share price: 732p (up 10.8% today)
No. shares: 32.5m
Market Cap: £237.9m
(disclosure: I have a long position in this share at the time of writing)
Final results for the year ended 31 Dec 2014.
It strikes me as odd that the market has reacted so positively this morning (the share is up nearly 11% today) to results which are only slightly above expectations. Indeed, the company flagged on 16 Jan 2015 that it was trading in line, and I reported on the company that day, saying I thought it looked good value at 789p. So it was utterly perplexing why these shares took a dive down to around 600p in recent weeks, only to come back up again!
I know shares fluctuate in price all the time, but that is usually driven by changes in the company's performance or outlook. There haven't been any such changes here to warrant such price gyrations, so I remain perplexed!
Actually, thinking about it, I wonder if the recent change in CEO might have given some shareholders the willies? Judging from today's results, there doesn't appear to be any underlying problem.
Earnings - up 20% to 36.8p (broker consensus is for 35.9p, so a small beat there). Note that the company has been a bit cheeky in classifying a £2.8m inventories writedown as non-recurring. This means prior year profits were effectively overstated by £2.8m. I generally find the accounting policies at this company a little too aggressive, e.g. they capitalised £3.5m in development spend in the year, which was well above the £2.3m amortisation charge for the year, thus providing a boost to profits.
Valuation - at 732p the PER works out at a rather warm 19.9. However, with EPS forecast to rise again to 45p this year, then the PER would drop to a more reasonable 16.3. If earnings continue rising in subsequent years, then the shares might end up looking cheap in a couple of years' time. Although if there are any nasty surprises between now & then, the price could take a tumble. This is the problem with almost everything at the moment - valuations look pretty full, and don't factor in any downside risk.
Balance Sheet - Dialight sails through all my balance sheet tests with plenty of room to spare, so it looks a safe share in terms of financial strength. Borrowings are low at £7.3m, and are offset by cash of £7.9m, so it ended 2014 with net cash of £0.6m.
Dividends - total divis for the year were hiked a modest 4%, to a total of 15.0p for the year. That's a yield of 2.0%. With such a strong balance sheet, the company has scope to pay more, I would say.
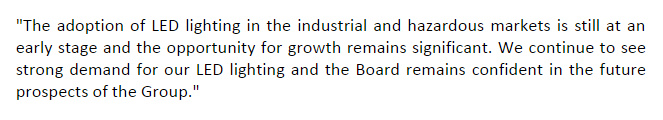
Outlook - sounds positive, but with no specific detail;
My opinion - I quite like this stock, as it is operating in a growth area of LED lighting, for industrial use. So they supply the very bright lighting that you now see at overnight roadworks, for example - those huge, very bright overhead lights which make it almost as bright as daylight on a cloudy day.
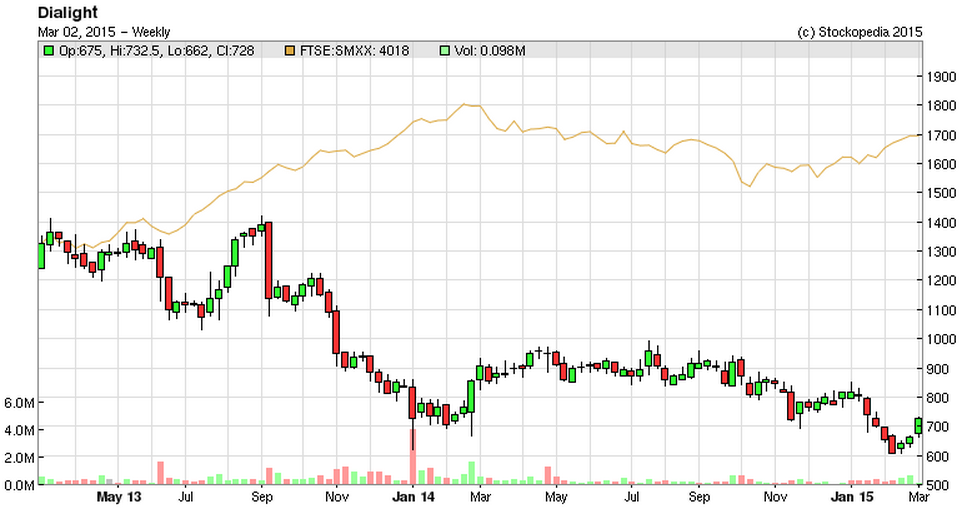
The shares have been much more highly rated in the past, and the strong growth being demonstrated now surely justifies the historic PER of just under 20. It's financially sound, and pays a growing divi. Not exactly a bargain, but seems reasonable if the growth is set to continue. As you can see from the two year chart above, the shares have been in a downward trend, scrubbing off a previous over-valuation, whilst the market as a whole has risen over the same period.
Naibu Global International Co (LON:NBU)
I'll keep this brief, as the shares are suspended, and unlikely to return, in my opinion.
If you recall, this is the Chinese company where the UK Non Execs recently said that management were not responding to their request for information about the company. Well the reason might be because it is alleged by investigative journalist Tom Winnifrith, on ShareProphets, that the CEO is in prison!
Apparently the Chinese authorities are cracking down on businessmen who damage China's reputation by behaving badly abroad. Is that a stable door I hear swinging off its hinges?! The horses are long gone!!
It will be worth waiting for the next comedy announcement from the Non Execs to explain this one away. People cannot say they were not warned.
Coms (LON:COMS)
Resignation of CEO - another saga here, that I reported on last week, so an update today. The CEO has withdrawn his EGM requisition, and himself resigned. It sounds a tricky situation. My reading of the accounts suggests that a fundraising is extremely urgently needed, so expect news of a discounted Placing in about 3 or 4 weeks't time maybe?
The matter of the former CEO making a shares purchase when he shouldn't have done is updated, with this bizarre "explanation", which doesn't make any sense at all to me. Is he perhaps hinting at having been in some kind of transcendental trance when he instructed his broker to buy the additional shares, and thus his conscious mind was not aware that he had bought these shares?!
Nothing that happens on AIM surprises me any more. It's getting more ridiculous by the day.
Seeing Machines (LON:SEE)
Share price: 5.25p
No. shares: 941.0m
Market Cap: £49.4m
(disclosure: I have a long position in this share at the time of writing)
Interim results for the six months to 31 Dec 2014.
This is a tricky situation to assess, because the company is mainly jam tomorrow. However, it is also delivering a little jam today! Its eye and face tracking software (which prevents accidents by alerting drivers who are falling asleep, or distracted) is currently being sold to the mining sector - a limited market, for the very large yellow trucks that are used to move large quantities of earth & rock.
However, the jam tomorrow potential is across multiple markets, mainly trucks & coaches, trains, aircraft, and the biggest one of course in due course could be cars. On top of that, the company also has a deal with Samsung to develop the product for consumer electronics.
So how on earth do you value it? In my view the only rational way is to guess what sales might grow to in these sectors, and then try to estimate a value based on that. This makes the current figures almost irrelevant, although I'm wary of saying that, as last time I thought that was with Tungsten (LON:TUNG) and the shares then dropped heavily, as investors took fright at heavy short term losses, and opaque future potential.
Results - turnover rose 41% to £4.8m (I am converting these figures using Aus$1 = £0.51) for the six months, although it's worth noting that a good chunk of the top line has come from forex gains, and what looks like R&D tax rebates. Excluding these items, turnover was quite small at about £2.8m for the six months. Still, it's a start - and in my view, the product clearly works, and if they can generate that level of turnover from a relatively small sector (mining trucks) which is in the middle of a big capex squeeze, then what might the potential be from the vastly bigger road transport markets?
Loss - this works out at £2.2m loss for H1, and the narrative refers to increasing development spending. I would prefer two columns for the results - one showing the trading in the mining sector, and the other showing development spending for other sectors, as merging them doesn't really tell me very much - the loss can be anything management want it to be, as it depends mainly on what pace they crank up development spending.
Cash - as with all loss-making companies, cash is king. The company had £10.8m in cash at the end of the period, and looks to have burned through about £8.0m in the last 12 months (taking figures from the cashflow statement). Therefore it looks to me as if the company will need to look at another Placing & Open Offer late in 2015 or early 2016. That's not necessarily a problem, if it coincides with good progress having been made by the company, and the market being receptive to jam tomorrow stocks.
Outlook - there are interesting developments imminent - especially their DSSFleet product, which is on track for launch imminently, in Apr 2015 - for road transport. This product could end up being pushed by insurance companies, as it should prevent some road accidents, and hence not only save lives, but also reduce claims against insurance policies. We know the product works, as it's being sold successfully in the mining sector.
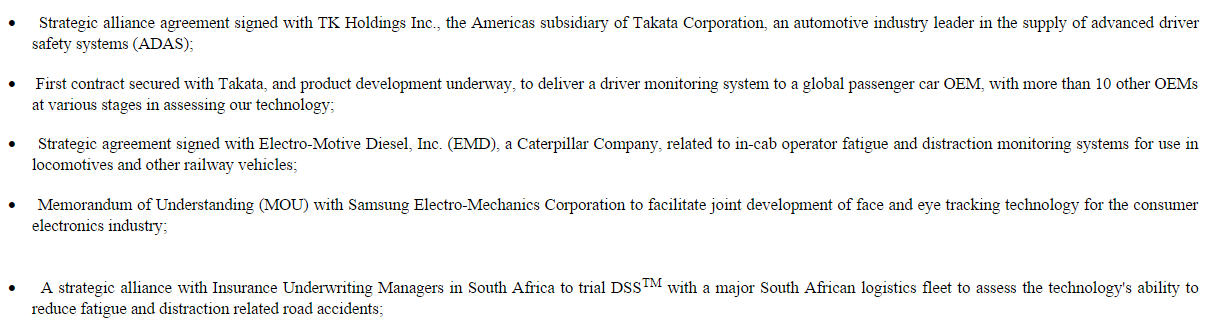
The third party development agreements look impressive too, giving further third party confirmation of the narrative from the company itself;
My opinion - this looks one of the most convincing jam tomorrow shares I've seen in recent years, because it is already selling a version of the product in a niche sector. How to value it? It's a finger in the air jobbie at this stage I'm afraid. If it takes off, then we could have a multibagger on our hands. If it doesn't, then the company could scrape along, diluting shareholders with more fundraisings at lower prices along the way, and perhaps never make the big commercial breakthrough?
Newsflow in coming months re the DSSFleet product will I think be crucial, and give an important pointer as to what the future might hold.
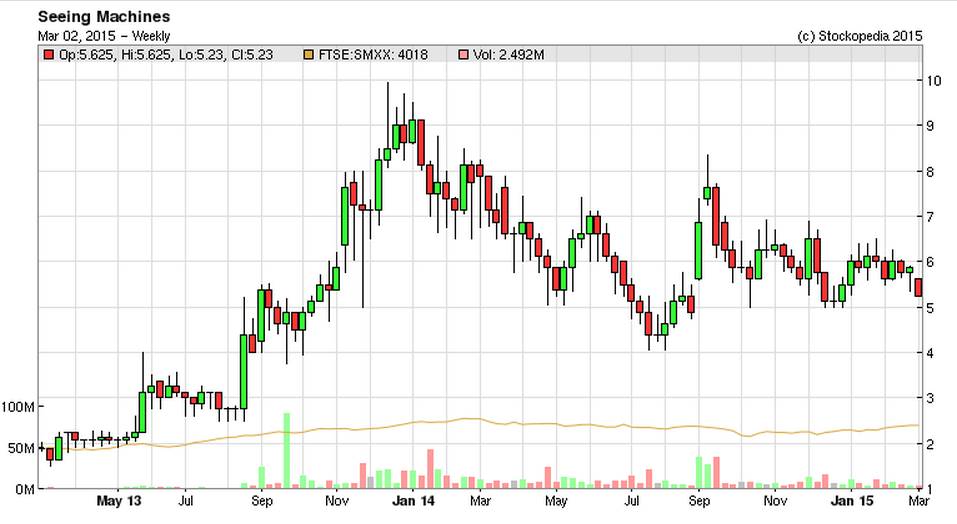
As the chart above demonstrates, it's all about timing with this type of share. If you buy when everyone is terrifically excited about the potential, then you're more likely to lose money. If you buy when everyone is nervous, and doubting it, then that can either mean the story has become stale, and is going down the pan, OR it can mean that you're getting in at a favourable entry point. Trouble is, we never know which it is until after the event!
I like this one though, hence am happy to hold, whilst appreciating that it has to be considered quite high risk. What do readers think?
Thorntons (LON:THT)
Share price: 70p
No. shares: 68.9m
Market Cap: £48.2m
Interim results - covering the 28 weeks to 10 Jan 2015. It's surprising to note that Thorntons appear to split their results into a 28 week H1, and a 24 week H2. I'm surprised that is allowed actually, and it's not something I can recall ever seeing before.
I have seen companies add an extra week onto a year occasionally to reflect the fact that 52 weeks is 364 days, so roughly every six years you will have ended up slipping back a week, if you report using 52 week periods, instead of 12 months. However, to report different length H1 and H2 every year (I checked back, and they did the same in 2014 and 2013 - 28 week H1) is bizarre - presumably their reason is to make stock-taking easier after new year?
Let's hope this isn't the start of a new trend for companies reporting interim results prepared on any date they feel like?
Trading - the company has already warned on profits, so reporting H1 profit a bit down on last year should not come as a surprise to anyone who has been paying attention!
There is pronounced seasonality here, with H1 approximating to a full year's profit, with H2 around breakeven typically, judging from recent results.
The problem here is that the company's strategy has hinged on them reducing their retail operations, and concentrating on building up being a FMCG supplier to supermarkets & other retailers. That seems to have gone a bit wrong, with apparently two large accounts causing them problems, and resulting in a decrease in the FMCG division's turnover by 11.2%, whilst the retail division seems to be performing quite well, with LFL sales up 2.2% (including an "outstanding" performance over Xmas with sales up 7.8%).
Another 20 stores are due to be closed, which should help profits, as presumably they are all loss-making, otherwise they wouldn't be facing closure. Or rent reviews would perhaps make them loss-making imminently.
EPS - basic EPS fell from 7.8p last year to 7.2p for the most recent year.
Valuation - at 70p per share, the valuation is a PER of only 9.7, which would begin to interest me, if the balance sheet was sound. Trouble is, it's not...
Balance Sheet - two specific problems here - there's too much debt, and a nasty pension deficit.
Net debt - this looks too high to me, at £30.8, which is up a whopping £11.0 versus the same period last year. Both inventories and debtors are up considerable in the last 12 months, which they shouldn't be, given that turnover is actually down. That suggests to me that maybe those pesky supermarkets are putting the squeeze on everything - not just profit margin, but probably also taking longer to pay Thorntons invoices, and requiring them hold more stock for them to call off when they want to.
Pension deficit - a lot of companies are reporting enlarged pension deficits at the moment, as low bond rates mean that liabilities have grown when discounted to present value using the lower interest rate.
Thorntons shows a £36.7m pension deficit on its balance sheet, but the actuarial figure is probably quite a bit worse, they usually are. The company says that cash overpayments are rising;

£3.25m p.a. being paid into the pension fund is a big old lump of cash, and that's money that is not available for paying as divis.
Dividends - no divis have been paid since 2011, and the company today says it wants to resume divis, but not just yet.
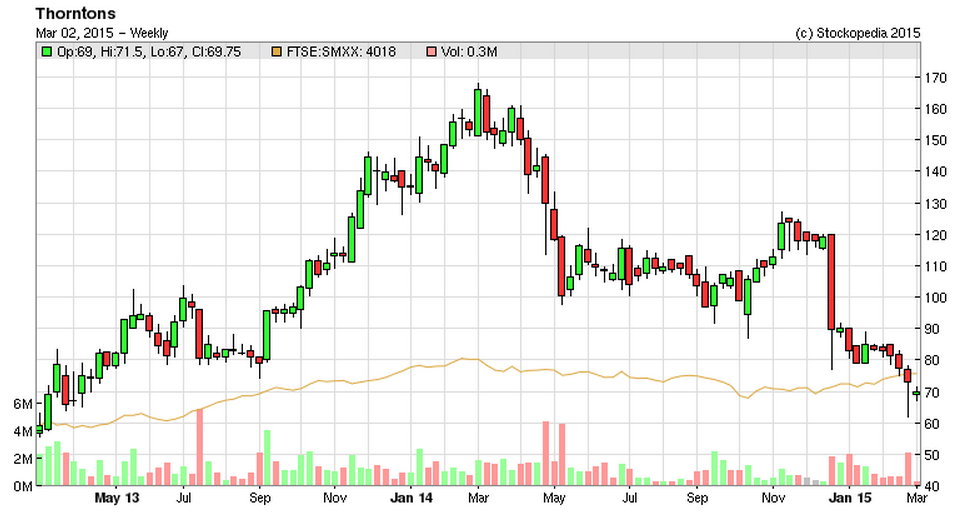
My opinion - it's starting to look potentially interesting at 70p, but it's always the balance sheet that puts me off here. Also, the FMCG strategy seems to have hit the buffers, and it's difficult to see them being able to make any progress against the supermarkets. More likely to go backwards, I would guess.
Overall then, with little prospect of sustainable divis happening any time soon (or ever, actually), I'm finding it tough to get excited about Thorntons. If they fixed their balance sheet, with a (say) £30m+ equity fundraising, then I might consider it. Overall though, as a low margin business with limited growth potential, it's probably not cheap, even after the share price falling a fair bit.
Although there could be scope for the shares to come back up again, if trading improves.
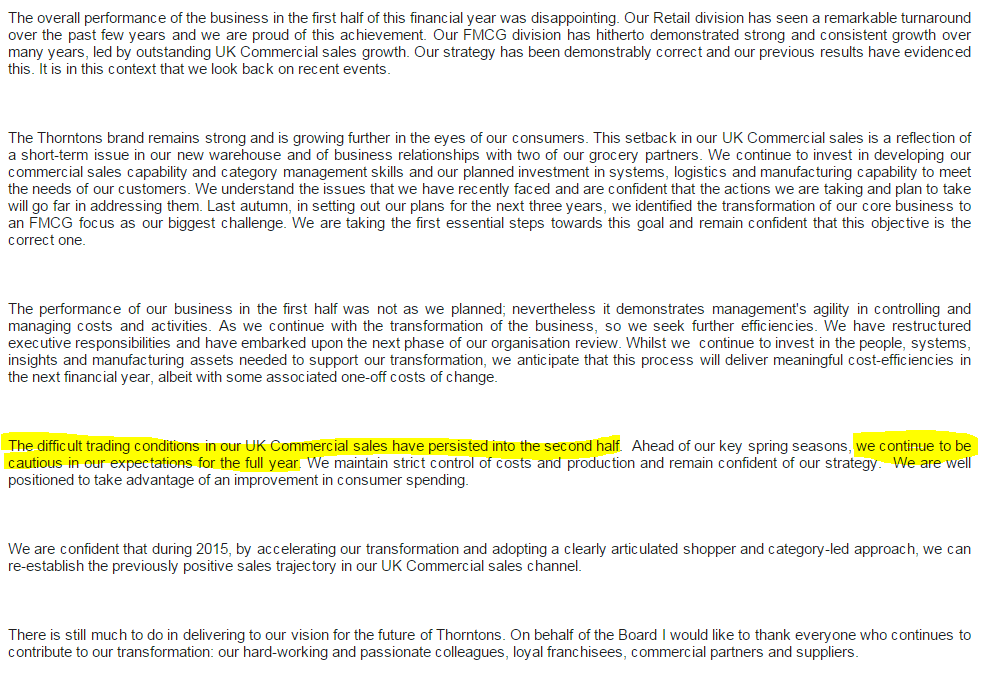
The Directorspeak today doesn't sound very upbeat though, here is the long-winded outlook statement today;
All done for today, see you in the morning, as usual.
Regards, Paul.
(Personal positions held by Paul are as disclosed in the article above. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Maybe they could apply the scoring system from Death Race 2000 :-)
Albeit I find him highly entertaining at times, I am slightly loathe to write this. but I thought that on Top Gear on Sunday, Jeremy Clarkson made (repeated from elsewhere?) some very valid points about driverless cars. Specifically, in a situation where the car cannot avoid being involved in a serious accident, but can effectively choose which parties suffer the most serious injuries (the person inside the car, drivers in other vehicles, pedestrians including groups of children), what should its rules be for the decisions it makes. One could see this leading to very lengthy legal cases.
This looks similar to existing health and safety dilemmas. A regulator or parliament can mandate society's preferred choice for anything controversial and then the vehicle manufacturers implement that in their algorithms. You could even have the car download local rules when it crosses jurisdictional borders.
There are numerous drive-by-wire advances out there now, e.g. throttle by wire (cruise control), brake by wire (anti-tailgate control), steer-by-wire (parking control systems), etc.
All of these technologies threaten SEE's proposal as they allow the car to recognise that it's heading for trouble before the driver e.g. too close to car in front or heading for obstructions. Why bother about checking if the driver is nodding off when you can prevent a crash due to drowsiness, alcohol levels or sheer incompetence by looking at external factors.
I think driverless cars are a fantastic idea particularly for the elderly who often lose independence when/if their eyesight fails.
I listened to the CEO of Mercedes recently suggesting they have the technology for driverless cars today. In fact recently 4 cities in the UK tested driverless cars. The CEO said one of the main issues was who would be liable if there was a crash the manufacturers or the owners? He suggested this was one of the biggest hurdles left and driverless cars were 10 years away. With this in mind I watched the CEO on the net and his response to the question about driverless vehicles was more than a little unconvincing. I like the story and was long these shares but this question is so central to the investment case I think the opportunity is a short window and so cut my losses having bought in at 6.25p.
Re driverless cars - I think it will be many years before driverless cars are widespread on the roads. Even then there will be many millions of conventional cars around. Who knows, insurance companies might eventually make fitment of SEE's product mandatory? It does seem crazy that at present cars don't monitor driver alertness at all.
So SEE probably has a 10-20 year window to potentially make a lot of money, which is plenty for the stock market to afford the company a decent valuation. After all, newspapers will probably have died out in 20 years' time, but Trinity Mirror (LON:TNI) and Johnston Press (LON:JPR) still have quite decent valuations. So I think it is possible to get too clever about trying to anticipate the reversal of future trends that haven't even started yet!
I'm in two minds about the 10-20 year window. R4 recently covered some poc testing on British roads. The main issue was the margin of safety - for example a driverless car would probably never overtake a cyclist on a busy road, hence causing tailbacks, frustration etc. This problem goes away on motorways though, which is where drivers at greatest risk of nodding off.
Hi Paul, Seems many have missed the $11m in Inventory on seeing machines which i believe is the fleet order. As for some of the comments above SM has patented technology so it cannot be copied, its also 2-3 yrs ahead of its nearest rival in development, and major car manufacturers are having to decide now who they use to fit in with go to market dates. Driverless cars are 40 yrs away and even when we have them there will be a requirement for the driver to remain alert. Google are far more likely to buy a company like this than try to copy it.
I get a bit confused when Paul refers to capitalising development costs as an 'aggressive' accounting policy. Under the old UK accounting rules, you used to have the choice over whether or not to capitalise, but as all listed companies now report under IFRS, I think this choice has been removed and it's now mandatory to capitalise these costs as long as you can be reasonably sure the spend will lead to future benefits.
Hi bestace,
Companies still have enormous leeway under the new rules, to decide whether or not to capitalise development costs. The ones that decide to capitalise want their profit figure higher, and the ones who still write everything off, are more prudent. That's the way I look at it.
Preparing financial statements generally involves many judgment calls, so profit can be within a surprisingly wide range, depending on how prudent or aggressive mgt want to be.
That why audit reports refer to "A true & fair view", not "THE true & fair view".
Regards, Paul.
I have been following SEEING MACHINES for some time but can't bring myself to buy in for the simple reason that if the world is going down the 'Driverless vehicle' route then why would they want the technology that SEEING has and is developing? What am I missing?
Have you taken a train lately? Did it have a driver? Driverless train technology has been available for a couple of decades, but adoption is still probably a low single digit percentage. Driverless cars -- nowhere near as easily solved a problem -- will likely take a long time before they get widely adopted, so there's plenty of space for driver monitoring in the meantime.
Besides the rise of the machines means more automated functions to supervise, with more bored supervisors to keep awake.
Hi Paul, agree on SEE, on the face of it a pretty run of the mill statement, but the transition to more consistent revenue is a positive development. It’s one where a lot of patience is required to say the least! If it was just a one tricky pony I’d be less bullish, but the application of tech to 6 different areas means they can have fingers in lots of pies and tailor they’re development accordingly. The line below stands out to me but obviously 'huge interest' is one thing, hard fact another:
‘We are seeing huge interest in our technology from other car makers, as part of their development plans for ADAS - Advanced Driver Assistance Systems. This will be a strong focus over the coming year.’
Thanks for your insight as usual.
James
Seeing Machines - i know little about the company but i don't believe that someone like Google couldn't copy their technology, or develop their own pretty quickly - given they have google glases now etc.
Not enough promise for me.
Shaun
Hi Paul,
Seems my message has disappeared. ANyway any view on SNTY which has dropped by 15% lately.
Hi herbie47,
I only comment here on results/news/updates from companies, not speculating on the share price movements between announcements.
Regards, Paul.
Re Dialight (LON:DIA) i took the opportunity this morning of a strong sp rise to liquidate my position. Basically broke even. IMHO the risk reward ratio is wafer thin and there are better prospects elsewhere. Prefer boring to roller coaster rides!
Ram
Yes hard to justify risk in Dia for 2.9% yld with all the downside factors already mentioned when one can have a high yld (USA ) corporate bond etf ylding 5.8 % ....SHYU......exactly twice the yield for less risk.
Hi Paul
Given your comments about DIA and the £2.8m effect to 2013 profits along with £1.2m difference in capitalised development costs and amortisation plus the £300k pension element not taken into P&L, should the new CFO be asked directly to comment and explain? Does he intend to continue with same accounting philosophy going forward as clearly he was not in place at time of last final results?
Ref share price this has often moved quite erratically on usually on relatively small volumes and this seems strange for a FTSE 250 company with solid performance record and realistic growth prospects. even taking into account mis-placed optimism that recently took the price towards £14 - a point Roy Burton acknowledged in last video presentation when he said the company needed to be more prudent in the way it advised the market about future opportunities.
Peter
About time China did something - the behaviour of some of those companies listed on AIM most certainly tarnishes their countries image as I can testify
Nigelo, YES, YES, YES!
Followed by a few bankers!
Paul Any chance of looking at £PPHE finals today please? Last march you gave them the thumbs down over their balance sheet?
Hi iwright7,
Sorry, I didn't get round to writing anything on PPHE Hotel (LON:PPH)
I did have a quick look at the results, and they seem impressive, with earnings up strongly. There's a reasonable divi yield too, of about 3.3%. I'm still not sure about its balance sheet though, in particular the large creditor which seems to relate to some apartments?
In a low interest rate environment, where credit is easy, the company seems to be doing fine. It would be essential to check out the terms of the debt - what interest rate fixes or caps are in place, duration of the facilities, etc.
Some friends whose judgment I respect have been enthusiastic about this share for some time, and they've been proven correct, looking at the chart! So am not sure I have much of any value to add here really. I feel I've missed the boat on this one.
Regards, Paul.
Nigelo & Jane
I think the recent announcement that Aviva traders were deciding where to allocate trades after they saw how they were going is another example - and so clear cut.
The only justification that I can see for the refusal to name them is that they will face criminal proceedings and Aviva/FCA want to do nothing that might prejudice these. But I wouldn't bet on it.
Former Morrisons Treasurer jailed for insider trading:
http://www.insidermedia.com/insider/yorkshire/134782-former-morrisons-treasurer-jailed?utm_source=breaking_news_newsletter&utm_medium=top_story_article&utm_campaign=breaking_news_tracker
You have to start somewhere!
Thanks Jane
This is a rare example - but if it heralds a new approach, that would be great. We don't know when he was caught - but it's still taken 18+ months to b ring to court. I've nothing against him personally, but it would also send a powerful message if he had to serve his (shortened) term in a proper prison.....
Wouldn't it be good if the police looked at some of the price movements ahead of announcements.
And maybe some of the recent announcements of director purchases, that were actually sales.....
I wish the UK authorities would take a leaf out of the Chinese book and imprison a few of our dishonest directors (and their complicit advisers) . Perhaps they could start with those who said they were buying shares in their own companies when they were actually selling and claiming to still have an interest in the sold shares.
BPI net pension liability jumped from 46.6m to 83.9m..
Hi Paul - do you have any thoughts on the Seeing Machines (LON:SEE) interims issued this morning?
Best wishes,
Imran.
Hi Paul
I agree there accounting seems to be aggressive. In addition to the points you covered above they also made an additional £300k in pension contributions which weren't expensed through the P&L account. If you combine this with £1.2m (difference between capitalised development spend and amortisation), as well as the £2.8m inventories write-down amount this is a material amount.
The cashflow statement is also a worry in that cash generation only increased by £0.6m for the year, and divis are largely being funded from the bank facilities. If you look back at the stock report, net cash has been falling over the last 4-5 years which is also a concern. Based on the Stock report EPS is projected to increase quite significantly, but the outlook statement sounded vague, and I think there's quite a lot of wiggle room.
Overall I think it's a capital intensive company, on a relatively high PER, and any slowdown in earnings is likely to hit the SP quite hard. I'm finding it hard to get excited about the company.
Even without the contingent consideration they still needed to borrow for the dividend which is a worry.