Small Cap Value Report (22 June 2021) - CGS, G4M, SAGA, CRPR, MCL, TRI

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Timing - TBC
Agenda -
Paul's section:
Castings (LON:CGS) - brief comments from yesterday's results webinar.
Gear4music Holdings (LON:G4M) (I hold) - so far so good! Sparkling results, boosted by lockdown, as expected. Current trading better than expected, and brokers upgrade forecasts by c.50% for the current year. A coffee can, hold forever stock, in my opinion. Still reasonably priced too.
Saga (LON:SAGA) (I hold) - financing changes proposed. I see this positively in principle, moving riskier bank debt onto safer, longer-term (and covenant-free) bonds. This would also provide another £80m of cash headroom, which is already ample, per trading update last week. I remain firmly bullish on this share, with a personal price target of 1000p in due course, I explain my workings & rationale below.
James Cropper (LON:CRPR) - I quickly review the FY 03/2021 results & commentary. Not madly exciting.
Jack's section:
Morses Club (LON:MCL) - Q1 performance is ahead of budget and impairments are within the expected range. Covid investment in tech could drive further growth down the line.
Trifast (LON:TRI) - full year results impacted by Covid but conditions are improving and the group is investing for future growth.
Paul's Section
Castings (LON:CGS)
Results webinar yesterday
Many thanks to Alex at Yellowstone Advisory, who organised a results webinar (and provided a link for us to join here, in yesterday's reader comments)from this interesting iron foundry/machining group based in the UK Midlands. It certainly increased my understanding of the business, and it's always good to get a feel for what management of any company are like. Castings management struck me as down-to-earth, hands-on managers, which is what I like.
A few key points I jotted down -
Potential for M&A (acquisitions) - looking especially at the electric vehicles sector suppliers.
Customers disagree on which technology will become prevalent for trucks - electric batteries, or hydrogen.
Considered a special dividend for surplus cash, but decided against it due to macro uncertainty (have done special divis in the past, something I hadn't spotted)
Pension scheme should be de-leveraged (?) this year - I didn't quite follow this point, but it sounds like they're gradually eliminating the pension deficit. Can anyone clarify this point?
Competitive advantage - Castings makes small batches of products to order for its customers, using efficient high tech equipment. This gives it a competitive edge. Would struggle to compete on large scale projects. Produces up to 2,500 product lines.
Research notes are available from Arden's website. You need to register, but can then view all their research.
My opinion - Castings shares look very good value to me, especially when you adjust out the net cash. However, heavy reliance on customers within the EU (mainly truck manufacturers), puts me off, because if Brexit turns sour, then there could be trade barriers for exporting to the EU - too much of a risk for me.
Gear4music Holdings (LON:G4M)
(I hold)
960p (up 3.5% at 08:54) - mkt cap £201m
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its financial results for the year ended 31 March 2021.
As we already knew, from repeated upgrades last year, G4M has traded exceptionally well, helped by lockdowns, which drove increased demand for musical instruments, particularly lockdown 1. Key numbers - which look in line with the last update (April 2021) from broker N+1 Singer -

However, whilst lockdown(s) helped, G4M is also a structurally growing business. The challenge has been to estimate how much growth is one-off, and how much is likely to be sustained? As commented before here, my view is that existing broker forecasts for the current year FY 03/2022 seemed way too pessimistic, e.g. N+1 Singer was forecasting adj EPS to fall to just 20p (from actual FY 03/21 adjusted EPS of 60.4p, per N+1 Singers note published today). That seemed an excessively pessimistic forecast.
The good news is that current trading is ahead of expectations, and FY 03/2022 guidance has been raised today -
However, trading in Q1 FY22 has been stronger than the Board previously expected and, having retained a good proportion of the gross margin gain achieved during FY21, financial results for FY22 are likely to be ahead of the Board's previous expectations.
Although we are reminded not to expect a repeat of FY 03/2021 sparkling results -
Given that the FY21 exceptional financial performance was driven by the initial COVID-19 lockdowns during H1, the Board does not expect to meet the same level of trading during H1 FY22, and as previously guided, does not currently expect to achieve the same level of full year profitability during FY22 that the Group achieved during FY21.
Forecast upgrades -
Both Progressive, and N+1 Singer have substantially upgraded their forecasts for FY 03/2022, so we were correct in believing the previous forecasts to be excessively pessimistic.
New forecasts for this year (FY 03/2022) are:
N+1 Singer old: 20.0p, new: 30.3p adj EPS
Progressive old: not sure, new: 29.0p adj EPS
N+1 notes that the raised forecasts are prudent, with forecast risk to the upside.
Personally, I’ve pencilled in about 40p EPS for the current year, which would put the PER at about 24, which looks good value for a structurally growing eCommerce business, that is executing well in Europe, as well as the UK.
The massive USA and possibly Asian markets could eventually follow perhaps?
Further European expansion - new distribution hubs are to be opened in Spain and Ireland
Acquisitions - in the past G4M has concentrated on organic growth, but is now talking about bolt on acquisitions. That makes sense, in a fragmented market, this could be a good way to pick up customer lists, and brands, on the cheap.
2 actual brands have been recently acquired - “Premier” (premium drums & percussion), and “Eden” (premium bass amplifiers). This is an interesting development. Margins are tight in this sector, so increasing own brand sales, raises margins considerably - own brand gross margin is 47.0%, and other brands (the bulk of sales) are 28.4%. I reckon the key to success is to shift more own brand product, at higher margins, hence acquiring brands seems a great strategy, if they can be acquired at modest cost.
Balance sheet - is strong. A new £35m credit facility from the bank opens up opportunities for more acquisitions, and more rapid expansion.
There’s a freehold head office in York of £7.35m in fixed assets, which I like.
NAV is £34.3m. To view it more prudently, deduct £10.4m intangibles, leaving a healthy £23.9m NTAV - a healthy position.
G4M has to keep a very large number of items in stock (SKUs are now up to c.60k), so it’s important that the balance sheet is strong, to support the large inventories.
Net cash was £2.7m, with most debt having been cleared from the bumper profits in the year (Gross cash is £6.2m, less £3.5m gross debt). Hence there is bags of headroom on the £35m revolving credit facility, giving scope to make more small bolt on acquisitions.
Cashflow - this bridge graphic neatly explains the numbers -

Dividends - none so far, but will be reviewed annually. Personally, I don’t want divis, I’d much rather G4M keeps investing in expansion & buys more brands. That’s a far better use of capital than divis.
My opinion - I’m delighted that the current trading is strong, against the toughest prior year comparators (in lockdown 1). In my view, there’s clear scope for further upgrades as this year progresses - the bar has been set too low, and getting an upgrade just 2 months into the new year is clearly a good indicator.
My feeling, reading through today’s commentary & broker notes, is that G4M seems a company which is only just getting into its stride. It’s becoming a much more significant business, making its first brand acquisitions, and holding out the possibility of hoovering up smaller ecommerce competitors (in a fragmented market).
Margins are improving, with increased buying power, and scale allows marketing spend to remain static at around £9m p.a. In the last 3 years, but that falls significantly as a percentage of revenue, hence raising the operating margin a lot.
To my mind, this share seems an absolute no-brainer. It’s likely to be a very much larger business long term, making much bigger profits. Yet we can still buy it today on a perfectly reasonable valuation (PER of about 24, based on my estimate of 40p EPS this year, down from c.60p last year).
What’s not to like?! It remains firmly in my coffee can (hold forever shares).
Of course something could go wrong, as it can with any share. So far, I think management has proven great ability at managing the growth. Remember it's a founder owner-managed business, with Andy Wass still holding c.30%. That really does make a difference. Owner-managers just take greater care with businesses, are more committed, and hate dilution.
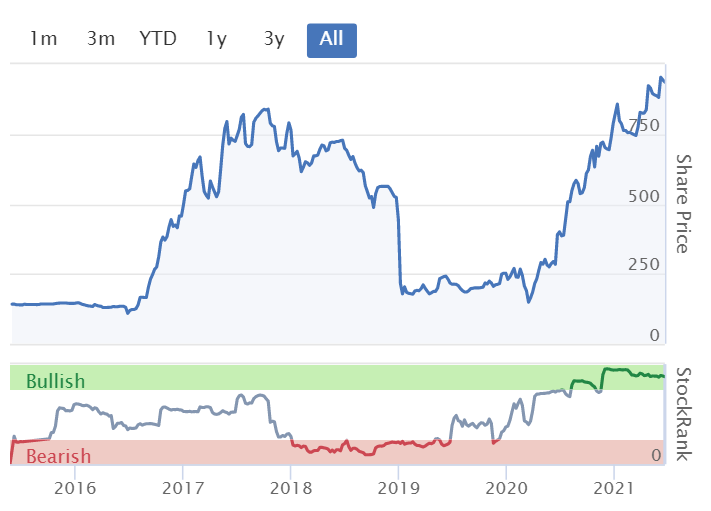
An interesting chart! Note also how the StockRank is now very high.
.
.
Saga (LON:SAGA)
(I hold)
435p (up 3%, at 10:55) - mkt cap £609m
Saga plc ("Saga" or "the Group"), the UK's specialist in products and services for people over 50, today announces a number of financing transactions intended to improve its financial flexibility by -
increasing available liquidity,
extending debt maturities and
providing greater headroom against covenants.
That all sounds good to me, and helps reduce risk for shareholders, particularly the risk of further dilution.
The recent trading update showed that SAGA has plenty of liquidity, so I’m viewing today’s refinancing as shoring up the position further, rather than emergency funding.
Key points -
Roadshow being launched to investors for a new £250m fixed rate bond (it already has a bond of the same amount in existence, which has worked well, costing 3.375% p.a. Interest, and repayable in May 2024). Bond funding is secure, long-term funding, without the problem of covenants. It amazes me that more companies don’t use bonds to finance their activities, instead of much higher risk bank borrowings. I like the idea of moving borrowings onto a fixed rate, at a time when there is talk of interest rates rising at some point.
Tender offer to partially repay £100m of the £250m existing bond. To my mind this implies the new bond is likely to be issued at a lower interest rate than the existing bond’s 3.375%, otherwise there would be no point in doing it (other than to extend maturity perhaps?)
Repayment of £70m bank term loan.
Easing covenants further on revolving credit bank facility (£100m available, which is not currently being used)
My opinion - we don’t know the terms of the new bonds (interest rate) yet, nor the terms of the tender offer.
In principle though, I very much like moving borrowing facilities away from the bank, and putting it onto much safer, secure bonds, which don’t have day-to-day covenants, unlike the bank debt, which can be so problematic when unforeseen problems emerge.
This new package seems to involve: raising £250m of fresh bond funding. Repaying £170m of existing debt (£100m of old bonds, and £70m term loan), which would give SAGA an additional £80m in gross cash.
As at 31 May 2021, SAGA had £78m available cash, plus £100m undrawn RCF, so £178m headroom.
If the package above goes ahead, it would have £158m cash, plus £100m undrawn RCF, which strikes me as putting it in an unassailable liquidity position for the foreseeable future, providing the cruise loan lenders continue to be supportive. They’ve been highly supportive so far, so I cannot see any worries with the cruise loans.
Remember the insurance division generates enough profit & cash to support the mothballed travel division’s monthly cash burn of c.£7m.
The 2 cruise ships are about to resume business very shortly, and customer demand is high.
Cruise load factors strong at 77% and 48% for 2021/22 and 2022/23; per diems ahead of expectations.
Having forgotten all of my O-Level Latin, I had to google “per diem”, it means per day. So in this context, SAGA mean the daily revenue generated per passenger. It would be better in plain English I think.
Overall then, let’s see what the full terms are of this refinancing, but assuming the interest rates are reasonable, then this package looks very sensible - pushing out debt repayment dates, clearing higher risk bank debt, and giving tons of cash headroom to cope with any eventuality re pandemic restrictions.
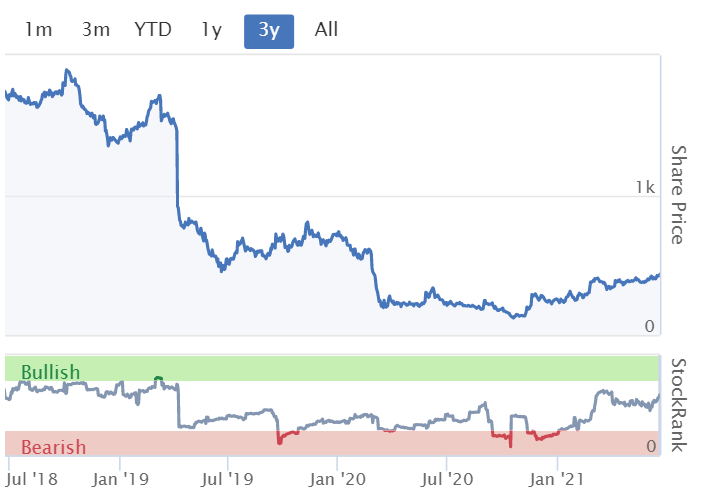
The market seems to like it too, with the share price now up 4% on the day, and what looks like a chart breakout at 440p.
A recent Numis note shows that, once trading has normalised, this share should generate c.62p EPS (EBITDA of £168m, and adj PBT of £101m, in FY 01/2023). Personally I’m hoping for more. But going on the Numis forecast, the forward PER Is only 7.1. Most of the debt is like HP on the cruise ships, so it’s asset-backed.
I would value the company on a PER of about 15, so that implies a share price of 930p, and I think there’s upside on that EPS forecast too. Hence 1000p price target is roughly where I’m at.
When viewing the chart below, remember that more shares were issued at the bottom, so there has been a fair bit of dilution. For that reason, don't expect the share price to get back to previous highs.
.
.
James Cropper (LON:CRPR)
1210p (down 1%, at 11:51) - mkt cap £116m
The advanced materials and paper products Group is pleased to announce its Preliminary results for the 52 weeks ended 27 March 2021
The pandemic caused a big drop in revenues, down 25% to £78.8m.
Despite that, profit remained surprisingly resilient, at £4.0m (LY: £6.7m) although that’s at the adjusted PBT level, and excludes £0.8m IAS19 costs [pensions] and £1.5m exceptional items, leaving statutory profit before tax down 70% at £1.7m.
Net debt (ignoring leases) is modest, at £3.7m
Balance sheet - looks OK, although the pension deficit has almost doubled to £18.4m, which would need careful scrutiny before buying any of these shares.
Outlook - I’m glossing over the now historic numbers, because as we move on from the pandemic, it’s the outlook which matters more. Costs of £2m have been removed during the pandemic. Capex projects put on hold last year are being resumed. The rest of the chatty (even a bit gushing in places) commentary is too vague, and doesn’t really give me anything to work on, in terms of how the future might pan out.
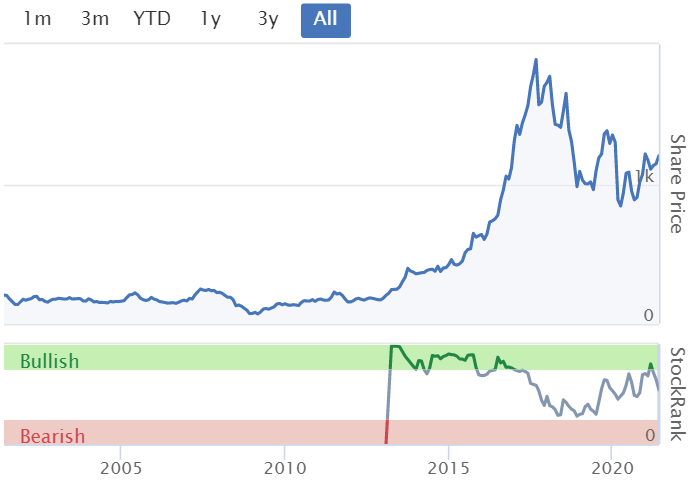
My opinion - I can’t take this any further, as there’s no guidance to speak of. Sorry about that. It doesn’t leap out at me as something I need to invest in. Although looking at the longer term chart, it did have a spectacular multibagger run from 2013 to 2017, but has been zig-zagging down since then.
Note it seems to be owner-managed, with the Chairman owning 19.4%, which is a positive in my eyes.
.
.
Jack’s section
Morses Club (LON:MCL)
Share price: 85.2p (pre-open)
Shares in issue: 132,530,539
Market cap: £112.9m
Morses Club (LON:MCL) is a provider of non-standard financial services with two separate divisions: Morses Club, the UK’s second largest home collected credit lender, and Shelby Finance, which is its digital division established after the acquisitions of CURO Transatlantic and U Holdings in 2019. The latter has two distinct brands: Dot Dot Loans, and U Account.
There’s arguably a need for this type of service that can be used by an underserved and excluded customer base, but there are also important and unavoidable ethical concerns as well. Regulators are aware of this and have been increasing their requirements recently.
The group itself says it ‘seek[s] to reward good customers with longer-term and lower cost products to improve their financial wellbeing.’
Home collected credit (HCC) is a specialised segment of the broader UK non-standard credit market. Loans are typically small, unsecured cash loans delivered directly to customers' homes. Repayments are collected in person during weekly follow-up visits to customers' homes.
The non-standard finance market is large and growing. An estimated 10-12m consumers (some 20-25% of UK adults) have difficulty accessing credit from mainstream financial institutions due to an impaired or non-existent credit history. While unemployment remains low, underemployment is an issue, with many adults working less hours than they would like or need.
It looks like Morses has been quick to adapt with an accelerated digitalisation strategy, where it hopes to see ‘ambitious volume growth’ in the years beyond 2020.
Highlights:
- Customer numbers as at 31 May 2021 were 144,000,
- Collections performance 104% of target and 118% ahead of the same period last year,
- Total new credit issued within HCC is 16% ahead of budget,
- HCC impairment charges are expected to remain within the guidance range,
- Customer satisfaction for the HCC division is at 98%.
Morses has seen a steady increase in customer demand across all lending products in both its HCC and digital divisions.
The group has invested in its technology infrastructure and further platform development is underway. This should help drive volume growth in the second half of the year. As a result of Covid conditions, 66% of all HCC lending is now cashless and over 70% of customers are registered for the online customer portal.
Customer numbers in the digital division for short-term and long-term lending products have increased by 40%, with total loan book balances increasing by 99% relative to the FY21 year-end position. New credit issued is 33% above management's budgeted plan, with collections performance also ahead of budget, so this increase in business is not affecting the quality of the loan book.
Morses anticipates that impairments should reduce as volumes stabilise. This is something to monitor.
Paul Smith, Chief Executive Officer of Morses Club, said:
Despite the continued impact of the pandemic, trading performance across all of our lending products has been very strong in the first quarter of FY22… The importance of a technology-led offering has never been clearer. Our investment and focus on ensuring our service model adapts to changing customer needs, whilst maintaining our core ethos of putting the customer at the heart of what we do, is central to our success as a Group.
Conclusion
This part of the market probably requires a more than average amount of due diligence. A cursory glance at Trustpilot shows a score of 4.6 from 2,129 reviews. That’s encouraging, although a smattering of one-star reviews brings home the potentially vulnerable position of some of Morses’ customers. These are important and delicate services to provide.
There’s regulatory risk here too - Morses et al need to comply with increasingly stringent regulatory requirements. This is a barrier to entry in terms of competition, but is also a risk to the business model. Others have left the sector due to these trends.
Recent regulatory changes following the FCA’s review of the high-cost credit market include the need to provide customers with details of the comparative costs of refinancing an existing loan versus taking out a new loan, and new rules were also introduced in relation to when and how an agent is able to discuss a new loan with customers.
Whatever your views on the above, Morses continues to offer decent value with a 4.6% forecast yield and a forecast PER of 12.3x despite a strong run up in the share price (shares have more than doubled since their November 2020 lows).
It looks like the group has a good market position, it is investing in its digital and IT capabilities, and it stacks up well across a range of factors. So, all in all, the situation here looks encouraging.

Directors appear to think so, with some sizable recent buys at the 65p mark.
Trifast (LON:TRI)
Share price: 141.65p (-1.97%)
Shares in issue: 136,042,435
Market cap: £192.7m
Trifast (LON:TRI) is a leading international specialist in the design, engineering, manufacture, and distribution of high quality industrial and Category 'C' components, principally to major global assembly industries.
The group offers end-to-end solutions around industrial fastenings, including designing, problem-solving, engineering, manufacturing, and sourcing. It looks, on the face of it, like a promising company with an established global logistics network, technical and design expertise, a track record of investment, and high-quality manufacturing capabilities.
The market cap may be just under £200m, but this is clearly an enterprise of some scale. It employs c.1300 people across 32 business locations within the UK, Asia, Europe, and the USA, and supplies to c.5,000 customers in c.75 countries worldwide.
Paul last looked at it here, noting signs of recovery in keeping with wider trends across businesses.
While forecasts suggest a slight moderation in revenue growth, the longer term trend has been very encouraging.

Nearly £8m of unusual expenses put a dent in profits last year, but apart from that Trifast looks to be proving itself as a growing, profitable, cash generative UK industrials company.
Highlights:
- ‘Resilient’ performance with revenues -6% to £188.1m,
- Gross profit -9.4% to £50.1m,
- Underlying operating profit margin down 150bps from 7.9% to 6.4%,
- Underlying diluted earnings per share -28% to 6.24p,
- Cash conversion at 147.9% of underlying EBITDA,
- £16m equity raise in June 2020 provides scope for investments and working capital,
- Strong pipeline and high activity levels,
- Freight, raw materials, and lead time pressures impacting margins in the short term.
While these results bear the marks of lockdown disruptions, the group believes it is in a much better position now than it thought it might have been at the start of April last year. It returned to growth across all regions and key markets in H2 following a rough H1.
Further, with demand ramping up in Q3 and accelerating into Q4, Trifast finished the year stronger than expected, delivering an underlying PBT of £11.0m. It now sees both the number and quality of organic and non-organic opportunities increasing.
Investment for organic growth - Trifast has continued to invest to support ongoing, organic growth opportunities in locations as diverse as Spain, Thailand, and the USA. Facilities in Hungary and within the UK will also be expanded.
The group will be using its base in Germany to hold stock in order to mitigate Brexit disruption.
Project Atlas is cited as a key initiative. This is ‘a transformational investment to build an integrated global business’ and is a significant multi-year investment into the integration and development of Trifast’s IT business platform and underlying processes. An annualised ROI of >25% is expected at the point of full realisation.
The group’s global talent management system is now operating in 16 locations, providing greater support of personal development goals of colleagues.
Acquisitions - Trifast says industry consolidation is ‘constant’, but the market remains fragmented with no one player owning more than an estimated 5%. Acquisitions therefore remain a key growth lever for the group and the current economic environment is creating greater momentum and opportunities.
Jonathon Shearman, group chair, comments:
The foundations are largely in place and Trifast stands on the cusp of an extended period of strong growth - both through continued organic growth and with an increasing focus on value-enhancing acquisitions. We aspire to be a much bigger company and are approaching matters with that in mind. In this pivotal year we will have to navigate a number of headwinds, even so, I can say that this is the most dynamic time for Trifast in more than a decade.
There are some risks flagged as well, however:
- Ongoing logistical challenges and pricing pressures continue to impact the global industrial supply chain environment.
- These include the semi-conductor shortages affecting automotive customers, container freight issues, as well as a global shortage of steel, causing pricing and significant lead time pressures.
- Trifast expects to see some impact on buy/sell margins and a potential build back of inventory levels at least in the shorter term.
Conclusion
As a slightly more qualitative aside, I quite like the way the management here communicates and the detail it provides in its reports to the market.
This does count for something, although it is impossible to screen for and its value is hard to quantify. If a team ever seems to be trying to make its business sound complicated, or is reluctant to provide obviously useful information to its shareholders, it’s sometimes best to walk away.
Trifast has a focused, experienced and highly skilled workforce. Given its expertise and track record (pre-Covid) of revenue growth, I’d back it to continue growing over the long term. But it is worth noting that its share price began to unwind in 2018, before the pandemic, so it could be that there is more to this story.

A lot of importance is attached to this major Project Atlas investment. Let’s hope it brings the anticipated benefits. Large, one-off projects are riskier to implement than smaller projects as they can be more complex and are more prone to slippage and increasing costs.
But Trifast does come across as a potentially higher quality industrial company worth investigating a little more closely. The business has exceeded pre-COVID-19 revenue levels of trading in HY2. Demand is continuing to grow, and customer orders are being brought forward.
The group says its pipeline of new business ‘has never been so exciting, including several new high-growth markets.’
At these levels, Trifast is probably more intriguing than it has been in the past - it’s just over half the price it was at its 5Y high of 273p back in April 2018 - but that’s not to say it’s cheap.
Its current level of 19.5x forecast earnings looks up with events for what appears to be a well run company with solid growth prospects.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Paul,
Re Saga (LON:SAGA)
The new bond will have covenants as does the existing one. They have been announced to bond investors and could be described as in-keeping with that of a B issuer - ie designed to keep the company from doing anything stupid.
Price talk isn't out yet but it will almost certainly be a coupon over 4%. The reason for a tender in this case could well be tax related or possibly to extend the maturity profile.
The reason that more companies don't issue bonds is the cost and the fact that the company needs to be big enough to issue a bond of enough size to gain investor interest. If you consider that a £100m deal is a small size and £1bn is not uncommon in GBP. So there is simply a point below which a company's EV can't justify it and in that case bank debt is the best option.
Best,
Paul
Thanks Paul, useful additional info.
I think we touched on covenants last time we discussed the existing SAGA bond. My point was that the SAGA bonds don't seem to have covenants like the existing bank covenants - e.g. breaching a net debt:EBITDA covenant is something that could happen with the bank borrowings, but not the bonds.
I think you said there might be some other more obscure covenants, but not the main ones that banks impose. Is that correct?
Funnily enough, I recommended your PIWorld podcast to someone today, as it's superb, who asked me for more info about bonds, as I obviously said I'm a generalist, not a specialist in bonds.
Regards, Paul.
Hi Paul,
Well remembered! I only had a brief look at the new bond covenants but they won't be dissimilar to the bank covenants. For a single B rated entity the bond market isn't more forgiving than the bank market. The bank will generally ask them to refi the debt in the bond market and the bond mkt guys will want parity in risk mitigation generally, knowing that they are giving the issuer certainty on the term of the debt. It's like a win win for both.
There is definitely a leverage covenant and interest cover covenant along with negative pledge, restrictions on m&a and consolidation. Also a change of control, which won't necessarily stop M&A but just protect bondholders from them selling parts of the business.
That's very kind of you to say. Always happy to chat bonds with anyone! Tamzin made me appear far more considered than I actually am!
Thanks also for all your ongoing insightful comment. Has kept me a Stocko subscriber for years!
Best,
Paul
A question, my fellow investors:
WHY have resource stocks across the board, seem to have pulled back 10 to 20% in the last 2 months?
Is it the "Sell in May" (little Summer news activity) effect?
Is it China and US economic policies?
Is it because generally resource stocks across the board hit a relative peak mid April propelled by lockdown Euphoria?
Possibly a bit of all three. Cathie Wood last week presented some stats suggesting the US consumer has ended her spending splurge on durables (CW mentioned copper and lumber specifically) and has moved to spending on services/ experiences now lockups have ended. So maybe commodities stockpilers have caught a cold? Hard to gauge how long this will last. Thing is, few individuals know where to access the sort of figures the professional money managers can summon up. John Authers often amazes me with his stats.
For my part, I'm always late to board trains and late to jump off. By which time the smart money has moved to the next platform......
A combination of the dollar strengthening, China threatening to release some reserve resources and a possible interest rate hike being brought forward from 2023 to end 2022.
I've been looking at the same thing 8888 over the last few weeks. Firstly, I have to say while commodity prices have an obvious effect on the companies day to day, they do not determine the value of these businesses. It's how the market perceives future direction of travel for resources rather than current price levels so macro forces seem to have a much greater effect here than elsewhere.
I can see several major possible causes:
1) They were generally overvalued at the beginning of the year (miners generally trade at much lower PEs than other businesses due to perceived risk)
2) The "reflation trade" that powered that overvaluation has become somewhat muddied - even as data continues to mount that we are heading for significantly higher inflation sooner that expected, many investors have either accepted central bank arguments that it is transitory or believe that no matter what they say central banks will step in to control it if not.
3) The strength of the dollar directly determines the price of commodities as they are all priced in dollars. The BOE this week (and others to follow) will be fascinating to see how they respond to the US last week - if they keep their current rhetoric, their currency will weaken against the dollar effectively importing that inflation. If they start to sound more hawkish (as I suspect), I think the dollar may weaken in response causing the direction in travel of gold and other commodities to perform an abrupt U-turn.
4) I have read several stories of China specifically selling strategic reserves of key metals to control pricing over the past few weeks. I have no doubt that this is a contributing factor although I've no idea as to the extent.
5) Last, John Authers had a fascinating section in his e-mail this morning detailing the problems Biden is running into with his infrastructure package. As so much of the future strength of many of these commodities is tied to this green revolution, these issues must have major effect on future commodity pricing.
I'm sure we can all think of others but honestly, it's impossible to know what causes market moves. I think it is fair to say that it had become an extremely crowded trade and my own guess is this is a minor period of adjustment before the onward climb starts again...
Thank you Mr Phuntt. Most useful and helpful.
Paul, further to you comments regarding share issuance for Saga (LON:SAGA) , is there a way to overly market cap and share price on one chart? This would be an easy graphic to visualise when viewing where a share price has moved from (typically fallen) and where it might get back to.
Many thanks
Funny enough I put in as a query/request for graphical visualisation of market capitalisation this morning (using the green thingamyjig in the corner). Recent dilutions make shareprice alone harder work to interpret.
Morning Paul, Great coverage as usual - One small question I can't see the quick answer to re Saga (LON:SAGA)
The load factors quoted - Are the % bookings in relation to FULL SHIP CAPACITY Load factors, or Covid 2021 reduced passenger capacity ? - It will make a revenue difference
It's 50% of load capacity until 19th July, at the earliest. They put out a statement yesterday:
https://travel.saga.co.uk/trav...
Being the lower of government guidance of 1,000 guests or 50% capacity until at least 19th July.
Can a stock be a coffee can stock if you review its updates every four to six months? Is the idea not to buy and forget it for 20 years? If the update was bad would you still hold?
Hmmmm, that's a really good point!
Might be a coffee can stock but still nice to have your updates thank you Paul.
Does no harm to open the coffee can every once in a while, if only to savour the aroma.
Thats a very interesting point. A buy and shove under the mattress for 20, 30 years type stock should be the ultimate lazy mans investing.
Something like Best Of The Best (LON:BOTB) (no position) has recently fallen in price due to slowing growth. There may be broker downgrades on earnings to follow. But if its a true coffee can stock why would that matter at all. If someone has paid, say £30, as they believe its a hold forever type company why even bother looking. So many have an urge to fidget and not leave alone and see out a strategy, myself included. I couldnt do it with anything more than a tiny percentage of my holdings, held in a separate account. 30 years is a long time to wait to see if its worked :)
Youd really need the right type of personality to buy and not look. Fine in bull markets, not so easy when everything is tanking.
Tell me about it! I hold Best Of The Best (LON:BOTB) and £TRMR.
Maybe we should differentiate coffee cans?
I am going with instant coffee can for this one
Decaf
Ground
etc.
Maybe a new classification system for Stocko to ponder on :-)
Always good to check the coffee inside hasn't gone off!
my penny worth on coffee can investing is while I try to think long term and try to hold for the long term (5 + years) I do think one has to be careful about the buy and hold forever to maximise returns maxim.
Running a quick screen on LSE stocks yields just seven still listed companies on one particular day (of course there could be companies that have been taken over that met this criteria) that have a CAGR total return greater than 20% (31 companies greater than 15% and 107 companies greater than 10%).
Bringing the holding period down yields the following (number in brackets number of companies with total return CAGR of 15% and 10%)
15 years - 21 companies (60 & 148)
10 years - 78 companies (158 & 310)
5 years - 220 companies (323 & 484)
For every Dominos (22.7%) or JD Sports (21.5%) there 205 companies that have shown a negative CARG over 20 years.
Holding forever may work/be necessary if managing at the scale of Warren Buffett but the stats would, to me, indicate picking the right company and holding for between 5 and 10 years.
I hasten to add that at the moment I seem to be struggling with the first bit!!
Kind regards
Michael
My thoughts are that most of the LTBH stocks have their day in the sun but in the majority of cases they fade in the end. Obviously we all like a good long run-up but nice to get off before the warm glow fades and your original research effort is wasted. I like to see reviews to either reassure myself or get a heads up if things are starting to look a bit flat.
Here are my SCVR heat maps for today (prices as at ~9:50pm).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Thanks for the write up on Morses Club (LON:MCL) I would just note that the company was making EPS of 12p before the pandemic and I would fully expect it to match or more likely surpass this before too long, so I would put this on a PE of around 7 rather than 12 quoted by Stockopedia - still way too cheap in other words.
Please can somebody explain why Trackwise Designs (LON:TWD) has gone down today? (I hold and expect to do so for quite a while.)
I don’t hold Trackwise Designs (LON:TWD) , but reading today’s results release it’s a pretty down beat statement suggesting tomorrow’s jam might not arrive until the day after tomorrow. Market is pretty unforgiving at the moment about anything other than perfection.
Gus.
I hold too, as I feel the technology they are offering is very much in demand as we try to reduce weight and size in the drive to manufacture EVs and medical instruments. They have been focusing on growing their capacity to meet this demand which I am sure is impacting todays figures but revenues are growing and for me, I have taken the opportunity to buy some more. It might not float everybody's boat, but I like this sector!
Hi Paul,
Worth noting, as I only realised today, that Ken Ford of SDI build and buy fame, is Chairman at £G4M. Certainly a positive IMHO.
Cheers, Martin
G4M I concur (I hold big time) but never forget owner managers are great providing the Finance Director is not bent alla CAKE, what ever happened to this AH, he cost me a fortune, they should be stripped of all their wealth but are they ever charged and found guilty ?
Ms International (LON:MSI) FY results to 30th April 2021 (I hold)
SP 184p +13.25%
Mcap 29.8m (cash on balance sheet 25.565m of which 6.165 held in escrow, 2.01 prepayments 17.39m cash on hand. No debts and miniscule lease liabilities).
(Edit - it's taken me a while to write this and I see that the SP has now risen to 196p - which put it on a Mcap of around 32m - in comparison with the 25m of cash sloshing around. ).
I'm in the process of updating my figures - here are som extracts from my notes on today's results.
Health Warning: This is old school. Very OLD SCHOOL, family run, tin-pot, metal bashing, micro-conglomerate based in Doncaster and specialising in naval cannon, forgings, fueling station superstructures and corporate branding signage. Trading is extremely illiquid since the directors and related parties own 49.9%. That's not put you off? Try this. Welcome though the 1.117m profit announced today is, the small print reveals that directors emoluments were 1.57m! If that's not your bag - then move along now please.
Anyone still reading? No I thought not. Never mind I'm kind of used to talking to myself about investments. Not necessarily healthy I know.
Anyway back to my problems with MSI. The reason for the jump in share price is because of:
1.117m profit
7.2p eps
and restoration of the 6.5p final dividend making 8.25p for the year.
announced in the FY results this morning. On the face of it not a big deal. But H1 was loss making so it's more impressive than it looks. It's not a beat on expectations because there aren't any. No coverage. And management is firmly old school. They might frown on the concept of expectations? Is the chairman chauffeur driven to work each morning in the company Bentley I wonder?
Disclosure: This was my third largest holding before this mornings rise. What caused me to invest more in such a dodgy proposition? Well I used to hold some as a value share but it was more of a value trap and in response to the directors pay I sold slowly as I cold. But as the share price has declined, directors have consistently bought more shares and shifted shares into ISA's and SIPP's despite their exorbitant emoluments. The company also bought back 550,000 shares. The interim dividend was restored despite the H1 loss due to the cashflow and cash on hand. With cash building and trading likely to be improving I thought the shares quite understandable extremely overlooked. I started buying back in earnest. Even so I am acutely aware of how illiquid this share is. If it goes wrong it is very hard to get out. Which is why it was only my third largest holding behind APF and MACF. Catching them up fast this morning.
The H1 results were a loss of -6.7p which puts the H2 results at around +14p eps.
That run rate for FY22 would put them on +28p if its not a flash in the pan (which seems unlikely) and that's ignoring the balance sheet stuffed with cash on hand 17.39m, 2.01m in prepayments and 6.165m in escrow. With the balance sheet also stuffed with 19m of Property, Plant and Equipment - there is not much in the Market Cap for the business?
Looking under the covers at the business. What's changed in H2?
In H1 three of the divisions, Defence, Forgings and Corporate Branding were loss making. Superstructures (fuelling stations) was profitable. That is due in the main to the pandemic induced lockdowns and businesses reducing or delaying investment in response. In H2 Defence became strongly profitable and forgings became profitable while superstructures profits reduced to a loss (lockdowns) and corporate brandings (mainly EU markets remains loss making) remained in loss.
The strong profitability in defence is also due to the reverse in a long term depression in the business caused by reduction in orders by the UK MOD (too many over budget big toys to pay for - but thats another story) originally the main customer for these weapons. MSI has invested in R&D and export opportunities and in H2 the US DOD ordered 8 systems, followed by an order for 7 systems by a US manufacturer for a foreign procurement.
This has clearly been very profitable on its own and is a prestigious achievement even if it doesn't result in a further large orders. Something of a game-changer for this division, it does raise the likelihood of further orders worldwide and the divisions can be immensely profitably when the orders roll in.
Outlook. With a run rate of 28p eps per year these is still scope for earnings to increase significantly with a return to profit from both superstructures and corporate branding as EU lockdowns relax and travel resumes as well as improving outlook for the forging division which has been subject to cheap imports in recent years.
My forecast for FY22 is 31p eps - though this may have to be raised once I get to crunch today's numbers and 39p in FY23 with all 4 divisions profitable.
Which does look like there is still scope for significant upgrades (except of course there are not any analysts following it to upgrade) but the downside of the tiny, illiquid, family run, tin-pot, metal-basher from Doncaster still applies to temper any enthusiasm from today's results?
cheers
Mark
Ms International (LON:MSI) Had figures today. 7.2 p of earnings and £23m of cash also with an unusually bullish outlook. Market cap is still only £33m after today's rise.
Ms International (LON:MSI) looks like the show is firmly back on the road here.
EPS of 7p, a reinstated divi, net cash of £23.6, up from £16.3.
Outlook comments seem positive. and the results commentary are in the usual down to earth style, which I find refreshing.
It's a bit illiquid, and the SP is 30% higher as I write, at 210p. There may be a bit more to come, given the outlook appears to be improving in all divisions.
Re Morses Club (LON:MCL) - this is now my largest holding and one I am super happy with. It will soon be the clear market leader in Home Credit. Provident, 40% mkt share pre-Covid are exiting having never recovered from a botched move from trusted local agents to distant salaried staff) and NSF/smaller players all unable to respond to the combination of new, cost reducing technology, increased regulation (that has to be embedded in technology) and the shocks of COVID. Home Credit has transformed in P5Yrs.
The customised for the non-standard market digital bank & lending operation they have assembled, slowly and relatively cheaply, will now enable them to retain customers they would previously lost when their credit worthiness improves - many of whom will then later fall back into Home Credit due to precarious earnings potential. The digital side will be in profit by my estimation by the end of next quarter and operates in a hugely bigger market than Home Credit. Many failures in this I know - but these from highly paid, get rich quick tech and financially led businesses who do not understand the non-standard credit world - which, with a 100+ years of history, Morses Club do.
Dividends are forecast to be very high and growing (as they were for so many years at Provident Financial (LON:PFG)). Share count has been stable since IPO 5 years ago and Mgt are buying shares.
Net, today's update confirms all is on track or better - and we are still coming into the sweet spot in the credit cycle for non-standard credit providers!
Hi Zipmanpeter.
I also hold Morses Club (LON:MCL) and increased my position on recent weakness. I think they’re in a good position and have been making the right moves but feel the biggest value driver going forward will depend on the actions of the FCA.
If the FCA recognise there is a definite need for an efficient non conforming lending market to service sub prime borrowers the regular banks won’t touch, they’ll look to work with the reputable major players and put in place a regulatory framework that provides barriers to entry against suspect new entrants, gets rid of bad practices and allows good corporate citizens that play by the rules and make a decent return. If they take a more adversarial view, all sub prime loan providers will be tarred with the same brush and punitive regulation will be introduced. In this case, the regulated sector will wither providing scope for the unscrupulous loan sharks sniffing around at the margin. (The poor will, after all, always be with us and they will want to borrow to spend today whatever the FCA says). Logic would suggest it’s in the interests of the FCA to try and achieve the former but when did logic ever get in the way of a good political/media sound bite?
Gus.
Major error on UK_Investor's part::-
I was drooling of Morses Club (LON:MCL) when it was 60p, and it was No 2 on my list. The main reason I didn't pile in is my largest holding, International Personal Finance (LON:IPF), has made 100% and it isn't done yet.
Morses Club (LON:MCL) will either saw further on re-rating or perhaps pull back... the opposite to what I do will occur.
Well done MCLers for spotting the share and making the win.
Saga (LON:SAGA) proposed 250m bond offering @ 3.75 per cent.
Can assume some of their target audience being very interested, so is this a smart move to raise funds or is their a devil lurking in the detail somewhere?
3.375%
Re Saga (LON:SAGA) - The appendix to the RNS does imply that dividends are not now expected to restart until 2023, instead of 2022, which is a negative as the leverage ratio is expected to remain higher for an additional year. But the plans should presumably put them on a firmer footing should restrictions with travel get extended much further.
I hold OPG Power Ventures (LON:OPG) as a small speculative punt - it comes across as a right basket case with the management not appearing very popular.
Would welcome any comments - even those who want to have a laugh at my expense!
hi letap, how long do you want to hold Opg Power Ventures (LON:OPG) then? I hold, just as I have held since December 2018 in what was a small speculative punt. Added to in April 2019 and in receipt of a share distribution the following December. Nothing good has happened since, perhaps it is in Covid Recovery Mode and with India suffering dreadfully may well be for some considerable time.
Silver
Ref: Opg Power Ventures (LON:OPG) I managed to get in at around 12p . You're getting a profitable cash generative power station in a growing economy at a fraction of the build cost, with rapidly shrinking debt. India cannot afford to phase out coal power for decades to come. Once the debt is paid off the dividend yield will be stunning.
I got 'free' Thungela Resources (LON:TGA) shares from £AAH spin off. Topped up as feel despite Greta billions of people still need heating, power and steel - and lets not forget the barby. Downside will be decommissioning but down the line.
Did anyone listen to Time Finance (LON:TIME) at Mello last night?
Hello CamRaid. Re Time Finance (LON:TIME) yes. What is your point please, if any?
Ridavies - thanks. I was wondering what the take away points were?
My morning smallcap tweet: G4M upgrades again
Trackwise Designs (LON:TWD) Surgical Innovations (LON:SUN) LPA (LON:LPA) Audioboom (LON:BOOM) Proton Motor Power Systems (LON:PPS) Morses Club (LON:MCL) Scancell Holdings (LON:SCLP) £G4M Novacyt SA (LON:NCYT), OPG Power Ventures (LON:OPG), Frenkel Topping (LON:FEN), Good Energy (LON:GOOD)
Trackwise Designs (TWD) FY(Dec). New contact with UK EV mfr "extended from three to four years, with a significant increase in expected volumes and potential value. First material revenues from the contract are now expected in H1 2022 rather than 2021." Worth £54m max. [SP=227.8 Cap=65m]
Surgical Innovations (SUN) AGM stmt: "signs of recovery as a number of key healthcare markets begin to resume elective surgery at close to pre-covid levels." Rev in Jan-May only 20% down on 2019. [SP=3.24 Cap=30m]
LPA (LPA) confirms the contract award to supply 165 new build carriages with LED lighting systems. It's in line with mgmt exp. [SP=70 Cap=9m]
Audioboom (BOOM) guides FY(Dec) rev significantly ahead of market expectations. "High demand for premium advertising inventory which has enabled the Company to increase average ad unit pricing by 22%." [SP=900 Cap=142m]
Proton Motor Power Systems (PPS) MoU with Electra Commercial Vehicles to integrate Proton's fuel cell systems into its trucks. Electra can only make c.200 trucks PA but is planning to expand capacity. [SP=55 Cap=426m]
Morses Club (MCL) Home Collected Credit credit issued 16% ahead of budgeted plan. "The significant increase in both demand and volume for longer and shorter-term digital lending products has led to the lengthening of the maturity profile of the loan book." [SP=85.2 Cap=113m]
Scancell (SCLP) COVIDITY covid vaccines preclinical data supports move to Phase I trials. "Versatile and efficient approach can potentially protect against covid variants of concern." [SP=21.4 Cap=174m]
Gear4music (G4M) FY(Mar) rev as per trading stmt. Guides FY22 likely to be ahead of mgmt exp. [SP=928 Cap=194m]
Novacyt (NCYT) FY(Dec). DHSC dispute: "if required, it should be possible to replace the product in dispute and a product warranty provision has been made accordingly. The Board's best estimate of the cost to replace is up to a maximum of £19 8m." Assumes DHSC's claim for a refund fails. Nnpaid invoices total £73m. [SP=357.5 Cap=322m]
In line: OPG Power Ventures (LON:OPG) Frenkel Topping (LON:FEN) Good Energy (LON:GOOD)
In your update on Novacyt Sa (LON:NCYT) I think you should have mentioned that the results were stellar with £91m Cash / Profit £167m / Revenue up massively at £278m / EBITDA at £176m........
When you consider the market capitalisation this morning was less than £235m those are very impressive numbers and a £20m provision for a dispute less meaningful.
FY(Dec) no surprise as there was a detailed FY trading stmt in Jan.
As for the £20m provision, that's probably the best case. The SP hinges on the outlook which was torpedoed by the DHSC's rejection of Novacyt SA (LON:NCYT) tests.
Novacyt Sa (LON:NCYT)
Lurking at the end of FY results are the numbers for the LTIP. This year £14.2 million was paid as Remuneration of key management personnel. I believe that this payment was made to the CEO in cash based on the share price at a specific date. There was an additional £11.1 million paid as part of an LTIP listed under Aggregate Director's remuneration. I do not know who received these payments. These payments are in addition to generous salaries, etc. There remains another £5.5 million payable at the end of 2022 under the LTIP.
As Novacyt has uncertain earnings after COVID, the cash that it can generate during this period is relevant to the valuation.
disclosure: no holding
Yes I saw the LTIP numbers - it was a scheme set up- before Covid and reflected trading / profit at the time. Covid volumes changed everything and the recipients have done very well!
re Novacyt SA (NCYT) i've read and re-read the results announcement and cant find the word "dividend" used at all, not even once. That scares the life out of me - are they going to spend the cash pile - £91m and growing on acquisitions so they have a business post Covid - we all know the empirical evidence on how succesful that as a strategy is... i thought shareholders deserved something.
Novacyt Sa (LON:NCYT) full year result looks better than expected, will the share price fly again?
I suppose that depends on your starting outlook. I couldn’t believe how many new senior jobs were appearing all over the show, spending money like it’s going out of fashion. As for their contract dispute with Government, we’ll, what a mess. Good luck to all still holding.
The risk reward here looks very good to me.
Thoughts please on Morses Club (LON:MCL) - trading update today - reads impressively to me (I hold). Thanks.