Small Cap Value Report (22 Sep 2016) - BEG, TFW, FISH, TMMG, SSY, SAA

Good morning!
I added 3 more companies to yesterday's report in the evening. Not sure why I've been splitting the reports into two sessions lately, just tiredness & being overloaded with information I think. Sometimes you just need to spend a few hours digesting things before writing about them.
So here is the link for yesterday's report, which now includes additional new sections on the following;
eg Solutions (LON:EGS) - lousy interims, but contract wins mean a stronger H2 is in prospect. I'm not prepared to give this company the benefit of the doubt, given its track record.
DX (Group) (LON:DX.) - rapidly declining profits & huge structural problem with DX Exchange. A value trap in my view. I don't see this ending well.
Dillistone (LON:DSG) - OK interims. Nice recurring revenues. Good divis, but balance sheet not great. Unexciting, unless it can crank up the growth rate.
That's enough to get you started, whilst I write up today's report!
On to today's news;
Begbies Traynor (LON:BEG)
Share price: 47.5p (up 2.7% today)
No. shares: 126.8m
Market cap: £60.2m
AGM trading update - this is an insolvency practitioner, which has also acquired other related businesses in property services (e.g. valuation, auction, etc). Today it updates on the year to date (ending 30 Apr 2017).
Trading seems to be alright;
Our trading in the first quarter of the current financial year was satisfactory. Performance in both divisions was in line with our expectations, despite the continuing challenging levels of market activity.
The insolvency market has been in the doldrums ever since we entered the artificial world of near-zero interest rates in 2008/9. This allowed zombie companies to be gradually restructured over the last 8 years, rather than being put through formal insolvency procedures, as happened in the past. So a lot less work for Begbies than expected, in recent years. Therefore it has down-sized its cost base, to remain reasonably profitable.
Today it also says that Govt insolvency statistics are roughly unchanged on last year.
Outlook comments sound reasonably upbeat in the circumstances;
...Overall, we continue to be confident of the prospects for the group and will look for further opportunities to develop and enhance the business, both organically and through selective acquisitions."
My opinion - it's valued on a forward PER of about 13.5, and has a nice dividend yield of 4.7%. Therefore there is some attraction to holding this share as a hedge against the next recession, and receive decent divis while you wait.
The group seems well managed, and the founder still holds a large stake.
I quite like it, but in current markets (which are growth-focused), it's likely to undulate in a general sideways direction, as it has done for the last 3 years. Only a looming recession would be likely to change that, in my view.
FW Thorpe (LON:TFW)
Share price: 246p (up 0.8% today)
No. shares: 115.7m
Market cap: £284.6m
Results y/e 30 Jun 2016 - this is a group of companies designing & supplying professional lighting systems. It's been a long-standing favourite of mine, as it seems well-run, has a great balance sheet, and usually performs well.
Figures today look good, helped by an acquisition. To save me re-typing it, here are the highlights as flagged by the company today;
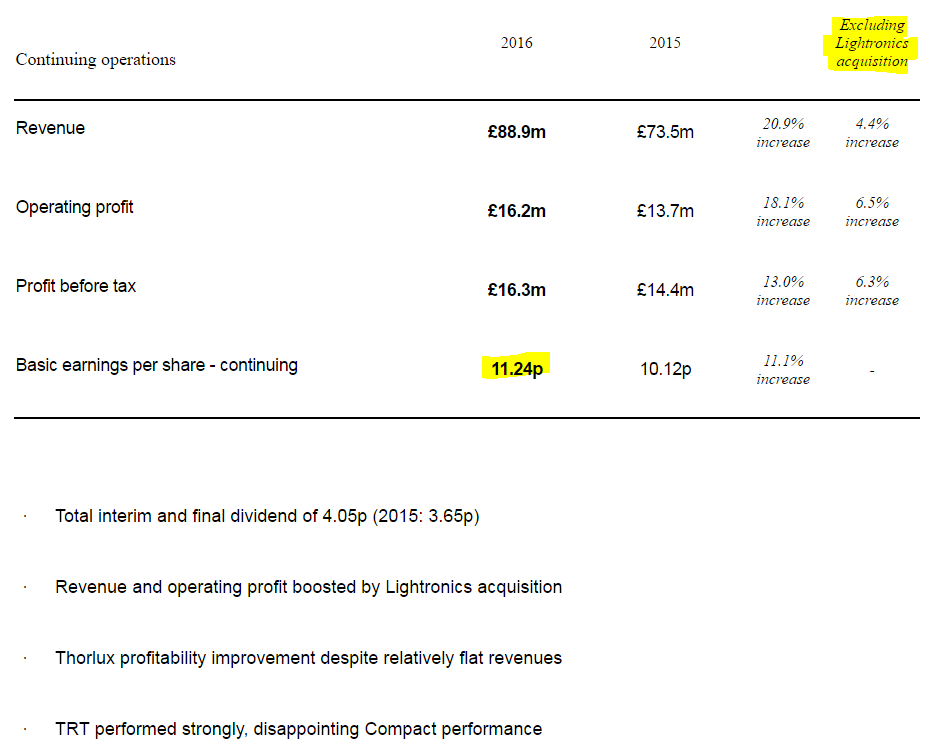
I particularly like that the company has shown the organic growth percentages, as well as the total (including the acquisition of Lightronics). This aids understanding, and all companies should do this. If figures are presented in a balanced, and clear way, good and bad, it engenders trust in management, and makes me more likely to want to buy the shares.
The opposite of course, is when some other companies cherry-pick the best points, and hide the negatives. Or, when companies are over-rampy in how they present the figures. Look back at how both Globo & Quindell presented their figures, with bold & underlining of UP x%, etc. So rampy presentation of results statements is a massive red flag. Thankfully, there's none of that nonsense going on with a traditional, sober company like FW Thorpe.
Outlook - I've enjoyed reading the narrative with today's results. It's written in a conversational style, so it almost feels like a fireside chat with the Chairman. There's nothing specific in it, but it's quite interesting nonetheless, especially his comments on BRICs countries;
I seem to say it every year but, yet again, I must say that the future is uncertain but now for another and additional reason; "Brexit". Most world economies are still not buoyant and this just adds another economic unknown.
We will, however, continue to concentrate on areas we think best whilst still hearing but not necessarily acting upon what others tell us! Concentrate on selling to the BRICS our government told us! Brazil isn't doing so well, Russia is suffering with low oil prices and sanctions, India we don't hear of much, and China has a reducing growth rate. All of these countries, by the way, have very high protectionist import duties for foreign manufactured goods such as lighting equipment. We do, however, remain cautiously optimistic about the year ahead.
We will continue to concentrate in stable areas and where we have "advantage", be it our efficient durable products and systems for high energy cost markets, our reliable rugged industrial ranges for rugged industrial uses or whatever.
However events play-out people will always need lights. We will continue on!
Valuation - this is where the warm fuzzy feeling deserts me.
Basic EPS was 11.24p for y/e 30 Jun 2016, so that is a PER of 21.9. That seems very stretched to me, for a business that has just announced organic profit up 6.3%.
The word "adjusted" does not appear anywhere in today's results though. So these figures are clean, and could no doubt be adjusted upwards, in the hands of more aggressive management. So that has to be taken into account in probably justifying a slightly higher PER. Not this high though.
Also, the strong balance sheet should be taken into account. There's £33.2m in cash, plus some freehold property, and no debt. Plus other surplus working capital, which could easily be geared up a little. So once could argue that the balance sheet probably has about £50m in surplus working capital, so about say 15-20% of the market cap. Adjusting that out would bring the PER down into the high teens.
I've looked to see if EPS could be massaged up, but amortisation of intangibles is mostly related to capitalised development spend. So we want to leave that charge intact, not adjust it out.
My opinion - overall then whilst I really like the company, it's just too expensive. This company used to languish on a PER in the low teens. Now it's in the 20s. So a good part of the share price performance has simply been an expansion of the PER. This is true of many companies now, and is being driven by QE & ultra-low interest rates, forcing investors into equities.
Sure, earnings have risen too, but I think we need to be very careful about not getting too carried away with over-paying for businesses like this which are good, but not exceptional.
So for me, it's not something I could buy at this level, even though I like a lot of things about the business.
A few snippets to finish off with;
Fishing Republic (LON:FISH) - the company is reporting modest profits, and growing. However, the blue whale in the koi carp pond can be found on the balance sheet - namely inventories are gargantuan for the size of business, at £3.3m. Remember that is stated at original cost price.
The cost of goods sold in the 6 month period was £1.25m. So in other words, this company holds 2.6 half year's worth of stock. That is equivalent to about 15 month's worth of stock sitting in its premises, gathering dust. That's a complete joke. Most retailers of non-perishable items hold roughly 4-8 week's worth of stock.
The figures are ridiculous in my view, and make it uninvestable.
Mission Marketing (LON:TMMG) (I hold a long position in this share) - looks cheap on an initial, very quick look. Balance sheet is quite weak, so would never be a conviction buy for me, however I do hold a small long position in it. There's a results video here, which is helpful.
Directorspeak sounds positive, mentioning contract wins, and upbeat about H2. Could be worth a deeper look. I'm relaxing a bit about marketing sector, as the risk of an immediate recession appear to have receded.
SCISYS (LON:SSY) - this company seems to have got back on track. A quick skim of its results make me feel it's worth a closer look. I've written a lot about this company before, and continue to believe there's latent value in the company.
Outlook comments today sound quite upbeat. Valuation seems undemanding, but it's always been cheap, as I think it's seen as a bit pedestrian - little growth, and serving a lot of public sector organisations.
M&C Saatchi (LON:SAA) - another marketing company announcing good figures today. In line with expectations outlook statement. Not cheap though - forward PER of 16.8 is pretty full for this sector.
I have to leave it there for today - am heading into London for meetings.
See you tomorrow!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Done a quick bit of digging and inventory is too high as you say Paul. Although as online picks up, they can fulfil from one warehouse and hold less stock so this will improve,
I pushed on this in the meeting but will find some proper comparables and get back in touch with mgt.
Not sure that makes it univestable though if the p/e comes down to a sensible level. Not a red flag for me.
JDW72
Re Fishing Republic (LON:FISH) - I attended a presentation today and have the following observations:
- Management are passionate and knowledgeable about the business and spoke eloquently without being "slick". The CEO started his first fishing business aged 13!
- Management and family own a large chunk of the business
- Terry Leahy and two others also own a large chunk and put more into the business than they were asked to
- The market in the UK is hugely fragmented and they have little comparable competition. Some of the businesses they buy are profitable yet are being bought for the value of the assets alone!
- The market is huge and fishing people love gadgets and new things
- There is a continual supply of new fishing people (lots of teenaged boys) and fishing stuff is the easiest birthday/Christmas present to buy in the world
- They are already the biggest wholesale buyer and have huge buying power
- They are already starting to establish local monopolies in areas by buying up other shops and closing them. New shops can't compete on price so won't open.
- Website being sorted, click and collect coming
All positive factors.
Inventories are high, but they have destination warehouses which by their nature need to be full of stuff. I wonder what a comparable business with big warehouses (furniture springs to mind) has with regards inventory. I will investigate. They do get advance notice of new lines and flog off old stuff via Amazon/eBay before the new stock arrives. At worst they cover their costs.
With cash in the bank, I don't actually see a huge urgency to drop inventory when the stock doesn't degrade and get out of date. They shift anything aging through eBay/Amazon at more than cost.
I believe there is some complexity with regards to some of the property which I will look into.
I don't hold, it seems to be on a somewhat racy multiple on brief inspection (I need to run the numbers properly) but there is a real business here being run by passionate family owners which in time might well be the dominant market leader serving an industry that has 4 million participants, lots of whom are obsessed, well funded and always seeking an edge through new kit.
Don't write it off.
JDW72 (no position or connection with the firm)
Is this the same Terry Leahy that was asleep at the wheel at Tescos? When fraud was committed under his watch? Where execs are under investigation by the SFO?
Personally that would be a reason for me not to invest. And after having seen how Tesco treat their suppliers, I just hope that FR don't go down the same route.
No, it was Paul who was asleep at the wheel at Tesco. See post 13.
Ho-ho Very droll !
Thanks for those meeting notes, very informative!
Personally, I just don't understand the valuation or story at all behind Fishing Republic (LON:FISH). In fact, I would go as far as saying it's vulnerable to a Crawshaw (LON:CRAW) type collapse in share price. A £15M market cap for a company with 11 stores and £5M of revenue selling fairly low margin products is just crazy. Contrast that with another retail roll-out in Crawshaw (LON:CRAW). For a £28M market cap, you get 42 stores with £37M of revenue. The fishing biz looks to be slightly higher margin, but the volume Crawshaw (LON:CRAW) does more than offsets that. Also, I don't see how Crawshaw (LON:CRAW) can be put out of business by Amazon or Ebay, which Fishing Republic (LON:FISH) certainly could be.
FYI - I own neither, but would be shocked if Crawshaw (LON:CRAW) didn't outperform from here.
Interesting comparison but perhaps coming at the same thing from opposite angles.
I agree that Fishing Republic (LON:FISH) is overvalued at current levels (although knock off the cash on the balance sheet and the gap starts to close a bit) but I see them in the role of the supermarkets who are eating into Crawshaw (LON:CRAW) turnover and profits.
As for being put out of business by Amazon or eBay - perhaps if those two companies went into fishing maybe, but not from the individuals who use those channels to sell as they can't compete on price. A distant relative of mine has made a good living in the last 5 years selling fishing stuff on eBay (he had one of the first eBay shops) but 6 months ago stopped as he was being squeezed to death by the bigger players with buying power that he simply didn't have and his margin dried up.
As I said, I don't have a position or connection (to either of the companies) and will watch with fascination.
Great debate though.
JDW72
Please can people generally try to remember to put the company ticker or name in every post, so that we know which company you're referring to.
Ta.
I attended a Share Soc presenation in Leeds a few months ago and Fishing Republic were presenting.
The Company is tiny and I was not impressed with the management. They are acquiring very small regional retailers and growing relatively slowly.
The shares are not cheap on a P/e of about 15X and the dividend word didn't get a mention.
As Paul said the stock turn is into years rather than months , possibly due to holding branded and own brand stock across the board. You can offer too wide a choice and maybe they are.
I think a niche market with limited growth prospects but DYOR.
Yes I am a big fan of Paul and grateful for his insights.
Jim Mellon is on Twitter saying Mission Group is darn cheap and bought more of the stock.
https://twitter.com/jimmhk/status/778902267248439296
I finally bought some TMMG too... and up 6% today already! :-)
I see Newmark Security (LON:NWT) shares are down 28%, have just issued a trading statement at 1.37pm which is not good.
Paul, what's your view on the announcement today from SEE, this new chip they have produced looks very interesting with the focus on driver distraction and the recent guidelines issued from the US regulator (NHTSA). Could they be another ARM holdings?
PP
"Only a looming recession would be likely to change that, in my view."
I suspect there is one imminent - just around the corner and no, it wont be due to Brexit as the likes of Simoan will claim but the impending China credit bubble bursting spectaularly, swiftly followed by government bond markets -
Simply unsustainable
And it will burst in spectacular fashion
I suspect there is one imminent - just around the corner and no, it wont be due to Brexit as the likes of Simoan will claim but the impending China credit bubble bursting spectaularly, swiftly followed by government bond markets -
Hi,
I don't understand where this has come from? Why do you feel the need to make such a personalised comment? I have barely contributed to Paul's blog for months and have to my knowledge not given thoughts on the likelihood of a recession. I'm totally baffled by your comment and it's personal nature.
All the best, Si
I merely mentioned you "in passing" so it's hardly personalised - stop being a snowflake
As to being totally baffled you've either a poor memory, or you're being disingenuous given the snidey one liners you made in my direction when we were attempting to discuss Brexit and its implications. Yours being the pessimistic doomongering ones in case you've forgotten!
Anyway, this is all I shall say on the matter as you're unable to engage in conversation with anyone who strongly disagreed with your Brexit stance and we dont want to clog up the board.
Sayonara
I'm sorry but you are just lying. You will not find a single post I made that claimed such doom and gloom and a sharp recession, for the simple reason I did not believe it or say it. In fact the only comment I made as such was against the desperate attempts by Osborne to suggest this would happen in the run up to the vote. It seems you have a poor memory other than some kind of personal grudge you hold against me from months back. I have no idea why Stockopedia let people like you get away with this rubbish...
Hi Paul,
Your comments about tiredness reminded me of this cautionary tale from Andrew Sullivan. It's about how constant blogging and trying to always be online to respond instantly to news events nearly broke him!
My takeout would be to concentrate on writing quality over quantity. Stick to the shares that really interest you and don't try to respond to every random request we make for comment on our latest finds as you can never win that game.
http://nymag.com/selectall/2016/09/andrew-sullivan-technology-almost-killed-me.html
Hi JohnEustace,
That's quite interesting (the article about the blogger who burned out).
I won't burn out, as I'm pretty indestructible, and if I feel tired, I just lie down and sleep. Usually after lunch - maybe my ancestors were from a hot climate and liked a siesta? I used to do that at Pilot too - drove to Tesco by the M3 at Winchester, reclined my seat, and had a snooze in the BMW.
Also, exercise is key. So yesterday, when there was long gap all afternoon between the first part of my SCVR and the second, it was because I jumped on my new bike & went for a hilly 10 mile cycle ride around Brighton & Hove. It blows away the cobwebs, and is ideal when we're seeing the last bit of sunshine for 2016.
I take your point about me concentrating on quality over quantity though. I'm bored with going through the motions on companies that don't interest me. So increasingly, the format here is for me to concentrate on 2 or 3 companies that I think look the most interesting, then just do a few snippets on boring shares afterwards.
We've had lots of fantastic winners here over the last few years. So although I see that nasty individuals on other sites seem to enjoy making ad hominem attacks on me, it's like water off a duck's back - they only do it because they're sad individuals (trolls) who are useless at investing themselves, so direct their anger and self-loathing towards attacking anyone with a profile. So be it, I couldn't care less.
Anyway, we've got a great little community here, so let's keep doing what we do!
Regards, PAul.
"I take your point about me concentrating on quality over quantity though. I'm bored with going through the motions on companies that don't interest me. So increasingly, the format here is for me to concentrate on 2 or 3 companies that I think look the most interesting, then just do a few snippets on boring shares afterwards."
You could ask the tech bods at Stockopedia to develop a program that runs at 8am every day that cross-references tickers with results on investegate with the associated StockRank and Guru Screens matches -- the idea being you would receive an automatic report in the morning showing which RNS tickers could be of more interest to Stockopedia users. The program could also filter for less than £Xm market cap etc.
That may save time instead of looking through the RNSs then checking on Stockopedia manually for interesting shares you have not come across before.
Hi Paul - would welcome your thought on Haynes Publishing (LON:HYNS) who have released their results today. I like the company as they have an excellent brand and after many torrid years are now finally turning a corner with a new and refreshed Board. Digital sales growing strongly. HaynesPro a slightly hidden gem and lots of freehold assets. Lots of work form them to do but a nice dividend whilst waiting for the recovery.
Hi Drvodkaquickstep,
I've had a skim of the Haynes Publishing (LON:HYNS) results.
The narrative sounds as if serious efforts are being made to streamline & modernise the business.
However, the elephant in the room is the pension deficit - it's £15.1m on the balance sheet (not far off the same as the company's market cap). Accounting deficits are usually smaller than the actuarial deficit too, so the problem could even be bigger than that. With interest rates low, and getting lower still, pension deficits are getting worse, not better.
With the controlling party being a 55% family member, I wonder how steeped in history the company is, versus actually being commercial?
Overall then, it might have some potential, but the big pension deficit probably kills it for me.
Thanks for flagging though.
Regards, Paul.
The other important thing to note about Haynes,other than the pension deficit which Paul flags,is that it has two categories of shares in issue,firstly circa 7 million that are listed on the Stock Exchange and can be freely traded & secondly another circa 8 million restricted unlisted shares which are owned by the Haynes family that are unlisted, making 15.1 million in total.Both categories rank equally in regard to rights.
The London Stock Exchange site does not take this into account when it lists Haynes market value.
Grateful for your originally bringing Begbies to my attention and I will continue to hold as have done for 4 years and may add. As you say seems competently run, founder still has a good stake and an excellent hedge against recession. And over the four years Ive had a significant uplift in share value and a 4.7% dividend rate per year. What not to like :)?
What not to like :)?
This sparked my interest so I looked at the StockReport page to see if it passes my filters for further investigation as a long term income paying hold. The problems I see are:
1. Inconsistent dividend cover
2. Low ROCE (as a general aside I don't understand how the Quality Rank can be so high when ROCE, ROE & Operating Margin are all quite low?)
3. EPS growth is negative for every year shown
So maybe the sustainability of the dividend is questionable?
Although the earnings are poor, because of the high level of intangibles on the balance sheet a fair amount of the costs going through the P/L are non-cash items. The free cash flow has been quite strong over the last four years, despite the so-so environment. I do not own the stock but I am quite tempted by it.