Small Cap Value Report (24 Mar 2015) - ACM, CTO, GTC, VLK, SKP

Good evening. Sorry for my absence yesterday & earlier today, I've been unwell, so spent 3 days in bed. Anyway, let's get this show back on the road! I'll do a report for today, and then circle back to yesterday's later this week, as I definitely want to comment on results from Spaceandpeople (LON:SAL) as it's not clear to me why the market marked the shares down 20% yesterday, as they reported in line with revised expectations.
Accumuli (LON:ACM)
Trading update - this IT security group reports that group EBITDA is line with management expectations for the year ending 31 Mar 2015. The detail sounds positive too. However, Accumuli inexplicably fails to mention the elephant in the room, which is that they've sold the company!!
Recommended acquisition - a separate announcement is today issued by NCC (LON:NCC), saying that it has agreed with the Board of Accumuli to buy Accumuli for mainly shares, but some cash. Normally when you look at takeover deals, you think to yourself, this is a done deal. However, in this case I think this deal looks a bit wobbly.
Firstly, the premium to the market price is not enough. They are only offering a 19.1% premium, at 32.8p. Takeover deals really should be at least a 30% premium to tempt shareholders to bank the profit now, rather than going it alone.
Secondly, the deal is only 5.97p in cash, and the balance of 26.83p in 0.1218 new NCC shares. Trouble is, NCC shares have already dropped sharply, down by 7.7% today to 203p. So that now values the takeover at 5.97p cash + (0.1218 * 203p) = 30.7p. That's now only an 11.6% premium to the share price last night. It's not enough, so I think NCC will have to dig a bit deeper to get this deal done.
However, the big shareholders have agreed the deal, and the company has 57.3% irrevocable undertakings to support the deal.
My opinion - this doesn't look a particularly good deal for Accumuli shareholders, but maybe the big shareholders prefer the idea of holding more liquid shares in a much bigger group (NCC is about 10 times the size of ACM in market cap). I would be pushing for NCC to sweeten the deal with a higher price, so for me (if I held the shares), I would be voting no.
It's also not great for NCC shareholders, who have seen their share price drop sharply on the news, so the board of NCC are probably already getting complaints from their shareholders. Doing a mainly paper deal, means that the NCC share price is likely to remain weak, as Accumuli shareholders take advantage of the increased liquidity to exit.
This type of situation is sometimes quite amusing, as Directors who have spent years telling everyone how brilliant their company is, now have to suddenly start telling everyone the complete opposite - how limited its potential is as an independent company, and being part of a bigger group would be much better!
T Clarke (LON:CTO)
Share price: 70p
No. shares: 41.8m
Market Cap: £29.3m
(at the time of writing, I hold a long position in this share)
Final results - for the year ended 31 Dec 2014.
I flagged up the turnaround potential of this company in my report here of 13 Nov 2014, when the shares were 50.75p, indeed I bought some personally shortly afterwards, having mulled it over a bit more. So far so good, as they're up almost 40%.
If you don't have the time or inclination to recap on my previous report, then the summary version is that this company now appears to be in a cyclical sweet spot, where the order book is filling up, and margins & cashflow are improving. The company does complex electrical fit-outs of office blocks, especially in London. So it lags behind the building cycle by 1-2 years, as obviously the building has to be built before it can be fitted out.
This company has a strategy of accepting low margin work in a downturn, to keep its workforce busy. However, they then have the workforce with the right skills & experience, to take on complex projects when the economy improves, as is happening now.
Profitability - at first this looks poor, with "underlying operating profit" down from £3.2m in 2013 to only £1.4m in 2014. Underlying profit before tax of £0.7m is £200k above broker consensus. which is shown on Stockopedia as £0.5m net profit expected by brokers for 2014.
These are very small numbers though, for the £227.5m turnover, so clearly this share would not be of interest if that level of low profit was likely to be ongoing. We saw recently with ISG (LON:ISG) what happens when a low margin contractor runs into contract problems - they had to do a rescue fundraising, and the shares lost half their value (as well as the dilution from new shares).
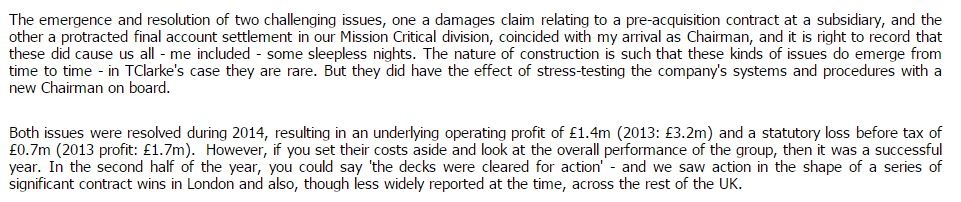
One-off contract issues - this is crux of the matter, so I am reading the narrative now to find some more detail on this, i.e. what went wrong in 2014, and how much that affected profitability? It doesn't seem to be that significant after all, and I am left wondering why underlying profit fell, since it adjusts out these one-off factors?
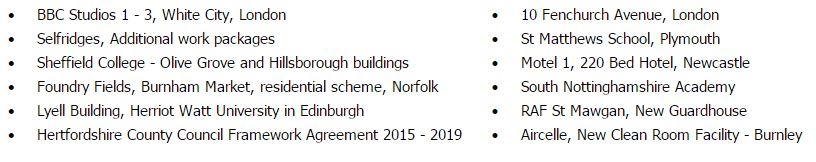
Order book - has risen strongly, and is now over £300m, including some high profile contract wins;
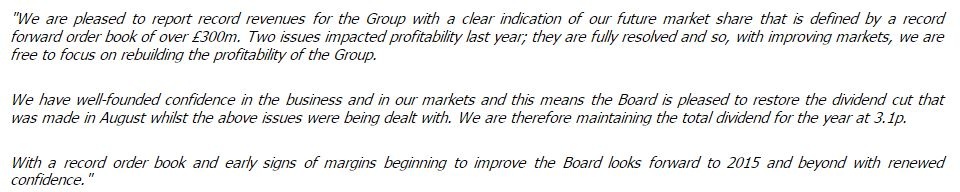
Dividends - it's pleasing to see that the company has restored the divi, which was cut in Aug 2014 as the company was dealing with contract issues (which have now been resolved). At 2.6p the final divi is generous, being up nearly 24% on last year's final divi. The total divis for 2014 are 3.1p, flat against last year. That gives a good divi yield of 4.4%, and I suspect the divis will now be on an upward trajectory over the next few years, as business improves.
Balance Sheet - not great, but not a disaster. It fails my NTAV must be positive rule. So taking off intangibles of £23.2m, net assets of £18.9m become modestly negative at -£4.3m.
The current ratio is 1.15, which although it's below my (arbitrary) lower limit of 1.2, it should be pointed out that T.Clarke has hardly any inventories. So it can operate safely with a lower current ratio - I normally go down to 1.0 for companies with little to no inventories.
The net cash position has greatly improved, from £1.0m a year ago, to £5.3m at 31 Dec 2014. That helps support the idea that they are gaining new work on more attractive terms than the old (i.e. customers can be persuaded to pay more up-front).
Note there is a pension deficit, which stood at £16.3m at 31 Dec 2014, quite a material amount, so investors will have to decide for yourself whether you can tolerate that risk or not.
Outlook - they sound confident about the future;
My opinion - I like it, as a very straightforward cyclical turnaround situation. The market cap is only £29.3m, so if the company gets anywhere near the 5% operating margins that it made at the height of the cycle last time, then a share price of 200-300p could be justified - which indeed is where the shares did trade before the financial crisis in 2008.
Note that T.Clarke has got through the depressed 7 years since without issuing any major number of new shares. So no adjustment to share price target is needed there, and it gives me confidence that they have the expertise to handle difficult conditions.
On the downside, I don't like low margin contracting businesses, as something always ends up going wrong with some contracts sooner or later - indeed that jumps out of the page today reading the 2014 results.
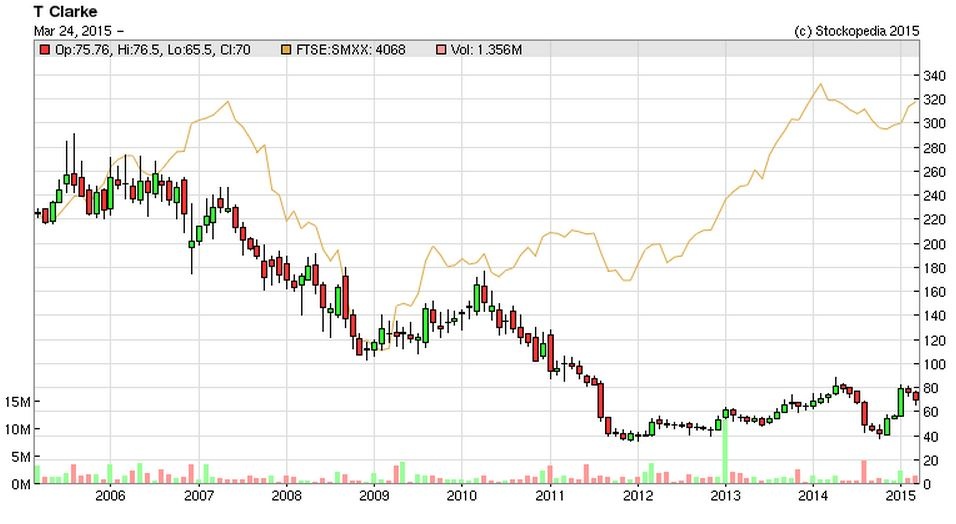
Here is the 10-year share price chart. I suspect that, providing there aren't any major problems along the way, it might continue gradually recovering from here, and shareholders are being paid decent divis whilst we wait - always nice!
Getech (LON:GTC)
Share price: 47.5p
No. shares: 30.3m
Market Cap: £14.4m
Interim results - for the half year to 31 Jan 2015 - look surprisingly resilient, considering the sector that Getech operates in (providing seismic services for oil exploration). The company makes some very interesting comments about current market conditions;
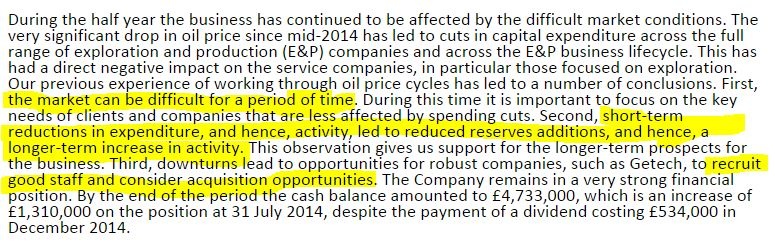
Strong cash balances are key, in my view, in the oil & oil services sector. That's certainly the type of share that I'm looking at in these sectors. Let the hot money chase the more highly geared stories, I'd rather have sleep at night safety. You only have to look at Afren (LON:AFR) to see what happens when a highly geared balance sheet implodes.
Balance sheet - this is strong, with £7.0m in NTAV. The current ratio is healthy, at 1.74, and there is no debt. Net cash is £4.7m, about a third of the market cap, so all good there.
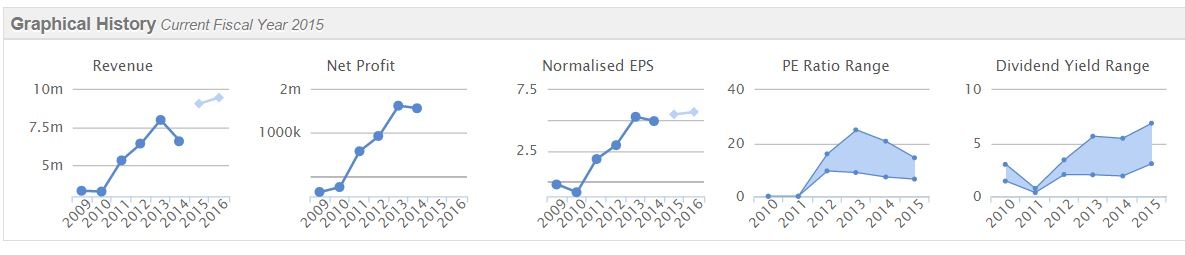
Profitability - this rose from £233k last H1 to £707k this H1, so a big increase there, surprisingly. Although this was only on £3.6m turnover, reinforcing that this is a very small company.
As you can see from the usual Stockopedia graphics below, the company has a good track record of profitability, but of course that was when the oil price was much higher. So is that sustainable, once the current order book has washed through, I wonder? There must be a high risk of another profit warning here, in my estimation. Also, will it hit full year forecasts?
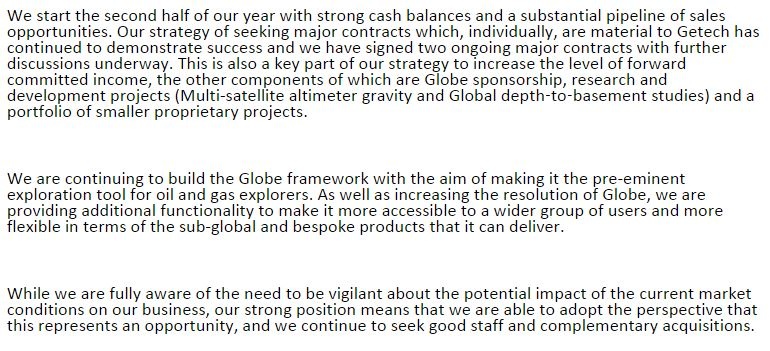
Outlook - sounds pretty buoyant, but sounds as if (as before) major contract wins provide the potential for a profit warning, if they don't close on the right side of the year end;
My opinion - Getech seems to be weathering the downturn in the oil sector remarkably well so far. On balance I think it's too small a company for me to want to get involved again (I've held before).
Vislink (LON:VLK)
Share price: 48.75p
No. shares: 122.6m
Market Cap: £59.8m
(at the time of writing, I hold shares in this company)
Final results - for the year ended 31 Dec 2014 are out today. The headline figures look very good, with adjusted operating profit up 66.1% to £7.2m, but on digging into the detail, it transpires that a strong performance from the Pebble Beach Systems software company acquired, has considerably more than offset a relatively poor performance from the existing hardware business (specialist cameras for broadcasting, and security systems).
The Executive Chairman here is a serial acquirer of other companies, and so far, from what I can tell, he seems to be getting it right.
Thinks I like;
- Pebble Beach already contributing over a third of profits
- Dividend hiked by 20% to 1.5p (yield = 3.1%). Note there is no interim divi.
- Balance sheet is still solid overall (but see point 3 below)
- Profits do look real - operating cashflow rose from £4.2m to £7.7m
- Reduction in capitalised development spend, from £4.5m to £3.6m
- Some promising new products in the pipeline - e.g. wearable cameras for sportpeople
Things I dislike;
- Core business saw turnover down 10.4%, and profit down 12.9%
- Debtor days & stock days both high, due to phasing of big orders
- Intangibles now £43.7m of £56.8m net assets
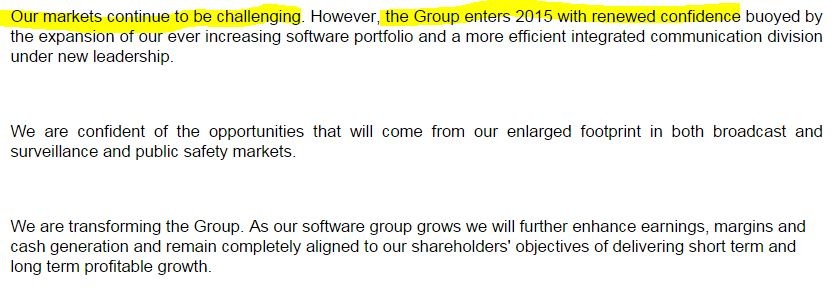
Outlook - I tend to put more emphasis on the "markets continue to be challenging" comment, than the "renewed confidence" comment!
My opinion - overall, it looks quite promising. The valuation is modest (about 11 times EPS forecast for 2015), and the balance sheet is alright. There's a reasonable divi to keep us amused whilst we wait. The software company acquisition seems to have saved their bacon!
It will now be a question of waiting to see how the new products are received. Even though most sports bore me to tears, even I can see that watching sport from helmet cams of the players, would be a remarkable experience - e.g. this video gives a flavour - GoPro is the company that Vislink has partnered with.
SkyePharma (LON:SKP)
(at the time of writing, I hold a long position in this share)
Final results - for calendar 2014 are out, and look impressive to me. I rarely touch pharmaceuticals companies, as you really need sector knowledge to get it right. However, I've held this one for a while because it came up on a GARP screen that I ran.
There was a bit of a wobble in Jan 2015 when the market sold off the shares on a statement about possible deferral of some milestone receipts, but the price has since recovered well - another example of how buying on minor bad news can be a very good thing - a theme I'll be talking about more this year.
Revenues rose 18% to £73.8m, and pre-exceptional operating profit shot up 67% to £22.7m. Impressive stuff. Moreover, the growth seems to be coming from recently launched products, and on outlook they say;

Sounds good to me.
Balance sheet - the historic issues have been dealt with, and the company now passes all my balance sheet tests comfortably. It had net cash of £15.0m as at 31 Dec 2014.
My opinion - broker forecast for 2015 is about 20p EPS, and note that has been creeping up over the last year, usually a good sign. Therefore at 321p the fwd PER is about 16, which doesn't seem expensive for a growth company. There's also potential for a takeover bid with this type of company.
Right off to bed, I've got another report to start writing in 8 hours' time!
Regards, Paul.
(Paul has long positions in SAL, VLK, CTO, SKP and has a short position in AFR. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Thanks Paul, PMR is a bit of a frustration for me. I bought after decent results in September and it's been a hard slog ever since! Was hoping for a positive reaction yesterday but that didn't happen. The introduction of a divi after 8 years has to be good news and profits up 84% too. It just doesn't seem to get the markets interested despite it being so cheap. I'm kind of in 2 minds, but if I put my long-term value hat on it still seems an anomoly to be this cheap - I just wish management would release a few more meaningful RNS's to publicise the company's progress a bit more, maybe it's just under the radar for most investors.
Great to see you back Paul and hope you are back to full fitness for the ED event tonight ?. If I had just a tenner from everyone who has asked me where & how you are ? then I could have set up a competing bid for ACM this morning ! lol Seriously you are massively followed, much respected for your honesty and regular updates and more importantly loved by thousands for the person you are. Do not feel obliged and take rest when you can but just keep one or two of us posted as everyone takes for granted that you will be tweeting and posting at all hours....D
Hi Paul,
Worth noting that Getech also announced the acquisition of ERCL today which will change the balance sheet and number of shares in issue. Details as follows:
· On the date of completion, an initial payment of cash £1,750,000
· On the date of completion, an initial issue of 2,176,630 shares. Application will be made to admit these shares to trading on AIM and it is anticipated that trading in the shares will commence on 13 April 2015. It is agreed that the shares will be retained by the ERCL shareholders for a minimum period of one year from completion. A further announcement will be made when the transaction completes and the shares are issued.
· Deferred consideration, based on the performance of the company over a three-year period. This has an expectation of generating a total of £1,550,000 over the three years if performance targets are met. The deferred consideration will be based on the profit before tax to the extent it exceeds a hurdle level in each year.
Bank loan
Although Getech has strong cash levels, a loan has been arranged with RBS/NatWest for £1.1m, repayable over four years or less (at Getech's discretion), with interest rate at 2.04% above base rate. The loan is secured against the Getech office building in Leeds. The Directors believe this is the prudent approach and will reduce the up-front net cash cost of the deal to £650,000.
The expected value of the aggregate consideration is £4,300,000.
Glad to hear your Mojo is back!
All the best
Si
Glad to hear you're on the mend Paul, it's been a quiet couple of days without you're cracking reports!
Any thoughts on PMR if you get the chance would be much appreciated - I see they're finally paying a divi again, but the market's not been too keen, down 5.9% today.
Thanks, James
Hi jimbobjames2002,
I had a very quick look at Panmure Gordon & Co (LON:PMR) results (which I hold), and thought they looked good, with positive outlook. So very odd that the shares fell. Very illiquid micro caps do this sometimes though - it only takes one or two holders who haven't really been following trading updates, to look at the results, and think they're bad, and to sell, to knock the price back temporarily.
What is your views on the results from PMR?
Regards, Paul.
Welcome back Paul.
Re: Panmure Gordon & Co (LON:PMR) I came close to picking some stock up within the last few months ahead of a good set of expected results and resuming dividends. I didn’t buy so have no position. The headline figures for me look lacklustre. H1 pretax profit £1.9m, full year £2.15m. H1 of 2014 was a good time for IPO’s in general for the whole industry. I’d like to see another set of results before I take a position here.
Paul do you have any insight into the employee benefit trust that the company runs? They add 20,000 shares PCM which now equates to approx 8% of the company. Presumably this is by way of giving employees a share of the company / a bonus. Would they then be free to sell down those shares? Not that these would all come to market at the same time but isn’t this like having a massive overhang which could drag the already illiquid shares down in the future?
Good to see that you're on the road to recovery Paul - I was wondering if completing your accounts had finished you off!
As for Spaceandpeople (LON:SAL) my feeling is that the outlook statement was rather bland and didn't give me the feeling that the company was about to come roaring back. So while the balance sheet has nicely protected the downside I'm of the opinion that we'll need a bit more red meat from the directors in order to get the share price moving upwards.
Hi RandomAmbler,
Yes you could be right. I quickly skimmed the SAL results yesterday on my iPad (in bed), and was staggered to see the share price down 20%, when the figures were actually a bit better than I had been expecting.
Possibly the narrative spent too long dwelling heavily on what had gone wrong in 2014, and maybe that somehow set a negative tone? It might had been better if they had just kept it short & sweet on the problems in 2014, and said that they've fixed the things that went wrong. Sometimes less is more.
Still, it's looking dirt cheap again, mkt cap of £10m, and a good divi yield of c.4%, with scope for that to rise considerably, given past divi history. The balance sheet is fine. Outlook - as you say, not sparkling, but I think the market has overlooked the potential for their new "promotional pods" - the economics of these are really very good indeed, and my back of the envelope figures suggest that they could drive a big increase in profits over the next 2 years, as they are rolled out.
So 100% upside on Spaceandpeople (LON:SAL) is the target I have pencilled in. It's cheap on a fwd PER basis, Stockopedia has it on a fwd PER of only 7.7, with a 5% forecast yield. Moreover, they're battle hardened now - having had a tough year, I think mgt have sharpened up their act & slimmed down the reporting lines internally, etc.
It scores a very high StockRank too, of 96. So in my view this looks like a good buying opportunity, possibly, providing nothing else goes wrong of course.
Regards, Paul.
Hi Paul,
These are all good points and I'm inclined to agree with them but it's worth remembering that this is a £10M micro-cap which has shown itself capable of being badly wrong-footed by its customers. So it's not clear to me that the company deserves any sort of premium rating at the moment and it's going to take time to re-build trust in the management - and this won't happen without the management delivering and being a bit more positive!
Also the forward P/E of 7.7 is for 2016 - for this year the forecast is 9.3 and I don't think that that's unreasonable given how far the EPS forecast has been downgraded (12.6p to 5.34p). So I don't think the Spaceandpeople (LON:SAL) is massively cheap at the moment but it could be if the next management statement has a bit of life to it!
Cheers, Damian
Hi RandomAmbler,
A nice summary, which I think is fair.
Note also that, given the debacle of 2014, management at Spaceandpeople (LON:SAL) have radically changed the forecasting process, and this was something I discussed with them face to face last year. From now on, they are not forecasting ANY new business. Just existing business. So the forecasts really should be close to the worst case scenario (unless they fail to win any new business AND lose existing clients, which I suppose is possible!)
Cantors reinforce this point today in a note which said;
"Results today confirmed SpaceandPeople’s 2014 profits came in a shade above management’s £0.8m-£1m guidance for adjusted pre-tax profit. Management was able to successfully replace business from 2013 that did not repeat and has put the company on a firmer footing going into 2015. Management prudently guides to stable sales this year with profit growth coming from more efficient operations. We think that's conservative given all the main units continue to actively pursue new business but base our forecasts on that outlook to also stay prudent. We expect new business to drive growth from 2016 onwards. Our 2016 EPS implies our new TP of 73p (from 68p). The 30% upside means we maintain our BUY recommendation."
Thanks Paul that's very interesting - so management have swung towards being pessimistic just so that they don't caught out! If all goes well then this could lead to upgrades to forecasts later in the year. That said I'm going to wait for the chart to flatten out and kick up like I thought it had earlier in the year - wasn't this something that CockneyRebel mentioned as a way to avoid buying a share that hasn't stopped sinking?
Hi RandomAmbler,
Exactly. Spaceandpeople (LON:SAL) mgt came in for a lot of heavy criticism (rightly so) from shareholders last year, and they listened, and acted. So the budgeting process has been changed that instead of putting out their best guess internal budget to the market (which will make assumptions about existing & new clients), they now put out the "base case" budget - i.e. the minimum they think can be achieved on business they already have.
Therefore, we should see a new pattern emerge, of the company gently revising up forecasts as the year goes on. Of course you can't rule out another setback, the nature of their business is that they do lose clients every now and then, but in the past they've had no trouble replacing them. 2014 was unique in that, after 5 successful years, a whole load of things went wrong simultaneously.
You can see from the Stockopedia graphs that from 2009 to 2013 inclusive, the company had an excellent track record of increasing turnover & profits each year. To my mind this should be taken into account, whereas at the moment the market is harshly judging the company on one bad year.
I'm too tired to come into London today for the presentation by SAL meeting at the EDIF meeting, but would be interested to hear any feedback from people who do attend.
The market has not yet latched onto the fact that SAL has successfully trialed high margin promotional pods (available on weekly rental slots to multiple organisations) in some UK shopping centres, and that these are going to be rolled out in 2016. They should provide quite a substantial boost to profitability.
For that reason, I'd be surprised if SAL shares don't get back to 100p+ in 2016.
I'm more with RandomAmbler/Damian than PaulyPilot/Paul on Spaceandpeople (LON:SAL). Over the last year on these pages I have been very critical of SAL's management and communications with the market but I'm a little less so on the latter point now. I wonder about Paul's remark:
Possibly the narrative spent too long dwelling heavily on what had gone wrong in 2014, and maybe that somehow set a negative tone? It might had been better if they had just kept it short & sweet on the problems in 2014, and said that they've fixed the things that went wrong. Sometimes less is more [my bolding].
We need all relevant information we can get particularly on a company attempting a turnaround. The volume, relevance, clarity, and veracity of RNSs are important and spin should be minimised (a forlorn expectation, I know).
Agreed. Also given the slack they got for not communicating enough at the time of the original profit warning, we can't now blame them for communicating too much and too clearly.
Hi Paul, Hope you continue to feel better. Like others, really enjoy reading your reports. Any views on IQE's results today too? Thanks.
Hi MaxPower27,
I've had a very quick look at IQE's results. My problem with this company is that I don't really understand what it does, nor its marketplace.
Adjusted profit is up nicely, from £13.0m to £16.2m, but the adjustments are big, at £10.9m.
The segmental analysis shows turnover down sharply, and profits halving at its largest division, Wireless - that's a worry, and could explain why the shares appear cheap on a PER basis, maybe?
The fwd PER is only about 9 for 2015, so it might be worth a deeper look? No divis though, which I'm not keen about.
If you like it, then do pls feel free to explain why.
Regards, Paul.
Hi Paul glad you're feeling better. Welcome back.
Echoing others. Glad you are ok and nothing serious.
Hi Paul relieved to hear you are ok, was worried as you were 'offline' for so long.
Really missed your reports and your tweets!
Cheers
Jon
Hi Paul, really, really, really missed your reports these past 2 days, especially with the deluge of annual results released. Great to know you are feeling much better. Thanks so much for your valued opinions.
Cheers guys! I took a multivitamin & went for a walk in the sunshine a few hours ago, and that seems to be restoring my mojo!
P.
You've been missed, Paul. Good to hear you are well now. I hope you will comment on VLK and look forward to your thoughts on SAL in due course. Thanks, Alan
Paul - Good to hear you are back and agree with your initial assessment of SAL - the results were hardly a surprise.
Welcome back, glad you are on the mend
Nice to see the SCVR and I'm sure a lot of subscribers have missed the daily reports.
Imran.
Welcome back Paul, I was getting a bit worried about you!
Get well soon my friend
Glad to hear you're okay,Paul !