Small Cap Value Report (28 Jul 2016) - BON, IPEL

Good morning!
It's starting to feel like a bull market again, with some remarkable recoveries in share prices from the recent Brexit sell-off. This is probably because most companies reporting seem to be dumbfounding the doomsters, and saying that it's pretty much business as usual.
Although we should also bear in mind that economic downturns happen gradually, and then feed on themselves, so we could have a deterioration yet to come. I have been pondering the recent comments from Victoria (LON:VCP) (in which I hold a long position), saying that the impact of Brexit is positive for them - mainly due to weaker sterling.
This got me thinking - we don't have to buy or hold the entire market. We can & should cherry-pick. So based on reports from many companies in the last month, at the moment I'm looking for bombed out shares with the following favourable characteristics;
Dollar earnings - or a broad spread of international earnings, which insulates (or benefits from) translation into weaker sterling. E.g. Empresaria (LON:EMR) , or 4imprint (LON:FOUR) .
Exporters - companies based in the UK which export a lot of product - they just got a lot more competitive (although bear in mind that any imported raw materials they use will also rise in price).
Import substitution - UK vendors of products, which are benefiting from weaker sterling, and can steal market share from imports - e.g. Victoria (LON:VCP)
Hospitality - forex movements, and terrorism means more people holidaying in the UK. Also there is some evidence that UK consumers want to do more things, rather than buying more stuff. Pub groups have been reporting good sales recently.
Defensive - anything non-cyclical, or counter-cyclical is worth considering, if it's cheap, and you think there's a recession coming (personally I'm not convinced there necessarily will be a recession, but we'll have to see).
Growth companies, particularly small caps, which have found an exciting niche, tend to carry on doing well, even in an economic downturn. So I'm thinking here about successful, rapidly growing e-commerce businesses, for example Boohoo.Com (LON:BOO) (in which I hold a long position).
Oversold - companies which are trading well, and have stated a positive outlook recently, but where the share price has been battered well below what seems sensible - a good example of that is I think Staffline (LON:STAF) (in which I hold a long position)
That's not an exhaustive list, but I think it provides some interesting areas to focus on, if you think the UK economy is likely to contract.
Of course, if the UK economy does better than expected, then sterling could recover against the dollar, and the opportunities above would then reverse! So it pays to stay vigilant, because things can change rapidly as the market anticipates likely economic changes, and re-prices everything very quickly these days. E.g. look at the astonishing movements in housebuilders' shares recently - very violently down, and now rapidly recovering. Although personally I've now banked the recent profits on all my housebuilder shares.
On to today's small cap results & trading updates.
Bonmarche Holdings (LON:BON)
Share price: 109p (down 6.4% today)
No. shares: 50.0m
Market cap: £54.5m
Q1 trading update - covering the 13 week period ended 25 June 2016.
To recap, I last reported on this value clothing retailer here on 10 Jun 2016, reporting on its full year results to 26 Mar 2016. The figures then showed that a 0.7% increase in LFL sales wasn't enough to maintain profitability, which dropped by nearly 15%.
In its outlook statement back then in June, it said that;
The beginning of FY17 has continued to be tough due to poor weather, however our full year expectation is unchanged provided trading conditions normalise. [PS: from 10 Jun 2016 update]
Today, the Q1 update gives figures, and they're very poor in my view, key points;
- LFL store sales down 8.1% Y-on-Y in Q1 - much worse than the previous quarter, when LFL was up 0.4%.
- Website sales have also gone into decline, down 2.7% Y-on-Y, in Q1.
- Blamed on bad weather.
- Full year expectations unchanged:
"our expectation for the full year remains unchanged on the assumption that trading conditions normalise through the autumn season. The Company's financial position remains sound.
Sorry, I don't buy this explanation. Poor weather had some impact on clothing sales in Apr-Jun, but not enough to cause an 8.1% drop in LFL sales. So the company is in denial I think, and it clearly has some home-grown issues that it's not facing up to.
You hardly ever hear clothing retailers say that our stock wasn't good enough, and we lost market share because competitors were better than us. Yet that's what the truth very often is, when weather is blamed.
For that reason, I am deeply sceptical that it will indeed meet full year expectations - another profit warning looks a virtual certainty to me, later this year. Something along the lines, of that trading has improved, but not enough to recoup the Q1 loss.
Brokers are lowering forecasts, usually a sign that things are not going well, and often the revised forecasts are still too optimistic;
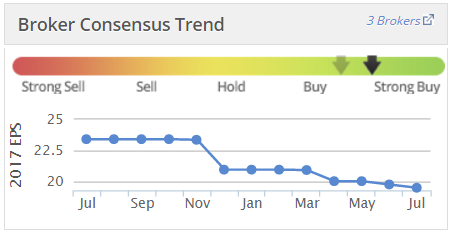
My opinion - I've been an investor through several economic cycles now, and over time you get better at spotting trends. Lower net margin retailers can be fantastic investments in a recovering economy, as they have high operational gearing.
However, in an economy which is turning down, that operational gearing works in reverse. So a 5% net profit margin turns to zero, or even losses, if sales fall by c.10%. That's not far off the sort of fall BON is reporting for Q1. Remember that their costs are rising too, with various measures which are putting a greater burden on employers, such as Living Wage, but also pension requirements, and the forthcoming apprentice levy.
So I reckon profits could easily crash at this company. It was these fears which led me to sell my shares for a loss recently. Clothing retailers are also big importers, so they're facing another headwind from higher import prices next year, once forex hedges expire.
It looks superficially cheap, but I think it could be a value trap, with worse news to come potentially.
Optimists may disagree though. So if the company does indeed claw back its Q1 shortfall later this year, then the current fwd PER of just over 5, might end up looking like a bargain. The forecast divi yield is also attractive, but again I wouldn't hang your hat on that yield being maintained.
I think High Street rents will need to come down substantially, over time, especially in secondary locations. So extreme caution is needed when looking at property companies focused on retail.
Impellam (LON:IPEL)
Share price: 670p (down 1.1% today)
No. shares: 50.3m
Market cap: £337.0m
Interim results - for the 26 weeks ended 1 July 2016. As with Staffline yesterday, I'm impressed with the prompt reporting schedule.
The highlights section looks good, but digging a bit deeper, I'm less impressed.
Growth has come from acquisitions, and that has seen a very large increase in net debt, up from £39.4m a year ago, to £109.7m now. Although the latter figure is £8.5m down from 6 months ago.
I tend to look closely at gross debt, because many companies squeeze their working capital at the interim & year ends, to minimise net debt (i.e. gross debt, less cash), hence presenting the most favourable possible picture. This makes Enterprise Value quite a dangerous concept, as it's often valuing a company on a very atypical net cash figure, which may have been window-dressed for the period end. To be more reliable, Enterprise Value really should be based on average daily net debt throughout the year.
Gross debt can often be a more reliable indicator of the worst position for cash/debt in the year. So a pessimist would value the company using gross debt, and ignore cash altogether.
In this case, gross debt is £188.3m, which is too high for comfort, in my view.
Adjusted EPS is 36.1% higher, at 44.9p for H1, but this is flattered somewhat by a low tax charge, so that would need checking.
Outlook comments seem less confident than what we had yesterday from Staffline (LON:STAF) (in which I have a long position), but are still saying in line with expectations;
Like many of our competitors, we have seen a softening in the permanent recruitment market in the UK since Q4 2015. Given the current social, economic and political uncertainties in the UK we do not expect this outlook to change.
However, we expect our businesses to continue to perform well in our key markets and we are confident that our differentiated high retention strategy, our portfolio of market focused contingent worker Specialist Staffing businesses complemented by our high performing Managed Services businesses, will deliver results for the full year in line with management expectations.
I saw somewhere else that Impellam makes 90% of its gross profit from temps, and that still seems to be a buoyant area in the UK.
Valuation - if we assume that nothing goes wrong, and full year forecasts are indeed achieved, then the valuation looks appealingly low;
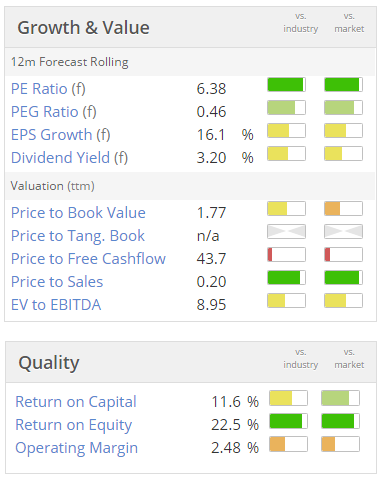
Note the "n/a" next to "Price to Tang. Book" - this is a very useful quick check - it means NTAV is negative, indicating a weak balance sheet.
My opinion - despite the low PER, I can't get comfortable with this share - it's one I've held before, and done well on.
The balance sheet seems weak, with too much gross debt. That wouldn't necessarily be a problem, if the business was delivering strong organic growth, and throwing off a lot of cashflow, but that doesn't seem to particularly be the case.
The shares are very illiquid for the size of company, due to Lord Ashcroft holding nearly 52%, and other large shareholders, making the free float quite small.
The spread of international business is good, which should help smooth out forex movements, and boost sterling profits.
Overall, given that they are on not dissimilar valuations, my preferred pick is Staffline (LON:STAF) (which I already hold, and have bought more today). STAF looks to me more like an out-performer, compared with IPEL, which seems to be struggling a bit in some territories and recouping it in others.
Also I like the way STAF is rapidly repaying its debt, and should be debt-free by the end of 2017, whereas that doesn't look likely here with IPEL.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Re Bonmarche
I have an interest in a small retailer of ladieswear for the over 45s , and we had a very difficult Spring period , but started clawing back sales from May onwards till we are about level by now.
I think 8.1% drop is not entirely due to the weather and that there must be other factors.
Also the idea of clawing back in the Autumn is not a given - with a new season range there is a whole new ball game .
Just my 2P worth
Calahan
I could could be wrong but a previous respondent referenced I believe the Morningstar absence of broker note info is down to new regulatory guidelines that giving broker notes may amount to investment advice.
Obviously silly if true, but sounds very plausible to me, as an example of compliance creep.
Do feel nervous about BON but, having bought some last month, am holding on. New CEO doesn't take up duties until next month.. so not implicated in these poor figures & am hoping she can have a positive impact.
Great list Paul. I would add luxury goods retailers - especially high end jewellery etc. They will benefit from wealthy foreign tourists visiting London - so an extension of your hospitality/exporters categories.
BON has gone from £3 to £1 in around eight months, anyone who was expecting good figures in the short term is deluded, the existing valuation implies trading is currently very tough, retail in general is tough and Bonmarche clearly isn't doing as well as it could be however the company could make 4 - 5 million this year and the shares won't look too expensive, also the dividend is not very important when the share price has tanked 50 - 60%, as far as I'm concerned they could scrap the dividend until trading improves, I've picked up a few today around £1.05.
Mortgage Advice Bureau (ticker MAB1, the £ marker brings up Mitchell & Butlers) had a trading update today. I hope this isn't considered bad form. I think it's an interesting company.
1. It's very profitable. Looking at the income statement you wouldn't necessarily recognise this because about 75% of their revenue is redistributed to their appointed representatives in contractually agreed commission payments. If you look at net income as a % of gross profit, it's about 50% (FY15).
2. It requires very little capital to grow and distributes a large percentage of profits in the form of dividends. Projected dividend for YE 12/16 is 17p on EPS of 19.3 and a share price of 300p. It's quite possible that the 17p EPS excludes the previously announced special dividend of 4.25p resulting from their being bought out of a JV. YE 12/17 projected dividend is 20p on 22.6p EPS. They paid 14.4p for FY15.
3. The company has a stated target to grow the number of advisers at 15% per year. This was, in a previous results presentation a 5 year term, subsequently changed to medium term. However, the Rule of 72 tells me that a 15% CAGR in advisers means that adviser numbers should double in a little less than 5 years. Assuming that adviser efficiency is constant, revenues should be double if the mortgage/remortgage market is flat. At 30 June, the number of advisers is +13% on YE 12/15 so they've nearly met their full year target at the half year stage.
4. You can check on the market the company operates in by looking at the CML figures for gross mortgage lending (yearly forecasts and monthly after the fact estimates). It provides a useful sense check. In the post-Brexit aftermath, the shares dropped to about 200p (from 400p earlier this year) even though the CML figures indicated that Jan-May 2016 numbers exceeded Jan-Jun 2015 (ie Jun could have been zero and the company still should have had a decent first half). Indeed the shares rallied when the Jun CML numbers came out a few days ago and showed YoY growth.
5. There could potentially be a network effect here as the company grows. The company represents about 4% of the mortgage market (not sure whether that's total mortgage market or 4% of the 70% of mortgages that are advised) and intends to double that with the 15% adviser growth target. If they do get to 8% there could be modestly better terms (relative to other advisers or non-advised customers) they might be able to offer through their adviser network . Maybe something along the lines of how Hargreaves Lansdown has negotiated slightly lower OCF for their fund holders holding through HL with an exclusive fund class (most of which HL takes back in the form of a higher custody fee).
6. I think there are still risks to 2H16 forecasts even though the company said they were "overall" on track. 2H15 was £44.3m in revenue and they need £50m in 2H16 to hit the £93m FY16 target. The good news is they have 23% more advisers (891 vs 722) entering 2H16 than 2H15. The bad news is that 2H15 was very strong (£118.5 bn gross mortgage lending vs 1H15 £93.5bn and 1H16 about £140bn). Also, they will lose a small number of advisers when the JV is officially sold though this will reduce exposure to London to about 6% of revenue.
I am a holder.
Totally agree, MAB is a cracking business, I know it well having held since IPO (recently topped up on price weakness), and knowing one of the original founders too. They have committed to paying out 90% of earnings, and even with a potential slowdown in the market the increase in adviser numbers should at least keep earnings steady, though I can see them beating expectations if the market does hold up.
I see the London disposal as positive, as that top end market seems the one most likely to come under pressure in terms of volumes, which is more important to MAB than house prices, and also investors don't tend to buy the add ons like life insurance that a first time buyer usually does, and which make up a large % of MAB revenues.
"and even with a potential slowdown in the market the increase in adviser numbers should at least keep earnings steady"
Yes, exactly. And, I think, they have potential to improve profitability over time with scale provided they can hold adviser compensation.
Incidentally, for others, their results presentations are pretty helpful with useful trackers that you can use to measure the progress of the business.
I walk into my local town center every fortnight or so, and glance into Bonmarche Holdings (LON:BON) every time I pass. I have barely seen a single customer in there outside of the Christmas period, and only a handful over Christmas. It's almost like a ghost shop. And I mostly walk in at the weekend when it's not raining - I can't imagine how few customers they have during quiet times or rainy times!
I don't hold (even though I'm normally a sucker for contrarian cheap valuations).
Paul (and also other commenters). Totally agree with your positivity surrounding Boohoo (Lon:Boo). Are there any other high growth e-commerce businesses you are tracking currently that fall into the 'Growth' category in your overview above?
I have now had a response from Morningstar regarding brokers forecasts ad they are now telling me that it is due to the MAR regulations. Funny that shortly before my annual subscription became due it was a bug that they were working very hard to fix.
I have asked them to look at the issue again - especially as they have the consensus forecasts in the Stock Report PDF. I don't hold much hope based on previous experience of reporting problems to them.
@IR35 (and FYI for those interested)
I contacted my broker (TD Direct) last week regarding Morning Star's removal of broker information (because TD Direct gives its users access to MS's data), and after a few minutes wait while the person I spoke to sought clarification on the issue from his supervisor , I was informed that Morning Star would be making the broker information available again "at some point". I asked if MS had given any sort of guidance regarding a time-frame for this happening, and apparently they had not, and had simply said "at some point". I also asked why MS removed them in the first place, and I was told no reason had been given (apparently the first TD Direct knew of it was when users starting contacting them regarding it).
No idea how much of the above is true, or how much of it is simply TD Direct's choice of spiel (or MS's for that matter) for anyone who asks about the missing broker information. I suspect TD Direct know the reason why the info was removed, but are choosing not to tell their users for some reason (or I just phoned at the wrong time and when nobody was around who knew what was happening). Either way I intend to contact TD Direct again at the start of September if MS's broker information has not reappeared by then (or they have not offered their users an alternative source for this information). Doubt it'll do much good in getting the broker information returned, but a clear and precise answer would be nice.
I have contacted Morningstar support again and asked them if I need to report them to the FCA as they are making the consensus forecasts available on the Stock Report PDF :).
Support are going to contact the responsible people and get back to me.
BON - agree entirely, poor figures and poor outlook, however isn't a lot of this built into price? Price seems to include Brexit fear, general retailer market sell off, anticipated profit warning & exit of rated MD. Or clutching at straws?
Proper divirsificaiton means hating a part of your portfolio permanently (it will be different parts at different times but if you don't hate a portion your eggs are in one basket). I have Begbies and H&T as natural hedges, they don't even cost anything as insurance given very nice yields. Key conviction is Accrol Group Holdings, 40% market share with discounters for tissue supply and gaining ever greater momentum with the multiples to supply private lable tissue where branded are seeing their market share erode. 5% yield and minimal CAPEX now after £18m invested over last 3 years. They even have exclusive rights to import New Tissue Techology, yes such a thing exists. Ultra soft apparently.
Paul, can you check your emails please from me, titled Kindred Spirits...
best
Stephen
HI Paul. Enjoy reading your articles. Are you going to be looking at Just Eat or are they too big?!
Nah, Just Eat (LON:JE.) is about 10x too big for me to cover in this report!
Sparkling figures today, but lofty valuation.
P.
Hi Paul,
Would it be possible for you to have a look at Angle Plc? Results out this morning generating its first revenues.
Your opinion is much appreciated.
Thank you
Edward
Hi eddiegoldstein!
You asked me to look at figures for Angle (LON:AGL) today.
I've had a quick look, but it's a jam tomorrow thing, so the figures for y/e 30 Apr 2016 look terrible;
Only £361k turnover
£5.1m LOSS after tax credit
Cash has dropped from £8.4m to only £3.8m in the last year - a cash burn of £4.6m in the last year.
Therefore, if cash burn remains unchanged, then it's going to run out of cash in about Feb 2017 by my rough calculations.
Aha, I've just spotted that it's fixed this problem with a £9.6m Placing (after expenses, done in May 2016). So it's actually now fine for cash, for the time being (i.e. over 2 years), so that's OK.
Overall though, it's just a complete punt. This is a jam tomorrow story stock, and there's a vague chance it might become a multibagger, but the vast majority of this type of stock fails.
So if you fancy a gamble, and like a good story, then this is the type of stock you might like. It's not an investment, it's a total punt! Punting in this kind of thing was the biggest leak from my portfolio, so I've (almost!) stopped doing it now, and the results are much improved.
Regards, Paul.
Not only Living wage for some companies, but pension contributions entitlements coming through in Automatic enrolment (with stage increases over time), and from next year a compulsory Apprenticeship Levy of 0.5% on payrolls over £3m.
Of course the Govt is lowering Corp tax, but as the various costs start hitting above net profit line, it feels like a bit of a spoof to lower Corp tax. But then I may be feeling somewhat tax exhausted, as increasingly I feel like I am working for the Govt, without the relevant State benefits.
Re STAF Iv'e bought some of these this morning. Not a sector I particularly like, but confident CEO statement, 2 x decent size director buys, PE of 7.8, reducing debt from acquisitions quite quickly and a 2.85% divvy. Downside is the 1% op margin which should grow to 3% this year.
If government decides to lift off with the helicopter money and spend on infrastructure this will play into Staffline's hands. We shall see.
I know it's out of your universe, but any thoughts on £LLOY? I thought their numbers were quite good, the restructuring looks to be all but done, the underlying earnings look strong with a PE well under 10 and a dividend hike.
Yes I never thought much of Bonmarche Holdings (LON:BON). I think the new CEO has a lot of work to do to turn this around.
Paul I take you have sold your holding now?
Hi Herbie,
Yes, I mentioned in the article that I have sold out of BON.
I had a general prune after the Brexit vote & big forex movement, of things that I thought would probably suffer in more uncertain times.
Even though BON looked ridiculously cheap at the time, I didn't believe that it would hit forecasts, post-Brexit.
The more I think about it, the more their statement today just doesn't make sense. If any retailer has a lousy Q1, with LFL sales down 8.1%, they usually wouldn't stand a hope in hell of meeting the full year figures. It's too much to drop over a whole quarter, to recoup in the rest of the year.
Their suggestion that they could recoup it, surely suggests that the original forecasts must have been way below what was likely at the beginning of the year? I can't believe there was that much fat in the original forecasts that a lousy Q1 can be brushed off so easily. Sounds to me like management are burying their heads in the sand.
On the upside, BON does have a very decent balance sheet, so I don't think it's likely to go bust. Although a full year result for 2016/17 not far above breakeven wouldn't surprise me in the least.
Regards, Paul.
Thanks Paul, sorry I missed the part you said you had sold. Yes I agree with you about the full years figures, I can see another profit warning later this year unless they have an exceptional autumn.
I see Waterman (LON:WTM) have a new contract and the shares are up 6% today.
I am anticipating a Trading Statement / IMS from Waterman (LON:WTM) either tomorrow or next week and this will hopefully state, as I expect, that currently it's "business as usual" although clearly we must all expect some slow-down in decision making by their clients. I hope that the prices on offer during Brexit fever have encouraged some new investors on board - I have stuck firm with my holding as the business is in great shape from a valuation perspective and the current weakness of Sterling may even encourage a bid from an overseas player.
Never liked the look of BON, even before the bad news started coming out... and the LFLs look appalling this time; I don't know how they can state a second time expectations are unchanged after a repeat bad performance.
I have to wonder how companies can keep on and on blaming the weather... because, certainly where I live, the weather is pretty appalling a lot of the time :-/
The Bonmarche figure which looks particularly alarming is the decline in website sales. The demographics of their customers may make this area less exciting than in some other retailers but an actual decline looks decidedly ominous.