Small Cap Value Report (29 Apr 2015) - BMK, THT, SVCA, RGD

Good morning! Well no profit warnings for me this morning, so far, so that's a good start. Ramridge posted an interesting comment after yesterday's report, saying that he'd crunched the numbers, and according to an EY report, 2014 was a record year for profit warnings, and the rate is about 15% - so if you have a portfolio of 50 shares (roughly what I have) then you should expect 7-8 profit warnings per year.
If you invest more in small caps, then the profit warning rate will probably be higher, because smaller companies usually have less earnings visibility, and can be heavily dependent on a few contracts, customers, staff, etc (e.g. Thorntons (LON:THT) this morning saying that their fall in FMCG sales is down to one customer).
This got me thinking about the margin of safety. With markets now fully, or over-priced for many, maybe most, small caps, I am increasingly firming up my view that it's dangerous to pay such high prices for stocks, because you then have no margin of safety if/when something goes wrong.
Also, if 15% of your stocks are going to warn on profit, then you have to be sure that the other 85% have enough upside potential in them to more than make up the shortfall. So if you're paying toppy prices for fashionable stocks with strong momentum, where is your upside going to come from? More momentum? So what happens when momentum eventually breaks? I think it could get very messy when eventually buying the dips stops working.
With us only days away from the start of "Sell in May and go away", made worse by General Election uncertainty this year, I'm thinking about putting a self-imposed ban on opening any new long positions, and possibly trimming back a little on existing long positions, and maybe opening or increasing a few of shorts on over-valued stocks.
What do readers think? Do you follow the (statistically proven) sell in May approach? Comments in the comments, below.
Benchmark Holdings (LON:BMK)
Share price: 82p (down 26% today)
No. shares: 219.3m
Market Cap: £179.8m
Profit warning - if the share price drops sharply on a trading update, I rename it here as a profit warning, for clarity. Shares in this fish medicines group have dropped sharply this morning, although they've bounced somewhat from the initial spike down to 71p in early trading this morning. Bad luck to anyone holding this share - a lot of my friends are in this one unfortunately.
I reviewed the 2014 results here on 27 Jan 2015, for anyone interested, and concluded that it was too complicated and uncertain a situation to be able to value the share with any degree of certainty. Hence it didn't interest me.
The key part of today's statement says;
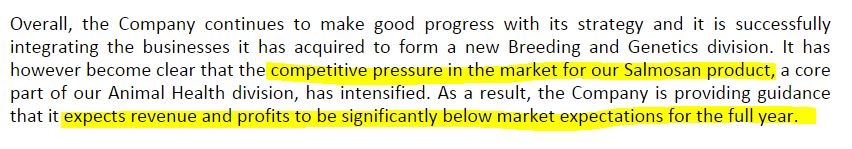
Looking back at 2014 results, the other divisions were all loss-making, so if your cash cow is withering away, then there's a problem.
Outlook - the Directorspeak sounds a bit more positive;
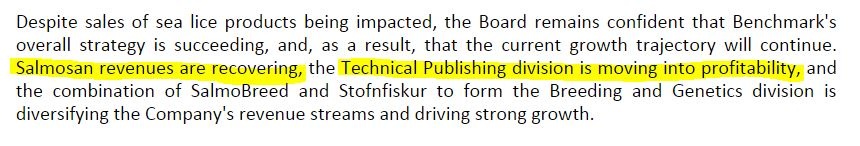
My opinion - I remain of the view that it looks way too complicated for me, and would need a lot of detailed research to understand all the moving parts, and then try to estimate what their prospects are. That's far beyond my pay grade - I usually like simple, easy to understand, profitable companies, on a reasonable PER, so I'll pass on this one.
Thorntons (LON:THT)
Share price: 80p
No. shares: 68.9m
Market Cap: £55.1m
Trading update - as is usual when reading updates from this chocolate company, I'm wondering "is this another profit warning, or not?" as I read it. Today's update came close, but I think on balance is not a profit warning - because it gives no comment on trading vs expectations. So that usually means a company is near enough to expectations.
Although it is sufficiently downbeat for me to wonder whether this is a deferred profit warning, if Q4 doesn't perform well (it's a 28 Jun 2015 year end).
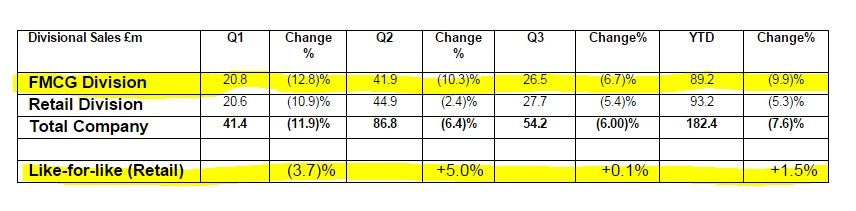
The company provides a useful table, which I have highlighted for the two key rows;
(please also note the recent reduction in highlighter wobbliness. This has been achieved by adjusting my mouse to move a lot more slowly!)
As you can see, the problematic FMCG division saw sales down 6.7% in Q3, but is showing an improving trend, from heavier falls in Q1 (-12.8%) and Q2 (-10.3%). Interestingly, the narrative says that the Q3 fall is entirely down to reduced orders from just one customer.
Outlook - re-reading this, it does sound like a deferred profit warning to me, so I'm expecting them to miss the full year forecasts;
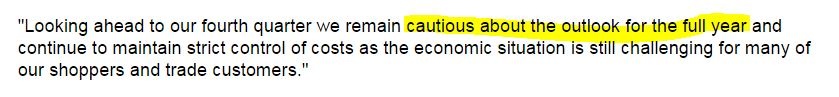
My opinion - this company is really only marginally profitable - forecast for this year is £210.3m turnover, and £4.4m net profit, and it sounds like they might not even manage that.
The balance sheet is weak, and the strategy of diversifying into FMCG doesn't seem to be working - not surprisingly, those pesky supermarkets are squeezing out the profits - that's what they do! More so now, than ever, as their own profits have collapsed.
There are no divis, and it has too much bank debt, plus a pension deficit.
I can't see any appeal to these shares at all, unless you think some kind of new turnaround strategy might emerge? I'd be surprised if this company still exists in 5-10 years' time - just my opinion, as always please DYOR.
Servoca (LON:SVCA)
Share price: 24p (up 14% today)
No. shares: 125.3m
Market Cap: £30.1m
Trading update - another good update from this staffing company;
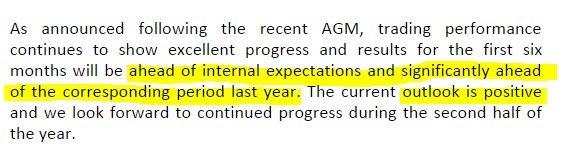
Checking back to interims to 31 Mar 2014, they weren't great, with a profit before tax of only £410k (before £73k amortisation, and share based payments), £337k after. So I would very much hope that a £30.1m market cap company would be significantly ahead of those figures at half time this year!
The full year last year was much better, with £1,703k profit before tax & amortisation/share based payments, so it seems a heavily H2 weighted year, 24%:76% last year, so a very heavy seasonal weighting to H2.
Therefore it seems to me that shareholders shouldn't get too carried away with today's statement, since it's effectively saying that they are a long way ahead of a small number in H1 of last year.
There is no comment about full year expectations, others than the generic "continued progress", so that suggests to me that broker forecasts are probably best left alone. That puts it on a PER of 15 times this year's forecasts - seems pricey for a small staffing company.
I'm not sure why you would buy this on 15 times, if you can buy Staffline (LON:STAF) on about 11 times revised forecasts? So I suppose that buyers/holders must presumably expect earnings to rise a lot more in future.
Real Good Food (LON:RGD)
Share price: 41p (up 28% today)
No. shares: 69.6m
Market Cap: £28.5m
Major disposal - this food business has announced the disposal of its Napier Brown subsidiary, for £34m cash + working capital. This is a highly material deal, and seems to fix the group's wobbly finances - eliminating net debt.
The company announced on 1 Apr 2015 that Napier Brown was up for sale, together with a profit warning. Since NB was 60% of group turnover, the big question is what will be left behind after it's gone, and will it be any good? Will the buyer be taking some or all of the pension deficit with it?
Ah, I've just found the answers - Part 4 of today's document gives pro forma accounts excluding Napier Brown, which is very helpful. The pro forma balance sheet looks pretty good actually, with a healthy current ratio of 1.89, and £5.0m debt which will no doubt be repaid from the £28.1m pro forma net cash.
So it will be debt free, but the £4.7m pension fund deficit remains.
As regards profitability, the pro forma company made an operating profit of only £93k for the 6 months to 30 Sep 2014, but made £2.7m profit for the year to 31 Mar 2014. Presumably there could be cost savings by reducing the central overhead too.
Anyway, at least shareholders won't now have to worry about this company going bust, nor dilution from a fundraising.
My opinion - overall the pro forma figures look quite reasonable actually, much to my surprise! So I am taking this share off my Bargepole List, since it has now fixed its wobbly balance sheet, and is something I would no consider investable.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Servoca (LON:SVCA) has been on my watchlist for a while, its looking quite good value now its fallen back. I did see Paul's comment about why buy and not Staffline (LON:STAF), so I did a comparison and now Servoca (LON:SVCA) looks better value to me: http://www.stockopedia.com/compare/?tickers=LON:SVCA,%20LON:STAF,%20LON:EMR
I also added EMR as similar size to SVCA. Maybe the minimum wage rise will affect Staffline (LON:STAF).
Regarding Margin of Safety, the notes by Robert Redfield on Seth Klarman's original book are, in my opinion, a must-read for all investors, http://rbcpa.com/Notes_To_Margin_of_Safety.pdf
Thanks Patxi - the notes were an interesting read. I must track down and read the Seth Klarman book.
Cheers
Geoff
Given the combination of the 'May flight to the seas' & the general election with forecast Dire results, I have certainly been unloading, after all the gains have been v good & I only have a few with wide spreads. Left holding solid stocks that will rebound and meanwhile hopefully provide the same Divi. Still fully invested in USA & looking to part sell whilst fx rates are very favourable. Shall wait & have a breather until some of the Global events calm down; it will only require one to erupt for all balls to roll down hill.
Bookies today are predicting Ed Milliband Prime Minister (4/6) forming a Labour minority government (7/4). Bookies have a history of being better at predicting general election results than opinion polls.
I have a sudden urge to run for the hills!
OK. Time to trim my portfolio to absolute 'must keep' only.
Ram - a Labour government would need to come to some deal with the SNP, so why aren't index linked bonds rising sharply?
This was in the Benchmark Holdings (LON:BMK) Outlook statement on January 27:
"Your Board is pleased that the Company is successfully executing the growth strategy set out at the time of the IPO and is optimistic about the opportunities ahead. We are enthusiastic about the continued development of the new product pipeline and progress with corporate acquisitions where the Company is evaluating a number of targets. We have been successful in diversifying our revenues away from Salmosan and this, together with the relative resilience that the product has shown to the introduction of generics, puts us in a solid position. The integration of Stofnfiskur and Salmobreed is progressing well with early indications of synergies and growth opportunities materialising as expected."
This is in today's results statement, results to March 31:
"Overall, the Company continues to make good progress with its strategy and it is successfully integrating the businesses it has acquired to form a new Breeding and Genetics division. It has however become clear that the competitive pressure in the market for our Salmosan product, a core part of our Animal Health division, has intensified. As a result, the Company is providing guidance that it expects revenue and profits to be significantly below market expectations for the full year. "
So it all went suddenly wrong between January 27 and March 31 and the "solid position" deteriorated to become "revenue and profits to be significantly below market expectations for the full year. "?
That makes it much worse, imo, since it raises questions about whether the CEO and the BOD know what's really going on in the company.
All IMHO, DYOR.
My impression on BMK is that the generic competition did not start as early as they expected and with the mergers going through management has very much taken its eye of the ball with regards to generics which has now required a bigger response , I can only assume this is now going to not only effect volume of sales but also the margin thereof so they need to get the pipeline moving forward quickly which unfortunately they appear to have failed to do upto this point. Hopefully this is a wake up call for the management and they will learn from the errors made here, I am will be holding for now as I can see the long term appeal of the company especially following the recent deals but management need to up their game.
Hi Paul
I am still forming my opinions but the statistic that most gains are made on relatively few days and that if one is not in the market on those days (ie you are trying to time entry exit points) then your overall returns will suffer but I think I am tending towards being a different type of investor to yourself? That said I do like the idea of keeping a substantial amount of cash (I think Klarman often has 30% in cash) ready to deploy when the next 87, 2008 etc comes along. That said I have been keeping cash in case my business has liquidity problems, which is beginning to look less and less likely so I am looking to deploy some fresh cash over the coming months.
Quick example. A chap I was "advising" retired in May 87 and received his pension cash lump sum that month but wanted to defer his investment in Unit Trusts and Insurance bonds because of the sell in May etc. thing. He could not be persuaded that he could not time the market. So he came back to us and invested his money on roughly 10th October 1987. After 19th October we managed to persuade him to hold fire and not sell but it was hard going.
So if one beats what ever bench marking you are measuring against maybe it doesn't matter. At the moment I am measuring against making a bit of money and increasing my knowledge benchmark.
Thanks as ever for a great column.
The "most gains on a few days" thing is a bit of a fallacy: it's sort of true, but it's equally true that most losses are made on a few days, so being out is sort of neutral: you miss both up and down outliers.
Couldn't disagree more but will have dig out the research from some pretty eminent people and come back to you in a week or so as I am away from tomorrow (yes through the election) and I have not adjusted my holding at all as, to use Ramridge phrase, my holdings are only ever must keep holdings until the fundamentals change and the UK election is not a fundamental.! Have a good bank holiday.
I checked the valuation of BMK with Vector Vest from a year ago at about 80p to yesterdays close at just 23p, clearly an overvalued stock. Having said that the estimated earnings and profits over the next 2 years with Stockopedia look very positive. They have 46 products to market. according to Reuters, so it appears it is only one of these that is giving a problem right now. One for the watchlist. There is plenty of fish in the sea to choose from.
I think profit warnings will be the least of our worries if its an 'anyone except the Tories' coalition.
I've had a look at Labours manifesto and it's terrifying.
I've had 2 companies warn in two days... BMK and IND... I going to stop looking and drink more Sake!
Benchmark Holdings (LON:BMK) is a story stock, another one sold on a nice line of patter to private investors.
It's what we aren't told that always matters more than what we are told.
Was the threat of the development of generic alternatives ever mentioned in any of those "presentations to investors"?
It's better to give this kind of stock a very wide berth.
Wait until the business is grown up before investing.
Jane, to be fair to Benchmark and its advisers, the generic threat to Salmosan has been up-front in all presentations, and in the fundraising literature. Also if you look in the prelim results from January, it's mentioned in the outlook statement. In those results they indicated that Salmosan sales were stronger than expected due to the generics not penetrating the market as much as they'd though likely, but now it seems they have.
For me, the issue is more the delay to the replacement treatments, and I'm not a believer in HypoCat.
The Thorntons (LON:THT) problems are self-inflicted, imo. Their USP was in having their own chain of shops. This is being run down in favour of competing head-to-head with dozens of other brands, perhaps equally good, on the bought-for shelf space of rapacious supermarkets, where the notion of « a premium price for a superior quality » is almost certain to be submerged in a sea of competing price reductions and special offers. Why would Thorntons do that, turning their backs on what makes them unique? Surely, there must be the opportunity in UK for a chain of boutique, higher-range chocolate shops, offering « more » (chocolate club, rewards scheme, chocolate tastings, pavement hot chocolate cafés, etc, etc)? There is in other countries, here's one example from France (sorry, it's in French):
http://www.chocolat-deneuville.com/son-histoire.html
This chain has over 150 shops, many or most franchised, and seems to be successful and expanding.
For THT to deliberately jettison perhaps the only thing that makes them commercially unique seems mad. That « the sales decline in UK Commercial is now solely due to reduced levels of orders from one customer which have continued into the second half of the year » is hardly surprising, the supermarkets play hardball and THT is learning that. This demonstrates, imo, that THT are giving over control of their business to rapacious sharks, rather than having a strategy they can control themselves, one of building up an alternative and unique business.
I find it rather sad.
Agree - Thorntons (LON:THT) is an example of how NOT to run a chocolate factory
http://brucepackard.com/how-not-to-run-a-chocolate-factory/
The other problem with Thorntons (LON:THT) is that the chocolate tastes horrid! But even if it didn't the brand I think is very fusty and dated.
"What do readers think? Do you follow the (statistically proven) sell in May approach?" -
I am also having trouble finding value. I am probably not going to sell anything in May, but I prefer to sit on my hands and wait for things to come back into range. I have been following this guy - he seems to write a lot of sense.
http://humblestudentofthemarkets.blogspot.de/2015/04/new-highs-last-hurrah.html
And of course, Mental Crumble.
http://mentalcrumble.com/blog/a-potent-and-combustible-combination142015
I have not followed it but I have cashed some shares as I think the market could fall next week due to the election result, so locked in some profits on housebuilders and sold a few that I've lost interest in or have not gone up for a while.
Paul,
If I was you I'd delay making any investment decisions while living on a £1 a day. I'd be very surprised if it wasn't clouding your mood or outlook generally. Wait until you have got at least a couple of pies inside you!
Sounding very pessimistic today, and wondering if the diet is having any effect.
Lee