Small Cap Value Report (4 Jan 2017) - NXT, BM, STAF, ACRL, SPSY, CAMB

Good morning!
Thanks for all the positive feedback on yesterday's article, I'm glad people found it interesting.
Graham's having a day off today, so just one report. I intend covering the following;
Next & B&M trading updates - yes, I know they're large caps, but the idea is to get a feel for how retailer bellweathers have done over Xmas. This has read-across to smaller retailer shares - note how M&S, Debenhams & French Connection are all down c.5% this morning, in sympathy with Next's lacklustre Xmas trading.
Staffline (LON:STAF) - in line trading update
Accrol Group (LON:ACRL) - interims to 31 Oct 2016
Spectra Systems (LON:SPSY) - positive trading update
Cambria Automobiles (LON:CAMB) - AGM trading update, in line with expectations.
Large cap retailers
.
John Lewis Partnership
EDIT - Sorry, I dropped a massive clanger here, and accidentally did a write-up on last year's results, thinking they were this year's! Huge apologies for that. I would blame having a cold, but apparently I did the same mistake last year. Rather embarrassing, sorry.
Anyway, there's no point in having an incorrect section in here, so I've deleted it.
Next (LON:NXT)
Basically, it's not as good as expected, so the shares are down, and have pulled down other retailers too. The prior year comparatives were soft, so growth was expected, but failed to materialise.
Special divis make this a nice income stock, and it's certainly coming back into buying range for me. Although I wonder whether Next may struggle to maintain its sector-leading net profit margin?
It's remarkable to find such a high quality business on a PER of below 10, but where's the growth going to come from? It seems that Next is likely to only, at best, stand still in terms of future profitability, maybe? Hence the low rating.
The market is really only interested in online retailers at the moment, or growing, smaller retailers. Although I wonder if the pricing gap between growth & value retailers may now be getting too wide?
B&M
Very strong UK LFL sales growth of 7.2%, from this pound shop chain. Although 1.1% of that was an extra day's sales, so LFL was really 6.1%, still outstandingly good.
Staffline (LON:STAF)
Share price: 856p (up 1.3% today)
No. shares: 27.7m
Market cap: £237.1m
(at the time of writing, I hold a long position in this share)
Trading update - I was worried that a profit warning might be on the way here, due to seemingly unrelenting selling pressure in the market, and a lowly valuation.
However, I need not have worried, as the company has continued its excellent multi-year track record;
The Board is pleased to report that the Group expects to deliver full year results in line with market expectations.
Profit is split roughly evenly between the 2 divisions, both of which seem to be trading well;
Demand in the Staffing business has remained strong through the second half and the division has once again achieved excellent growth in the number of OnSites this year.
PeoplePlus, the Employability, Skills and Justice Division, has also made good progress, becoming the top performer in Work Programme contracts as well as benefiting from its focus on improved margins.
I recently interviewed the CEO of Staffline, Andy Hogarth. He sounded a little downbeat, but that's probably because he had a heavy cold.
There are some short term issues over the timing of Govt contract renewals, which is reflected in cautious broker forecasts.
My opinion - the company has an outstanding track record of identifying new business areas, and executing them well. For that reason I'm happy to look through any short term uncertainty.
The valuation looks very modest to me. I think worries about its E.European workforce disappearing are misplaced.
Results meeting for private investors - this was a great success last results time, so the company is once again putting on a presentation for private investors on results day. Details are below;
A presentation for private and retail investors will also be held on Wednesday 25 January 2017, starting at 12.00pm at the offices of Buchanan, 107 Cheapside, EC2V 6DN.
Admittance is strictly limited to those who register their attendance in advance of the event. To register for the event, please contact Buchanan on 020 7466 5000 or staffline@buchanan.uk.com.
I encourage more companies to put on presentations for private investors. It's extremely helpful in giving us access to good companies & management. Last year there was a light buffet, of mainly sandwiches & wraps, plus a small selection of soft drinks, and some cakes/cholcolates.
Accrol Group (LON:ACRL)
Share price: 126p (down 0.4% today)
No. shares: 93.0m
Market cap: £117.2m
Interim results, 6 months to 31 Oct 2016 - this is a low-priced loo roll (and similar tissue products) manufacturer, based in the UK, which floated on AIM in Jun 2016. I reviewed its admission document in my report here on 8 Nov 2016. My conclusion then was that there were too many risks for this share to interest me.
These interim results don't look particularly great to me.
Revenue up 8.8% to £63.9m for the 6 months
Adjusted EBITDA up only 1.5% to £7.1m
So clearly margins are already under pressure. However, what worries me is that adverse forex movements have only been deferred, through hedging;
Our current hedging position in both US$ and Euro together with agreed paper prices until April 2017, lead us to remain confident in the outlook for the full year.
So the current year looks fine, but what happens after that?
If exchange rates continue at current levels then the soft tissue industry, along with many other sectors, will need to increase prices to recover the rise in raw material costs.
That could prove tricky, as trying to raise prices for customers like Lidl & other discounters is probably likely to be hard work. It may end up with Accrol suffering margin compression, maybe?
Valuation - this share is rated at 11 times forecast earnings for this year. Given that it might struggle to meet, let alone exceed that profit next year, I can't see much attraction here for investors.
Balance sheet - NAV is £54.5m, which drops to NTAV of £23.8m, once we get rid of intangibles.
There is some debt, but it doesn't look excessive at £19.9m.
Dividends - a maiden interim divi of 2p has been announced. The company "remains committed" to a 4p final divi.
I'm a bit sceptical whether that 6% yield on the 100p IPO price is sustainable, if something were to go wrong with trading. It's a cash outlay of around £5.5m p.a., and that looks a tall order to me.
So dividend seekers might want to look more closely at whether that level of payout was a sweetener to get the IPO away, or whether it can really be maintained long term? If future divis are cut, for whatever reason, then it would be accompanied with a big drop in share price - as we saw with another high yielding Zeus float, Entu (UK) (LON:ENTU) .
My opinion - this looks a risky share to me. Movements in forex & paper prices could easily trigger a profit warning.
The IPO was a mechanism for large shareholders to sell. So personally I wouldn't want to be on the other side of that trade. It's not for me.
Spectra Systems (LON:SPSY)
Share price: 34.5p (up 35.3% today)
No. shares: 45.3m
Market cap: £15.6m
Trading update - this is one of the oddest companies on AIM (and that's saying something!). Based in the USA, it performs erratically in terms of revenues & profits, with no clear trend either way.
Be that as it may, 2016 seems to have been a good year;
...today announces that it expects its profits for the year ended 31 December 2016 to significantly exceed market expectations. Revenue is also expected to be ahead of market expectations.
Looking back at the interims, they're unremarkable, with a $430k loss on turnover of $4.8m.
Note that the balance sheet with this company is cash-rich. It's been sitting on a big cash pile since 2011, which strikes me as a comfort blanket for management. Therefore I would apply quite a discount to the cash, when valuing the company, as it appears they're not likely to do anything useful with it.
My opinion - for me, this share is too illiquid, and long-term performance has been lamentable really. Perhaps it's just a lifestyle business for management & staff?
That said, if the improvement in performance in 2016 is sustainable, then the shares might be worth a fresh look?
Cambria Automobiles (LON:CAMB)
Share price: 61p (up 0.8% today)
No. shares: 100.0m
Market cap: £61.0m
AGM trading update - as mentioned in yesterday's report, my view is that the market has oversold car dealership shares. So it's pleasing to read a report from Cambria that seems supportive of my view. This is not a share I currently hold, but probably should buy some - as I like the company, management, and valuation.
The company has a 31 August year end, so today's update covers the 3 months to 30 Nov 2016;
The Group has maintained its momentum from the strong results delivered in the last financial year and its trading performance in the first three months of the current financial year has been ahead of the corresponding period in 2015/16, both on a total and like-for-like basis.
What is remarkable, is that new car sales were down heavily (down 9.4% on a LFL basis) in the 3 months. However, this has not impacted profits because margins improved. So clearly the manufacturers are supporting dealers. Also, crucially new car sales are not actually the main profit driver at car dealerships any more.
After a strong September trading period, the Group did see some pressure on new car margins in October and on new car volumes in November. New vehicle unit sales for the first quarter were down 0.7% (like-for-like down 9.4%), but gross profit per retail unit improved in the Group's like-for-like businesses.
Used vehicle sales are key to profits, and are doing well;
Used vehicle sales continued to perform well, with unit sales 3.6% (like-for-like 2.5%) ahead of the same period in the prior year and gross profit per unit continuing to increase. This performance has again enhanced the profit from the used car segment of the business.
The other key profit generator is aftersales (servicing, repairs & warranty work, I suppose), which is also doing alright;
The Group's aftersales operations increased revenue by 13.1% (like-for-like up 2.9%), with profitability up by 6% year on year (like-for-like down 1.5%, impacted partly by a fire in October at the Welwyn Garden City Jaguar and Aston Martin workshop).
Mind you, if new car sales drop for a sustained period, then that's bound to have a gradual impact on aftersales.
Outlook comments - a bit cautious, but crucially still in line with expectations for the full year;
The Board continues to believe that there may be some pressure on new car volumes and margins in 2017 as a result of the uncertainty in the economy and the foreign exchange volatility witnessed over the past few months.
However, the Board also believes that the Group's robust balance sheet and proven management team ensure it remains well placed to take advantage of any opportunities that may arise.
The Group's trading performance in the first quarter means that it is trading in line with market expectations for the full year.
Valuation - as with other smaller car dealership chains, it looks great value to me;
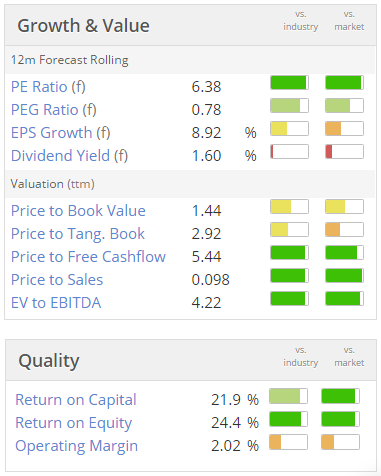
My opinion - the car market has changed radically, with new cars far more affordable than they were historically. Also, most private buyers now use personal leases, which are very affordable indeed. So I reckon the higher levels of new car sales we've seen in recent years could hold up better than some expect.
The dealerships make most of their profit from aftersales and used car sales, so seem reasonably well insulated.
Of course things could get worse, so if you're very negative on the economy in general, then it's probably best to avoid this sector. However, if like me, you're a bit cautious, but reckon things will probably be OK, then the low valuations in this sector right now could be presenting a decent entry price.
All done! See you in the morning.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
I came across the news that The Limited in the US is closing all its 250 physical stores:
https://www.washingtonpost.com/news/business/wp/2017/01/06/the-limited-is-closing-all-of-its-250-stores/?hpid=hp_hp-more-top-stories_limited-725pm%3Ahomepage%2Fstory&utm_term=.6b7e3eb168b3
The store closures there in women's apparel seem to be coming thick and fast.
The UK is surely likely to follow the same path.
Perhaps the tipping point is already here.
So does NEXT actually have a future on the high street and, if not, is it able to compete online with operators such as BooHoo or Light in the Box?
Does NEXT even have a future or is it the next Marks & Spencer?
Will Primark be the next to be threatened?
RE: Staf CEO seeming downbeat.
That’s strange really didn’t think he seemed all that downbeat and actually topped up based on that interview. Strange thing perception but I suppose as the interviewer you're in a much better place to gauge his mood. Thanks for the report and the interview BTW.
At this point, I prefer Marks and Spencer (LON:MKS) to Next (LON:NXT), although I do not aniticpate their results being good. I have been impressed by the statements from the new CEO who sounds like a genuine technical, handson retailer who has an understanding of Marks UPS. May not work in turning it around - nothing else has - but there's a lot of gain if he can manage it and their most direct competitors (BHS, Next) aren't as tough as they were a few years ago.
I haven't bought anything in Next for a few years. They seem to expect a 'premium(ish)' price for goods that don't have the quality. Last year I bought some stuff from Marks for the first time in quite a few years; the prices were at about the right level for the quality and the stores felt OK and were quite busy.
Apart from quality, I have a concern that Next have been underinvesting in their business generally; they seemed very focused on EPS and shareholder image rather than their customers. More needed to be spent on their Directory and online offer which is not as easy to navigate as it should be. Their shops are overcrowded and a bit dowdy (at least the ones I have been in); overcrowded with clothes, but not people any more. The Directory credit business was high return, but is gradually reducing - maybe because they were taking too high a return? Could be a cash cow with a long expiry date but it had attracted a premium rating because of its steady 'growth' which was always supplemented by their share buybacks. There will be a good price for the cash cow side (although they will probably be tempted to start spending bigger, but not necessarily cleverer, if they keep losing market share) but I'm finding it hard to work out what I think it is because margins and profitability could fall heavily as turnover drops.
Hi Paul
You wrote in your post 13/08/15 that you were long Telecom Plus, I was researching this share when I came across the post and stopped dead when I found TEP mentioned with Camkids and Globo. As TEP is now a NAPS suggestion perhaps you could give a view as to your feelings regarding a "new leaf having been turned". Although I appreciate that if I dig further there could be many other reasons but I expect to see a standstill in profitability when turnover stalls, not an 11% increase as shown in the last update.
Thanks
Ken
Hi Ken,
I only held Telecom Plus (LON:TEP) briefly, a while back.
I deepened my research, and just decided that I wasn't so keen on it after all, so dumped them.
Having a quick look at its StockReport today, it looks very expensive to me. Earnings forecasts have come down in the last 12 months, but the fwd PER is still 20.7 times this year's forecast EPS. That seems very high to me.
It's not one that I plan on revisiting.
Regards, Paul.
Hi Paul.
In the interests of balance, possibly worth noting that Telecom Plus (LON:TEP) has the highest stock rank (of 84) in the Telecoms Service sector peer group of about 20 companies or so. Decent Q and M scores although I accept that the V score in the low 40's suggests it is looking a bit expensive.
I think Robbie Burns/the Naked Trader is a big fan (possibly due to the bias of being a sales agent for them in the past) and topped up his holding as recently as November 2016. Recent trading update was quite upbeat (full year profits expected to be at the top end of forecast) and pays a decent running dividend (although dividend cover is a bit on the low side). They're also due to pick up a windfall of c.£70m (vs book value of £7m) from the sale of their 20% minority stake in Opus Energy which is being acquired by Drax Q1 2017
Best,
Gus.
Thanks Paul/Gus for info
What impact do the 'we buy any car' companies have? Makes it easier and therefore more people upgrading more regularly?
None really. People sell cars because they want a new/newer/different one not because it's any easier elsewhere. Dealers make changing your car much easier. Drive in hand keys over get new one. People will rather do this than make a couple of hundred more but potentially being motorless for a few days. Plus you never hardly get what they advertise as they'll say an alloy is scuffed or the tyres are too worn etc. What it has done is makes some people more aware of what they 'could' get for their car in pet ex and use it to negotiate a slightly better deal but as said above any savvy dealer will use that rhetoric to put people off.
NXT
"I'd echo comments that quality of Next ladies wear has dropped - I have an Outlet store near me and the quality of their range at the mo compared to, say, only two years ago"
I wonder if events at Next have been due to the departure of Christos Angelides during 2014. Mr Angelides was group product director for c15 years and was described by some as "the power behind the throne"
https://www.theguardian.com/business/nils-pratley-...
Ultimately it is people who design clothes and decide what to stock, and I wonder if Next's replacement is not as talented as Mr Angelides.
Yes I have read this before about Christos Angelides and there maybe something in that but he did not last long in his next company.
So you are buying £FCUK?
It will be interesting to see what impact he does have there but I understand Stephen Marks is not easy to work with.
Yes, he did not last long at Abercrombie. He was only there for 18 months. Could he have made a complete hash of things in that time? Especially as it would have taken a few months before any of his own work/ideas filtered through into the stores. I don;t know. Perhaps his face simply did not fit.
On FCCN -- ha ha :-) I was a FCCN shareholder for five years until I gave in last year. I met Mr Angelides at the AGM and while he admitted he was working the occasional afternoon with FCCN's designers, I did not get the impression he was looking for a full-time exec job with Mr Marks.
And even if he was looking for a full-time exec role, I doubt FCCN could afford him. I have been told Mr Angelides is doing similar 'consultancy' work for other, larger retailers, which I guess is where he could resurface.
I see, thanks for the information. Yes seems he was ousted by the new president, he did not do too badly out of it. I also sold my £FCUK last year, just too uncertain for me and retail is not a sector I want too much exposure to at the moment.
Staffline (LON:STAF)
Thanks to all of you that have pointed out to me the shortcomings of my approach to the EPS figures.
I will review my process and make improvements in this area.
I'd echo comments that quality of Next ladies wear has dropped - I have an Outlet store near me and the quality of their range at the mo compared to, say, only two years ago is absolutely appalling, the quality/range of the main stores is less downhill, although I notice that the sales have lasted a lot longer this year than last year; I bought a few things last year but not many.
The cars residual value (RV) is on the balance sheet of the finance company, normally owned by the manufacturer or as a JV with a bank, the dealer simply asess for anomalies in fair wear & tear terms and the finance company (up to balloon) holds the depreciation risk , or the customer (over the balloon)
Dealers love PCP
I bought a second-hand car recently from one of these big, high-volume second-hand car dealers. They had a huge stock of second-hand BMW, Mercedes, VW & Audi all around 2-4 years old. Dozens of sales staff, constantly busy, very competitive pricing. The previous owner of the car I bought was a leasing company, I suspect most or all of their stock were ex-lease. I wonder, if the leasing trend continues, whether the traditional dealerships will find their supply of second-hand cars disappearing.
I'm keeping an eye on MOTR and will buy if they begin to show some momentum.
Re: Cambria Automobiles (LON:CAMB), read an article in FT yesterday where Mike Hawes, CEO of SMMT (Society of Motor Manufacturers and Traders), predicts a 5% decline in new car sales in 2017 due to the UK market having reached peak demand. Food for thought.
Re: Cambria Automobiles (LON:CAMB), read an article in FT yesterday where Mike Hawes, CEO of SMMT (Society of Motor Manufacturers and Traders), predicts a 5% decline in new car sales in 2017 due to the UK market having reached peak demand. Food for thought.
And of course, in a low margin business even a small decrease in revenue has a magnified effect on profits. I hear what Paul is saying, and if I had to hold a car dealer it would be Cambria Automobiles (LON:CAMB) because I think it is well managed. However, even if it outperforms in a falling market there is only one direction the share price is heading.
There was an interesting interview on R4 Today this morning. It seems the manufacturers have been forcing cars for lease onto the dealers for pre-registering in order to push leases in the presence of low interest finance. It seems they are now heavily rowing back on this, particularly with the prospect of interest rate increases. The dealer interviewed reckoned that as much as 20% of the SMMT sales numbers released today are for leases and he described it as a "bubble".
Add into the mix the high level of household indebtedness reported yesterday and the likelihood of Brexit fallout and I have no idea why anyone would want to be holding car dealerships at this stage. After all, they are just another retailer and with very much lower margins than most.
All the best, Si
The aely morning R4 Today programme covered car sales this morning (Thursday), saying that most new car sales were lease-purchase with a big (and unaffordable) "balloon payment" after 3 years if you wanted to own the car. Apparently most people roll over into an upgrade at that point as the most affordable option.
That feels unsustainable to me, and parhaps could lead to claims of mis-selling. R4 Today also said that consumer credit is at record levels, which will be a problem unless it can be inflated away.
How do car dealerships carry the asset of the leased car in their accounts? Does it get written down if the second-hand value after 3 years is less than the balloon payment?
I reckon over 90% of new car sales are by lease if not more. Pretty astounding. PPI payments have meant lots more people have had much more disposable income. Once they've stopped paying it then you'll see a sharp drop in sales IMHO. I'm generalising but a lot of people who get PPI refunds are not really people you'd want taking out credit on high value items. It would never be worth less as there are penalties in place to protect this. I.e. damage, excess mileage and service penalties. Whether they can pay the difference is something the credit company has to worry about. The finance company is taking the risk so not sure what goes on companies accounts? The difference between the GFMV and what the dealers will give you for your car at return is the deposit for the next one and so the cycle continues. Leasing is simply financing the depreciation of the motor. A lot of people won't see it as that kind of transaction though. I'm of then same opinion as all the dealers collude and think that mis-selling will be an issue.
Inflation only works if there is wage inflation.
"Inflation only works if there is wage inflation."
Agreed. There seems to be some sign of wage inflation starting in the USA, which is one reason why US interest rates are set to rise.
Profuse apologies for me dropping a massive clanger on using the wrong year's figures for John Lewis. I followed a google link, but didn't double-check the dates unfortunately.
Anyway, I've removed that section, as it doesn't make any sense.
Thanks for those who pointed out my stupid cock up.
Regards, Paul.
Sales might be up at within John Lewis Partnership however profits are estimated to be quite a bit lower yr on yr. Expectations for profit before Partnership Bonus, tax and exceptionals for the year ending 30 January 2016 remains unchanged at between £270m and £320m versus £342.7m last year. Indicates they're being squeezed and that the market is tough for all retailers even the better ones. Think Next (LON:NXT) and others with large portfolio of retail outlets will have a tough year.
Just bear in mind Next (LON:NXT) usually under promise and over deliver. They are still a solid bellwether company with little debt and pretty decent margins. it's realistic to put out an uncertain outlook statement as we're about to embark on triggering brexit
Two comments on Retail and online retailers:
First, from a professional Marketing point of view we should expect BOTH online and high street /retail park shopping (with fusion executions between the two). Some people will like one and some the other. However it looks likely that the (still small) online segment - perhaps 13% by value now will grow at the expense : my view is equilibrium will be closer to 40:60 ie online can triple whilst offline reduces by 1/3. (hence long on BOOHOO albeit much reduced) That still leaves a big High St/Retail park business!!! Interesting stores in good locations will still do well (I also hold DEBS as i think they are navigating a tricky time quite well with growing internet and non-clothes sales and good locations to sell perfume and decorative lamps!). With BHS gone and M&S shaky, there is still a role for Debs with its in house fashion brands. I'd love to see it take on French Connection (FCCN), rebrand the stores and sell the dresses across its estate.
Second, for an under valued stock look at N Brown (BWNG), another holding. This is transforming itself into an online/digital player and is 4 years in. Too much debt but at low PE levels etc when you think 70% of sales are now online. JD Williams is coming back and Simply Be whilst no BooHoo has found a place and will do well in the US I think.
Retail is far from dead!!
PS writing from Nigeria with a dodgy american laptop so no pound symbol available :)
PS writing from Nigeria with a dodgy american laptop so no pound symbol available :)
Techy aside:
To get the pound sign try holding down the Alt key and typing 0163 on the numeric keyboard. Alternatively you could copy and paste one from somewhere else.
A few points why I wouldnt buy NEXT
quality isn't as good as it was.
too many shops that will hurt going foward as sales on the high street decline further.
More importantly, the next generation of shoppers are shunning the dowdy fashions of next. BOO, ASOS are most defo where the young fashion conscious shop.
I expect a further warning on trading in the coming year also.
pye
More importantly, the next generation of shoppers are shunning the dowdy fashions of next. BOO, ASOS are most defo where the young fashion conscious shop.
I'm not sure this is entirely true. I asked my 11 and 15 year old nieces about clothes shopping over Xmas. It seemed to be common knowledge amongst their friend groups that the quality of clothes from Boohoo.Com (LON:BOO) was poor and they preferred the better quality of high street names such as Jack Wills, Hollister and Brandy Melville. I'm not saying they are typical, but it's interesting nonetheless, especially if you hold £BOO like me.
IMHO the "young people only shop on-line" schtick is being overplayed and they seemed to actually enjoy a day out shopping with their friends, having a coffee etc. and so were quite happy to receive cash as a present to fund these trips. If Next (LON:NXT) have not got it right in terms of clothing and presentation to a younger audience, then this seems to be something that is easily fixed. If it gets to a yield of 5% (target price £36) I am going to back the truck up.
All the best, Si
Is it a cold Paul or man-flu? :-) Whichever, get well soon, and thanks for posting.
Those John Lewis figures are for last year, i.e. Christmas 2015!
Those John Lewis figures are for last year, i.e. Christmas 2015!
Paul performed the same trick last year -- looking at John Lewis figures for Xmas 2014 rather than Xmas 2015:
http://www.stockopedia.com/content/small-cap-value...
Tee hee.
I prefer to go online, more choice. saves hassle of going shops.
if something doesn't fit it so easy to give me back as postage is paid for, just drop it to a local drop of point and money is refunded if need be.
My wife has been using the NEXT ( LON:NXT ) catalogue for years for clothes and home furnishings but over the last couple of years she has been less impressed with the quality and cost of the products. She still shops at NEXT stores but now buys a lot of other clothes from different shops. Not sure where the growth is going to come from anymore. Special dividends are fine but you tend to find the share price drops accordingly. As a holder of Boohoo (LON:BOO ) who sadly sold out too soon at least that company is growing and showing no signs of falling back although the share price is now in to overbought territory in my opinion. I have been to my local Debenhams ( LNO:DEB ) in Norwich several times but it always seems a bit haphazard however John Lewis has a superior feel about it and was very busy on my recent visit although I was always able to find a member of staff who knew how to help me . I think they will always price match as well. Disclaimer I own no shares in any of these companies.
Also worth noting that the British Retail Consortium reported shop prices declined by 1.4% in December compared to the previous year (confirming margins are being squeezed?). However, they went up on the previous two months, especially non-food: http://brc.org.uk/news/2017/shop-prices-show-first-signs-of-upward-trend
Not got the figures to hand but when I last looked at Next's financials I went through the exercise of assuming the bricks and mortar business was worth zero and valuing on the basis on the digital business only. It then looked a good valuation for a growing digital business (note this includes some fast growing overseas operations that being digital won't require a big high street roll out) with the high street business thrown in for free and providing cash flow and dividends in the meantime.
Although the lower rate of digital sales growth at Next as compared to John Lewis for example is now giving me pause for thought, coupled with the fact that the Next in Southampton has looked a bit empty the last couple times I've walked past it, I'd be interested in any views as to whether the market is underrating some retailers with a strong digital presence because of they have a high street presence as well, notwithstanding that the high street presence is actually profitable and generating cash.
Personally I find the range in Next (LON:NXT) a bit generic and same same each year for its price, when you can get similar stuff cheaper in H&M or other cheaper retailers such as Primark. Given the other pressure from competing online focused retailers I can understand the fall across these large caps.
As an avid shopper, I do not see either H&M or Primark as Rivals to Next. The quality of clothing is much much better at Next than those two, perhaps Next's rivals are more the Arcadia Group including Burton and Top Man plus Marks and I see Next as better than them. As Paul says the pressure on Next and all High St Retailers is likely coming from the move to online fashion where I suspect the 16-24 market has latched onto for many years and now the 25-40 and maybe above are finally catching up with!
My wife tells me that the quality of clothes at Next has dropped
I have never bought anything from Next other than their #85 perfume for men (for my dad!)
I do buy a lot of clothes and have a stupid number of shirts - I recently moved and counted over 45 whilst I was hanging them all....
I have for the last couple of years bought some fantastic branded clothing from ASOS - always at a big discount of 30-70%. I'm going to have a big sort out again and take some bits and pieces down to my local charity shop and have decided to try and go at least a year without buying any new clothing.
I think ASOS (LON:ASC) will struggle. I estimated that my return rate is probably greater than 50% and I do know someone who 'bought' 10 jackets to try and then returned them all. This seems to be very common and must cost ASOS a fortune! I also believe that online only stores will need showrooms and a shop front so that people can touch and see what they are buying and then order online or in store for delivery the same day or next straight to their homes. Perhaps Debenhams (LON:DEB) will be ok because they have the shops, which they can convert to destinations and move towards larger home departments such as lighting (something which BHS actually did quite well). People will not stop going out and in my opinion many people would say that their main hobby is shopping (I think this is sad). The high street is continuously changing and adapting let's see where this takes us! I would like to see a return of many more independent shops and cafe's instead of the identical chains which we see throughout the UK. Next (LON:NXT) to me has always felt a bit mundane.
Hi Bsharman, I read with interest your comments on shopping, which seem to suggest that perhaps people might drift back to the high street from on-line purchasing, at least with regard to clothes. Hope I understood you correctly. If so, that is exactly how it seems to me, with so many returns perhaps putting some customers off further on-line clothes shopping. However, the figures don't seem to be suggesting that such a trend is occurring so far, with the inconvenience of having to return a lot of items being offset with the inconvenience of traipsing round shopping malls. I also know a lot of people who find the distraction of shopping on-line during their lunch break and other free time irresistible, so maybe that's at the root of the sea-change in shopping habits.
The problem with online is the size and the fit. I prefer to try things on first, buying online I'm not surprised they are high returns, also you can't really see how the clothing looks, often when you get it looks a lot different from the photos. So I rarely do online shopping now for clothes. It is probably different for younger people.
It's a different market for old blokes like us and younger female buyers. The girls are comparing clothes with one another all the time and looking for the next trend so they often have a good idea what they are buying and treat it as a hobby. That being said the way reverse logistics is handled is key for online retail.
For myself I go for the Costco private label Kirkland stuff so no-ones getting very wealthy from my clothes shopping.
Yes, I would agree with you, I rarely buy clothes online unless I have tried them on in a shop first but I also think you are right that we (and probably the great majority of posters) are different in our clothes buying habits to younger people who drive sales at clothes retailers. I normally spend less than £50 per year on clothes and get some good shirts from charity shops. Based on my observations of my son and his wife, I don't think younger people do that! More seriously, I would agree with the idea that there is clearly a place for bricks and mortar clothes shops and eventually equilibrium will be reached between online and traditional shopping. However, my impression is that the rapid rate of transfer to online buying has some way to run yet and when the equilibrium is reached, the likes of Next (excellent company though it is) will be shown to have too many shops. I sold my Next shares a few months ago and sold my Ted Baker shares today as I think I underestimated the impact the move online will have on businesses such as these. I would note that Ted Baker had less than 25% of its sales online in its last results and even though they are growing fast, this does not look good to me. I have, however, held on to my Boohoo shares (thanks Paul).
Hi. Thanks for the reply. I think that many people still want to touch and feel what they are buying and also enjoy browsing. I think that this is true for both clothing but more so for home furniture/décor (IKEA in Southampton always seems to busy) I watched a Mary Portas talk and Q&A at the Oxford Union a while ago (I'd highly recommend this youtube channel)
https://www.youtube.com/watch?v=p_g-Jc0nOrM
I also thought that this extract from an article she wrote for the Telegraph was interesting:
So what does this mean for the future of retail and our High Streets? Well it's quite simple. Be good. Be good at what you do. Be good in the way you do business. Because if you aren't, you ain’t going to survive. Today the customer is truly king. We can shop where we want, when we want whatever time of day we want and pretty much at whatever budget we want.
And the legacy of the Internet has meant we tap into trends faster, demand more choice, but also gain access to how goods are made so we demand higher ethics, behaviour and standards. We know that digital won’t replace the High Street either. People crave social interaction. We are neurologically wired to connect. That's why farmers’ markets are more popular than ever.
I believe we have reached a place where digital plays an everyday important and continuing part of our lives but we now seek more experiences to compensate for our digital overload. Indeed, 38 per cent of the millennial generation would rather spend on an experience or something ‘interesting’ rather than just buying more ‘stuff’. And so the visionary and creative retailers and entrepreneurs of tomorrow are delivering just that. Where the old school have left the High Street, a new breed is driving in. Ones who put their values at the heart of what they do. And then envelop it with a Positive Experience - what I call The PX factor.
Amazon are opening physical stores in the States and perhaps this is a trend which will be adopted in the UK?
I don't think people crave face to face social interaction. I certainly don't. I also don't think people go to farmers markets for it. They go to buy good local produce all in one place that they can't necessarily get from the supermarket.
Hi Paul & thanks for your highly valued SCVR.
Given that Staffline's in line trading update relates to a forecast increase of 548% in EPS for the year to Dec 2016, I have just conducted further research & topped up my holding.
Warranstar
AIUI, Stockopedia's data supplier takes a far sterner view of some of STAF's costs than does STAF's broker. Whereas STAF focuses on underlying numbers, Stockopedia apply a number of costs that STAF back out of their figures.
In particular, as stated in STAF's 2015 results...
..."* Underlying figures are stated before amortisation of acquired intangible assets, acquisition and exceptional re-organisation costs in A4e and the non-cash charge for share based payment costs ("SBPC")"
I don't have an issue with most of the above, but STAF's business model uses share options to retain and incentivise staff, so those ongoing costs certainly should not be ignored. Anyway, whatever the details, it is definitely the case that STAF's underlying earnings will not be increasing by anything like 548%.
HTH. Cheers, Martin
Hi Shanklin100 and thanks for your comments.
There seems to be some misunderstanding. Perhaps I was not clear enough in my comments above.
The figure of 548% for EPS comes from Stockopedia and is based on consensus forecasts for normalised EPS. I believe this to be higher quality information than any underlying EPS number that Staffline may be putting forward.
What do others think?
Hi Warranstar
You are comparing apples and oranges. The broker forecasts are adjusted numbers whereas the historic numbers are unadjusted. IMHO, both numbers are probably wrong, in that:
- the historic numbers, calculated by Stockopedia's data provider, reverse out too many of STAF's adjustments, and,
- the forecast numbers, provided by not Stockopedia or their data provider, include adjustments, for share awards, that should not be being included.
However, the basic point is that the forward numbers and the historic numbers are being compiled on completely different assumptions and cannot be sensibly compared
So, yes, I agree there is a misunderstanding and it is in thinking that there is any rational basis for your 548%.
HTH. Cheers, Martin
Hi Shanklin100
It is not MY 548% increase in EPS. It is STOCKOPEDIA's 548%.
The numbers that the 548% increase in EPS comes from are both in the line in the stockreport called "EPS NORMALISED" From 17.4p for historic to 112.6p forecast gives an increase of approx. 548%. Surely the fact that the figures are on the same line means that the figures are comparable.
If you feel that the numbers are incorrect / inappropriate / misleading / badly presented or generally do not suit your purposes, then please ask Stockopedia to make the improvements that you feel to be appropriate.
Hi Warranstar
I give up. You just don't understand the basis for the information on Stockopedia.
Regards, Martin
Dear Warranstar,
Re: STAF
I find it useful to compare the Stockopedia page from the previous year to the current page. The 2 JAN 2016 report (click the arrow next to the PRINT button and a choice of historical pages appear) says that estimated eps for 2015 was 90p. The current page says that Stocko’s view on the actual normalized eps for 2015 was 17.4p.
I consider a difference of this magnitude a warning to spend more time than usual with the annual report so that I can form my own opinion.
In 2015 there was a huge D&A charge (over 13 million) and considerable share based payments (normal for STAF, which many would want to treat as if they were a part of normal compensation/salary). How you choose to treat these will give you wildly different EPS figures.
Laurie - as you say there a number of adjustments that every investor needs to consider in the case of Staffline (LON:STAF). To be fair to them Note 3 in the 2016 FY results issued last January, does provide a breakdown of the "non-underlying" items and a breakdown of these. Share based payments are a large ongoing cost, but every individual investor needs to factor this into their respective valuation of the company.
In the interims they issued in July, non-underlying items were a lot smaller.
Regards,
Imran.
Hi Paul,
Thanks for the fantastic article yesterday in which you set out your investing themes for the year. Lots of food for thought and many interesting points to go away and research.
On your point above about logistics and IT being critical to retailers, perhaps a company such as Sanderson (LON:SND) could be set to benefit? I don't hold them personally but they have been on my watchlist for about a year. They specialise in developing bespoke software for 'digital retail technology', wholesale and manufacturing. Their website has a wealth of information available, including case studies and broker notes. The business has a very high quality score of 97 (value 71) with operating margins consistently over 10%. They have net cash on the balance sheet and pay a reasonable 4% dividend.
I think they look good value and will inevitably have lots of retailers looking to them to help them become leaner and meaner and enable - (buzz phrase alert) Omni Channel revenue streams. Their solutions probably facilitate long term relationships with their customers - resulting in a 'sticky' relationship!
Has anyone else looked at Sanderson (LON:SND) and thought that they might be set to benefit from the competitive retail environment?
Best Wishes and Happy New Year!
Ben
@BenSharman
Yes I was looking when they warned sometime ago & after Brexit, trying to get in around 65p. Am now looking again.
Recurring revenue but see Paul's 2015 & 2014 comments:
Balance Sheet - dominated by intangible assets.
Pension deficit,
Development spending capitalised.
Knowing what you feel about reporting timings, I am a little surprised that you haven't commented favorably on £STAFF's reporting end year prelims within 4 weeks of the year end. I believe you commented favorably in the past on their inviting both individual and major investors to their presentation. On these few occasions, I wish I lived within striking distance of London because would like to hear what Hogarth has to say - hopefully without a cold and domestic distractions like those in your very good interview with him. Like you, I am Long and am tempted to buy a few more because I don't think they deserve to be where they are re SP. Could they be another Lavendon (LON:LVD) in terms of undervaluation, though not in terms of likely take over, more in terms of revaluation?
Is you excellent articles restricted to subscribers of Stockopedia?
Lennart Sjostedt
lennart.s@ntlworld.com
John Lewis's positive remarks about logistics would appear to directly read across to Clipper Logistics (CLG) which is now handling the JL click and collect business across the UK. CLG is already enjoying a heady multiple which is only enhanced by JL's performance
Kicking myself on B&M European Value Retail SA (LON:BME) I can't remember who it was, but someone suggested in the comments section a few weeks ago that it was worth looking at. I actually looked at it, said it was cheap but sat on my hands. Grr.
Hi Paul. I was interested re Staffline (LON:STAF). results as I hope this bodes well for Gattaca (LON:GATC). I'm not a holder of Staffline but am a holder of Gattaca and despite being good value trend like Stafflines has been downward. If Staffline gave a profit warning I was going to sell out of Gattaca. Hopfully they will start to recover.