Small Cap Value Report (Fri 11 Dec 2020) - FOXT

Good morning, it's Paul here with the SCVR for Friday.
Foxtons (LON:FOXT)
Share price: 44.14p (+0.32%)
(Jack writing - I hold)
Trading update from this London-based estate agency today. With its reasonably resilient lettings-based revenue, I’ve bought a few shares here on the basis that fears of a widespread migration out of London might have been overplayed.
We’ll see in the coming year or so if that thesis plays out, but in the meantime Foxtons (LON:FOXT) strikes me as a sensibly-run outfit that, post placing, has a good opportunity to consolidate and grab share in the London market. Directors have made a series of substantial buys at these lower levels.
In fact it doesn’t stop there - the company today announces a share buyback programme, so clearly the management team is signalling that it thinks the shares are cheap. Whether or not you will share that view of course is another question.
Performance improvement continues
- Group revenue in October and November was £14.8m, up 2% year-on-year.
- Splitting this out, sales revenue increased by 11% to £5.4m as momentum increased;
- Lettings revenue was down 1% to £8.0m with strong volume increases being offset by a decline in average rents and; and
- Mortgage broking revenue was down 14% to £1.3m.
This means that revenues for the eleven months to the end of November 2020 were £83.6m, down 15%. But, ‘as a result of the improving revenue trend and the continued tight control of costs’ the board now anticipates adjusted operating profit of £1.0-1.5m for the full year compared to a £0.7m adjusted operating loss in FY19.
Foxtons has a healthy cash balance expected to be in excess of £30m by the year end.
The company's trading performance has been better than expected, enabling it to spend £4.6m spent acquiring three lettings books this year. Trading so far suggests to Foxtons that this is the correct strategy in today’s market. There’s a good pipeline here and the group expects to make further investments in the next 12 months.
Not only that but the board says the combination of stronger trading and shored up cash balances means ‘it is now appropriate to start to return this to shareholders’. Foxtons is therefore buying back shares in the market from today, up to a maximum consideration of £3.0m, with a further update on capital allocation to be provided around the 2nd of March 2021.
Conclusion
Foxtons raised £22m of gross proceeds earlier this year and this put it in the position to capitalise on any market recovery. It looks like this is happening with £4.6m spent since on consolidating three lettings books.
There are still plenty of macro risks concerning the property market and London in particular. Lettings revenue makes up the majority of Foxtons revenue now, and this was down 1% due to a decline in average rents. So whether rental values in London in the year ahead recover or decline is probably a key point to consider and might well divide opinion.
This is a smaller holding for me but on balance, I’m quite reassured by the body language of this update. It’s worth remembering that Foxtons has plenty of cash on the balance sheet and could do well acquiring high quality lettings books around London.
That five-year chart doesn't look too smart - particularly when you consider the timing of that share placing in April 2020 causing maximum dilution - but there has been some buying activity recently, from directors, the community, and now the company's own coffers:
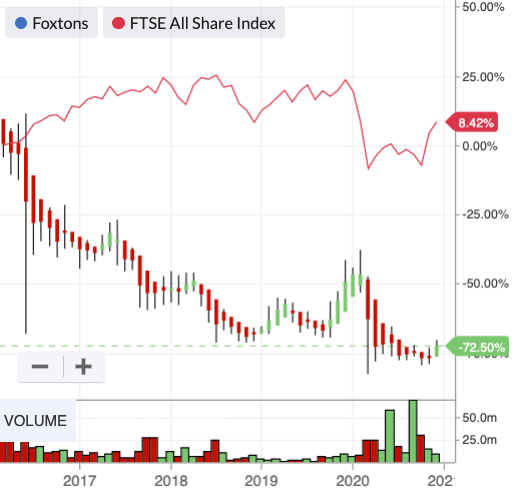
That said, the share price has fallen a long way and, even with share dilution from the placing (Foxtons now quotes 330,097,758 shares in issue), a return to previous levels of profitability could drive a material rerating if the market holds up and management can execute on the growth strategy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
Paul, Thanks for that Wonderful 'Harpy' Christmas. Thoroughly enjoyable & loved by all our bubble.
thanks Paul for a wonderful hour with Lauren - most enjoyable. My wife logged in as Sarah.
Best wishes to you both and a Merry Christmas
Mark
Hi Paul,
How did you plot the FTSE All Share over the Foxtons (LON:FOXT) chart in your report? Also, I see you've used a Heiken-Ashi chart, is this your preferred chart option?
Best regards,
Ian
Hi Ian,
Just type FTSE:ASX in adjacent to LON:FOXT in the long text box that you see above the chart and select it from the dropdown.
Thanks,
Nitesh
Thanks for the tip Nitesh, much appreciated.
Ian
I'm a London landlord and have by-passed using overpriced lettings agents like Foxtons (LON:FOXT) for many years. Very easy to do these days with cheap and excellent platforms like Openrent. If Foxtons (LON:FOXT) had falling sales commission during the recent period of stamp duty exempt turbocharged housing liquidity then the company is doomed.
Momoko. Your comments are interesting but the figures really don’t appear to support them.
Foxtons (I hold) as a whole appears to be doing well. Sales are actually up 11% (compared to 2019) during Oct & Nov, which is the period one would hope to start seeing sales income increase after the SDT holiday was announced in Sept.
Their lettings revenue was only down 1%, which surprised me, as during the past 9 months, we found our London residential properties being let at 10-20% discount to the previous rent. However, these properties are in the City and Central London where there are few people looking to let. Interesting, most of our new tenants previously lived in zone 2, 3 or 4 and are taking the opportunity to move in to the central area while rental prices are depressed.
I also like that the management team at Foxtons are buying some very smart mid to up market local agents for their lettings book. This is the market where few landlords have the time or inclination to do the viewings and haggle with prospective tenants by using an online letting platform such as Openrent.
Momoko. Your comments are interesting but the figures really don’t appear to support them.
Foxtons (I hold) sales haven’t fallen during the present stamp duty holiday as you suggest, they are actually up 11% (compared to 2019) during Oct & Nov, which is the period one would hope to start seeing sales income increase after the SDT holiday was announced in Sept.
Their lettings revenue was only down 1%, which surprised me, as during the past 9 months, prime central London residential properties have been let at 10-20% discount to the previous period.
I also like that the management team at Foxtons are buying some very smart mid to up market local agents for those agents lettings book. This is the part of the market where few landlords have the time or inclination to carry out the viewings themselves by using an online letting platform such as Openrent.
Have we got so used to Brexit talk that despite many stocks tanking, I noticed today there was not one comment on Brexit! Certainly affected my portfolio!
the market was relatively calm given the potentially calamitous circumstances. Either in denial or thinks Bojo is bluffing. He may not actually be joking this time, it's hard to tell.
Thank you for your insights this week. I wish you both an excellent weekend and I look forward to your commentary next week. Stay well.
Is this it?
Agree!
Deltic Group are on the point of administration, I notice. They are a nightclub chain.
I think there was a slightly strange reverse takeover approach regarding £RGB at one point. Revolution didn't engage much to Deltic's annoyance.
Not hard to understand why Deltic are in bad straits, given the various lockdown and Tier restrictions.
Paul you normally have a view on FCCN. Guessing you are tied up today but if you get time they have had a bit of an update. The Wholesale side seems to be going well.
Om French Connection (LON:FCCN) I had a thought. With the founder owning 41% and Frasers owning 26%, wouldn't it be easy for them to take it private on the cheap? Isn't that a key worry about investing in French Connection?
I know the rule is 'don't buy shares in businesses you don't understand', but I bought some Tiziana Life Sciences (LON:TILS) on a bit of a covid bounce, and continue to hold on the basis that their lead product -foralumab - seems to have worthwhile prospects anyway, As I understand it, it's an oral or nasal alternative to established intravenous drugs, which must be a 'good thing'. Tiziana Life Sciences (LON:TILS) has another drug which I understand is close to Phase 2 trials for liver cancer - it seems to have shown a 20% reduction in tumor size in an earlier trial. But as I watch the share price sink, can anyone help with a valuation of these things?
On the positive side, Tiziana Life Sciences (LON:TILS) has demerged it's breast cancer test as a separate company which has yet to reach the market but is due shortly, which will (hopefully) help recoup some of my losses
I learnt with Futura Medical (LON:FUM) - these companies need funding to stay afloat. It all sounds amazing and exciting, but can take a decade or more before any revenues are seen. I now don't touch small cap pharma with a bargepole, it's way too hard, takes way too long, and at the end the trials might fail and you're left with nothing.
Much easier and less risky ways to make a return.. :)
IGotPoeJacket - Totally agree with your sentiments. Don’t buy the initial story - wait until things are proven. I started accumulating shares in Angle (LON:AGL) in 2014 and now ‘expect’ to get into profit Q2 2021 when their Parsortix device gets FDA approval. Should have made much better use of my funds.
The story is in 3 parts as far as the market is concerned in my opinion.
(1) A US house put out a note saying that they considered Tiziana Life Sciences (LON:TILS) breast cancer unit as being worth more than the share price of the entire company and I think the price was then 135p approx. Tiziana Life Sciences (LON:TILS) subsequently emerged this unit and called it Accustem and plan on listing it in UK this year and in US next year.
(2) Market then got excited by its Foralumlab nasal product being tested on covid wide scale in Brazil. I think results will be Q1. It's basically supposed to protect against you getting covid I think.
(3) The rest - liver cancer phase 2 / churns disease phase 2 / nasal alternative to intravenous etc etc
It raised $57m in August at a price of around 130p I think - ($5.20 on ADRs but I forget the ratio now). Had starting position of £7m cash at end H1 so probably around £50m of cash. losses were around £3.9m for H1 so not terrible against current cash balance.
Problem is Accustem has not yet listed but went ex rights so people who bought for the value in that business can exit and still get their Accustem shares. No news on US listing which is really where the market value will be driven from and results from covid trials not till next year. So I think what you're seeing is the inevitable investor boredom factor....low liquidity, people selling up as no real news. It's illiquid and until the pieces of the story start coming together it will drift. The positive is that it is well funded.
I do not hold Tiziana Life Sciences (LON:TILS), but I do hold Hutchison China Meditech (LON:HCM) which has several drugs in phase 1/2/3. and Renalytix Ai (LON:RENX) which has an AI Early Kidney Disease Diagnostic system seeking for FDA clearance. Valuation wise, it's always a bit touch and go, with loads of assumptions included into a NPV calculation. Here is access to £HCM's notes if it helps you understand what I am referring to https://www.edisongroup.com/co... . Included in these assumptions is usually FDA authorisation as well as authorisation from other countries' FDA equivalent.
The problem about drugs is that they may not get approval in any one of the phases. An epic example is Circassia (LON:CIR) - check it out in 2016. Provided your sizing of your investment and insight into the Tembusu Investments (LON:TIL) 's drugs provide you with confidence, investing in drug companies can be good.
P.S - You could always leg it and sell out just before the annoucement of the phase 2 / 3 results and make a small profit - so you do not need to go through all hurdles.
Bonne chance!
Does anyone hold any strong views on Foxtons based on the news released today?
Foxtons (LON:FOXT) has revealed improved sales in recent months as it said it will hand cash back to shareholders.
Foxtons said it continued to see strong sales in the final quarter of the year, with group revenue rising 2% to £14.8 million in October and November.
Sales revenue jumped by 11% to £5.4 million during the period
lettings revenues slipped by 1% to £8 million.
“strong volume increases” in the rental market but said these were offset by a decline in average rents
mortgage broking revenues fell by 14% to £1.3 million for the two-month period.
Foxtons said it now expects an operating profit in the year to end December of between £1 million and £1.5 million and to finish the period with cash of £30 million.
It now believes it is appropriate to launch a share buyback due to its strong cash position, will now buy up to £3 million worth of shares from its investors.
Hi Tony. I was surprised to see Foxtons languishing at 33/34p a month or so ago and put in an offer at the asking price for a shed load.
I work in the property industry and know Foxtons very well. It is a very strong and aggressive agent.
After the large fund raising earlier in the year, I couldn’t see why they were at a basement price. The business looked newly refurbished and excellent order throughout.
Sorry about all the property puns but I couldn’t resist it, seeing as it’s in such a prime position.
Creightons (LON:CRL) H1 presentation 9.12.20 from Wednesday. Fantastic achievement in spite of CV19. They show great agility. Interesting market insight: male grooming nose dived during Covid! They expand on how they are grasping opportunities. Towards the end they give their aspirations going forward. Video & podcast.
Tamzin - thanks for highlighting. The presentations of Creightons (LON:CRL) are often full of insight and this one is no different. I used to hold the stock but no longer. I think the key magic sauce that they have is a wonderful management team, that is so agile - that is not afraid to chop and change - and that again was demonstrated in an outstanding H1. But I do not feel able to give that management team too high a multiple as Bernard Johnson and William McIlroy (who never seems to do presentations) are not exactly spring chickens. Admittedly there is some depth with a seemingly solid "next generation".
My main takeaway was not the fall in the male grooming market but the clarity with which it was stated that the hygiene market (which created such a strong first half with the exploitation of Pure Touch) is now totally flooded and overstocked. NHS warehouses are full of hygiene products and retailers are completely overstocked. Creightons itself, which commendably is never afraid of mentioning its own misjudgements, has excess inventory which will still take a couple of months to clear. I think this is essential information if looking at other stocks which have benefitted from the hygiene trend, e.g. Venture Life (LON:VLG)
Creightons (LON:CRL) I am sure Pippa enjoys rubbing it on for us men - for the two most recent presentations she has highlighted that during lockdown, men have literally stopped buying bathing / washing products or to that extent. Makes me chuckle everytime she emphasises this point! Yes, indeed, we can be rather uncooth neanderthals!
Hi Paul,
If you have the chance it would be great if you could circle back to review Cambria Automobiles (LON:CAMB) final results that came out of 25th Nov. You had previously reviewed a trading update. You actually got me looking into the car retailers following a recent comment you made about watching them yourself in light of potential supply disruptions post no deal Brexit. When you compare Cambria Automobiles (LON:CAMB) to Vertu, Marshalls, Pendragon, Lookers using stockopedias comparison tool, £camb comes out on top.
In the results profits held up well in light of the sales decline, debt seems to have come down a lot too.
In my view I think a lot of people will be looking for new cars next year as an option to spend all this cash that has been saved. I believe £CAMB are also focusing on more premium brands, so appealing to those middle class and above who should be in a decent financial position.
On a side note I really enjoy reading your reports, keep up the great work and Merry Xmas!
Hi
Does anyone know if you can turn off the graph thing in the folio windows?
Hi Steve I guess you must be on Chart View. If you look on the right hand side of the screen about half way down, just above the individual charts on your folios, you will see the icon option for Table View if you hover over it. Just right click that and hey presto you are back to table view.
Folio Graph: agree it not useful and seems to make loading slower.
Apologies meant the Folio chart itself with all shares performance by %
nails, your link does not work - is it just me???
Just had to share this link to Bill Blain’s Morning Porridge blog this morning -some hilarious comments on some of the recent IPOs that may brighten up an otherwise dull day!
https://morningporridge.com/th...
it worked for me and made me laugh and think, in that order.
I reported the RNS failure yesterday afternoon. I have received a reply:
We are currently investigating the issue surrounding the news feed on the Today page. Our development team hope to have this issue resolved soon.
(not that I reported or have ever found a 'Today page')
The 'Today' tab is found in the top left corner of your screen. It is effectively the home page of the site.
I'm on the old site where the home page is called "Home". I wonder how much some trendy consultant charged to tell them to rename it.
Morning all. Stockopedia seems to be missing quite a number of RNSs today. Must be a glitch in the system somewhere.
My morning smallcap tweet: ASH turns to ash, FOXT splash cash
Ashley House (LON:ASH) Nucleus Financial (LON:NUC) Westminster (LON:WSG) Inspired Energy (LON:INSE) Eagle Eye Solutions (LON:EYE) LSL Property Services (LON:LSL) Foxtons (LON:FOXT) French Connection (LON:FCCN) Altitude (LON:ALT) TruFin (LON:TRU) Deepverge (LON:DVRG) Zaim Credit Systems (LON:ZAIM)
Ashley House (ASH) RTO talks with Piper Homes break down. Administration and delisting. [SP=1.1 Cap=1m]
Nucleus Financial (NUC) guides FY(Dec) adj EBITDA and AuA ahead of mgmt exp. Purchase of certain assets of OpenWealth completed. [SP=172.25 Cap=132m]
Westminster (WSG) wins £750k 3 year contract. [SP=4.15 Cap=7m]
Inspired Energy (INSE) Guide FY EBITDA c.£1.2m below current expectations (whose?). SME division recovery didn't happen. Corporate Assurance Service ahead of management expectations. SME division disposal is complete. [SP=14.5 Cap=139m]
Eagle Eye Solutions (EYE) wins contract with US speciality office and home products & services retailer (>1000 stores) for real-time digital marketing. "The program will initially be a pilot launch for a limited number of regions, with a full roll-out based on a successful first phase." No $$$. [SP=390 Cap=100m]
LSL Property Services (LSL) guides FY(Dec) U/L profit (before covid related net costs) marginally ahead of 2019. Oct rev down 5%, first ten months down 18%. Nov key front-end sales metrics up. [SP=230 Cap=242m]
Foxtons (FOXT) Oct & Nov rev up 2% making first 11 months down 15%. Guides FY adj op profit £1-1.5m (-£0.7m). Starts share buyback of up to £3m despite planning acquisitions. Co had £22m placing on April. [SP=44 Cap=145m]
French Connection (FCCN) loackdown made conditions slightly more difficult across the retail channels.Wholesale performed well. Spring 21 orders currently ahead of mgmt expectations. US business gets 5 year $6.5m covid loan. [SP=9.88 Cap=10m]
Altitude (ALT) delays H1(Sep) "in order to present the most accurate view of the Group's financial performance and position." Blames extended cash collection timescales and extended payment terms for customers making rev recognition difficult. [SP=17 Cap=12m]
TruFin (TRU) Lloyds Ban to license Satago's software platform for its customers seeking single invoice finance solutions. 6 month pilot. [SP=45 Cap=36m]
DeepVerge (DVRG) the new R&D service, launched in Aug, has already generated £400k sales in Q4. "Agreements include framework Master Services Agreements with 2 of the world's largest suppliers of consumer products related to skincare." [SP=23.35 Cap=39m]
Zaim Credit Systems (ZAIM) Zaim-Express online loans up 62% in Nov cf Sept. Default rates remain stable. Expects positive momentum to continue. [SP=2.62 Cap=12m]
Nice to see that Britain may potentially be getting its first battery “giga factory” with a location now having been agreed by the company involved. Must admit it’s a company I have never heard of before so there has to be some doubt over whether they will secure the necessary funding to get this plant up and running - one thing is for sure there should certainly be the demand for the batteries that this plant would produce.
https://www.dailymail.co.uk/money/cars/article-9038971/UKs-gigaplant-Blyth-bring-3k-new-jobs-North-East.html
A U turn. Location moved from Wales. Another blow for Wales following Ineos confirming it's pledge to build in France not near Bridgend.
Disappointing for Wales not having the construction jobs getting the Ineos car plant up and running. However, I suspect it would be no great loss in the long term. Jim Ratcliffe is a clever guy but totally deluded thinking that his £50K defender clone has a long future. Major car manufactures are struggling, cutting back and merging resources. He's starting out with a old design, running on fossil fuels, blinded by his Landrover enthusiasm.
He's starting out with a old design, running on fossil fuels, blinded by his Landrover enthusiasm.
If I squint and hold my head sideways, I sort of see a point or two. It may not be Mr Ratcliffe's:
1 - Enfield motorbikes in India
It seems there is a market for something simple and strong
2 -Europe is not the world
There is a lot of the world that does not have running water, never mind electricity. IC cars will still be for sale there for some time.
There is a lot of the world that does not have running water, never mind electricity. IC cars will still be for sale there for some time.
Completely agree, but will they be buying 50,000 pound cars ???
I would have thought building in India or somewhere like that would be a better idea, perhaps closer to markets, before long ic cars will be banned throughout the eu, so all cars will need to be exported. Perhaps there will be exceptions for this kind of niche car ?? Sounds like a bit of a gamble to me.
Its not particularly moral to be exporting, promoting and marketing old legacy technology that ultimately kills people.
India is infamous for its pollution and anarchic traffic.
How would investors find this profitable and conscious able?
Hi Andrewdb - Electric vehicles - (As it's a slow Friday in the markets) I have just watched the long way up TV series (Electric Harley Davidson motorbikes ridden by Ewan McGregor & Charlie Boorman from tip south America to Los Angeles escorted by electric Rivian prototype trucks - Interesting about how much of the early episodes was about range anxiety, but once they reached LALA land travel became much easier.
Oh and they had branding gear from Mr Ratcliffe's BELSTAFF Brand.
(He really is the new Victor Kiam). If you are too young, Goole it
Hi EzLife - great series wasn't it. In a future life I think I'd like to be reincarnated as Ewan McGregor!!
Well hopefully if the proposed wales site has the available space it will get snapped up sooner or later by something similar. The article mentioned there wasn't really alot of these large potential sites to chose from - certainly the Blyth site seems to tick all the boxes infrastructure wise. With the move from petrol to electric building steam (hmmm?) one would kinda guess it may be easier simply to build something new shiny and fit for the 21st century rather than retrofit or repurposes existing sites - its a shame Tesla picked Germany over the uk for their Gigafactory plant.
Why would anyone build a new petrol / diesel car plan in the UK now that they are to be banned by 2030?
Well France currently has a ban coming in from 2040, and there's every likelihood that they will effecitvely stop sales no later than the UK - once you allow for the inevitable Johnson fudge and the likely tightening of French rules. The real reason of course is the likelihood of post Brexit tariffs. In France the immediate market is 27 tariff and customs free countries, plus the rest of the world on various terms. In the UK it's now likely to be the domestic market only, plus similar access to the rest of the world, including the EU. Why would anyone choose the UK for a primarily export based product on those terms?
In the UK it's now likely to be the domestic market only, plus similar access to the rest of the world, including the EU. Why would anyone choose the UK for a primarily export based product on those terms?
Well, the timing - ahead of the actual deal/no-deal decision - was interesting. It suggests they decided that it didn't matter either way. In which case this came down to a combination of access to engineering skills, the availability of a cheap ready made facility and, probably, some undisclosed state subsidies. In the end all's fair in love and trade :-/
Also the next gen Grenadier will likely need to use hydrogen cells rather than lithium batteries - the thing weighs in at three and half tons! France and Germany look to be ahead of that game, and their new site is slap bang on the French/German border so that's probably a factor.
But the final decision isn't quite done, so Ratcliffe would probably be open to the UK government dropping a half a billion or so on him to stay British ...
timarr
Re., 3.5 tonnes
There will be driveways (and drains etc) that will collapse with that on top of it.
Also, some minor road country bridges unable to take that weight.
And traffic parking regulations make it not so easy to park a 3.5 tonne commercial vehicle in a residential street.
Nice to see that Britain may potentially be getting its first battery “giga factory” with a location now having been agreed by the company involved
The intention is to IPO next year to try and raise £1.2 billion in seed funding. I've been looking at it but frankly I don't know, taking this kind of technology from start-up to a real roll out seems like a stretch. The loss of the Tesla gigafactory to Germany last year along with their R&D centre was a real blow:
https://www.autoexpress.co.uk/...
Europe already has 16 gigafactories either operational, in construction or in the final throes of planning with Germany the epicentre, unsurprisingly given its vehicle industry. The UK needs at least 4 by 2026 in order to be ready for vehicle electrification by 2030 and that probably isn't enough, so this process needs to be accelerated rapidly. Given the scale of investment required that can only be done with inward investment so this really needs some government focus, asap.
timarr
The intention is to IPO next year to try and raise £1.2 billion in seed funding. I've been looking at it but frankly I don't know, taking this kind of technology from start-up to a real roll out seems like a stretch.
I don't see why the plant should particulalry be a stretch tech wise - i would be more worried about them being able to get adequate funding. By the time the plant is up and running i would expect the tech won't need to necessarily be anything special and it does sort of make sense each county having at least one such site that is geared up not only to produce the batteries but ensure hopefully that there is some associated recycling plans put in place to manage the whole life cycle of similar products. Whether an ambitious project like this would make a good invetsment or not i would be slightly more dubious about.
I don't see why the plant should particulalry be a stretch tech wise
Dunno. Sounds quite complicated to me:
https://britishvolt.com/resear...
But perhaps this Wired article gets a bit closer to the problem:
69,000 to 186,000 engineering workers left the UK each year since 2016 to be replaced with only 46,000 engineering students and apprenticeships.
https://www.wired.co.uk/articl...
The underlying issue is that without home grown battery manufacture the future of the UK car industry starts to look pretty doubtful. At the moment a battery is about 40% of the cost of an EV so it makes importing them a costly proposition, far easier to make them local to manufacture.
Tesla can go from unbroken ground to a functioning gigafactory in a year. The government really needs to get a wriggle on.
timarr
But perhaps this Wired article gets a bit closer to the problem:
69,000 to 186,000 engineering workers left the UK each year since 2016 to be replaced with only 46,000 engineering students and apprenticeships.
I would have every confidence that this won't be a major problem - obviously if this goes ahead they may be importing into the region a high % of the specific expert labour needed at the beginning But the north east has a fine pool of competent individuals with engineering background probably crying out for semi skilled upover local work. One only has to look at the local talent that Siemens has been ditching over the last few years (and will probably continue to ditch) to see the quality of the talent pool that resides here - there is also a very decent pool of people that live here and have traditionally worked way from the locality due to them following the work wherever that may be so perhaps a portion of the 186k that left will return even if its not as easy to get a pint of Mcewans nowadays as it should be.
But the north east has a fine pool of competent individuals with engineering background probably crying out for semi skilled upover local work
Yeah, but we're not talking semi-skilled work. The standard perception of an "engineer" is someone who gets their hands dirty but what we're referencing here are people with STEM qualifications.
Not only do we have a shortfall of between 37,000 and 60,000 engineers a year, nearly 20% of all qualified engineers in this country are due to retire in the next 6 years (including me). And this is an area where there's global competition for skills - it won't be as simple as just importing the people we need.
timarrYeah, but we're not talking semi-skilled work. The standard perception of an "engineer" is someone who gets their hands dirty but what we're referencing here are people with STEM qualifications.
Not only do we have a shortfall of between 37,000 and 60,000 engineers a year, nearly 20% of all qualified engineers in this country are due to retire in the next 6 years (including me).
Well, I'm out of circulation from next April. This country has never considered engineering a worthwhile career, as they do in Germany for example, and the perception has always been wrong. Unfortunately, you reap what you sow. If I knew anyone graduating with an engineering degree I'd tell them to go get themselves a better life overseas where their work will be appreciated and they will be paid commensurately.
All the best, Si
As an investor I appreciate engineers...mainly because they tend to do important stuff ..but they are also hard wired to tell the truth...as otherwise bad things happen
Couldn't agree more. The low status of engineering as a profession in this country is a disgrace.
And a UK surplus of tattooists, nail technicians and influencers.
Wired tends to be a remainer-editorial publication.
There are no lithium or cobalt mines in Britain (ASFAIK). I don't see that as much different from Tesla and Panasonic's US plants?
The magic materials presumably come by ship and rail.
We are pretty good at shipping, ports and rail infrastructure.
No. The Cornish pixies claim to have found 'globally significant' promise of lithium.
https://www.bbc.co.uk/news/uk-... and https://www.cornishlithium.com...
That is very good news.
And good news that its not in the independent national socialists republic of Scutland.
Just imagine if Krankie suddenly found she controlled The British Isles leading source of the future key commodity.
There are no lithium or cobalt mines in Britain (ASFAIK). I don't see that as much different from Tesla and Panasonic's US plants?
As the proud scion of a Cornish fishing family I can confirm we've found lithium down the pasty mines. And the engineering loss figures are consistent with the various Engineering UK reports (https://www.engineeringuk.com/...). The Faraday report suggests we need about 50,000 Phd level engineers to run the industry needed to meet the 2030 targets (https://faraday.ac.uk/wp-conte...).
I don't think the materials for battery production are particularly difficult to get hold of - it's more the process to get the factories up and running which will need inward investment and the expertise needed to build and run them. Everybody is trying to do this so you've a global crunch on skills and investment.
The UK is late to this game, it needs more than some start-up to move to critical mass - LG, Samsung and Amperex have already committed to plants in the EU, for instance, while Total / Opal will have an initial site up and running next year. Northvolt's plant will also come online next year, along with Tesla's.
The UK also has a structural problem with car manufacturing as well because we only have a small handful of volume producers - we need a big enough home grown industry to support the battery production. Of those the Toyota factories must be at risk because even with a Brexit deal they won't meet the country of origin rules and will be hit by WTO tariffs. And the UK-Japan trade deal means they can import from Japan at zero cost. The Vauxhall plant is also at risk, as it's Peugeot owned. So that leaves Nissan, Jaguar Land Rover and BMW.
As you might suspect I'm looking hard at this to figure out how and where to invest, but the UK government needs to start backing rhetoric with action if it's to be worthwhile investing in companies in the UK.
timarr
They say in the article that the first £500m of the £1bn government funding that Boris announced will be made available next year and they will be looking to get some of that, but don’t know how much.
Timarr:
Have the DNOs sorted out the problem that the IET identified almost 10 years ago, that the distribution networks can't cope with a huge reactive load (car chargers and heat pumps), or balance load and supply effectively without the smart grid instrumentation that has been left out of the UK Smart Meter SMETS specifications?
Martyn
Hi Martyn
Have the DNOs sorted out the problem that the IET identified almost 10 years ago, that the distribution networks can't cope with a huge reactive load
I believe that this is part of the Power Potential project being run out of the National Grid. But, to be honest, I haven't spent any time looking at it:
https://www.nationalgrideso.co...
timarr
Morning Paul, it would be great to get your views on Nexus Infrastructure (LON:NEXS) they have provided a good breakdown of p/l between their 3 main divisions.
Re £NXS..nothing showing here (though I use the old system). Went to a SIPP which uses Morningstar to find the results. More or less as you might have expected I think.
A steep drop for the BOTB SP yesterday on no news. Volume was almost 10x average. Does anyone have insights?
Someone elsewhere has connected it with the government’s recent announcement on gambling review and bringing this kind of site within the credit card ban but I don’t know for sure if that is the reason.
Although, I don't think Best Of The Best (LON:BOTB) is considered gambling? https://www.gamblingcommission.gov.uk/for-the-public/Fundraising-and-promotions/Commercial-schemes/Spot-the-ball.aspx says:
Is your spot the ball scheme a prize competition?
Your spot the ball scheme could be a prize competition, depending on how you arrange it.
To be a genuine prize competition, rather than a lottery, there must be an element of skill, knowledge or judgment that is reasonably likely to prevent a significant proportion of people who wish to participate from doing so or prevent a significant proportion of people who participate from receiving a prize.
For example, if a panel of judges determine the position of the ball and participants have to apply judgment, skill or knowledge to match their own decision of where the ball is with that of the panel, it is more likely to be a prize competition than a lottery.
Genuine prize competitions are free from statutory control under the Gambling Act 2005 and therefore do not require a licence.
Best Of The Best (LON:BOTB)
Westway001
Someone elsewhere has connected it with the government’s recent announcement on gambling review
Andy Sav
Although, I don't think Best Of The Best (LON:BOTB) is considered gambling?
andy
Is the point not that a review of the rules may conclude that it is gambling?? and therefore going forward they may have to abide by the relevant stricter rules and presumably possibly pay additional taxes too. The company cleary states that their activities may end up regulated.
Ah, ok. Good point :) Just wasn't sure if the gov announcement applies to companies currently considered as gambling, or if there will be an extension to then pull in other companies like £BOTB as gambling and then applying further restrictions. I haven't seen the announcement, so maybe have looked for that first :)
There was a VAT case back in 2015 where HMRC argued that spot the ball is a game of skill and not gambling because they wanted to charge VAT on it.
Certainly Best Of The Best (LON:BOTB) have a reasonably strong case that their "spot the ball" is not a lottery, in that it involves a certain degree of skill (to at least get into the ball park of winning).
Arguably different skills may apply dependent on how the competition is settled : one skill might be to determine where a "panel of experts" think the ball might be; determining where the ball actually was might be another skill altogether. (I think there is an investment message in there, but that would be going off topic.)
However, not being a lottery does not mean that it is not gambling.
I think most people would consider poker to be a form of gambling. Most people that have an understanding of the game would also accept that it is a game of skill and that over the course of a large enough number of games, the most skilful player will leave with the money.
It is harder to sell the idea to the general populace (although I know at least one person here agrees) but exactly the same argument applies to betting on the horses (or even the dogs).
Roulette on the other hand is entirely gambling as the outcome is entirely random. If someone tells you they "have a sure-fire system" to win at roulette - run for the hills, you are about to be scammed (or be a patsy in some kind of fraud -probably involving electro-magnets).
So why do governments want to control or tax gambling?
To raise revenue obviously, but also they want to discourage the activity - to protect the participants. The vast majority of participants are operating with the false opinion that they have "as good a chance as anyone" of winning (or perhaps even more chance, because their wife knows this woman whose brother lives in Newmarket).
If its a tenner every year on the Grand National to make it more interesting, then it is not really a problem. However, you don't have to search too far to find the stories of people that become obsessed with the idea of easy riches and then entrenched in chasing their losses.
This is why I think Best Of The Best (LON:BOTB) could fall under the spotlight. I have never looked at the company in detail, but I think to grow they have to :
1. Ensure more people have visibility of their competitions.
2. Make those people really want their prizes.
3. Convince some of those people that they have such a good chance of winning that it is worth making (i.e. paying for) multiple entries.
Personally I am not totally morally adverse to a business like this (although I do have tendencies) but I don think possible regulation should not be ignored.
As luck would have it I entered a (free) competition in my local newspaper last weekend for a family ticket to a local tourist attraction; my prize arrived in the post on Wednesday! I will now be entering every competition I possibly can as I obviously have the lucky touch!!
(Thankfully it is an attraction that I would visit anyway - otherwise I would still probably be out of pocket having been extorted in the Restaurant and Gift shop!)
Still a risk that the government tighten the regulatory framework and considers "spot the ball" a form of gambling!
Best Of The Best (LON:BOTB)
To add to the discussion, it's probably also worth noting that every person is limited to 100 ticket purchases per competition per week. That's about £500 max per week for the most expensive tickets in the Dream Car competition, and £15 for the cheapest tickets (eg an iPhone).
Given that one of the biggest changes anticipated from the upcoming gambling review relates to stake sizes, BOTB would therefore probably only be affected if:
As long as any new stake limit (if that is indeed what is recommended) is £5 or over, then there should be no impact on BOTB given that this is the maximum ticket price customers currently pay.
As an aside, I see that the Dream Car competition is offering £50k again with each ticket sold. The company must be doing well to be able to offer this so frequently.
Well, I hope so anyway as I hold.
A