Small Cap Value Report (Fri 15 Jan 2021) - CARD, XAR, FIF, CLG, BWNG

Good morning, it’s Paul here with the SCVR for Friday. What a busy week it’s been!
Spectacles steaming up when you wear a face mask? It's been the bane of my life lately. I've found a solution which completely eliminates fogging up with glasses, explained in this short video. If you find this helpful, then feel free to share it on social media, because this does work brilliantly!
.
Timing - Today's report is now finished.
Agenda -
Card Factory (LON:CARD) - Trading statement - covenant breach imminent, so risky
Xaar (LON:XAR) - Trading update FY 12/2020
Finsbury Food (LON:FIF) - H1 trading update
Clipper Logistics (LON:CLG) - Founder/Chairman sells £62m-worth of shares
N Brown (LON:BWNG) - Q3 (18 weeks to 2 Jan 2021) Trading update
.
Card Factory (LON:CARD)
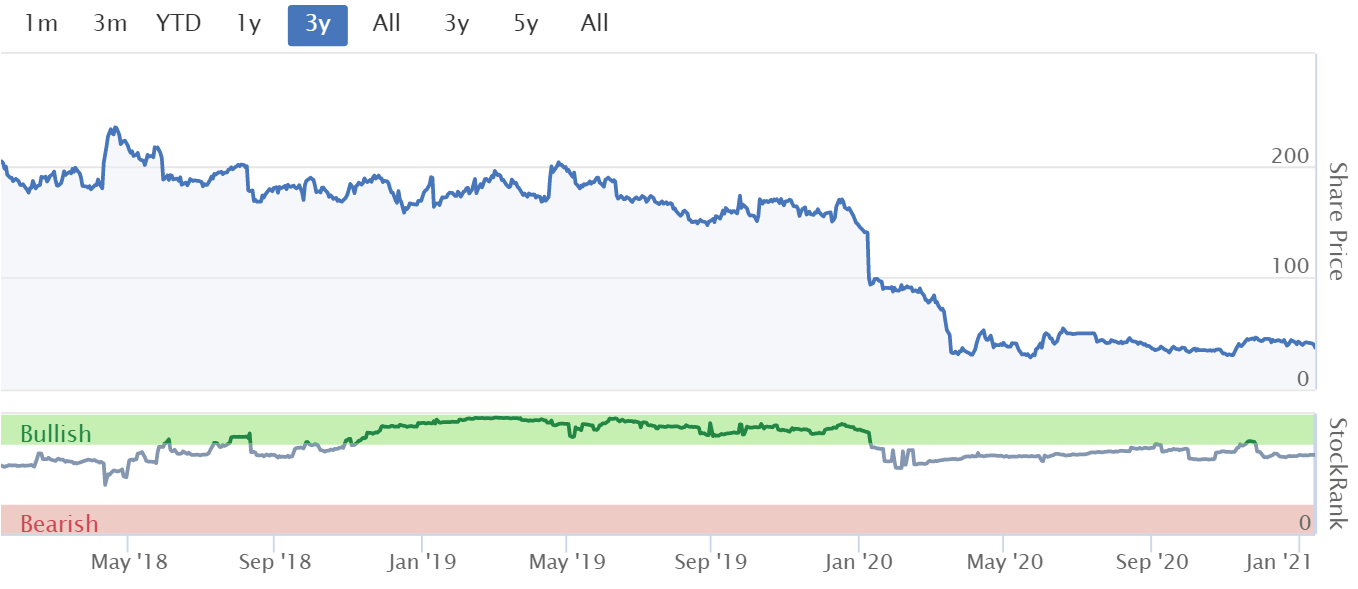
37.3p (down 7% yesterday) - mkt cap £127m
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, announces its trading update for the eleven months ended 31 December 2020.
Obviously it's been hit hard by covid/lockdown enforced store closures, no surprise there. Revenues down 34% in total, of which store sales down 38.1%. This suggests that online growth, whilst good in % terms, is nowhere near enough to compensate for store closures.
Although stores did trade better when they were allowed to open;
Recovery following first national lockdown exceeded board's expectations, building to sustained positive LFL from early October 2020 with the shop estate fully open
CARD was highly indebted before the covid crisis, so I am concerned about its solvency & bank position, which could end up forcing it to do a big placing.
It reckons current bank facilities are enough;
Assuming the current national lockdown for non-essential retailers does not extend beyond 30 April 2021, existing bank facilities of £200m would be sufficient to meet the current requirements…
Despite the unprecedented nature of this year, our aggressive but considered management of costs and cash has resulted in a material reduction in our utilisation of the debt facility, resulting in net debt being reduced to £90m as at 31 December 2020, compared to the net debt of £119m as at 31 December 2019.
We would not expect this facility to be fully utilised unless the national lockdown, restricting non-essential retailers from trading, continues beyond the end of April 2021.
Bank covenant breach looming - this is a major concern;
… we anticipate that current covenants will be breached at the end of January as the significant impact of the November and current national lockdowns are reflected in our trading performance. We continue to have constructive discussions with our banking syndicate.
Note it says “will be breached”, not may, or might be breached.
Despite initially being given access to Coronavirus Corporate Finance Facility (CCFF), following changes to the scheme rules, we no longer have that opportunity. We are, however, progressing discussions to access supplemental funding options.
What does that mean? Are they looking at alternative debt facilities, or an equity fundraising?
Guidance - I’m surprised the anticipated loss is so small, at just £10m. Although the company must have received substantial assistance under the furlough & business rates relief schemes.
With the certainty that all stores will be closed through to the end of January 2021, the Company anticipates revenue for the full financial year of approximately £284m, and a loss before tax of approximately £10m (equivalent to Adjusted EBITDA (excluding the adjustment for IFRS16 for Leases) of c. +£5m)
No guidance for FY 01/2022, because they don’t know when the shops will be able to re-open.
Stretched creditors? We’re not told, or given any numbers, but I would take it as given that VAT would probably have been deferred, hence flattering the net debt figure.
My opinion - I’m not interested in this share, because the debt was too high before covid, and once creditors have normalised, it’s likely to look quite a lot worse in future. Therefore, I imagine an equity fundraising is only a matter of time.
If we want to bet on consumers returning to the shops, then I think there are much safer options in terms of balance sheet strength. Also, I feel CARD has missed big opportunities re online. Press reports are saying that Moonpig is intending to float, with a £1bn valuation! Clearly CARD has missed the boat, in terms of online. I’m only interested in retailers that are also doing a large amount of sales (half or more) online. Examples are Next (LON:NXT) and Joules (LON:JOUL) (I hold).
.
.
Xaar (LON:XAR)
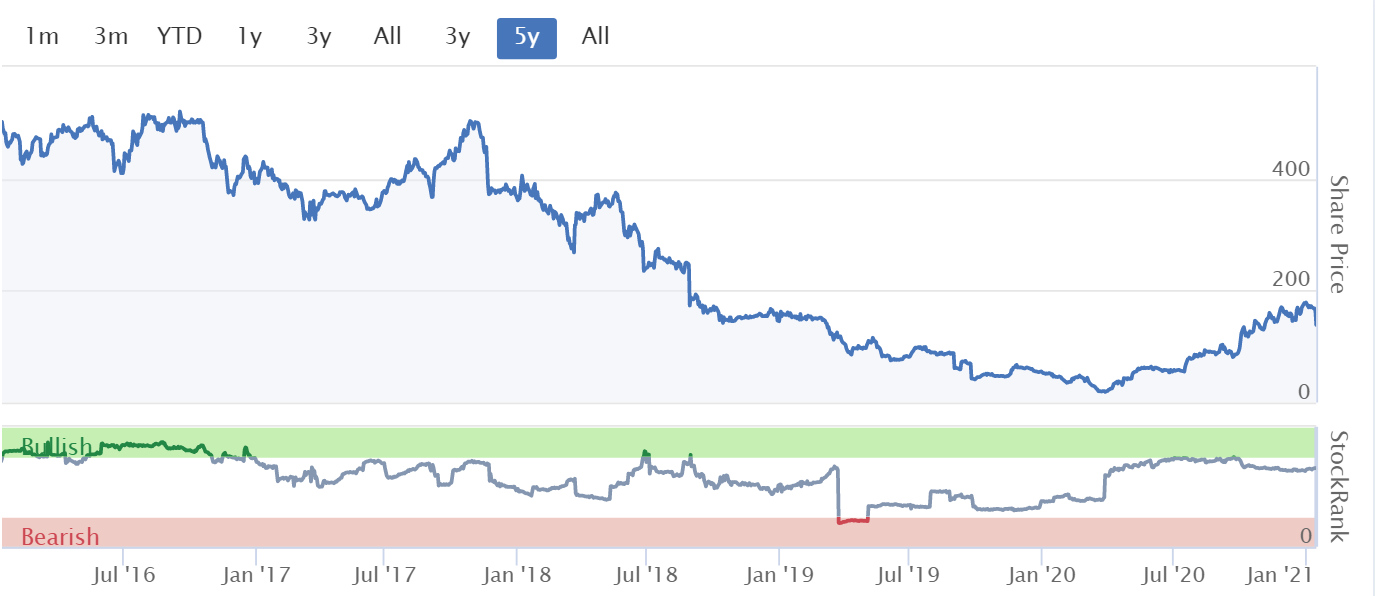
138p (down 15% yesterday) - mkt cap £109m
This share has had a great run up in price, but took a breather yesterday, down 15% on publication of its latest trading update.
It’s had a lot of positive commentary in recent months from renowned investor Richard Crow (CockneyRebel), and Andy Brough from Schroders has talked about it positively several times. The bull case is that it’s a turnaround, with good technology, plenty of cash, and a likely takeover target in due course.
I last looked at it here on 16 July 2020, seeing a possible turnaround, but wanting to see more evidence first before diving in. Pity, as it’s more than doubled in price since then!
Xaar plc ("Xaar", "the Group" or "the Company"), the leading inkjet printing technology, today announces a trading update for the year ended 31 December 2020.
The Board is pleased to announce that, with the on-going successful implementation of the new strategy, trading was in line with its expectations. Revenue for the year was approximately £48m and in line with that recorded in FY2019.
Xaar achieved £23.7m revenues in H1, so H2 is £24.3m - hardly changed.
It lost £(9.8)m in 2019, on an adjusted PBT basis (continuing ops).
H1 2020 also saw a loss, of £(3.9)m on the same basis, which annualises to £(7.8)m loss, not much better than 2019.
The commentary says positive things about products, etc.
Cash & liquidity - sounds OK, but nothing is said about whether any creditors have been stretched or not;
The Group retains a strong balance sheet and cash position. Cash and cash equivalents at 31 December 2020 were £20.2m. This was driven by positive operational cash generation in both Printhead and EPS, as well as maintaining a strong focus on cash and disciplined cost controls.
Outlook - promising profits in the future;
… the order book remains strong with a positive pipeline. We continue to rigorously review opportunities available in the market, remaining focused on our strategy, and are on-track to return to profitability and growth.
Xaar said that the “short term order book is healthy” in July 2000, but that doesn’t seem to have translated into any significant improvement in revenues in H2.
My opinion - profitability at Xaar was previously dependent on Chinese printed tile manufacturers buying Xaar printheads. That fell off a cliff in 2018, and the company has made losses ever since.
Therefore the £109m market cap hinges entirely on it being able to rebuild profits from new products. I don’t have a view either way on that, as it would need detailed research & knowledge of the sector. Therefore I’m neutral.
There’s nothing in the figures to encourage me to have a punt on Xaar shares. The commentary does sound more interesting though, with a return to profits specifically mentioned. It could work out, as Xaar has historically had good technology, and made good profits in the past. Other people are in a better position than me to judge how likely a turnaround is.
.
.
Finsbury Food (LON:FIF)
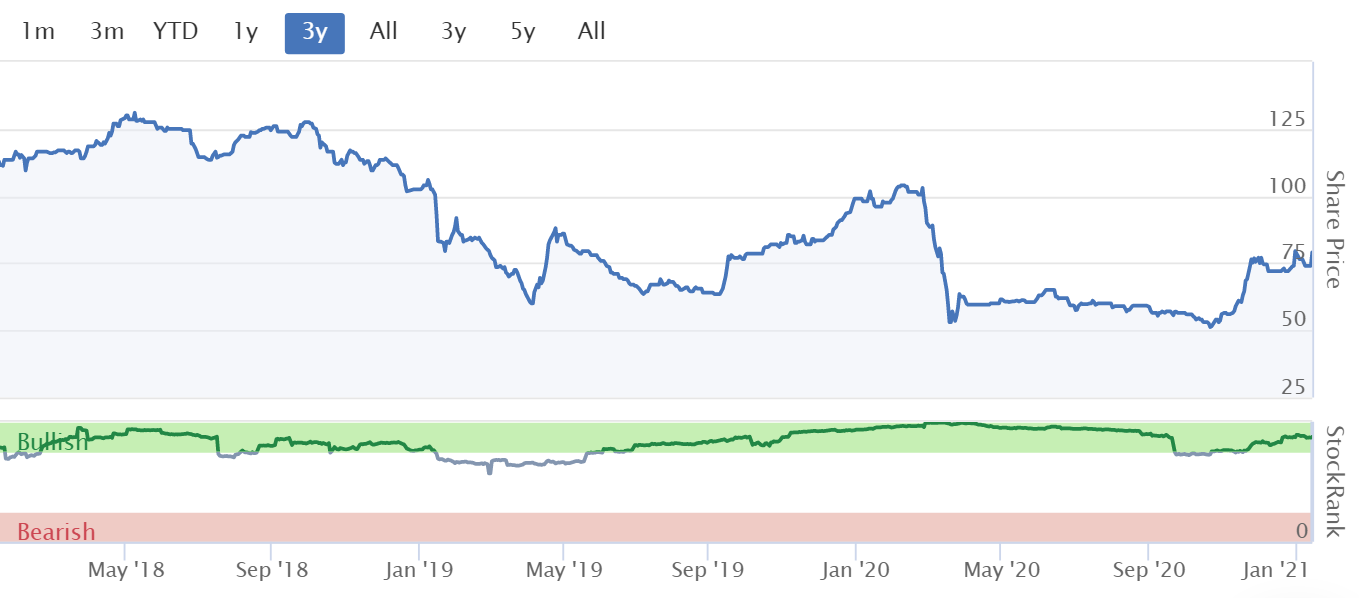
79p (up 7% yesterday) - mkt cap £103m
Finsbury Food Group plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for both the retail and foodservice channels, announces an update on trading for the six months ended 26 December 2020 ("H1").
Resilient trading, despite challenging backdrop
H1 sales of £152.9m, down 4.1% on LY H1
Foodservice (e.g. supplying cakes to coffee shops, etc) down -27.4% - continued impact from lockdown restrictions
Net debt down £5.0m in the last 6 months, to £21.5m
Confident in delivering FY performance in line with expectations.
There’s no footnote, to inform us what market expectations are, and with Cenkos withdrawing coverage today, I’m not confident that we can necessarily rely on previous forecasts.
If the old forecasts are reliable, at c.8p, EPS for FY 06/2021, then the PER looks good value at about 10. What a pity the company and its advisers didn’t include a footnote to inform us of market expectations today.
Overall, it’s up 50% in recent weeks from the lows, and is probably priced about right for now, maybe? It should benefit from re-opening of coffee shops in 2021, so might be worth a closer look, if you like value-style shares.
.
.
Clipper Logistics (LON:CLG)
588p - mkt cap £598m
Chairman/founder sells
After the market closed last night, it was announced that the founder/Chairman of Clipper, Steve Parkin, is selling 11 million shares in a secondary placing.
(For anyone not aware, a placing usually raises money for the company itself, by the creation of new shares, which are sold to institutions usually. However a secondary placing, is where a shareholder wants to sell a large number of existing shares, too large a sale to go through the open market. So the company itself receives no money from a secondary placing).
The reasons given for his selling a substantial stake are;
The Placing is being undertaken by Clipper founder Steve Parkin as part of an estate planning exercise and to improve the liquidity in the Company's shares.
Can we just stop this nonsense about people selling in order to improve market liquidity in the shares please? It’s nonsense, and everyone knows it. Improving liquidity in the shares is a by-product of selling, it is never the reason for selling. The reason for selling is simple - that the seller would rather have the cash, than continue holding the shares!
Result of placing - this morning, we’re informed that the placing has been done. 11m shares sold, at 565p (a discount of c. 4%).
That has raised £62.2m before fees for Mr Parkin - so party time at his place!
Importantly, he still retains a substantial stake of 13.9% of the company.
My opinion - when a founder sells a big stake, I’d be inclined to follow suit, and reduce or completely sell my own position. It’s the person who knows the most about the company, signalling that the price is attractive for a seller.
Clipper does seem a good business mind you, and has an excellent track record of growing revenues & profits. It's doing well from conventional, and eCommerce logistics. I think it makes a lot of sense for eCommerce businesses to outsource the logistics/warehousing/dispatch side of things, as that frees up management to focus on what drives their own business.
.

.
N Brown (LON:BWNG)
65.3p (down 12%, at 09:43) - mkt cap £301m
Is this an eCommerce business, or a finance company? It’s more a finance company in my view, that sells things online, in order to make a profit on the extended payment terms. That’s why the shares always look cheap. Plus its finances got a bit stretched, although that seems to have been fixed with a placing in 2020.
It’s a potential turnaround situation too. So lots of moving parts to take into account here, and it’s very difficult to value as a result, with investor opinions differing more widely than for most other companies.
The one year chart below shows a good recovery, although I feel the recent market upward moves (since vaccines approved) have generally been a bit indiscriminate, and might reverse if not supported by improving fundamentals, in some cases.
.

.
The longer-term chart paints a grizzly picture - with bears saying this is a lousy business, but bulls saying there’s an opportunity for a re-rating on a recovery in performance -

.
Dilution - note that the business was run with inadequate capital, and paying overly generous dividends, which left it high & dry when the covid crisis struck. It had to do a dilutive fundraising (at 57p), and now has 460.5m shares in issue, as opposed to 289m pre crisis, a 59% increase. That limits the upside % on the share price, because there are so many more in issue now.
.

.
Doesn’t this demonstrate the folly of operating with a weak balance sheet? It’s not hindsight either, as I’ve been constantly banging on about the importance of balance sheet strength since these reports began about 8 years ago. You never know what’s around the corner, hence why balance sheets need to be robust. See more on this theme in the separate section below.
Although note that BWNG has a very wealthy backer, Lord Alliance, estimated to be worth £3.1bn. That clearly came in useful when more funding was needed. The price of the fundraising could have been very much lower, without such a key major shareholder prepared to back it.
Trading update - the company is reporting for the 18 weeks to 2 Jan 2021, which it calls Q3, but it isn’t a quarter (which is 13 weeks!). I think BWNG should adopt the terminology used by Boohoo (LON:BOO), which refers to P3 (i.e. period 3, of 4 months), and P4 is just 2 months Jan-Feb 2021.
This is all self-explanatory, and sounds OK to me;

.
The footnotes really matter here, because the net cash claim above strikes me as rather misleading. It actually has tons of debt, which part-finances its huge receivables book for customer extended payment terms, as explained in tiny font further down the announcement;
4 Excludes debt securitised against receivables (customer loan book) of £399.6m and lease liabilities of £5.3m
Marketing costs - a major discretionary spend for online businesses. It’s noteworthy that BWNG cut marketing spend by 40% in Q3.
Revenue trends - are improving quarter-on-quarter, as you can see below. However, revenue is still negative Y-on-Y in Q3, when other eCommerce businesses reporting so far have shown excellent growth over the same/similar period (e.g. Asos +23%, Gear4Music (I hold) +30%, and best of all BooHoo (I hold) +40%)

.
Cash collection - from the large customer receivables book sounds OK. In line with last year (so no deterioration feared from higher unemployment as yet). The arrears rate has actually improved, from 7.9% LY, to 7.0% now.
Regulatory changes are mentioned as a negative factor, which is always a potential risk with a high interest lending business.
Fundraising of £100m, and a move to AIM done, we’re reminded. Net cash position of £83.7m, ignoring all the debt related to customer receivables, as mentioned above. I like this bit -
... the capital raise will also enable the business to invest further in its digital capabilities and accelerate its growth strategy.
Debtor book is £663.6m - huge! There is £399.6m of borrowings under a securitisation facility, funding 60% of the receivables book. The business model is to borrow cheaply in bulk, then charge customers a lot more, for small loans incurred from selling them stuff online. It’s a consumer credit company really.
Supply chain disruption - doesn’t sound too bad, but this is clearly an important theme at the moment, affecting lots of companies;
As with a number of other retailers, we are currently experiencing delays of two to three weeks for many of our stock deliveries, given global container issues, as well as cost pressure in the supply chain. We are working through the operational challenges which this presents us and looking to minimise the impact on customers.
My opinion - I’ve got the general gist of this now. With the fundraising done, and turnaround actions being undertaken, I think this share looks a lot better than it did last year.
I think the opportunity here is if they manage to crack being good at selling things, rather than relying on profit coming from expensive consumer finance. If that is achieved, then there could be both a profitable eCommerce business, and hefty profits from consumer finance.
The increase in bad debt provision is a bit of a worry though. The risk with consumer credit is that bumper profits are booked in the good times, only to prove illusory in the long run when customers default in a recession.
Overall, I think it looks potentially interesting. The lack of revenue growth is the main problem. Why should the shares re-rate, whilst growth is going backwards? Surely an eCommerce business should be enjoying boom time after almost a year of on-off lockdowns? Hence probably a lot more work needed to deliver a convincing turnaround.
.
Business models need to change
We didn't know this before, but covid has demonstrated that many business models were deeply flawed, since they assumed uninterrupted revenues forevermore. We now know that a large part of the economy can be shut down for months at a time, repeatedly, if a pandemic emerges.
There have been lots of these in recent years, e.g. bird flu, swine flu, SARS, MERS, and now covid. Authorities managed to shut down the previous ones, because they weren’t highly contagious, but the disaster scenario was always the risk of something mutating into a form that is highly transmissible from human to human, which is what we have now with covid-19.
Is it a once in 100 years event, or is this likely to repeat? Who knows? It seems to me that the important thing is for companies to realise that their business models need to change, in particular these are my thoughts & suggestions;
- Costs need to be more flexible, so that they can be switched off quickly in a crisis - this is where online businesses have a huge advantage
- Property leases - are a millstone, and have already rendered many retail/hospitality businesses insolvent, or nearly so. Leases need to be reconfigured to turnover rents, with low base rents, so that they are not onerous in the event of a lockdown, but of course landlords are not embracing this idea!
- Many companies have too much gearing, and not enough cash reserves. This is “efficient” in the good times, but disastrous in the bad times.
- Companies with the weakest balance sheets have been forced into dilutive equity fundraisings, at the worst time, when the share price was low, and confidence weak, in the spring/summer of 2020.
- All companies (especially in travel sector) should be required to segregate all client deposits, and keep them in trust accounts (SAGA [I hold] is now moving to this model by the way)
- Far more business needs to be moved to the internet, so that things can carry on even in lockdown. Automation of routine processes is more important than ever too.
- Dividends should only paid out of genuinely surplus cash, after allowing for a substantial contingency reserve, in case of another pandemic.
- Bank covenants need to take into account possible future periods of inactivity.
- Markets could be more volatile - e.g. if virus outbreaks occur again, then markets could sell-off more quickly than last time - remember we had about 1-2 months when covid was known about in Jan-Feb 2020, before the really big sell-off began. I don’t think that’s likely to happen again, once bitten twice shy, so we probably have to live with more extreme volatility.
- Government support measures have been unprecedented. It’s important to realise that, without these, large swathes of UK companies, of all sizes, would have gone bust, and the stock market probably would have crashed by 90%, wiping out most of our portfolios, and plunging worldwide economies into a massive economic depression. This time round, QE, zero interest rates, and massive Govt deficit spending saved the day. But what if next time, inflation & interest rates are already high when another virus strikes? It doesn’t bear thinking about, it would be carnage.
- Will companies take the above into account, or just go back to business as usual? I reckon the latter, as people have amazingly short memories, and we rarely learn from past crises.
.
I'll leave it there for today. See you next week, and have a nice weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
Clipper Logistics (LON:CLG) - founder sells to improve liquidity - seems to have worked - reading 100 baggers so may be worth study and a separate post tracking founders or CEO with skin in the game.
Sunday - The Intelligent Investor by Benjamin Graham is 99p in the Amazon Kindle daily deal today.
Well, if people can't be a bit charitable with their clicks and perspective during a raging bull market whilst coining on their genius....just imagine how snarky we are all going to be during a bear market.
Nevertheless I will promise to be just as disagreeable and contrary then...and to post long rambling yet detailed comments like now when I comment.
Anyhoo...I found this simple analysis quite interesting today:
https://www.variantperception....
Enjoy the weekend muthaf....
Hi Paul
Good postings nothing I am tempted to buy; think I will watch BWNG
Paul, thank you as always for the tremendous input you provide daily. A broader question, if I may, which may well be outside the framework you suggested for comments yesterday.
I see a lot of value in UK stocks at the moment and as you've mentioned before, a successful roll out of the vaccine could be a real game changer. I grapple with the real opportunity that exists here with the backdrop of a US economy that seems heavily over extended and could snap at any point. And as we know, a sharp correction in the US is likely to lead to a disproportionate reaction in the UK.
So my question / call for advice to you and other investors is how best to position a portfolio when the UK upside appears significant but is countered by a macro picture which could be significant on the downside? I'm caught between wanting to fully commit to the investment opportunity while all the while feeling a sense of trepidation with what's developing in the States.
Apologies for the waffle and also if this has veered off track..
Here is my view. Personally I think markets are very extended at the moment. Japan is at a 30 year high, the US moves to record highs almost daily. More stocks are on a PE of 100 than in history, Tesla is on a PE of about 800. Almost every market indicator is screaming a warning signal. Unemployment is moving higher again in the US yet markets still move higher and higher. Retail sales figures released today were poor with even internet sales down 5.8% although well up on the year of course.
Can it continue? It might for a good while. Government's are still pouring money into the economy at an extraordinary rate.
Who wants to be out of a raging bull market? Even my neighbor has asked for help in setting up a broker account and he has never been interested before. The "Robin Hood" generation are talking in the press of huge winnings and no-one wants to be out.
The vaccine looks promising but what if it does not work against a new variant? Will we have to get a second or third jab? The R rate is still well above 1 it seems.
So I remain invested but I am a net seller. My biggest position is major oil company Bp (LON:BP.) Never invested in that stock before strangely but I happily joined the "BP below £2" club. Now nearly 60% higher it is no longer the value it was just weeks ago. I have sliced many small cap stocks. I have done very well on buying bitcoin via miner Argo Blockchain (LON:ARB) I topped up at just over 6p last October; it hit 140p last week. Just evidence of a crazy bubble in my view as novice buyers chase some hyped twitter stocks to incredible levels with almost no thought of company market caps. £300 million here, £500 million there with balance sheets showing negative assets in some instances. Of course it hardly matters if you can sell the stock at a higher price a few hours latter.
These markets are great fun and week days seem to fly past in this lock down but I know it cannot last for ever.
Peter,
I agree with everything you say but would add the following:
How will the economy reopen, especially the Hospitality Trade ? A lot slower than a lot of investors would like i think.
We all know there is a huge amount of Pent Up demand out there for all sorts of products and services, when the economy does reopen this demand will not be satisified initially and could lead to inflation which will cause problems.
Have a great weekend !!
I can't personally speak for how fast (other) investors would like the restart to be, but I do sense that it will be a lot slower than the ending of lockdown's 1 & 2. I will pleased if so as I think another start / stop would be disastrous for some businesses, particularly in hospitality.
I do sense that there have been (some) lessons learned (to some degree) and that care will be taken to try to ensure that this is the last lockdown.
As I mentioned earlier in the week I am convinced that schools will reopen after the half-term. Over the next couple of weeks I expect us to see case numbers fall quite markedly and this will feed through to a reduction in stress on NHS capacity by the middle of Feb.
I am sure that this will create a clamour for the restarting of other elements of the economy at the same time - the prize is a sustainable resumption towards normality from the spring into the summer.
The fact that the UK is ahead of the global curve in terms of vaccination roll out, I think reduces one of the pressures to open too quickly. Namely there probably won't be other European countries re-opening before us - or if they do they will be a more reliable canary in the coal mine.
On inflation, I don't think I agree with you :
Consumer related stocks (that relate in some way to consumers being out of the house) is going to be a volatile space I expect - so I think attention to detail and staying on top of the news/trends will be key for investors brave enough to play here.
Japan isn't extended in my view. It is only just breaking out of a multi-year base formation. It is well below its long term high. The currency is appreciating against the dollar. A bull market may just be beginning. I think it could be a good buy. As I said in an earlier comment today, different opinions make a market.
I don't think the US will go into a bear market until there is clear evidence of interest rates increasing. They will do all they can to try to avoid this although there are small increases now. The interest liability on their debt would be so significant. It has already been suggested that rises in inflation to over 2% nor decreases in unemployment will encourage them to do otherwise at the present time.
I agree with your post in almost every detail Jock. The UK market not only looks good value - it now has a catalyst for growth.
There are four factors in my opinion that could knock it off and lead to another correction. The scariest is probably a general crash in the US.
What would cause this? Well, the bubble there is being caused by effective negative interest rates driving vast amounts of money into the markets. This will change if interest rates rise. Inflation expectations are what determines that so I judge it’s fairly safe to invest as long as I don’t see inflation starting to tick up. This is one of things where I think you will have time to react if you see it moving. Just keep an eye on it.
It's interesting that both N Brown (LON:BWNG) and Klarna both offer buy now, pay later models in ecommerce. Yet N Brown is heavily regulated but Klarna is not!
Surely existential threat to N Brown? As more fashion companies offer buy now pay later then customers who need it will have a choice of brands, not just N Brown?
It's interesting that both N Brown (LON:BWNG) and Klarna both offer buy now, pay later models in ecommerce. Yet N Brown is heavily regulated but Klarna is not !
Worth noting
In September 2020, the FCA Board asked Christopher Woolard to review change and innovation in the unsecured credit market and to report to them in early 2021. The review will concentrate on how regulation can better support a healthy unsecured lending market.
I recently saw an extended zoom run by Centre for the Study of Financial Innovation where Mr Woolard was specifically asked about this point. Unsurprisingly, he kept his cards close to his chest about what will be done in the Woolard Review - but Klara et al are clearly on his radar.!
Mood music seemed to be recommendations for slightly less prescriptive regulation but wider 'do no harm' obligation forced on everyone issuing credit (ie if if looks like credit, it is credit!) with loan costs communicated in £/pence vs APRs
I hold a lot of Morses Club (LON:MCL) (good) Non-standard Finance (LON:NSF) (bad) and so following closely !
But until that becomes regulation.... Klarna is going to run riot, be able to offer attractive credit deals to customers, be able to say what they want in marketing etc...
While N Brown is stuck with the compliance overheads of adhering to lending regulations, having to hold adequate capital (therefore lowering ROCE), and with a perpetual risk of mis-selling and misconduct fines if they ever cross the line (on purpose or even on accident).
Hard competing in an un-even playing field.
I hope this post will cause a healthy debate and if it is inappropriate here, I am happy to post it somewhere else.
In the last couple of days we have seen trading statements of companies popular in this blog, namely Boohoo (LON:BOO) , Xaar (LON:XAR) , N Brown (LON:BWNG) that somehow caused their respective shareprice to fall, considerably in Xaar’s case. Here is the question: are the respective trading statements definable as Profit Warnings? If not, what really defines a Profit Warning?
(I hold BooHoo, I am watching closely N-Brown but not bought yet)
In my opinion, I don't consider them to be profit warnings, as they seem to be inline or above forecasts but were below market expectations, Xaar (LON:XAR) they were expecting more progress. You can also add Games Workshop (LON:GAW) which was inline but the shares have fallen, previously they often beat the forecasts by some margin.
Profit warning is when results will not meet forecasts.
Were they profit warnings & how defined?
It's a profit warning if profits are going to be less than expectations (broker consensus forecast usually).
Boohoo (LON:BOO) (I hold) - certainly not a profit warning, as they exceeded guidance on revenues, met guidance on EBITDA margin, and brokers have increased earnings forecasts since. No guidance yet for next year, as too much uncertainty, will be given in next update.
N Brown (LON:BWNG) - is in line with expectations, so not a profit warning either.
Xaar (LON:XAR) - not sure.
It's not worth agonising over why share prices do this or that, why are people so obsessed with short-term day-to-day changes? The market price is not an accurate valuation of any company. It's just the equilibrium price between buyers & sellers at any specific point in time, and is subject to go absolutely anywhere based on sentiment - look at the extremes of valuation we've seen in the last year alone!
There are large numbers of people in the market who may be buying or selling for any number of reasons. Who cares?
Regards, Paul.
thanks herbie47 and Paul, I agree with both of you that these were not profit warnings per se. If they were, I would be worried as they tend to have a negative medium to long term impact on the share price, and sometimes they come in threes too...
Tricky the relationship between forecasts vs estimates that you mentioned, and the impact on shareprices. Actually I think there are three levels (or types) of forecasts/estimates: company guidance forecasts, brokers consensus forecasts and market expectations (psychology). The three are almost never aligned.
in the case of Boohoo (LON:BOO) I think the results announced yesterday were partially in line and partially exceeding company guidance forecasting, fell slightly short of brokers consensus (Stocko graph updated down a notch last night) and definitely fell short of market expectations.
Paul, any thoughts on the continued #BOO sell off?
No, Boohoo (LON:BOO) is just a volatile stock. I don't pay any attention to short term market gyrations in price, it's background noise only. People can buy/sell for any number of reasons, personal to themselves. I'm happy to buy when people are selling irrationally. It works very well indeed with this particular share - just look at the chart.
There are different opinions which is what makes a market. Also, different time frames from day trading to long term. There were over 19,000 trades in this on results day and very significant numbers in the days before. In other words a lot of punters going long or short and those who bought last month or the day before the results will in many cases be moving on to something else.
Boohoo (LON:BOO)
1. Some holders who decided to sell because of the supply chain issues didn't sell out completely as the SP fell and waited for the anticipated positive announcement.
2. Some traders who bought when the SP fell are cashing in and moving on.
3. Market falling; weak holders selling this one because of high PE.
4. Much lower SP seen recently; potential buyers happy to wait to see what happens this time.
5. The update wasn't vastly better than expected. Especially after the ASOS (LON:ASC) results.
6. Some holders expected more? Seems unlikely as a cause.
No shortage of possibilities. I'm sure there are plenty of others.
Boohoo (LON:BOO) has a volatility of 68.48% (click on 'Full Quote' below the share price to reveal the share price volatility). This equates to a potential price swing of about +/- 4.3% on any particular/normal trading day. Today the price was down by -3.7% so the price drop is within normal perimeters.
Hi Logical David, thanks for sharing this, I never knew about the volatility on full quote, I do have one daft question, please could you let me know using your example above how a volatility of 68.48% equates to +/- 4.3%, apologies if it's simple, but I just don't get it :-)
Many thanks
Steve
Hi Steve W,
There are approximately 255 trading days in a year. The square root of 255 is 15.97 . For simplicity, lets call it 256 days. The square root of 256 is 16. When you divide 68.48% by 16 it gives you 4.28% and when you round up 4.28% to one decimal place it becomes 4.3%.
The reason why you divide a share price volatility by the square root of the number of trading days per year is due to some complex advance mathematics (which seems to like using square roots) but by just dividing the volatility% by 16 in your head this gives you a guide as to how much a share price could potentially move on a normal day.
If you were to look at Novacyt Sa (LON:NCYT) , it has a whopping volatility of 166.02%. Ouch!! Hence, when you divide 166.02% by 16 it gives you a whopping potential price variation of +/-10.4% on any normal trading day, bar a market crash of course. Hence, the reason why Novacyt Sa (LON:NCYT) is classed as 'Highly Speculative' and moved +5.1% today which is well within its expected daily movement. So hopefully you can now see why Boohoo (LON:BOO) is classed as 'Speculative'.
NB: There is no such thing as asking a Daft question. The only Daft question is the one that isn't asked!!
David.
Hi Logical David
That's brilliant, thank you, every day is a school day!
Really appreciate the explanation will add a formula to my spreadsheet for ease
Steve
Novacyt SA (LON:NCYT) shares have gone up from 15p to over 1000p in the last year, so it’s not surprising that the volatility is high but I wonder what it is over the last month? I would expect that it is lower, I don’t think 10% movements are the average anymore.
Something to do with Standard Deviation?
Probably is "something to do with SD" IGP.
The real issue, I suspect, though is that Stockopedia's (and I'm guessing the wider market's) definition of volatility favours arithmetic over reason.
If a stock makes some big daily moves during an uptrend (or during a downtrend) then those big moves mark it out as "volatile". However it may not have varied much at all from the "trendline" and may not "wobble" much at all.
Personally I only judge true volatility these days "by inspection" although that is leading me to an hypothesis that there might be a meaningful mechanical metric for true volatility.
Work in progress.
Great news for SMEs -
From Guardian
"Tens of thousands of small businesses will receive insurance payouts covering losses from the first national lockdown, following a court ruling."
The Supreme Court found in favour of small firms receiving payments from business interruption insurance policies.
Re Hiscox (LON:HSX) - and other insurers. Supreme Court hands down decision re company cancellation policies and whether they covered disruption caused by covid.
https://www.bbc.co.uk/news/business-55661702?at_custom4=B1925068-5719-11EB-9D28-2C640EDC252D&at_custom2=twitter&at_campaign=64&at_custom3=%40BBCBusiness&at_medium=custom7&at_custom1=%5Bpost+type%5D
Doesn't seem to have done Hiscox (LON:HSX) much harm - currently up 3%
Hilton Food (LON:HFG)
I hold. They are down 11% today. Trading update yesterday was broadly positive albeit sadly wafer thin on actual numbers and it lifted the price. Today we have a placing of c10% of the shares which has to be either Aberdeen or Fidelity. As a humble and relatively inexperienced PI should I follow the smart money or is this a buying opportunity?
Hi Millbank, cannot find the news of the placing on investegate, advfn or sharepad, where did you see it please?
It is in the news on here: https://www.stockopedia.com/share-prices/hilton-food-LON:HFG/news/brief-hilton-food-group-secondary-abb-bookrunner-says-deal-size-81-mln-shares-c99-isc-offer-price-1050-1100-per-share-urn:newsml:reuters.com:20210114:nFWN2JP0M2/
Also here: https://www.sharecast.com/news...
thank you herbie. i remain confused as to why it was not rns'd
Probably only just happening, there will be a RNS after the change.
Sorry did not respond. Perplexed and exasperated at how difficult this game is. I will continue to hold as I think it will come back on the funadmentals but left with a nagging doubt now about what the motive behind the sale was.
millbank - it's fine thank you (and to herbie for showing me where the news was!). i bought on the drop on no apparent news as it was on my watchlist with it's long up-trend
Agree. Topped up
I don't hold Hilton Food (LON:HFG), I did some years ago and the shares have done well but the margins are too low for me. I wonder if Brexit may affect their costs?
.
Clipper Logistics (LON:CLG) - I wasn't sure whether to comment on this first thing as not sure still a "small cap".
The last time this happened was in Jan 2018, the directors dumped 8.8 million shares. The price drifted lower over the next few months and took what felt like forever to recover back to the price the directors sold. Thus I decided last night I would offload my entire position at the open and I did. I was happy to get more than the 565 but note if I'd waited I'd probably have got a couple of pence more.
Having made 60% on these in less than 12 months I'm happy, and will look at what the price is doing in April / May and judge whether to buy back in. Good luck to those hanging on (I mean that genuinely, I hope for their sakes it holds the ~£6 level or higher :) ).
Hi Paul,
Thought you were not going to comment on LON:FIF and LON:CARD (I hold) when they had updates yesterday but weren't on your list - so much appreciated that you've done so today. I know RIS tends to come in bursts so IMO waiting a day or so for your thoughts is much preferable to no comment.
On that topic, if you ever have a quiet RIS day, I would like to hear your views on LON:STOB. It was listed as to be discussed on an SCVR a while back but got dropped as you had a full day and if "looked complicated".
Just added Card Factory (LON:CARD) to Multibaggers with 10 Bagger Potential - CARD FACTORY
The link is provided below.
https://www.stockopedia.com/co...
DYOR
BSV
I do agree with your comcern. Time for many of us is scarce and it now taking an increasing amount of time to wade through many of the entries to find comments on individual shares which, after all, is what SCVR is all about.
VIDEO; Loved your Video Paul - why don't you do some investment-related ones?
We've just posted another piworld interview, with Ben McKeown, Investment Director, Dowgate Capital. Ben discusses how he manages money at Dowgate, where he looks to generate 20% pa. We learn some of their investing criteria, and where he sees their current opportunities. He discusses Alpha Fx (LON:AFX) Thg (LON:THG) & On The Beach (LON:OTB) Video & Podcast.
Separately, at 1.15pm today (15.1.21) there is an Investor Presentation with Q&A by Accrol Group (LON:ACRL) This follows their interim results that were announced on Tuesday which showed strong cash generation, with reduced net debt. FY21 at least in line with expectations. They restore the dividend.
Presenting: Dan Wright, Executive Chairman, Gareth Jenkins, CEO & Graham Cox, MD Tissue Division, who will present followed by Q&A. Register here.
If there's time it would be great to get a view on yesterday's update from Polar Capital Holdings (LON:POLR)
Might be a job for Jack since he knows it well and it's owned by his club. I think they bought at about £6 and now it's nearly £7, so does he still see value (I do, but realise that to a large extent it is aligned to markets in general, and tech in particular, continuing to do well)
Paul relevant to your eclectic comment re facemasks. I bought one of these graphene masks and have to say it is great. http://www.versarien.com/mask no misting at all. Bit more expensive than your tape though. I am hoping the shares will sort that out.
Thanks for the tip but Versarien appear to have supply problems at the moment. I clicked on the versarien link, but it looks like it's currently sold out.
Deleted and moved to the right place....
Hi Paul,
Another tip that you may want to use to stop your glasses steaming up is to apply a small drop of washing-up liquid to the inside lens of your glasses. Rub until lens is completely dry and that will also solve the Problem. Used it all the time on Crash helmet visors during riot training in a past life.
Didn't know that you were an ex-scout leader :)
I wander if the powers that could be could simply split the chat section into two tabs - similar to the tabs for swapping between portfolio's in the daily news section.
One tab would be for individual stock specific discussions with zero tolerance policy for anything else being posted there and another tab for everything else.
Would that keep all the punters happy?
As Paul mentioned, this is one effect of increasing scale.
The definition of 'relevant' is subjective.
For example some here think commentary on vaccines is relevant, and some do not.
This problem is common to all comment sections that have more than 2 posters
Answers range from
Pre-moderation of posts by - in theregister, this is done for reports on some court cases
to
Member based moderation - in slashdot some users have the ability to vote a comment up/down and assign a type (interesting / humorous / troll etc) and readers can filter out based con category / score
to
free for all - where we are
Trying to work my way towards something relevant, this seems to be a thing on the internet that is fairly common but has no good solution: balancing the demand of a large audience.against a limited supply (of relevant articles)
This (imo) is why Naked wines had to merge with Majestic - they used to sell parcels of 500 cases of wine. When that sold out over a day or so, most who wanted that wine got it and were happy.
When that sold out over a minute or so, most who wanted that wine did not get it and were not happy.
If you see a small company that has this 'feature' in their operating model, you do need to be aware of its limits to scaling up.
Hi Paul,
Strange reaction at XAR but the £20m cash is actually 'net cash' (well it was at the interims) and they son;t have debt. Rhey also have other assets and are likely to get another £25m from the dale of the remaining 55% of the 3D business to Stratasys.
It would also seem that forecasts have risen yesterday according to Stokpedia.
just £100m mkt cap this am
sorry for the typo's working in bad light on a laptop first thing!
Credit Suisse raise price target for Boohoo (LON:BOO) from 300 to 350, that's brave of them saying it's 351 even following yesterday's drop.
Liberum raises £BOO to 380 from 350 - Hold
Boohoo (LON:BOO)
Liberum were big bulls of Boohoo and have now become reactive. Their main concerns relate to ongoing ESG fallout and the cost of fixing the supply chain problems. Hardly new issues which Paul and several posters have commented on at length.
With regards to £SAGA. I noted that both Investec and Numis have cruises resuming end H1/start H2. Numis who are the brokers have circa 62p of earnings pencilled in for 2023 so a p/e of roughly 4x.
Clearly, they are the brokers so there may be an element of bias especially if there is any hint that Saga may need to raise money again for which Numis would no doubt be handsomely rewarded! . They do state however that they think liquidity is fine and that insurance is pretty much paying for cruises at the moment.
Hi, where have you read this r.e SAGA? Would be interested in reading the broker notes but can’t see anything anywhere?
Thanks
Hi Paul, any thoughts on N Brown trading update today? A recent placement underwritten by the CEO has paid down all debts and leaves a health 83m of net cash on the books (not including their loan book). Trading has continued to recover following Covid and they seem to have a much better handle on marketing spend it would appear. Not as racy as BOO but seems like terrific value as a Covid recovery play with nice growth prospects.
Yes, I'll be looking at N Brown (LON:BWNG) next. Section should be up by about 10:30 today.
N Brown (LON:BWNG), Trading update for the 18 weeks to 2nd Jan 2021 announced this morning. Bit of a mixed bag.
??? N Brown (LON:BWNG) looked absolutely fine to me. £85m EBITDA forecast for 2021
remember Net debt of £315m is offset by the debtor book (ie those who are paying on instalments) of £663m so their debt is more than twice covered by performing assets even at 7% default rates.
Based on default rate they have an effective net asset of £300m and are a digital business that will generate £85m EBITDA with a market cap of £340m.......that looks like the wrong price to me.
I'm in agreement, FY expectations of circa 45-50m PBT in what has been a difficult year with debt cleared and significant cash in the bank .The board underwriting recent placing was a huge tick in the box as well. I think it's easy to sideline BWNG vs the likes of BOO and ASOS, less sexy, more value operating in growing niches in my opinion. Let's see if they can deliver on growth plans moving forward.
N Brown (LON:BWNG) is really a finance company. It doesn't make any money selling product, it's more a device to charge for credit.
hmm not sure that's true anymore Paul though clearly does still have a large element of finance. Same is true of Next though but obviously on a bigger scale. Their debtor book is what £3bn+ ?
I've never been able to locate the % of customers who pay via credit. I've emailed BWNG and will report back once confirmed.
The trading update says that they are trading in line with expectations. I take that to mean that they will achieve an EPS of 9p for the full year to the end of Feb 2021. They sold all their stores in 2018 and this is now an online only business. They have eliminated all their expensive unsecured debts. They have made major investments in their IT systems to rationalize and integrate them. This is a late stage turnaround scenario,
My morning smallcap tweet:
Inland Homes (LON:INL) Gabelli Value Plus + Trust (LON:GVP) Hammerson (LON:HMSO) LSL Property Services (LON:LSL) GYM (LON:GYM) Eurocell (LON:ECEL) Osirium Technologies (LON:OSI) Innovaderma (LON:IDP) Allied Minds (LON:ALM), Shield Therapeutics (LON:STX), N Brown (LON:BWNG)
Inland Homes (INL) Hillingdon Gardens planning (514 homes) won't be called in by the Secretary of State. [SP=58.5 Cap=134m]
Gabelli Value Plus+ Trust (GVP) intends to propose members' voluntary liquidation and, as an alternative, a Tender Offer. [SP=143 Cap=141m]
Hammerson (HMSO) CFO resigns, will stay until replaced. He is thanked. [SP=23.29 Cap=945m]
LSL Property (LSL) guides FY(Dec) down 15% after 'very strong' Dec rev up 12%. Guides U/L op profit c. £41.5m before covid related net costs and including covid Job Retention Scheme. [SP=255 Cap=268m]
Gym Group (GYM) guides FY(Dec) rev down 48% to £80.5m. C/F positive during post-lockdown trading periods with £3.8m of deferred rents outstanding at the end of 2020. Current lockdown cash burn £5m pcm. "We have significant liquidity available...we have started discussions with our lending banks, who continue to be supportive, to review the future covenant tests relating to this facility." [SP=218 Cap=362m]
Eurocell (ECEL) guides FY(Dec) rev down 8% after string finish, U/L pretax ahead of expectations (whose?). [SP=227 Cap=253m]
Osirium Technologies (OSI) guides FY(Dec) rev in line, bookings slightly ahead of market expectations. "Optimistic the momentum seen in the final quarter going into the new financial year will continue." [SP=22.2 Cap=4m]
InnovaDerma (IDP) NED (who is a substantial shareholder) makes secured loan of £500k to July at 5% over LIBOR. He can require early repayment if co raises in excess of £2m through debt or equity issuance. [SP=55 Cap=8m]
Minds (ALM) CEO resigns but will continue to support the Group as CFO pending replacement. He is thanked. [SP=NA Cap=NA]
In line: Shield Therapeutics (LON:STX) N Brown (LON:BWNG)
I’m not based in the UK, so usually get round to reading these reports PM/ early AM, UK time.
I have just finished reading Thursday’s report, so as Friday’s is already partly posted, it seems better to post these comments here, than on the previous day’s comment where they won’t be read.
With my comments below in mind, I can see this could be considered hypocritical, as my comments do not relate to today’s report but Thursday’s report.
Also, it might not be my place to say this and I apologise in advance if I offend anyone.
I totally agree with Paul’s comments in Thursday’s report about the amount of dross subscribers are now writing in the comments section.
When I first signed up to Stockopedia, readers’ comments were thoughtful and added value and I looked forward to reading these as much as the report. Now half the comments seem to be off-topic or are simply people bickering and trying to win a fight. Is this now an outlet for lockdown frustrations?
Take Thursday’s comments, even after the foreword from Paul asking people to only post comments that are business related, there was an enormous tit for tat on vaccines.
This is such a shame, as you all have a lot of insight and I enjoy your different takes on company matters. So can I second or third Paul’s request for this to please stop.
I know I don’t comment very much here, but that’s because most of the time I don’t have much to add. But this is all getting soooo boring. (By the way, what’s the record for red flags? As I have a feeling this post might be a contender.)
Glad to second your comments , it now takes ages to scroll past the crap to get to SHARE BASED comment.
irony alert
Yes, I agree, lots of dross, BUT scribers pay and deserve the freedom of speech and be allowed to post.
BSV
At the risk of adding yet another 'nothing post' If the very special nature of this quality site is lost by irrelevant and unnecessary postings it becomes just like all the other sites and there wont be any subscribers Bluesky Ventura.
-52 for what is a valid and fair point of view! Are we descending into mob rule? For me the value of this board is informed discourse politiely and respectfully conducted. None of the discussions here have bothered me except where they have become bad tempered. I think we all need to chillout a little.
If this continues the high quality posters here will stop posting. I was wary of posting here because the quality was awesome and I didn’t want to risk posting something foolish. That quality made this comments section a must read. Now I can’t be bothered scrolling through all the dross. Remember, as Paul has pointed out this section is read by thousands. Does that include some of the Companies themselves, and financial journalists and perhaps some Fund Managers too?
This problem could be the result of a lot of newer subscribers to Stockopedia whose previous experience of posting is on sites like ADVFN where anything goes, who haven’t realised that what is OK there isn’t here. I hope there’s a way to stop it as Paul’s appeal yesterday fell on deaf ears, That’s disrespectful to him. What’s the point of Paul and Jack writing about shares in such quality detail if the posts here often ignore all of them? Obviously that doesn’t mean no off topic posts at all and Paul himself goes off topic, but all things in moderation, and with main focus on the shares updating that Paul and Jack analyse and comment on.
I realise this post adds to the dross and off topic posts (and risks yet more today) that many of us don’t want to read, but unless it is stopped now then it will go from bad to worse. Tighter regulation and quick removal of off topic posts might be needed, at least until it is under control.
I don't think we should blame the newbies. I really don't think the quality of the site is any worst or better than before. I actually think it's improved. I'm ok with every post even if it is dross, as long as it's not sexist, racist, or phobic in any way.
BSV
I agree we need to chill out a bit. Times are difficult for a huge number of people. Let’s keep our spats on here in perspective.
Steamed up glasses, vaccines, viruses, lockdown strategies, dog health, cars, someone’s ramble about how they traded a stock, a recount of drunken ramble finding somewhere for a slash behind a beach hut, shares that aren’t small caps and so on and so on. Don’t worry if some of it, or even none of it interests you; it will all have moved on to something else after a relatively short time.
And now for something completely different.....
Clipper Logistics (LON:CLG) chairman’s sell down via a secondary placing. I agree with Paul’s comments. The only thing that I would add though is that at this particular time there is a lot of talk about potential changes to the tax regime (CGT, entrepreneurs’ relief, etc.) and, while it is unlikely to be mentioned explicitly in the RNS, we may well see quite a number of these sells as people are worried about tax increases. So, reading between the lines ‘estate planning’ may be code for ‘I’m doing this in case the CGT rate goes up’.
Ooo I am not sure that subscribing to Stocko allows posters to post anything that is not in line with the purpose of this report. Bit anarchical ??
Nothing more constructive to add so I won't !
Smell the coffee and scroll on.
Take Thursday’s comments, even after the foreword from Paul asking people to only post comments that are business related, there was an enormous tit for tat on vaccines.
Well, it really depends on what the rules are and it then relies on the author following them.
Given that Paul has repeatedly commented on the importance of understanding the vaccine rollout - e.g. only on Tuesday he posted a long section on "Covid vaccination thoughts" - I think posters - obviously including myself, might be forgiven for thinking that understanding how the vaccination program will work and how long it will be needed for are on-topic for the board.
Personally, I'm happy either way as long as the rules are clear. But as soon as the author of the SCVR goes off-piste we can be fairly sure the rest of the board will follow.
timarr
Great point Timarr, I always find your post well thought out and relevant.
BSV
Well, it really depends on what the rules are
I sincerely hope it doesn't - if it becomes matter of "rules", then I think the comments section will have completely lost it's value.
I personally think the moaning will pass once people can think of something better to exercise their minds.
You'll no doubt recall timarr, that such outbreaks of unrest were a periodic feature of this boards spiritual predecessor over on the Motley Fool. Such outbreaks seemed to be linked to periods of market uncertainty, so perhaps the current discussions are a subliminal indicator of market mood?
Personally I think that understanding the virus, the vaccine and most particularly the potential course and timing of return to normality are vital investment topics at this time. Certainly some the discussions veer too far towards the science (and I'm a least a guiltily of that as anyone) . For those not interested there is no compulsion to read every comment in full.
Oftentimes there will be companies covered that are of no interest to me, but which attracting excruciatingly detailed (from my point of view) and lengthy comment. I have problem with that content being there, I'll just click on.