Small Cap Value Report (Fri 15 June 2018) - REC, NXR, BPM, GYM, BWNG

Morning!
Yesterday was a fun day out at Mello South, as expected. I was too busy to attend the morning sessions, as I was preparing notes on Revolution Bars (LON:RBG) for my own presentation. But I was pleased to attend the afternoon sessions from Titon Holdings (LON:TON) and Non-Standard Finance (LON:NSF), and in particular very happy to hear the presentation by actuary, investor and author Guy Thomas.
Guy's book Free Capital was inspirational to many of us in the investor community. It had a big impact on me, too. It showed that a determined individual, if they put their mind to it, could succeed in the stock market. Furthermore, it showed that there was no single path to success. While successful investors may have certain traits in common, their "edge" tends to be unique to them.
Guy gave a strong presentation on a new topic: fund manager selection. This is more commonly discussed among professionals in wealth management than among the typical private investor who is interested in picking their own stocks. But in the field of finance it is a key issue, and one which has been relevant to my own career. So it was terrific to hear the considered thoughts of Guy Thomas on the matter.
Many other strong presentations were given - too many to mention them all here. Equally as important, however, was the chance to network and to put faces to names. Well done to all concerned.
Right, time for some stock analysis.
Due to the business of the week, I've not covered quite as many I hoped by now.
For today, I'd like to cover:
- Record (LON:REC) - final results (I hold this one)
Stocks with news this week I haven't covered yet:
- Norcros (LON:NXR)
- B.P. Marsh & Partners (LON:BPM)
- GYM (LON:GYM)
- N Brown (LON:BWNG)
Quick personal note on my own portfolio: I've been nibbling up some more shares in Ranger Direct Lending Fund (LON:RDL). I've realised that this is ok since it should be properly categorised as a fixed income-type of investment, not an equity investment.
While it's far riskier than cash, it's not giving me all that much more additional exposure to equity risk. So buying it doesn't break my own internal rules about having too much equity exposure at this point in time.
Also, while RDL does expose me to GBPUSD fluctuations, the recently strengthening dollar has, I believe, helped to widen the NAV discount by another few percentage points.
Perhaps the general point to make is that we shouldn't forget the role that fixed income instruments can play in our portfolios. It's all too easy to forget the opportunities in this asset class, especially when interest rates are so low. Let's not forget the wise words of Andrew Mellon: gentlemen prefer bonds.
Record (LON:REC)
- Share price: 45.55p (-2.3%)
- No. of shares: 199 million
- Market cap: £91 million
(Please note that I own shares in REC.)
This has some surface-level similarities with Park (LON:PKG), which I also own. They are both niche financial stocks, which I think I understand reasonably well, and have really strong balance sheets, but aren't growing very fast.
Record is a specialist asset manager providing currency management services: hedging products and return-oriented products.
Nobody is going to get too excited by these results. But I'm satisfied with them.
Key points:
- PBT down, but EPS up (because of the share buy-back last year).
- Lower share count allows for 10% increase in the full-year dividend
- Special dividend to bring the full-year dividend to 2.8p (versus EPS of 3.03p, i.e. a 92% payout ratio). Historic yield including the special dividend is c. 6%.
Operationally:
- Net outflows of $1.6 billion from Assets under Management Equivalent (AUME). Dynamic Hedging continues to lose ground. Currency for Return experiencing small net inflows.
- AUME increases 7% in USD terms thanks to exchange rate and other market movements. Down 5% in GBP terms.
...largely attributable to the 11% growth in personnel costs due to continued investment in additional headcount in order to maintain innovation and enhancement of our services
Balance sheet equity has reduced from £37 million to £26.6 million, thanks to the share buybacks. ROE should therefore improve, assuming stable performance, thanks to this more efficient balance sheet. Stocko currently calculates Record's ROE to be 22%.
The company is facing into a period of some earnings uncertainty as it switches to a more performance-based fee structure on its Passive Hedging product (responsible for about half of all management fees in 2018).
Performance fees on this product "over time are expected to match or exceed foregone management fees". Whether or not this turns out to be the case is a key question.
I am planning to continue holding a stake in this one. Founder and Chairman Neil Record has a 31% shareholding, and my overall impression of his stewardship and of the company as a whole is that they are extremely disciplined. So I think this makes for a nice hold.
Incidentally, it might share a nice feature with another stock which I hold, IG Group (LON:IGG). IG benefits from financial market volatility, as volatility tends to stimulate trading activity.
In the same way, volatility in the currency markets may help to stimulate new client activity for Record. As it says in today's outlook statement:
"...financial markets, including foreign exchange markets, will continue to be impacted by ongoing geopolitical developments and instability.
Such developments provide opportunities for the Group to engage with both current and prospective clients, and to use our innovative and flexible approach in tailoring our products to meet specific client objectives."
So if the macro environment becomes more uncertain, this may prove beneficial for Record.
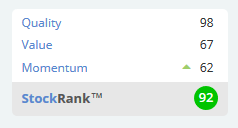
Stocko algorithms are very impressed, particularly by its Quality:
Norcros (LON:NXR)
- Share price: 225.5p (+1%)
- No. of shares: 80 million
- Market cap: £181 million
On April 11, Paul wrote:
Maybe this share might suit very patient investors, who might eventually be rewarded with a re-rating;
The share price that day was 182.5p.
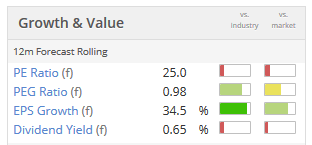
Two months later and the share price has increased by 24%. A nice re-rating, but the shares are still rather cheap-looking:

Momentum is very strong, too. The re-rating is underway.
To recap what this company does:
Norcros is a market leading supplier of high quality and innovative bathroom and kitchen products with operations primarily in the UK and South Africa.
A £59 million acquisition was made in November 2017 - very material relative to the pre-existing group. It made 4-5 months of contribution to these results (for the year ending March 2018).
As usual, I want to find the pace of organic growth rate at constant exchange rates:
Group revenue for the year was £300.1m, 10.7% higher than the prior year on a reported basis, 8.6% higher on a constant currency basis and 4.4% higher on a like for like constant currency basis.
4.4% is the answer.
Actual sales growth, with the help of the acquisition and exchange rates, is 10.7%.
Strategy
I covered this stock a year ago, and was turned off by its acquisition strategy and complicated accounts.
In particular, I didn't like the fact that it set such huge sales targets. I like profit targets and especially ROCE targets, not aggressive sales targets.
Norcros has failed to reach its 2018 sales target of £420 million, set in 2013.
Actual revenue is £300 million, far short of the target and it would be very short even if GBPZAR (the South African rand exchange rate) was unchanged compared to 2013.
Ironically, I would view this as a blessing in disguise, as it means that acquisition activity was more moderate than planned.
The new strategic objectives are as follows:
- We aim to grow revenue to £600m by 2023 (previously £420m by 2018);
- Maintain approximately 50% of Group revenue derived outside the UK (no change); and
- Deliver an improved and sustainable ROCE of over 15% (previously a 12-15% range) through the economic cycle.
Doubling revenue over the next five years is not as dramatic as it sounds. A compound growth rate of 15% p.a. would be enough. So hopefully the acquisition activity will be moderate over the next five years, too.
Note that Norcros also has a return on capital employed target of over 15% - that's a very positive sign. It has recently been achieving ROCE (using its own measurement approach) of about 18%, better than its strategic objective set in 2013.
Something that's probably not a coincidence is that Norcros fell very short of beating its sales target, but was ahead of target in terms of ROCE. It made better-than-expected use of existing assets, perhaps because it didn't expand its asset base as much as originally planned.
Balance sheet
The balance sheet is now carrying £47 million of net debt. This looks manageable, relative to operating profit of £20 million.
However, note that not all of this operating profit translates to free cash flow. There has been about £8 million in capex during each of the past two financial years.
The company has also been paying £2.5 million each year into its pension deficit (these payments are about to be renegotiated).
The ongoing acquisition strategy will also bring with it plenty of exceptional and one-off cash costs.
So I think there are a lot of demands on the company's cash, and so I don't see the debt levels reducing very much.
My opinion
Probably quite a cheap stock, even taking into account the re-rating over the past few days.
I'm not overly impressed by the like-for-like rate of sales growth at constant exchange rates, and tend to stay away from companies seeking to grow rapidly via acquisition. I'm also not sure if ROCE is quite as good as the company claims, as there are a lot of adjustments in the calculation.
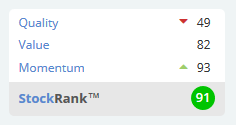
But overall, the outlook for shareholders appears favourable from the current share price. StockRanks agree:
B.P. Marsh & Partners (LON:BPM)
- Share price: 281p (unchanged today)
- No. of shares: 29 million
- Market cap: £82 million
I missed covering this on Tuesday.
B.P. Marsh & Partners Plc (AIM: BPM), the niche venture capital provider to early stage financial services businesses, announces its audited Group final results for the year to 31 January 2018.
This investment vehicle produced a huge return for shareholders in the financial year. The total return is 25.5% (a small portion of which was distributed as a dividend). Nearly all of the gains arose from revaluation of the existing portfolio.
New additions to the portfolio during the year included stakes in both Lloyd's brokers and US-based insurance brokers.
Outlook statement is confident. BPM management think that it is well-placed to deal with further Brexit uncertainty.
The Group's model of making equity investments in financial services intermediary businesses with a partnership approach and a long-term view continues to deliver attractive opportunities.
Definitely worth noting that its track record is top-notch over a very long period of time. It has significantly outperformed the equity market as a whole.
The directors note that the Group has delivered an annual compound growth rate of 12.0% in Group net asset value after running costs, realisations, losses, distributions and corporation tax since 1990.
Placing and open offer - BPM is also raising £15.5 million in a Placing, and up to £1.5 million in an open offer..
The Directors intend to use the net proceeds of the Placing and Open Offer received by the Company to grow the Company's existing portfolio as well as to continue investing in early stage financial services intermediary businesses with the aim of becoming the capital provider of choice for the sector.
My opinion - I think BPM's achievements justify it being given more capital to grow.
One strange feature of the deal is the issue price for the placing: 252p. It's nearly a 26% discount to the most recently reported NAV.
Management only a few months ago said that they might buy back shares whenever shares traded at a more than 20% discount to NAV. So it seems rather odd to be willing to sell shares at a level where actually buying them back instead would create value for shareholders.
The Executive Chairman, after whom the vehicle is named, is reducing his stake but will continue to own the majority of the company. He is 76. Key man risk may explain why this continues to trade below NAV.
Indeed, that factor gives me some doubts as to whether I should want to invest in this. At least the BPM board looks very strong, so the risk might not be as severe as it first appears. Readers who have studied this over a longer period of time might be able to make a firmer guess as to what the future has in store.
GYM (LON:GYM)
- Share price: 282.5p (+7%)
- No. of shares: 128 million
- Market cap: £362 million
Trading Statement & Acquisition
This low-cost, 24/7 gym operator continues to do well.
Trading in the first five months of the year is in line with expectations. Members are up 32% year-on-year.
It reiterates expectations for 15-20 new organic site openings this year (starting at 128).
In addition, it is buying 13 gyms from easyGym for up to £24.7 million.
According to healthclubmanagement.co.uk, easyGym is switching to a franchise model, and wants to expand overseas. So it doesn't need to own these sites any more.
I covered GYM last year when it acquired 18 sites from Lifestyle Fitness. The update this week informed us that the conversion of these is sites is going according to plan and "we are seeing strong member uplifts in the sites where the full GYM (LON:GYM) model has been implemented".
I like the business model and I like the way management keeps achieving everything it sets out to do. The valuation is not ridiculous, given how well it is doing.
N Brown (LON:BWNG)
- Share price: 182.4p (-0.2%)
- No. of shares: 284.5 million
- Market cap: £519 million
This is a niche retailer operating through the JD Williams, Simply Be and Jacamo brands, among others.
Big news today for the company:
Given continued very disappointing footfall, and despite significant cost efficiencies being achieved, we are today entering into a consultation with store colleagues to consider closing our 20 stores ahead of lease expiry. In FY18 these stores generated £15m revenue (2% of Group revenue) and an EBITDA loss of £3m.
The 20 stores may end up being closed. Sad news for employees, and it is very important that they are treated fairly.
For investors, this may have read-across to other retailers whose high street presence is already a drag on results or who might wish to transition online at some point in the future. Think French Connection (LON:FCCN).
Results guidance at N Brown is unchanged, except for potential store closing costs (£18 - £22 million, of which approx. half will be cash).
Its brands don't seem to be doing particularly well, except for Simply Be (one of its three "Power Brands"):
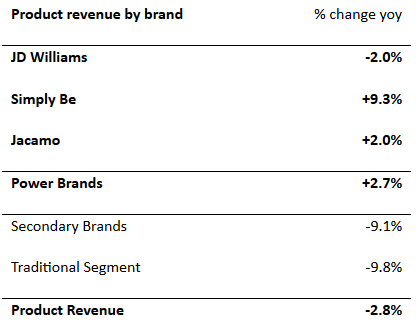
Online revenue is up 3%. Not bad but I think most retailers are doing considerably better than that online.
Revenue from Financial Services (lending to customers) is doing a lot better than product sales, and is up 9% year-on-year.
My opinion
I'm not too familiar with this company's brands, so I'll have to reserve judgement for now on their value and their reputation among customers.
The shares are extremely cheap, and I'm not immediately sure why this is the case. The company had balance sheet equity of £460 million in the most recent results, nearly all of it consisting of retained earnings.
So the shares are priced at only a small premium to book value for a company which is apparently solvent and profitable. Definitely worth looking into. I also recommend the detailed comment #39 in the thread below, from a reader who owns shares in this.
Earnings have admittedly been volatile, but the earnings multiple has collapsed:
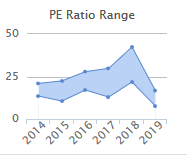
Right, that's me done for this week. Looking forward to watching Spain vs Portugal with assistance from the local Chinese takeaway.
See you next time!
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
the NSF note never got posted on thsi site Graham ? rob collinson
Hi Graham,
Received this in my inbox about 10mins ago...
"Ranger Direct chairman resigns in boardroom exodus"
The chairman and two directors of Ranger Direct Lending (RDL) are to resign as rebel shareholders tighten their grip on the troubled investment company which last week announced it would wind up and return money to investors.
http://citywire.co.uk/investment-trust-insider/news/ranger-direct-chairman-resigns-in-boardroom-exodus/a1129906?ref=investment_trust_insider_latest_news_list
"Old news? I don't follow RDL but you mentioned it above so thought I'd link you the story"
re Ranger Direct Lending Fund (LON:RDL)
Yes, thanks. I spotted that. Didn't want to mention the stock too many times in the SCVR but I viewed that as positive news re: the liquidation.
Graham,
Thanks for promising to circle back to N Brown (LON:BWNG) I wrote to the company this morning more or less as per below.
Since your professional coverage might stimulate some considered responses, here were my thoughts as well. Despite my complaints I actually think there is good value here and once it presents itself as a modern, wholly online fashion company for specialist, under served markets, it will re-rate. Meantime I am optimistic the stationary but very big divi can be maintained, although I expect and want no more than symbolic growth in divis until the debt stops climbing.
Few brief comments on the 14th June 2018 trading statement from a very weary, long term private investor on strategy/progress
1. Decision in principle to close stores
Hurrah.!! At last !!! As a shareholder, I have always felt stores were not part of the company's DNA and complicate an otherwise simple, sexy story - online fashion specialist (with some profitable legacy paper.....until this gets small enough to stop as well). I am frustrated at the waste and another exceptional cost but at least it will then be (finally) done.
2. JDWilliams
This is the critical opportunity. Operating at scale, with still few direct competitors concentrating on the older/middle aged wome - Midsters in your new jargon. (This compares to Simply Be which I feel is doing well but in a now no longer under-served curvy young women segment). I worry on JDWilliams as Creative Agency being changed just 12months after relaunch with a lack of transparency on numbers. Customer numbers are always "up double digits" but net growth is is low due to "drag from Fifty Plus conversion" . Unless FityPlus is doing dreadfully AND still quite big I don't see how it can drag JDWilliams back so much. At the end of the day, net "JDWilliams" revenue is -2% and profit growth seems low. I expect 10% growth pa as online generally grows fast especially I think with middle age women who are now embracing it. Note I fully support the age agnostic, lifestore concept (providing it focuses on fabric fashion not garden furniture!)
3. Secondary / Traditional brands
Similar view to stores. As an outsider they complicate the story and I presume complicate life/dilute mgt focus internally.
i) What long term advantage do you have in garden furniture or electronics vs Amazon if "where fashion fits" is the corporate tagline. Bite the bullet: exit these categories
ii) Figleaves - where is communication of the turnover strategy and results. It should be big enough to warrant separate reporting like a Power brand. If NBrown can't leverage it as a standalone, sell it and focus on the Power brands
iii) House of Bath - missed chance to sell out of group instead of moving its independent headquarters to Manchester to raise cash/simplify(see comment on fashion focus above). If retained, need to focus on fashion related items in the Famous Five - bedding, furnishings etc, not garden tables!!
Cumulatively these secondary/traditional brands are a large chunk of turnover but get glossed over in reporting. No specific figures for turnover by brand. No sense of direction. Now the business is so much clearer after the great brand consolidation work of the last few years, perhaps this can be addressed in the Full Year results presentation. I also commend the work done to improve the Financial Services side but this only fires if the fashion side gets customers.
4. International - USA
i) USA - Perennially disappointing with a real focused effort always 6 months away. Capital markets day 2014 spoke of $100Mn by 2020. Look at the speed with which others are moving here. The opportunity gap for (British) online curvy fashionis closing fast.
Overall, I have liked the direction of the company these last few years: focus & simplification(fewer brands), greater agility (digital) etc. Just still more to do and do it faster, please !
re nxr I notice stockopedia is penciling in a near 50% increase in eps for 2019,
if that comes to pass surely that in itself on the same lowly pe of 7 or so will see the shareprice from
200p to 300 p, pretty good return over a couple of years
mind you eps was 24,7p on 2016 and the share price wasn't above where we are now, perhaps pension deficits are receeding as an issue though ?
K
Norcros (LON:NXR) interview with Nick Kelsall, CEO:
https://www.brrmedia.co.uk/broadcasts-embed/5b1e553202f5e74d0f2da462/event
Regards,
Seadoc
REC, spread >5% wow....
I too look forward to Graham's wise words on B.P. Marsh & Partners (LON:BPM) . I don't currently hold but have been fascinated by this company since meeting the very formidable Bryan Marsh a few times some years ago in my professional career.
TU today from SThree (LON:STHR) looks good, driven by continental Europe. (no position but considering).
As it is really quiet, hopefully people won't mind me mentioning that Bonmarche Holdings (LON:BON) 's FY results are out on Tuesday. Graham covered their last trading update - click on the "Discuss" tab of the stock report to find that and other commentary. I've also gone on about them in comments on a number of occasions, including this comedy moment: https://www.stockopedia.com/content/small-cap-value-report-wed-11-apr-2018-gmd-air-blv-nxr-srt-352043/?page=1#20 - see the reply from Paul.
I'll be looking at a few things in particular in the results: Cash levels, anything about lease cost reductions on renewal and of course an update on current trading. On the last point I feel there is good cause to be optimistic. The last two months retail sales have been good and the weather has continued to be good or very good. It is quite possible that their customers were particularly affected by the earlier wintery weather and so the underlying picture is also not as weak as it appeared.
A few things to note about BON. Obviously it's small, with a market cap of £50m, but it is on the main market so there's stamp duty and no IHT exemption. It is thinly traded, with usually less than 10 trades a day, usually all small and with a market size of only 2000 / £2000. The quoted spread is generally large, but the true spread somewhat better - for example today it is quoted at 97-105 but trades are at 98.65-102.9. These factors may contribute to it being overlooked, and perhaps explain the short-term underperformance against Next (LON:NXT) :). I also have them as XD 4.6p 1st July.
[I have a full-sized position in Bonmarche Holdings (LON:BON) which I will gently trim in the event of a large rise. Furthermore, due to the small market size I might move the market if I dumped them all e.g. on a profit warning.]
Hi Graham,
If you have the time and the inclination please could you look at the N Brown (LON:BWNG) statement from yesterday.
Thanks.
Paul gave a good writeup to Norcros (LON:NXR) on 11th Apr, concluding "Stockopedia really likes it - "Super Stock" style, and very high StockRank. Maybe this share might suit very patient investors, who might eventually be rewarded with a re-rating;"
Results were issued on Weds this week and escaped comment, but revenue was up 10%, proift up 15% and that seems to have stirred the share price into life over the last few days.
Any comments welcomed.
Norcros (LON:NXR) didn't entirely escape comment: https://www.stockopedia.com/content/small-cap-value-report-wed-13-june-2018-mul-ntbr-cnct-cay-373274/?comment=11#11 (also see the reply and earlier comment)
Morning Graham
A further vote for B.P. Marsh & Partners (LON:BPM), time permitting. I hold and will participate in the open offer.
Jonno
Just read through the Prospectus for the placing and open offer on the B.P. Marsh & Partners (LON:BPM) website. Seems like a sensible transaction which gives the Company some 'dry powder' for new investments in partnership with a like-minded investor with international experience. It also has the benefit of allowing Mr Marsh to reduce his holding and perhaps increase liquidity for the shares (although I think the liquidity benefits will be marginal - presumably PSC Group intend to hold on to the placing shares and the shares transferred from Brian Marsh, so the free float will remain roughly the same).
Reading through the risk factors, I was a little spooked by the one titled "No guarantee that the ordinary shares will continue to be traded on AIM". The way I see it, after the placing roughly 44% of the shares will continue to be held by Mr Marsh and roughly 20% will be held by the new (Aussie-listed) investor. Do you think there's a risk that these two dominant shareholders will consider their AIM listing as an avoidable cost and hassle, and take the company private? That would be pretty disastrous for minority shareholders. Unlikely I know, but it did make me stop and think before pushing the "BUY" button.
Could just be a warning that they might move to a full listing...
Hi Graham, if its a fairly quiet day I would be interested to get your thoughts on the recent GYM (LON:GYM) update and acquisition. Looks like the expansion is going to plan so far.
Good call, EI. I will be covering GYM (LON:GYM) today. G
Hi Graham, I'd love to hear your thoughts on Duke Royalty (LON:DUKE) (I mentioned yesterday) if you can fit it in. A new one for you I think and one well suited to your financial expertise.
cheers
Francis
Alpha Real Trust (LON:ARTL) full year results this morning...
highlights :-
"· NAV per ordinary and A share 172.9p: 31 March 2018 (158.9p: 31 March 2017)
· Basic earnings for the year ended 31 March 2018 of 18.5p per ordinary share and of 23.3p per A share (18.6p per ordinary and A share for the year ended 31 March 2017)
· Adjusted earnings for the year ended 31 March 2018 of 3.5p per ordinary and A share (7.4p per ordinary and A share for the year ended 31 March 2017) *
· Declaration of a quarterly dividend of 0.6p per ordinary and A share, expected to be paid on 20 July 2018"
Morning all,
I'll second Record (LON:REC), where I'm also a holder.
Mark
I see today that Revolution Bars (LON:RBG) SR 73 has been demoted from Tiny Titans.
Good morning Graham, it might just sneak in Mkt cap wise but (LON: STHR) would be appreciated.
' Mobile Streams (LON:MOS) Mobile Streams, the emerging markets focused mobile media company [no-hope penny stock that sells knock-off games and gambling to people with no money on non-smartphones], today announces a partnership with Electroneum, a new cryptocurrency, made just for mobile, making it easy for users to trade and earn digital money.'
Hahhahahahhahahhahahhahahhahahahah. Peak 2017. What a joke. I hold.
My morning smallcap tweet: Laffable speling from LVCG.
Leaf Clean Energy Co (LON:LEAF), Audioboom (LON:BOOM), Inspiration Healthcare (LON:IHC), Live (LON:LVCG), Redstoneconnect (LON:REDS)
Leaf Clean Energy (LEAF) Invenergy Judgement - $1 nominal damages to Leaf but subsequent appeal obliges Invenergy to pay $36.4m by 21 June. Following receipt Leaf plans to announce a compulsory redemption of shares. Don't know what that means.
Audioboom Group (BOOM) 2 new and one renewed ad deals. No guidance on rev. from these.
Inspiration Health (IHC) receives, much later than they expected, regulatory certificates to sell upgraded Patient Warming System. Will "endeavour to make up for lost time and minimise the impact of the delay through putting in place a number of cost saving measures across the Group. We remain confident that the projected full year operating result remains achievable."
Live Company Group (LVCG) - 'Renewal of Soth Korea contract'. They can't even spell it right. 2 yr extension for BRICKLIVE. "New Agreement wavers the previous exclusivity..." Er, waivers? PR is W Communications, for all your poofreading requirements.
RedstoneConnect (REDS) Following sale of Systems Integration and Managed Services Divisions the CEO resigns but will remain employed for hanover. Chmn Frank Beechinor becomes CEO."Frank has significant experience in growing SaaS-based software businesses and is well-placed to implement the Company's strategy."
A bit off topic but I would just like to say a big Thank You to David Stredder for arranging the first Mello 1 day event. Many great and thoughtful speakers including Graham Norton. A great event at any price.
I must have missed that, was it part of the evening 'entertainment'?
Anyway I would echo your thanks to David and the team - an excellent day.
I guess today's announcement by Redstoneconnect (LON:REDS) of the CEO stepping down explains why they were unable to present yesterday,
Graham Neary now to deliver today's SCVR in the style of Graham Norton! Excellent!!!
So-so year end final results announcement from specialist currency manager Record (LON:REC) .
https://www.investegate.co.uk/record-plc--rec-/rns/final-results/201806150700034813R/
AUM up or down depending on whether you choose to denominate them in £ or US$. Revenues slightly ahead, PBT slightly down. Slight concern that they’re trotting out the “investing in the business” euphemism to explain margins falling from 34 to 31%.
Gus.
Good Morning Graham, Record have produced their finals this morning. Opened an office in Zurich, some positive comments about opportunities to engage with clients. Increased div. Its not a huge growth story but with management buying back their shares and a very strong balance sheet promises to be rewarding going forward imho. I am a holder and I would be interested to hear your thoughts on it.
Have a good weekend.
Hi Camtab - I am also a Record (LON:REC) shareholder and will be covering their results. Cheers. G
Morning Graham, it seems a quiet day on the RNS front today. I would be grateful if you are able to circle back to the B.P. Marsh & Partners (LON:BPM) results released earlier this week.
https://www.investegate.co.uk/b-p--marsh---38-partners--bpm-/rns/final-results/201806120751050770R/
Thanks
I think the more interesting thing on BPM is the share placement and new equity partner. Whilst the stock is trading at a discount to NAV the placement is at quite a discount to the share price. I hold and will take part in the placement as I see it has a positive move to grow the company and at the same time add liquidity to the stock.
My first thought was that it was likely driven by Brian Marsh looking to retire and seeking a succession plan for his business.
Edit - not sure why your post has the thumbs down, it wasn’t from me!
I thought the same..
It says on his website he started more than 50 years ago ..so surely coming up to retirement age!
I'm a sizeable holder in BPM, and am taking up the placing in full, plus a bit more.
I am mildly concerned about the age of Brian Marsh, but this is a great fund with good prospects of future growth It has developed a nice niche.
Hi reacher, I will be covering B.P. Marsh & Partners (LON:BPM) shortly. Thanks for the suggestion. G
I have held B.P. Marsh & Partners (LON:BPM) since buying in at about 90p in 2012. Brian Marsh is a very decent honourable man and I am sure he would say if he was planning to retire. Also, he is keeping a 44 per cent stake: if he wanted out, surely he would have sold more, and/or placed some of his own shares rather than giving existing shareholders the chance to buy in at the same price as the Aussie investor.
Simon Thompson at the Investors Chronicle continues to be very enthusiastic - https://www.investorschronicle.co.uk/comment/2018/06/12/corporate-activity-to-boost-bp-marsh/ - and so am I!
re: B.P. Marsh & Partners (LON:BPM)
Hi, just wondering about the Brian Marsh stake, isn't it 56.7%? Thanks - G
----------------------------------------
Brian Marsh, the Executive Chairman of the Group, who (along with certain of his connected persons, being B.P. Marsh Management Limited and the Marsh Christian Trust, as further referred to below) currently holds in excess 60.7 per cent. of the Ordinary Shares, wishes to diversify his personal holdings by transferring beneficial interests representing approximately 4.0 per cent. of the Existing Issued Share Capital (held through B.P. Marsh Management Limited, a company wholly owned by Brian Marsh) to a suitable, supportive third party investor.
I can answer my own question - after the dilution with up to 6.7 million new shares in issue, his percentage stake will reduce.
You beat me to it. Sorry
I did some "back of a fag packet" calculations. After the B.P. Marsh & Partners (LON:BPM) placing, there will be 37.48 million shares in issue. BM's reduced holding will be 16.56 million (44.2%) and PSC Group will hold 7.34 million (19.6%).
Dear Graham,
According to their website: http://otp.investis.com/clients/uk/bp_marsh1/rns/regulatory-story.aspx?cid=736&newsid=983795
Released : 01 Mar 2018 15:19
RNS Number : 4439G
B.P. Marsh & Partners PLC
01 March 2018
Date: 1 March 2018
On behalf of: B.P. Marsh & Partners Plc
Immediate release
B.P. Marsh & Partners Plc
("B.P. Marsh" or "the Company")
PDMR and Director Dealings
B.P. Marsh (AIM: BPM), the niche development capital provider to early stage financial services businesses, announces that it has been notified that B.P. Marsh Management Limited, ("BPMM"), a company wholly owned by Mr. Brian Marsh, the Executive Chairman of the Company, on 1 March 2018 sold 39,000 ordinary shares of 10 pence each in the Company ("Ordinary Shares") at a price of 271p pence per Ordinary Share.
As a result of the transaction, Mr. Brian Marsh has a total interest in 17,729,581 Ordinary Shares (including 998,000 Ordinary Shares held by the Marsh Christian Trust and 1,166,310 Ordinary Shares held by BPMM), representing approximately 60.71% of the total voting rights of the Company.
Please note, for the avoidance of doubt, that in the Company's announcement dated 9 February 2018, references to Brian Marsh Management Limited should be read as B.P. Marsh Management Limited.
Hope this helps!
Richard