Small Cap Value Report (Fri 18 Jan 2019) - REC, BOOT, MGR, CCT

Good morning!
The RNS is thin today. I have covered:
- Record (LON:REC)
- Henry Boot (LON:BOOT)
- Miton (LON:MGR)
- Character (LON:CCT)
Record (LON:REC)
- Share price: 28.65p (-9.5%)
- No. of shares: 199 million
- Market cap: £57 million
(Please note that I currently own REC shares.)
This is a niche currency manager, founded by Neil Record.
I covered it during my reflections on 2018, describing it as a mistake and explaining that in hindsight I gave too much weight to its strong balance sheet when I invested in it, and did not give enough weight to its competitive positioning and growth prospects.
The difficult competitive environment continues to make life tough for Record. Performance isn't going anywhere at present, with "assets under management equivalent" (AUME) falling by 4% when expressed in Sterling.
$1.1 billion of client withdrawals were made in the quarter (out of a starting pot of $61.8 billion), and there are another $1.7 billion of withdrawals where clients have notified Record in advance. So maybe the withdrawals will amount to 4%-5% of starting funds over the course of H2.
On the other hand, the reduction in AUME that is attributable to stock market and exchange rate movements doesn’t bother me, since it is unavoidable. It's the poor trend in client flows that is more of a worry.
Fee rates are "broadly unchanged" - the company has ongoing pressure on fees from rival currency managers.
On the positive side, the balance sheet probably remains as strong as ever - net assets of £25 million as of September 2018.
And the CEO continues to talk up the possibility of rolling out new products and services. I remain hopeful that they will succeed.
It has been a close decision in terms of whether or not to sell out of this position. Most people would sell, but I tend to hold on to things for as long as I possibly can.
Henry Boot (LON:BOOT)
- Share price: 254p (+1.6%)
- No. of shares: 133 million
- Market cap: £338 million
This property developer has traded in line with expectations.
It points out that it would have done better than expectations, except for a "one-off" pension-related hit. So it's inviting us to consider that the underlying performance was slightly better than expectations.
Outlook - the company has had a good start to the year, and is positioned "to react to whatever challenges and opportunities arise through 2019".
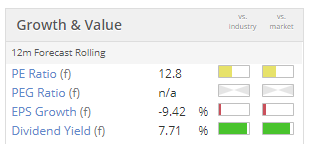
My view - cheaper than the last time I looked at it, with the premium to June 2018's NAV now just 17%. The real premium (vs. December 2018 NAV) should be materially smaller than this.
I can see why readers are requesting it, given its massive StockRank:
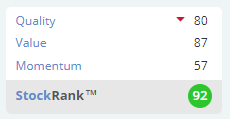
No reason for me to change my tune on this - if you like property developers, this one looks like it could be a nice choice, with a reasonable valuation and a great track record. But I haven't studied it in detail, since it's not a sector I focus on.
Miton (LON:MGR)
- Share price: 50.5p (-4%)
- No. of shares: 173 million
- Market cap: £87 million
I'm very interested in the fund manager space at the moment, sizing up opportunities in City of London Investment (LON:CLIG), Ashmore (LON:ASHM), Jupiter Fund Management (LON:JUP) and Schroders (LON:SDR).
Miton is the manager which looks most like me, concentrating on the UK and on small-caps.
Let's see how it has performd to year-end 2018:
- AUM up 14.5%
- Net inflows were a massive 27% of the starting pot
- "Overall performance in line with market expectations"
A possible concern might be the negative trend from Q1 to Q4 in net inflows:
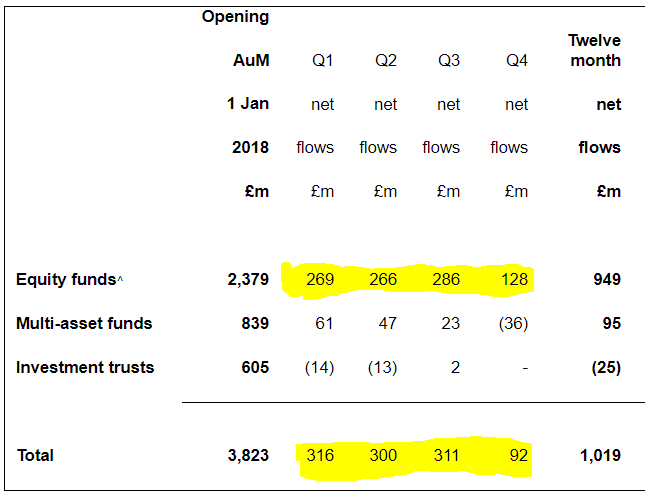
Q4 was particularly weak. Perhaps that is understandable, given the weakness in equity markets and political uncertainty?
All categories of funds had negative performance during the year.
My crude calculation of the company's equity performance is that it returned minus 11.6% of "average" equity AUM.
Despite that, the company says that 13 of 16 funds were first or second quartile performers since their current managers were hired (underperforming managers tend to leave!)
The UK Multi Cap Income Fund is particularly important, with £1,265 million AUM, and is currently the best performing fund in UK Equity Income.
Outlook - "positive business momentum" and "well placed as we enter 2019, despite uncertainties in global stock markets".
My view - I remain a fan of this business. StockRank is 88. Worth looking into.

Character (LON:CCT)
- Share price: 530p (+1.5%)
- No. of shares: 21 million
- Market cap: £112 million
I'm out of time sadly. A few quick points on Character, the toy designer and distributor.
- strong performance continues in UK
- international doing well, except the USA
- new products lines coming soon (I haven't heard of them, probably less valuable than the core lines Peppa Pig, Pokemon, etc)
Its Danish acquisition has had a setback with a retailer going bust. Nice comment from Character in the context of the Toys 'R Us failure:
"the demise of a major toy retailer creates opportunities for distributors....recent events in the market have shown that the market share of "fallen" retailers is quickly absorbed by other established retailers."
Performance and prospects in line with expectations.
My view
Another decent small-cap, this one has a StockRank of 99. While bearing in mind that it doesn't own the underlying IP of the brands it works for, and therefore is unlikely to ever enjoy a very high valuation multiple, I would be positive about its long-term prospects.
I've got to dash now. Have a great weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Bonhill (LON:BONH)
Strange - Companies House are still expecting accounts for the year ended 31 March 2019. Can't see a change of accounting reference date form.
Stockdale
"Source: Stockdale estimates, company data. *9 months to 31 December 2018 as company has changed YE from 31 March to 31 December."
Hello Aislabie
Bonhill (LON:BONH)
Thanks for that - it does look pretty interesting if the current forecasts are to be believed.
Mar 18 loss 1 mill
Mar 19 profit 2.6 mill
March 2020 3.39 mill
Shareprice 90p and 2020 EPS of 9.84 - means next year pe of just over 9 - with a nice trend there.
The less of the stats look goddam awful - but i would expect that looking at the prior history of never making any money. Worth some further research.
Oooh todays trading statement confirms they are ahead of expectations so perhaps the numbers may be slightly uplifted soon?
The 3% increase in shareprice today seems pretty muted.
A look under the hood of the balance sheet is needed - on a very quick look though - it all seems fine with borrowing matched by cash and receivables matched by payables.
The main negative to me is the sector they are based in is one where its hard to work out how sustainable profits are - hey ho.
Bonhill (LON:BONH) does look potentially interesting if the step change in performance is real (presumably acquisition related?) so I might have a look if I can make the time.
One thing that immediately puzzles me though is :
Since when do we have market expectations for 9 month periods?
Presumably what they are trying to tell us is that so far they are ahead of expectations for the 12 month period ending March, with full year performance dependent on the final quarter?
As someone mentioned yesterday I'm getting a bit 'grinchy' (I like that description - thank you!) when it comes to the wording of RNSes.
If an odd form of wording is chosen rather than one that is clearer, it makes me wonder why (again perhaps because I spent so much time 'word-smithing' statements for a very particular MD a little while ago).
I wonder if the 'missing clarity' here is something along the lines of : "we are doing better than we expected so far, but Q4 was always the important one this year and we haven't a scooby how we'll do over the next 3 months"?
Hi Gromley
Bonhill (LON:BONH)
Had a quick look at - Stockdale note on Researchtree - they appear to have changed their Y/E to 31 December - which explains a lot.
Looks interesting.
Phil
Thanks Phil,
The Bonhill (LON:BONH) statement makes a lot more sense in that context.
It makes it more difficult though to understand what the market expectations are/were for that 9 month period - the broker forecasts on Stocko are clearly still for a 12 month year.
It strikes me that the potential confusion over year on year comparisons could create a possible mis-pricing opportunity for those that really know what is going on.
For myself, however, I think l will park this in the 'too difficult' pile. I look again when the results come out.
Bonhill (LON:BONH) (I hold) came out with a very nice "ahead of expectations" TU this morning but it does not appear to have followers here. As a "Highly Speculative" "Sucker Stock" on an SR of 5 there is clearly scope to ignore it. But I believe that the transformation that Simon Stillwell (ex founder and CEO of Liberum) is making of what used to be Vitesse Media is worthy of study.
The purchase of Investment News is clearly changing the size and potential of the company and the live events are also doing well. Strong institutional support came on board with the fund raising for the purchase,and with the results expected to move from loss in 2018 to a profit in 2019 it should start to show on the private investor radar soon.
Hi Graham,
Re Miton (LON:MGR)
I have looked at this a number of times and as a firm believer in scuttlebut, I have some reservations about it which have stopped me in the past.
I have two friends who are former FMs there and one loose contact who is presently employed, so have a small grasp of the culture and individuals. The risk of a dominant figure head seems large for Miton (LON:MGR) and currently key man risk is a factor that makes me hesitate, along with the reliance on a relatively small suite of funds focussed on similar niche area. Other than M&A I don't really see what gets them the growth they need.
Fund management is becoming increasingly cut throat and as operational costs increase fee pressure is weighing at exactly the same time. I don't see their performance as warranting really substantial inflows vs the opposition. So it seems to me that buying Miton (LON:MGR) is an M&A trade.
Whilst you mention City of London Investment (LON:CLIG), where I have been a long term holder I also having growing doubts here as I see the founder move towards the exit and the business model face competitive headwinds that may make their institutional investor base question the logic of paying them as a multi-manager. Their under-performance and fee pressure both seem like issues that won't disappear in a hurry. It will be interesting to see if the u/w to tech results in an out-performance as the numbers shake out. If it doesn't I will reluctantly say goodbye. However, the level of clarity and detail the company presents is worthy of a big tick and keeps me interested.
The final name you mention you mention where I have an interest is Jupiter Fund Management (LON:JUP), seems to be being driven by fears about the large bond fund and redemptions. Whilst I haven't done the numbers I do wonder if there is now a lot of fund manager being thrown in for the money when you see an operating margin which is still running at over 40% whilst the market is fretting about its bond fund redemptions. As a result this is my current favoured one to add to on further weakness.
The irony for me would be if Jupiter bought Miton Group!
Regards
Just wanted to say a big thanks for the detailed views on the fund manager space. I have no position in any of them as of tonight but am keen due to the valuations on offer. Jupiter Fund Management (LON:JUP) is probably the most "conventional" of the lot which leaves it most vulnerable to competition from passive funds, would you agree? (this could of course be fully priced in now.) Cheers. G
No worries Graham, glad it was of some value. Difficult to say re Jupiter Fund Management (LON:JUP) as I haven't looked at the breakdown of aum. At last check Mutual funds were the biggest by a country mile. So if you forget segregated mandates and Investment Trust, as they will generally be quite sticky money then you are really having to consider their performance in mutual funds. I haven't checked this but I would guess the strategic bond fund at £3.65bn is the biggest of their fund suite. Whilst many would tell you passives are worth considering, I fundamentally disagree in the corporate bond space. It is absolutely not the case that they (at the moment) present a viable alternative. Therefore, I don't think this is a competitive pressure that I would worry about in this case. The more pressing fear is that the manager has made a bad call, most likely on duration or bond asset class. The strat bond fund is mostly in BBB space and that has been his call for some time from memory. It looks like the fund size has fallen by c£200m since Apr 18 or roughly 5%. Unless you assume a 2009 style event I can't really see greater than another 5% fall in AUM barring a manager created disaster. This brings an interesting scuttlebutt point for my own analysis. Of all the current major bond investors, which in my former life were my bread and butter clients, Jupiter is one of the few I didn't have a good handle on (The other being Fidelity), however, his longevity points to him being good at his job. The other point being there is massive upside in this fund if you consider the M&G retail fund is at last look about £22bn. So, its entirely feasible that his AUM grows with good calls from here. That in large part is down to the marketing machine, nevertheless there is upside potential not just downside.
As for the other mutual funds, it seems that there are a lot of them, but I haven't found a ranking by size. I'm sure there are measures of firms number of funds in top quartile etc, so I may well do some digging.
My general feeling about Jupiter Fund Management (LON:JUP) is that it could be a beneficiary of the ongoing consolidation driven by cost pressures as it is still bite sized to global players (I'm thinking Henderson and Friends Life here being swallowed up by Janus and Aviva respectively), but in the meantime it is at no greater risk of passives undermining its business model than a Miton (LON:MGR) for example. If anything it may well have the resources to counter that threat by diversifying its fund structure further. The SP does seem to be discounting a lot of risks right now, unless you presume further equity weakness and more importantly a flight from the bond fund.
It's clear to me I need to dig further, but i do think the SP performance warrants further investigation.
Cheers
Paul
Record (LON:REC) is off my radar screen now. But the last time I looked it struck me that there were two big factors to consider, one positive and one negative.
The negative was that MIFID required collateralisation of fx forwards. Assuming that Record's client base is predominantly institutions that are collateralising other instruments (eg swaps) - there will probably be big incentive to collateralise under one roof. As Record just does currency I suspect they could see outflows as institutions pull their funds to places where they are collateralising their other instruments. My understanding is that this requirement was not enforced but delayed (but I would be unaware of any developments on this).
The other factor, positive, is that Record lost its carry trade business when global interest rates collapsed making it unviable (The carry trade matches the purchase of a high interest currency against a low interest currency which is sold, think -picking up pennies in front of a steamroller). The carry trade works until it doesn't - but it's the clients not the currency provider who go under the steamroller.
If interest rates start to rise - the carry trade could be back on and you could expect Record to multi-bag - from memory Record's share price was north of 300p when it had a carry trade business.
What puts me off Record (LON:REC) is that the directors seem to be ludicrously over-remunerated. The three senior executives have averaged over £700k p.a. each total remuneration over the last two years, over 50% of which has been cash or share bonuses.
This is in the context of a £63m market cap business that has delivered consistent mediocrity both in absolute terms and relative to its indices.
Isn't it likely that Record (LON:REC) are losing out to £AFX ?
I hold Alpha FX (LON:AFX). Better to own the disruptor than the disrupted.
I'm no expert on the sector so happy to be corrected .
Hi Graham, again thank you for your insights they are extremely useful. As you would guess we agree some and we disagree some. On this occasion I am in slight disagreeance (which of course is what makes a market!) on REC. I have held this for a few years now and it continues to pay an excellent dividend. Yes there are questions about the value of a divi cut in these more chastened times. Howev er the management will fight this as much as they can because they are invested in the business as are staff. This is a criteria I really like in shares as I know our interests are aligned. Furthermore the bal sheet gives them time to bring the ship around. I agree the current position isn't great but having been involved in the City and fund management funds come and funds go as long as they don't go in a sustained way, which I don't believe they will here. (That though is uncertainty). So we are at the point of disagreement i would like to think they will bring out new products and I am prepared to back that whereas you want to see the baby before you pay for more nappies. Small difference really...... I hope I have interpreted your position correctly.
Hi Camtab, thanks for the comment. To clarify, let me repeat that I currently own Record (LON:REC) shares, i.e. I already paid for the nappies (to use your analogy)! I am backing them to keep fighting and gain some traction with their new products, and I hope they succeed. G
So you're going for the second child !
Have a good weekend !
Phil
just a side bar comment on Taptica International (LON:TAP) but when I tried researching them in the past I found it hard to get a grip on what their actual technical capability and offering was (apart from their acquisition of DSP capability from Tremor for $50m), Normally tech companies and even martechs will want to show off their propellers (take a look at the d4t4 site for example), Taptica International (LON:TAP) had a lot of generic AI, ML algo type language but no specifics which struck me as odd
I may well have been wrong (although the price collapse suggest otherwise) but that gave me a sense of unease. They could well be kosher (pardon the Israeli pun) or alternatively just overpriced media buyers and click harvesters.
I do hold d4t4 mind and have a good grip of how they work and why they are worth holding
Lots of G4m holders on here...good bounce from 160 level yesterday continues today. Might be worth a look at this bombed out level but of course very much dyor. Ditto quiz which was the subject of Paul Scott note on Monday has moved up from 21p to 26p this week. I have been buying both near the lows this week so that’s my disclosure
Hi Graham, your views on Character (LON:CCT) would be great, thanks
Hi Dan, I've done that quickly. Thanks for the rec. G
Yours views on Henry Boot (LON:BOOT) would be highly appreciated, thanks
I feel your pain on Taptica International (LON:TAP)
I tried to catch a falling knife after the CEO resigned as I believed the market had overreacted but have cut my losses already and will consider it a lesson learnt.
While there share price is absurdly cheap, I just felt that given everything what has happened over the last few months (CEO resignation, share buyback announcement, share buyback postponement, potential takeover etc) yesterdays trading update was far too vague. It's clear the market has lost trust in the company so it would have been a very good opportunity to win some of that trust back by sharing a bit more insight into what is going on behind the scenes and what next year might hold in terms of sales/profit etc. The fact they didn't raised alarm bells for me and as such I am happy to take the loss.
In terms of what could have been done to avoid investing in Taptica International (LON:TAP) in the first place, I guess the key thing is the CEO made it clear in the admission document that he was under ongoing investigation. I don't think many people spotted this so I think the only way of managing risk in this instance would have been to conduct exceptionally detailed research or simply through diversification.
Hi Foolish Ben.
Thank you for your input.
I did top up after the resignation but I am tending towards your view.
I know it is thumb sucking but I will do some final research over the weekend and put the sell order in before the market opens or tuck it away and wait for it to make me a lot of money.
Key for me will be:
Apologies if this counts as highjacking the SCVR
BW
Michael
Any chance of looking at Sophos if you get a chance please.
Hi Graham. Are you still holding Record (LON:REC) ? AUME has fallen but fees have remained constant. With uncertainty ahead there could sti be vslue here despite the fall today.
Hi Beginner, I've taken a look at Record (LON:REC) - pretty dull! G
Just passed their GNVQ Level 1 (Going Nowhere Very Quickly).
Henry Boot (LON:BOOT) and/or Miton (LON:MGR) if you are inclined please Graham. Both trading in line, although their share prices more susceptible than some to the pervading air of despondency that overhangs UK. economically and politically at present.
I would also be interested in your view of Miton (LON:MGR) please Graham. Is their performance out of line with the rest of the sector, or even the market as a whole? They do report positive inflows.
Yes and it would be interesting to compare valuation with other asset managers like Ashmore and Premier, e.g. Market Value to AUM.
Richoux (LON:RIC). As a pat on the back to Stockopedia in the light of Richoux (LON:RIC) going private, at least as far back as August 2017 (I didn’t look further back) when it was trading at 16p Stockopedia had it qualifying for Altman Z score in short selling.
As someone who is still trying to decide whether to liquidate my car crash investment in Taptica International (LON:TAP) I am interested in how one can spot these car crashes (£cake) in advance.
I hold Taptica International (LON:TAP) but never held Patisserie Holdings (LON:CAKE) or Richoux (LON:RIC).
Hi
To me you are looking at 3 very different scenarios:-
Richoux (LON:RIC) . To be frank the stock screen looks disastrous, however, what would have stopped me investing was the free float - even in 2013 it was only 14% currently 3% - what's the point of the listing? There is always therefore a risk of delisting.
Patisserie Holdings (LON:CAKE) . If, as is alleged, this is a management fraud then it will be virtually impossible for an outside investor to spot. The person(s) involved may well have had a checklist derived from Stockopedia/ Sharepad/ etc to ensure there were no red or amber flags. Its probably best for the investment community to stop beating itself up on this - every so often we will get one of these. Probably more important for the auditing profession to learn what went wrong and to try and stop in the future.
Taptica International (LON:TAP) . This is a car crash and I've recently sold out. The final straw was the TU update yesterday which essentially contained no detail and therefore was just saying "trust us" - well trust was at a premium after the Buy-back debacle. That's what I take from this - if you just even just start to get a twinge of distrust get out or don't get in - but I was trying to be clever. Perhaps on a wider perspective, and with the benefit of hindsight, that should have been after they'd raised the cash at the start of the year and then didn't use (I wasn't in at the time).
Strange thing is I strongly suspect there's nothing wrong here and I'm missing an opportunity.
So as Ben suggests , in the latter 2 cases, perhaps the only defense is diversification. I guess you could add reasonable stop-losses to that.
Phil
(Never held Richoux (LON:RIC) or Patisserie Holdings (LON:CAKE) )
Thanks Edward John Canham. Really helpful.
Have a good weekend.
Purpleski
Hi Michael,
I hold a small amount of TAP too. I bought it based on fundamentals when it qualified for the sif portfolio. Do you know what the Institutional holders are doing? They are bound to be closer to the newsflow than us!
Hi DMG2305
Schroders PLC and MTD PTE Ltd have substantial stakes though MTD is based in Singapore so god knows who is behind that one.
Purpleski.
Miton (LON:MGR)
Market / investment performance went from +ve £118m at end of Q3 to -ve £466m at end of Q4 a fall of £584m. My maths tells me this is a this is a 12% fall based on AUM at 30/9/18 which looks to be a poor result and could hinder inflows in the future.
Phil
Disc: past holder
My morning smallcap tweet: Barely worth reading
1Spatial (LON:SPA)
1Spatial (SPA) wins 4 year €1m contract Ireland's Property Registration Authority plus a 3 year framework contract with Ordnance Survey (no value for that one).