Small Cap Value Report (Fri 20 July 2018) - REC, SIXH/MPAC, ATY, BGO, MIDW, VLG

Good morning!
Stocks of interest today include:
- Record (LON:REC)
- 600 (LON:SIXH)
- Athelney Trust (LON:ATY)
- Bango (LON:BGO)
- Midwich (LON:MIDW)
- Venture Life (LON:VLG)
Record (LON:REC)
- Share price: 43.3p (+4%)
- No. of shares: 199 million
- Market cap: £86 million
(Please note that I currently own REC shares.)
This is a specialist currency manager whose shares I've held for about six months now.
I like many things about this company and its financial characteristics, and have likely mentioned them in previous editions of this report.
The only thing it's lacking is growth. This is why it remains one of my smaller positions. If it showed signs of growth, and the valuation remained reasonable, I'd be interested to promote it.
This update shows a few signs of life. Key points:
- AuME (assets under management equivalent) down from $62.2 billion to $61.9 billion. Not good, but....
- Client net inflows of $0.6 billion, with an inflow to the higher-margin Currency for Return product.
- Number of clients increases by four to 64
My view - I still don't have enough conviction to take a large position in this stock, and I may end up selling out of it to go into something where I have more conviction.
The benefit to holding it is that it is very good at generating cash, and most earnings are being paid out as dividends.
For example, nearly all of 2018 EPS is being paid out, including a special dividend. I think the trailing yield based on today's share price is 6.5%. Record is achieving that even while maintaining a very strong balance sheet.
So for someone who likes a bumper dividend yield and isn't too concerned about growth, this may be of interest.
600 (LON:SIXH)
- Share price: 17.75p (+8%)
- No. of shares: 113 million
- Market cap: £20 million
In truth, these final results are of less interest to me than yesterday's announcement: Buyout of Pension Scheme Agreement.
After the plunge at MPAC (LON:MPAC) this week, lots of people have been scratching their heads over the true danger of having a large pension scheme attached to their companies.
600 (LON:SIXH) has come up with a handy solution to get rid of its £200 million pension problem entirely: selling it to an insurance company.
Note that 600 had an actuarial surplus of £12.2 million as of October 2017, and an accounting surplus of £42 million as of March 2018 (the accounting calculations tend to be more optimistic than the actuarial ones).
This made it attractive for an insurance company to come along and take it off its hands.
The insurance company will be compensated for taking on the risk of the fund, but will return surplus funds after wind-up back to 600. This is estimated to be less than £4 million.
600 will lose its accounting surplus from its balance sheet, but will be freed from having to worry about these liabilities.
From an investment point of view, it is nice to have a simple business proposition without having to worry about interest rates and investment returns and all the other variables that go into a pension fund.
Besides the uncertainty they create, large pension schemes can restrict what a company can do with its cash flow.
As the Chairman says today:
At one point a prominent portfolio manager observed that the Scheme effectively controlled the company. In a sense he was correct as there were undertakings and security arrangements in place which severely limited our flexibility.
So I think 600 might be worth a fresh look, now that the pension scheme is off its back.
As for MPAC (LON:MPAC), I would continue to view it as a very difficult situation for investors.
Its pension scheme liabilities are twice as large as 600's, and it has a much smaller accounting surplus compared to what 600 had. Annual payments of nearly £2 million into its pension scheme are required.
While this hangs over it, the shares are a bet on interest rates and investment returns more than they are a bet on operating results or earnings.
Athelney Trust (LON:ATY)
- Share price: 251p (unch.)
- No. of shares: 2.2 million
- Market cap: £5.5 million
As before, I bring this to your attention not for its investment merits (on which I have no opinion) but for its entertaining commentary.
Bango (LON:BGO)
- Share price: 156.5p (-3%)
- No. of shares: 70 million
- Market cap: £110 million
Trading Update & Notice of Results
I've not written about this one before. The last time Paul covered it in a little bit of detail was back in September 2017.
In Paul's words, it "processes small payments for phone apps, via the end user's mobile phone bill". Sounds very much like Zamano (LON:ZMNO) (which has ceased to exist as an operating business, is now just a shell).
This growth in "end user spend" reported today is encouraging:
End User Spend (EUS) continues its four-year growth trend of at least doubling every twelve months.
If full-year 2018 user spending is more than double the full-year 2017 user spending, it will be more than £540 million.
Bango says its platform with the current cost base could process more than $5 billion of EUS per year, i.e. to grow by 7x from the level which 2018 might achieve.
Cash - it says it is "fully funded to reach Group profitability", having cash of £5.8 million.
My view - I am intrigued as to whether this might be one of those speculative Sucker Stocks (as classified by Stocko) which has a real chance of success. The growth rates and partnerships with the likes of Amazon have piqued my interest.
At the last results statement, for 2017, Bango converted 1.5% of EUS to revenues.
If it succeeded in reaching $5 billion of EUS per year, that would translate to juicy revenues at that 1.5% conversion rate.
But the conversion rate is likely to fall, I think. The recent trend for this rate has been lower, and I assume that bulk sales will attract discounts, and that competition will heat up.
If we assume a 1% conversion rate, then Bango would generate $50 million (GBP £38 million) of revenues on that $5 billion of user spending.
I would expect the marketing budget, executive pay, etc to increase. So administrative expenses would be higher than the £8 million recorded last year. There should still be meaningful net income, unless costs ballooned out of control.
Putting it all together, I think there is an investment case to be made for this stock.
The market cap is pricing in that end user spending will double again and keep going. If you feel comfortable with the technology and trust management to deliver, then I can see how it might be reasonable to give this a chance.
Midwich (LON:MIDW)
- Share price: 690p (+4%)
- No. of shares: 79 million
- Market cap: £548 million
Midwich, a specialist audio visual and document solutions distributor to the trade market, is today providing a trading update for the six months ended 30 June 2018.
Midwich listed in May 2016 at 230p, so it's now a three-bagger.
Earnings have generally been revised upwards since IPO. Underlying sales growth has been positive, while acquisitions and sterling weakness have helped:
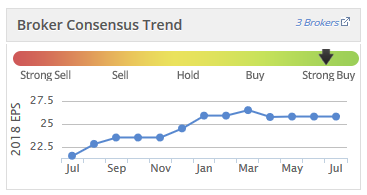
It's an equipment distributor. Not the type of company I would typically be interested to invest in. But it is clearly getting something right.
One of the reasons I don't typically invest in distributors is that their competitive advantage is often tied to the specific attributes of their employees, rather than to any assets owned by shareholders.
For example - on its website, Midwich attributes its competitive position to its "technical expertise, product knowledge and customer service offering".
But It keeps outperforming, so it deserves credit for that. After a strong first half, and with positive sales momentum, performance for the full year is anticipated to be ahead of expectations.
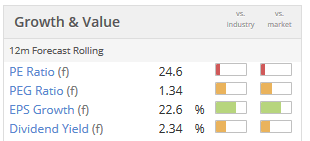
It's categorised by Stocko as a High Flyer, with strong Quality and Momentum. Statistically, therefore, things are looking good for shareholders.
But at the current rather elevated share price, I would now be a bit concerned that it is more than fully valued.
Venture Life (LON:VLG)
- Share price: 42p (+1%)
- No. of shares: 37 million
- Market cap: £15 million
Placing, Proposed Acquisition and Notice of GM
This is an "international consumer self-care group focused on developing, manufacturing and commercialising products for the self-care market".
I know a little bit about it, because I used its UltraDEX mouthwash for a short while. That is an effective but tasteless and somewhat niche product.
Today it announces a conditional, oversubscribed placing to raise up to £18.75 million (gross). It will more than double the share count.
How the funds will be used:
- £4.2 million to purchase Dentyl mouthwash and the right to distribute Dentyl BB mints in the UK.
- £3.7 million to repay loan notes and expensive convertible bonds.
- the rest for growth & further acquisitions.
Bear in mind that the VLG strategy is to buy brands which aren't performing very well, that are "unloved", and try to turn them around. It expects to "reverse the declining sales" at Dentyl.
Dentyl generated £1.2 million of pre-tax profits from just £2.9 million of sales in 2017 (using management accounts).
We can assume that 2018 figures are smaller than this. VLG might be paying a multiple of something like 4x or 5x PBT. Nice and cheap, but this is a very small business in decline.
My view
This looks like it has a lot of potential to me.
VLG has been doing a good job with UltraDEX. Revenue from that brand increased by 24% last year. Distribution has been widened in Boots and Lloyds Pharmacy for the UK market and there has been a big international drive, too.
Shareholders are betting on continued success with that brand and for something similar to happen with Dentyl and other future acquisitions.
Operating profit last year was £600k, before some heavy finance costs. With the newly-structured balance sheet, those finance costs should be significantly reduced in future.
So I suspect we are due for a very significant improvement in the current year, and brokers agree. There are pre-existing forecasts for VLG to generate EBIT of £1.3 million in the current year, rising to £1.9 million in 2019.
Definitely worth doing more research into this one, then!
Calling it a day there. Have a fine weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Just read the very late RNS from Staffline (LON:STAF) announcing the acquisition of Grafton Recruitment's Ireland business. Very frustrating that they disclose revenue, pre-tax profit and net assets, but nothing on what they've paid (assumed very small consideration) or most importantly the impact on earnings - so not sure how much we can glean from it. As a holder of Staffline (LON:STAF) I have been concerned for some time that they are too focussed on revenue targets over earnings - and that this latest acquisition may be another step in the vanity project towards their next revenue target...
I wonder if it was worded deliberately? It would take some time to think whether to put your hand up or not, by which time the chance would have gone.
Can these Sports Direct investments be even deemed as 'strategic' if they are not going to influence them in some way? I don't know exactly but there must be some opportunities between them, Debenhams and Game.
Announcement today from Sports Direct says:
During a year-end results presentation by Sports Direct at the Stock Exchange on 19 July 2018, Mike Ashley read aloud a brief statement about the Group's relationships with its strategic investment companies. This statement has led to interest from various parties, and in response to this we are publishing the statement in order to make it freely available to all.
The statement read by Mike Ashley is as follows:
"One of our biggest challenges this year end has been an assessment of our relationships with our strategic investment companies. A number of these such as Game and Findel consider us to have significant influence over them by virtue of signalling us as a related party in their accounts.
I do not believe that we have significant influence over these companies. I do not believe they apply the core SD principles of being conservative, consistent and simple.
I want a show of hands of those people in this room that disagree that applying our core principles of being conservative, consistent and simple, and thus increasing our significant influence within these strategic investments would be a bad thing? I want to be crystal clear, if you disagree with this put your hands up?
Now you know why I don't think we have significant influence. We will be contacting our strategic investment companies in the next few months and urging them to adopt our core principles of being conservative, consistent and simple, and we will let you know at the half year where we have got to.
Sports Direct believe accounts should be shown in a form that can be understood and relied upon and I am sure you would agree."
Does anyone understand what he is actually trying to say and the possible implications? It seems to be causing a drop in the price of Game Digital (but not so much Findel).
Does anyone understand what he is actually trying to say and the possible implications?
I think the excellent post above from ratioinvestor about Athelney Trust applies equally to Sports Direct - bonkers management, crap investment -> who cares! :-)
All the best, Si
Perhaps he'd visited a pub a few hours before the presentation?!!! I'm a holder of £GAME and wondered about the drop in SP over the past two days. Like you I'm wondering what his statement means, and whether it spells problems for £GAME...?
Just a guess but classification as a "related party" normally means additional disclosures of transactions between the investee company and Mr. Ashley or SD. Perhaps Mr. Ashley, who is a private man when it suits him, is seeking to "convince" the investee companies that such additional disclosures are unwarranted (or, perhaps more accurately undesired and unwelcome).
What a bizarre statement from Ashley! He seems clueless about what a related party is. This bit in particular:
I find that mind boggling in the context of the Financial Reporting Council still having an ongoing investigation into Sports Direct's 2016 accounts for failure to disclose related party transactions with a company controlled by Ashley's brother.
From the regulatory announcements and disclosures in the accounts of Findel (LON:FDL) and GAME Digital (LON:GMD), the nature of their relationship with Sports Direct is clearly more than just that of a major shareholder, so I really don't see how Sports Direct can be treated as anything other than a related party, all the more so if Ashley is talking about exerting influence to get them to follow some accounting principles specific to Sports Direct.
So in my view the accounts of Findel (LON:FDL) and GAME Digital (LON:GMD) would not be complete without full disclosure of all their dealings with Sports Direct.
As an example Findel spent £680k on professional fees in FY17 on matters relating to Sports Direct, including a proposal for Ashley to become their chairman. Even if that amount is not financially material, it is surely information of interest to shareholders, but it would not have been disclosed were Sports Direct not treated as a related party.
Ashley seems to think it is only by removing those related party disclosures that the Findel and Game accounts can be "understood and relied upon", which is completely bonkers.
Athelney Trust (LON:ATY) seem slightly bonkers in my view. Did anyone ask them for their political, economic views? They come across as the London taxi driver who unprompted feels the need to tell you what they think about the world. The Athelney Trust (LON:ATY) commentary should be in a blog on their website.
What seems bizarre on Athelney Trust (LON:ATY) is that there is almost no commentary on the stocks they hold. The stocks they do mention seem to be low quality to me. I would accept Athelney Trust (LON:ATY) giving their views on the world if they were one of the world's greatest investors. This appears to not be the case.
Either the people at Athelney Trust (LON:ATY) are bonkers or their commentary is an attempt to get media attention. Turning it around and what would you think if a political/economic analyst started harping on about stocks in a very opinionated way? The Athelney Trust (LON:ATY) commentary makes me think they are a bit too full of themselves. If I held I would sell just on the basis of their bizarre commentary. The commentary ensures I would never buy Athelney Trust (LON:ATY).
Looking at their website and Athelney Trust (LON:ATY) have underperformed so why do they think we want a long commentary about the world as well as their personal advice?:
http://www.athelneytrust.co.uk...
Graham
re Bango (LON:BGO) : This is a potentially cracking stock. The current operating costs of the business will support up to 10* the existing EUS so don't expect the cost base to ramp up from existing levels by much at all. Almost everything from now on drops to the bottom line as they hit operating cashflow breakeven a few months back from memory and should be close to moving into overall group profitability soon.
Great deal in Japan with Amazon Prime. Also strong presence in LatAM, one of the fastest growing payments markets.
2019 EPS is expect to be circa 8p so roughly 19* earnings. For a business that should grow at 25%+ per annum post the next year or so of expected doubling I can easily see a case for 300p over the next year or so.
Graham, thanks for highlighting Athelney Trust (LON:ATY) ... entertaining reading over lunch.
re: Athelney Trust (LON:ATY). You're welcome! Always fun to keep an eye out for their updates. G
Hi Graham,
Thanks for the nod on the Athelney Trust half year report - a work of genius and very entertaining.
I'll look out for reports of inflatable tanks and invisibility cloaks in some of the forthcoming defence company reports!
Richard
Graham, I have been thinking about pension schemes in the light of MPAC (which a company I have shares in). Is it right to say if interest rates rise this will be beneficial as liabilities are reduced? What if they have pursued an investment process of liability matching over the last few years? An approach Mercer and others consultants promoted. If you have matched liabilities then a rise in interest rates would mean a fall in capital values of the scheme (as presumably they are invested in govt debt vehicles). BUT the cashflows have been secured so the deficit aspect is of no interest (unless inflation rises significantly, which has long bothered me about this advice). Alternatively if you are 100% invested in equities (which a mature scheme won't be) a raise in interest rates becomes a negative because we are told money goes away from equities and towards bank accounts and yield instruments so liabilities fall as assets fall. I don't know how the two are correlated.
Graham. Thanks for highlighting 600 (LON:SIXH) I see the company has loan notes (with convertible warrants) maturing in Feb 2020, which if I understand correctly, could result in 44 million share dilution (at 20p a share) - not that far above the current share price.
Hi WS, re: 600 (LON:SIXH), thanks for pointing out the existence of the warrants. G
Hi Graham
I’d be interested in you having a really good look at these results.
Haddeo & Partners already control this company with over 25% of the shareholding and it is Haddeo that also stumped up the £8.5m for the loan notes which pay a coupon of 8%. So in 2020 the debt will be able to be refinanced at lower levels or Haddeo could accept shares at 20p and reduce company borrowings by £8.5m. If they do it would be a sign of confidence in the business going forward.
Other points are
- significantly reduced borrowings due to pension buyout, fund raising and sale of ProPhotonix stake
- introduction of dividend at circa 3%
- decent trading update
- indication that margins will improve
- Stockopedia data currently understated significantly
It seems to me that Haddeo are making all the moves to position this business for a sale
I look forward to your comments
Regards
Hi WallerMa,
That's a very interesting point re 600 (LON:SIXH) and Haddeo. I looked quite extensively at the accounts and prospects but hadn't looked at that angle.
That has given me something to think about over the weekend as I had previously considered all of the divestments to be a matter of survival given that they had been cashflow negative for at least 18 months.
They have basically sold off pretty much all of the family silver and the balance sheet now has an interesting profile
*1 - assuming the get £ 3.5m from the pension scheme surplus.
*2 - I'm not totally sure about the deferred tax, but this is what is left over once I eliminate the 35% on the pension surplus.
That strikes me as being rather like the profile one sees when Private Equity (re-)floats a company on the market - No real assets and material net debt.
I can't think though that I have seen such a manoeuvrer performed on a company that remained listed, but would be grateful in anyone has seen such.
As far as I can see though - Haddeo only have about 12% of the loan notes, so I'm not sure if they did stump the whole amount originally? (They may have disposed of some already).
Interesting angle !!!!
I realise I should have added a disclaimer to my previous post, for the avoidance of doubt, I have been a previous holder of 600 (LON:SIXH) . Not at the moment though as I consider them a little expensive in the round, their results though were better than I expected, so I'm slightly more interested.
Thanks for pointing out the Haddeo proportion of the Loan Notes I hadn’t picked that up
I’m expecting the bid to come from an American Company given the profile of the trade revenue and the dominance of the dollar
It seems the only way Haddeo and the other Directors will maximise their interest.
Finally I would have voted your post positively if only I could have worked out how!
Regards
Also thanks for the prompt to mention I do have an interest in 600 Group.
Thanks Gromley. Makes sense, much appreciated.
On Record (LON:REC) , although USD denominated AUM fell it may be worth pointing out that in Sterling terms their AUM went up from £44.3 to £46.9.bn. Perhaps they need someone to manage the currency risk for them ....?
Gus.
Nice one Gus made me smile !
Following on from yesterdays report covering MPAC (LON:MPAC), I received a mail from Master Investor this morning suggesting it was a good asset play as break up value exceeds 200p per share (and therefore share price should be over 200p)
Any thoughts, other than the obvious - asset value doesn't always translate into share price.......
They are being too superficial.
With 20m shares in issue £2 would give a market cap of £40m.
Now it's true that as of December that had a NAV of £42.8m and a TNAV £41.9m, all the more attractive when £30m of that is cash.
But,
Those figures also include the UK pension fund valued at a surplus of £17.6m (although after tax I think it is only £11.4m)
As Graham mentioned yesterday, there is another view (the old actuarial view) that says the scheme is in deficit of £70m.
Even if we discount the old actuarial view entirely, there is no way that would be able to recover the full £11.4m via a "buyout", in fact I strongly suspect that currently they would have to pump in additional cash to get an insurer to take the scheme off their hands.
That £11.4m on the balance sheet is about 57p per share, so even in a best case of offloading the pension for nothing, the current share price is above the "break up value".
(Oh and the US pension scheme is in deficit and would require more than the accounting deficit paid into it in order to pass it off to an insurer).
I don't disagree that the NTAV isn't 200p+
BUT
if the pension fund goes the NTAV being circa current market cap assumes that the existing packaging business is worth absolutely nothing, which is bonkers. As a stand alone business to private sale it is worth at least 60p in my view and actually probably north of 100p.
The US pension unlikely to be in deficit if the FED tightens at the rate it is signalling to the market.
Of course if there is another recession / downturn that changes things again.
A fundamentally misunderstood stock which, I guess is why it probably trades in such a volatile range depending on reported conditions. As a consequence of the debate investors have over where it should be valued that won't help the share price either particularly until there is more of a consensus.
Thanks for the requests. I'll add Bango (LON:BGO), Midwich (LON:MIDW) and Venture Life (LON:VLG) to the list for now. G
Symphony Environmental Technologies (LON:SYM)
https://www.bbc.com/news/science-environment-44888185
Ouch! Thanks for link John, and for your comment Francis. Felling happier now that I sold a while ago above 20p...
Has anyone please got an idea why Symphony Environmental Technologies (LON:SYM) are down 28% on no announcement? I can see price monitoring extensions in RNS this morning...
Hi Andrea, you'll find the answer on the ADVFN bulletin board. Something about a BBC story that seemingly undermines their technology.
cheers
Francis
Another vote for Midwich (LON:MIDW) please Graham; ahead-of expectations outlook, reasonable stockrank
Hi Graham,
You covered Venture Life (LON:VLG) back in March. They've come out with a significant placing today to takeover a dental brand plus clear out some loans and give them more working capital. Placing was oversubscribed at 40p (against yesterdays close of 41.5) and they are up 3.6% this morning so seems the market likes it. Any comments welcome.
I'm long.
Any chance of commenting on Midwitch (MIDW). Ahead of expectations. Good momentum and quality (ROCE/ROE). I have a small position.
Greyster
Hi Graham,
Time permitting I'd love to get your view on Frontier Developments (LON:FDEV). They released good news yesterday and yet the share price keeps going down...
Morning Graham,
Perhaps this is speculation, but I've read suggestions of deliberate share price manipulation related to Frontier Developments (LON:FDEV) specifically heavy selling during the day followed by heavy after hour buys. I wonder, if you had time, whether this could be debunked? I've no idea whether it's true or not, and if I'm honest, I'm not even sure what to look out for, but I find the whole think very intriguing.
Thanks,
IG
Another vote for Bango (LON:BGO) if you have time Graham thanks.
My morning smallcap tweet:
Feedback (LON:FDBK), Bango (LON:BGO)
Feedback (FDBK) CEO resigns with immediate effect 'in order to devote more time to his other business interests.' Kind words but he'd only been CEO for 5 months. In April he said "I look forward to delivering continued progress towards our long-term vision." We want the truth.
Bango (BGO) H1 trading End User Spend (EUS) £220m (£92m) "continues its four-year growth trend of at least doubling every twelve months...Our competitive customer offering has been greatly enhanced by Audiens, allowing global merchants to boost customer acquisition and revenue through powerful data insights. This combined proposition is driving EUS and revenue growth, positioning Bango well for a strong second half of the year." In line? No guidance.
Personal Group (LON:PGH) 'had a good start to the year, with trading in line with management's expectations and ahead of last year's performance in all three business segments.' A few new customers. Although the TU is in-line, it seems a nice dependable counter-cyclical stock (outsourced pensions & insurance) so might Graham or others be interested in taking a look at it? I hold a little slice.