Small Cap Value Report (Fri 21 Jul 2017 - Part 2) - QUIZ, IQE, Positive retail sales data

Good morning! It's Paul here.
Graham usually does these reports on Fridays, but there are a few things I want to comment on too, so it's 2 reports today. Graham's report is taking shape here.
Please note that I had a late surge yesterday evening, and wrote 4 more sections in yesterday's report, which is here. (covering: Audioboom, Carrs, Mothercare, and Judges Capital)
QUIZ
This is a Glasgow-headquartered fashion retail business - physical stores, and online. It's in the process of floating on AIM, at a £200m market cap. Being my specialist sector, I was keen to meet management. I attended a group meeting earlier this month, and reported on my (mostly positive) thoughts here.
After much pondering, I decided to apply for the Quiz IPO, through my broker. Most placings are only available to investors who are classified as professional investors by their broker, or who meet suitability rules. It seems ridiculous that there are restrictions on who can buy new issues. Yet anyone can buy any share in the aftermarket, without any restrictions applying. Seems daft to me.
Anyway, the good news is that I think this is likely to be a successful new listing. The reason is that the allocations fell within the goldilocks zone - so there was enough excess demand for the new shares to make it a success, but not so much excess demand that allocations were derisory. Mind you, people tend to over-apply for the good placings, expecting to be scaled back.
There is an RNS here giving schedule 1 information. I see that the great & the good of institutional small cap investors are on board - e.g. Hargreave Hale 6.5%, BlackRock 5.0%, and Slater Investments at 3.1%.
The shares start trading on 28 Jul 2017. My hunch is that they're likely to go to a premium, but time will tell.
IQE (LON: IQE)
(in which I hold a long position)
There was a remarkable move up yesterday, on strong trading news, which I reported on here. For anyone (like me) who doesn't really understand what the company does, there is an outstanding video here from PI World, by IQE's CFO, at Mello Beckenham, in Jan 2016.
I think this presentation is an wonderful example of how to explain complicated technical subject matter in a completely accessible way. This should be used as a teaching aid, the presenter is that good.
Arguably I should have done my research before buying the shares!
Retail Sales
I noticed that a lot of retail shares were more perky yesterday. This is because of more positive retail sales data from the ONS. I really must diarise to check this data when it comes out, rather than being behind the curve on it.
Here is the link to the ONS report - well worth a read, and they're straightforward. The main points section is below:
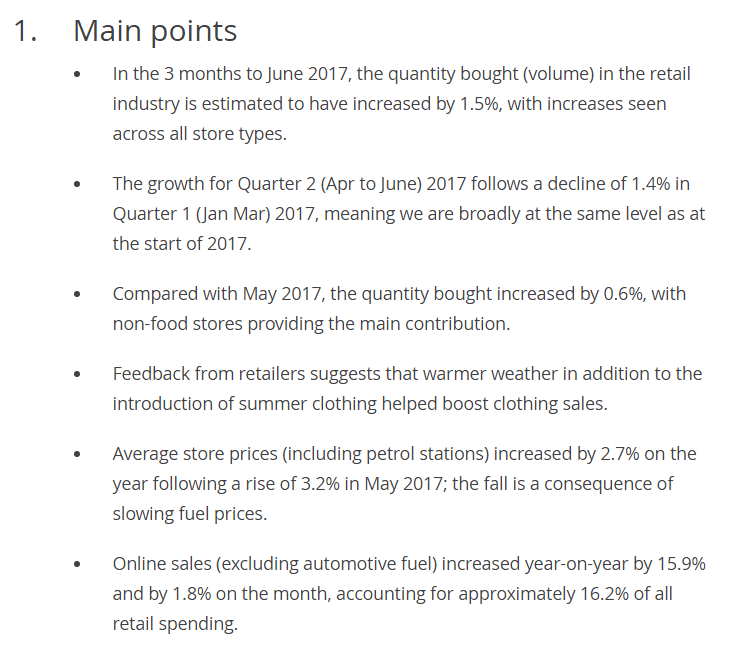
Remember that the above 1.5% is just sales volumes. As prices are 2.7% higher, this means that putting the two together, I make that about +4.2% in overall retail sales terms. That seems pretty good.
Looking further down the report, that seems to be an under-estimate, see table below:
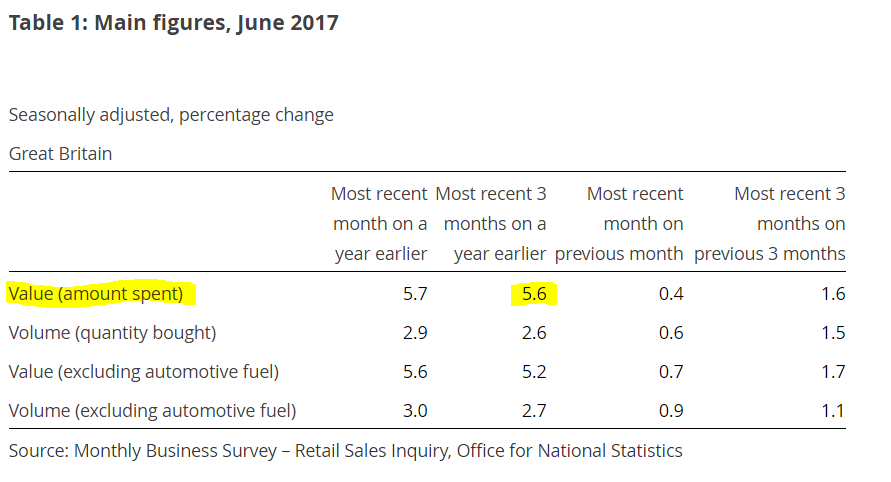
Total amount spent being up 5.6% on the prior year's Q2. Hmmm. That's actually really good!
So I've decided to close my short positions on retailers. We might even get some strong reports from retailers, maybe it's time to (selectively) go long? I've just bought back into Next (LON:NXT) at about 3820p. It might have another profit warning in it, but this retail sales data looks very good, so I think maybe that risk might be receding?
Good weather has helped the figures, although over a whole quarter, weather shouldn't have that much impact. Not for the first time in the last year, we have to ask ourselves whether all the doom & gloom is actually justified? That said, retailers are under ongoing pressure from growing online competition, plus many cost headwinds. So it probably won't be plain sailing. We shall see.
OK, that's my bonus report done. I'm off out for lunch with a very interesting charity which I support, providing desperately needed aid for the poor in Zimbabwe, called Zane.
Zane is highlighting in particular, how elderly ex-servicemen, and their families, all over the Commonwealth, have been abandoned by the UK Government, despite them having fought for us in years gone by. We need to lobby Government to use some of the bloated overseas aid budget to provide vital support & healthcare, to ex-servicemen in the Commonwealth, not just those in the UK. If people fought for the UK, then the military covenant should extend to them too.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Re: IQE (LON:IQE) being taken over? I think it's a definite possibility! Let's hope UK investors are savvy enough to make it sufficiently expensive beforehand.
Paul,
A further reason to participate in a placing is Subscribed share Income Tax loss Relief in the event of a loss.
Just a quick point about how rich a country we may or may not be. People often quote this based on GDP for the whole country, making no adjustment for the number of people living here or purchasing power.
A better measure is GDP per capita PPP. The different organisation such as IMF and World Bank come up with different numbers. But if you look at these figures on Wikipedia you can see that the UK doesn't actually make the top 20.
In other words there are lots of countries that may have a smaller economy than us but they are richer per person than we are and so more able to afford to spend more on overseas aid.
JB's comment still applies, JE. 2% of tax take is not a large sum for the 5th richest country in the world to be paying. And it's well known that foreign aid has positive diplomatic and economic advantages to the donor countries - a lot gets paid back in contracts.
That 5th richest country in the world statement irks me every time I read / hear it. It is true, but utterly misleading.It's usually accompanied by Why can't we have X,Yand Z when we are the 5th richest country in the world?
Another truth is we spend more on healthcare than Norway, Sweden and Canada combined. If anyone thinks the UK is richer than those countries they are, at best, confused.
The stat that counts is GDP per person, not in absolute terms.
Sorry, personal hobby horse.
It's 0.7% of Gross National Income, not taxation.
UK tax is roughly 34% of GNI, so foreign aid is 2% of the tax take.
Bloated overseas aid budget? 0.7% of the UK spend? Or a massive 7p of every £10 of tax? I think that's the absolute bare minimum a wealthy civilised country should be spending to help, for instance, victims of the Nepal earthquake, or provide access to effective TB treatment, or working to eradicate polio.
,
"We need to lobby Government to use some of the bloated overseas aid budget to provide vital support & healthcare, to ex-servicemen in the Commonwealth, not just those in the UK. If people fought for the UK, then the military covenant should extend to them too."
Absolutely - Foreign Aid isnt being spent, in full, nor properly - splashing cash on Saddam Hussein's palace, or the Ethiopian spice girls is not how the money should be used.
Charity should go to those, first and foremost, British citizens in need, such as veterans...And then to those who fight for us.
Eg Nepal. *Long term supporter of Gurkha Welfare Trust"
Eg Fiji
Paul, ZANE is a really excellent small charity that needs support badly. It does a huge amount despite limited resources and gets no government cash. No distended secretariat costs either. I suppport them from time to time and you have reminded me to send them a cheque!
Cheers,
Mark
Mark,
Absolutely, ZANE is a terrific charity. They raise about £2.5m p.a. from private donors, but don't even have an office! Everyone works from home, and they're all part-time self-employed, so that the charity doesn't incur any costs or liabilities of having employees. Really impressive stuff. ZANE must have saved thousands of lives, by giving out small cash grants to the needy in Zimbabwe, where conditions are absolutely atrocious. It's a really inspiring small charity. I try to bung them over a donation every now & then, if I've had a good run on the markets.
Regards, Paul.
RE RBG burger & cocktail offer - unless I've misintepreted this is covering the "Revolution" branded stores as opposed to the more upmarket "Revolucion de Cuba" ones as when I specifically look at one location where I know that there are both it points you at the Revolution brand one.
While there is clearly possible cannibalisation between the two brands, from what I have seen they get materially different clientele with the Revolution brand attracting the younger age range (who in crude terms are more happy with a pizza, a pint and a table of shots) as opposed to the "de Cuba" side of things which is materially more upmarket both in terms of decor and price. It also attracts a more mature consumer.
Cheers,
0inK
Re: RBG burger & cocktail for £9, agree can't be much profit in that - maybe just to get them in !
Is this the sort of food they sell? The pictures look mediocre & do people who buy expensive cocktails really want to eat burgers or pizzas ?
Still holding but watching like a hawk.
D.
The competition in the restaurant sector must be hellacious at the moment. I see that your pick Revolution Bars (LON:RBG) are doing a burger/pizza and cocktail for just £9. Terrific value, but surely margins are going to take a pasting?
https://www.groupon.co.uk/deals/revolution-bars-pizza-burger-nationwide?CID=UK_AFF_5600_225_5383_1&utm_medium=afl&utm_campaign=206616&mediaId=531&utm_source=GPN&subs_group=afl
PayPoint (LON:PAY). I know they are probably way over your size limit now, but your interest and insight in the past (2014) into this in some ways strange and controversial company make them interesting!
Today we have an acquisition AND a bid! The bid is complicated and I dont see any reference to the Board of Directors recommending it. One largish shareholder - Old Mutual with 10% - wants out, but nothing more than that. The only other largish shareholder on the website (Fidelity - again around 10%) makes no comment.
Your comments would be very much appreciated on the content of the bid and the exact timing juxtapoisition of the acquisition and the bid.
Hi ridavies
I can't see any ref to a bid in the RNS announcements or to an acquisition for PayPoint (LON:PAY).
As a holder would be very interested in where you picked this up.
Thanks
Think they mean Paysafe (LON:PAYS).
The bid is for Paysafe (LON:PAYS)
Shares up at 580 based on the 590 bid. This is a low take over bid of only 9% premium on yesterday's close.
Sory. My non-deliberate mistake - Paysafe (LON:PAYS) not PayPoint (LON:PAY).
Arguably, Paul, you should have done your research first. And then you would have missed the tide and ended up buying IQE at a 20% higher price. There is no point in adding lots of shares to a Watchlist that never gets researched. So it can be better to buy first and check it out when you have a bit more time.
I will be doing some more checking on IQE over the next few days and might add to my initial holding if it looks good.
Thanks as always.
IQE, is there any reason why this company would not be taken over? It has been very successful, would it make it sense for one of the companies it supplies to, to take it over?