Small Cap Value Report (Fri 22 Feb 2019) - Ryanair how-to guide, FLYB, MERL, NSF/PFG

Good morning!
Today would be a good choice for a duvet day given the lack of news flow, but I will keep the show on the road.
Ryanair Holdings (LON:RYA)
Did anybody notice that Ryanair Holdings (LON:RYA) was fined €3 million by the Italian authorities?
As a frequent flyer and occasional Ryanair customer, it's nice to have a moan about it sometimes.
For context though, I do celebrate the era of cheap air fares which was created and sustained by Michael O'Leary. While it doesn't happen as frequently as it used to, I still fly with Ryanair from time to time, when their offer is too good to pass up.
Indeed, last month they brought me and my lady to Athens for a bargain price - no complaints about that at all!
But where they let themselves down a little bit is that they have turned the booking process into an IQ test and a test of your nerves. Booking a flight is now a game in which they try to tempt you and trick you into buying things you don't necessarily want, and you try to spend as little as possible without making your flight experience completely miserable.
For example, this is what I was greeted with when I put a dummy flight into their system this morning, and clicked on an offer advertised as "from €19.99".
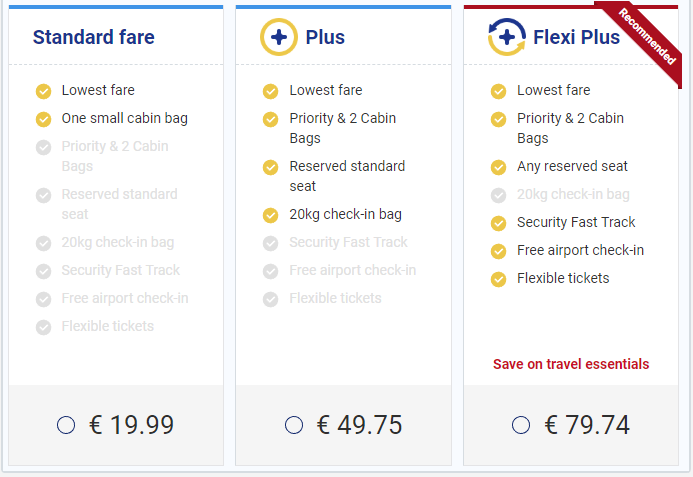
Hmm. This is less attractive than it seemed at first glance!
If I spend €19.99, then I get the "lowest fare" but it looks like I only get to bring "one small cabin bag" on board. How is that going to be appropriate for an international flight?
On the other hand, do I want Priority & 2 Cabin Bags and a 20kg check-in bag, and a reserved seat with the Plus option? Not really.
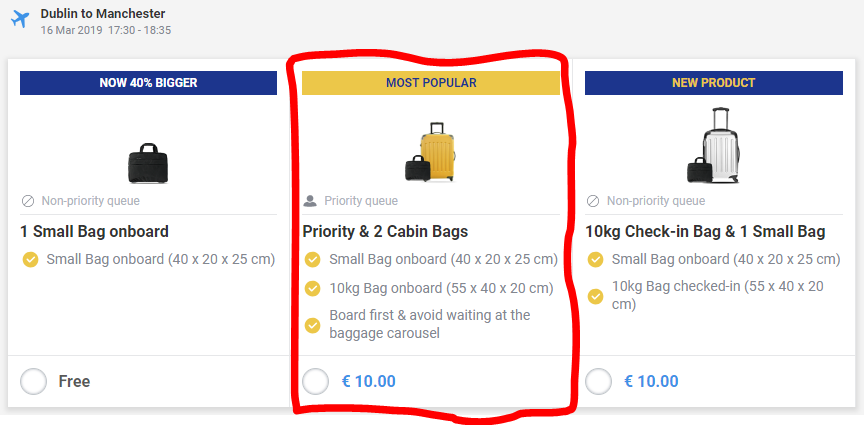
The way to beat them is to bravely click the cheap Standard Fare option for both the outbound and return flights, then Continue.
On the next page, Ryanair will give you the option you really wanted: the 10kg cabin bag. It's cheap and it comes with priority boarding for €10.
After insisting that you don't want to pay to reserve a seat*, you will finally be given the option for a 20kg bag. Good for holidays and longer trips!
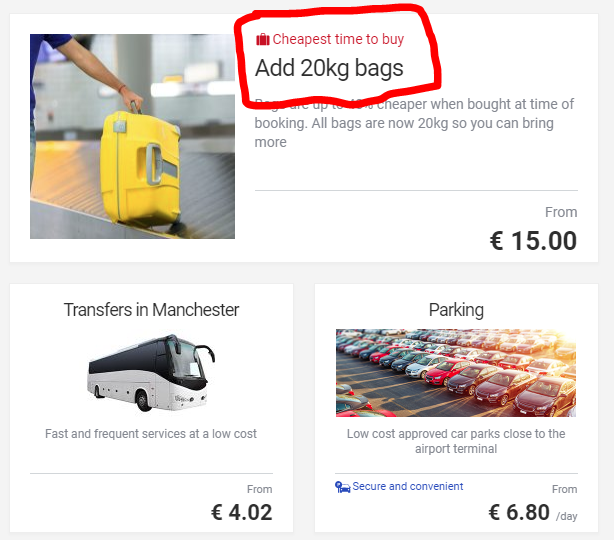
(*Be careful about not reserving a seat if you are travelling with someone or as part of a group. A study has found that there is a 35% chance of being split up by Ryanair, about double the probability at other airlines.)
So whether you want a 10kg or 20kg bag, you can get them cheaply. You just have to proceed bravely through the booking process until you are offered them on a standalone basis.
Italia - Il Rifiuto
Italy has had enough of this, and similar carry-on with carry-on bags at Wizz Air Holdings (LON:WIZZ). Both airlines have been fined, although Ryanair Holdings (LON:RYA) gets the much larger €3 million fine for failing to suspend its baggage policy, as requested.
The Italian regulator has argued that:
"The request for supplementary pay for an essential element of air transport, such as hand baggage, provides a false representation of the real ticket price ... misleading the consumer."
I would have to agree with this. How can it be reasonable to say that the price of an airline ticket is X but you can only bring a small bag with you at that price. Is anybody capable of making a flight with just a small bag? Even if the answer is that 1% of passengers can do it, a headline price should not be unsuitable for 99% of potential passengers. The headline price should be the price with a 10kg bag, and there should be a discount if you don't need it.
From Ryanair's point of view, surely they realise the damage that this practice must be doing to their reputation? On my flight to Athens, there were not one but multiple instances of passengers who had been caught out by the booking process.
They had brought luggage to the gate which they presumed they were entitled to bring on board, only to be told that they had no such entitlement. Some of them had paid for hold luggage, while others had paid for no luggage at all.
And if lots of passengers aren't paying enough, there must be other passengers who are accidentally paying too much. This might seem like a good thing from Ryanair's perspective but why not simplify matters and help people to get the option they really want? Are you listening, Michael O'Leary?
Ok, I should probably look at one two RNS announcements.
- Flybe (LON:FLYB)
- Merlin Entertainments (LON:MERL)
- Non-Standard Finance (LON:NSF) & Provident Financial (LON:PFG)
Flybe (LON:FLYB)
- Share price: 1.49p (-27%)
- No. of shares: 217 million
- Market cap: £3 million
Completion of Sale of Flybe Ltd and Flybe.com Ltd
Most shareholders will have left the building by now but there are still a handful in the Denial phase of the grief cycle, judging by the trades placed this morning.
Management have sold the group's operating subsidiaries, against the wishes of many shareholders, and the deal closed last night.
FLYB shares now represent ownership in a shell whose only asset is a small amount of cash swirling around, and the right to be taken over at 1p by the the buyers of its subsidiaries.
Management are definitive on this:
The Flybe directors strongly advise shareholders to vote in favour of the Scheme at the shareholder meetings on 4 March 2019 in order to receive the consideration under the Scheme of 1 pence per share as otherwise shareholders are likely to receive no value for their shares in the Company.
Given the scale of shareholder dissent, it can't be ruled out that the Scheme could fail and that some sort of legal challenge could be mounted by someone.
I'm not a legal professional, but I don't see what sort of recourse the dissenting shareholders might have. It seems to me that shareholders are overweight anger and frustration, but are underweight any real prospect of a better financial return.
Management are giving notice to the LSE that they wish for the listing of FLYB shares to be cancelled and intend to wind-up the company if the Scheme is not approved.
If I owned FLYB shares today, I would be selling them immediately at any price greater than 1p.
Merlin Entertainments (LON:MERL)
- Share price: 364p (-0.5%)
- No. of shares: 1.02 billion
- Market cap: £3,722 million
Another big-cap gets mentioned in the SCVR but I have a really positive impression of Merlin and have been thinking that it might make for an attractive buy-and-hold, so I noticed when this RNS popped up.
It is selling its Australian ski resorts for £95 million. Proceeds will be used "for general corporate purposes".
The rationale is to enable Merlin to focus on theme parks and Midway attractions (incorporating Madame Tuassauds, The Dungeons, LEGOLAND Discovery, etc.)
It's a green flag for me when a company sells off non-core activities to focus on its core competencies. It's essentially the reverse of when you see companies diversifying into categories where they lack any real expertise.
I have a good impression of Merlin's brands and of management stewardship, with the guidance of the LEGO family who are 30% shareholders. It's a capital intensive business, but a very good one.
Non-Standard Finance (LON:NSF)
- Share price: 62.1p (+8%)
- No. of shares: 317 million
- Market cap: £197 million
Firm offer by NSF for Provident Financial
Response to Offer for Provident Financial
NSF management, led by John van Kuffeler are making a play for the reverse takeover of Provident.
Van Kuffeler was the CEO of Provident from 1991 and Chairman from 1996 (he was Chairman for some 17 years).
The approach for Provident today is scathing of its current management, claiming that it suffers from a long list of problems including the Board's "limited operational experience", "cultural challenges", an "inability to deliver shareholder returns", "regulatory failures", and so on.
The deal will "return Provident's culture to one focused on positive customer outcomes, working closely with regulators". In a letter to Provident employees, van Kuffeler says; "We understand the problems that some of you are facing and have a clear plan to address these." Ouch!
Many Provident shareholders agree and three of the top four holders (Woodford, Invesco and Marathon Asset Management) have provided irrevocable undertakings or letters of intent to vote their shares in favour of the deal. Together, they own just over 50% of total PFG shares outstanding.
This puts Provident directors in a tricky spot. Even if some of them would like to oppose the deal, they can see that there is an uphill battle to be had with their own shareholders.
Indeed, we have confirmation that Provident directors tried to prevent this transaction from happening before:
We have recognised the strong logic and value creation potential of a combination with Provident for some time and hence approached the Provident Board with a proposal in January last year. That approach was rebuffed and since then Provident has further lost its way... I'm delighted that holders of over 50 per cent. of Provident's shares have given their support to our proposal today."
My view
It's an ambitious play. While the combination of the NSF/PFG businesses should lead to material synergies and cost savings, the more important element of the deal might be the change in culture as Provident goes back to its roots.
Provident shareholders would own 88% of the enlarged group, which according to my calculation is perfectly in line with the market caps of the respective companies as of last night. So it's a straightforward merger and a replacement of the bigger company's management team by the smaller company's team. Given their respective performances in recent years, it sounds like a sensible idea.
Have a fine weekend everyone.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
re; ryanair the added extra's are there con trick. im off to benidorm 5 march and the extra's are a joke, i wont ever book again ryanair,also they said if you dont book seats and we over booked you may not get on flight this needs to be sorted as blackmail. at least jet2 include everything .
Couple of snippets:
1) Re Duke Royalty (LON:DUKE) - I've recently been looking into the Royalty partners, to (try to) obtain figures from their accounts for the past 3 years, not only see if they're able to service the royalties, but also if there's an upward trend in revenue/profits etc. A bit more difficult than going through an Annual Report, and even more so with the overseas companies !
2) Re Flybe (LON:FLYB) - The 'shareholder approval to move from a premium listing to a standard listing' in hindsight, seems calculated. I wonder if this proposal is searchable on AGM notices/RNSs, and if so would enable investors to have a serious think as to why.
Keep up the good work Graham whilst Paul's away, although he may come back with investment idea for Zimbabwean mining companies ! lol
I went with flybe last weekend and they are worse than any other carrier they checked every case with a box placed over each case. Several people caught out with cases two big that resulted in £50 charge, caused delays boarding aircraft and both flights delayed due to this issue would avoid flybe next time flying!
Also FlyBe's carry-on case size limit is just that bit smaller than almost every other airline. So your bag that you've been happily using on Ryanair / easyJet (for many years) may result in extra charges with FlyBe.
I understand that the Credit Card Companies were holding back £50 Million of Flybe Ticket money in case the company went into liquidation. Can anyone tell me what has happened to the £50M now that the company has been sold for £2.2M?
I understand that the Credit Card Companies were holding back £50 Million of Flybe Ticket money in case the company went into liquidation. Can anyone tell me what has happened to the £50M now that the company has been sold for £2.2M?
Not quite, the money was collateral against flights that have been paid for with credit cards and not yet flown. Most of it will flow back to customers. Broadly it works like this ...
The "Credit Card Companies" referred to are not Visa or Amex but Acquirers. Acquirers have a relationship with the merchant (Flybe in this case) and they direct a credit card payment request to the right payment scheme (Visa, Amex, etc) who pass the payment request onto the bank. When the actual funds are settled they're moved from the bank, via the payment scheme to the Acquirer who then pays the merchant.
For credit cards, as we all know, there is a right of refund - a 'chargeback' in the industry lingo. This can happen for many reasons but in this instance it means that every customer who paid with a credit card and didn't get their flight has the right to contact their bank and request their money back. The bank pays out to the cardholder and then sends a request for payment to the Acquirer.
Normally the Acquirer pays the bank and then reclaims the money from the merchant. But if the merchant has gone bust then the Acquirer is on the hook. Because of this if Acquirers decide that the merchant is looking a bit dodgy then they'll ask for collateral - actual cash - upfront to cover the chargeback liability. Which is what happened to Flybe.
Broadly the amount of cash that the Acquirer will require will match the risk exposure that they're taking. So if Flybe have £50 million in unflown flights on credit cards then Acquirers would want some function of that based on their risk assessment. In high risk cases then they'll probably want to have all of their risk covered, especially if they can't get insurance cover (which was probably the case with Flybe).
The Acquirer can receive chargeback requests for up to 120 days after the payment - so roughly 4 months. Only after 4 months would they know how much of the collateral has remained unclaimed - at which point it would be refunded to the administrators.
I would be extremely surprised if much, if any, money flows back to Flybe as I'd imagine that nearly every Flybe credit card customer will be exercising their chargeback rights. Indeed, if the Acquirers were a bit lax on collateral they may end up being creditors themselves.
timarr
I would be extremely surprised if much, if any, money flows back to Flybe as I'd imagine that nearly every Flybe credit card customer will be exercising their chargeback rights.
I don't think I understand this point, Tim. Since Connect will be running the operations "as before", at least for now, those booked flights should be flown, so there should be no chargeback due to customers, in most cases. Though that does raise the question of where the money flows to - Connect who operated the flight, or Flybe who initiated the booking? I'd suspect the former, so either way nothing much is going to come back to Flybe
I don't think I understand this point, Tim. Since Connect will be running the operations "as before", at least for now, those booked flights should be flown, so there should be no chargeback due to customers, in most cases.
Hi Peter
I'm not really familiar with what's happened at Flybe (I'd rather buy a lottery ticket than airline shares): I'd lazily assumed that they'd gone into administration and customers had lost their flights.
But having has a quick look at the situation I agree with you. Either Flybe assign the Acquirer collateral to Connect - essentially it's deferred income on flights already booked - or the deal collapses and the customers claim the chargeback. Nothing comes back to Flybe either way.
What I'd note, though, is how valuable that credit card protection is. I can never understand why people buy online using debit or Paypal, or even use a Paypal type intermediary for credit cards, it's just an unnecessary risk.
timarr
Thanks for the very clear in depth reply, I was hoping that I might get some of my money back!
I've flown with Ryanair many times - probably getting on for 100 by now, and throughout the years that I've used them it has been the game that Graham refers to in the header, with Ryanair trying new tricks at least every six months to get extra cash from you.
However, there comes a point where enough is enough, and I believe Ryanair are now on a slippery slope which will lead to a drop in share value (last week we flew Easyjet for the first time in ages).
The jiggery pokery with bags is bad enough, but to me Ryanair's continuous battle stretching over probably the last five years, to make people pay for an allocated seat takes the biscuit. It started about five years ago with free seat allocation only for check in reduced to less than 2 weeks before flying - the obvious intention being that most people go on two week holidays and would feel forced to book seats at least for the return. A year or two later this slot for online check in with free seat allocation was reduced to only seven days before flying, with the same obvious intention. Then it was reduced to three days, then to two days - all with the same motive, imho.
But this technique didn't work on some battle hardened Ryanair customers. During all of that period up to approximately a year ago, my wife and I would use the reduced check in slot. Each time, ie, many many times, until a year ago, we were allocated free seats together, with the worst situation being once either side of the aisle.
Then a year ago Mr O'Leary came up with a new ruse. If you used free check in without paying for an "allocated" seat he would send us to opposite ends of the aircraft. He came up with a real load of bullshit to try to justify this when questioned by consumer organisations, but it was soon seen as the bullshit it was, by regular customers.
Four times in the last year, we have been sent to our respective ends of the aircraft as punishment for not paying up, only to find that the person sitting next to my wife at the back was the partner of the person sitting next to me at the front - with the obvious solution to that punishment regime, quickly undertaken. Very clear evidence imho, that this is just a deliberate ploy to get extra cash with no truth in the justification offered.
But the baggage nonsense seems to me a step to far, so it's goodbye Mr O' Leary.
"I've flown with Ryanair many times - probably getting on for 100 by now, and throughout the years that I've used them it has been the game that Graham refers to in the header, with Ryanair trying new tricks at least every six months to get extra cash from you.
However, there comes a point where enough is enough, and I believe Ryanair are now on a slippery slope which will lead to a drop in share value (last week we flew Easyjet for the first time in ages)."
Wow you're patient
100 flights.
Such behaviour would be enough for me after 2 -3 flights and I'd never fly with them again. As I have never done with British Airways since 1980's....
Fangorn,
Our tolerance of Ryanair's foibles was mostly due to the fact that they had more flights to and from airports that suited us, as well as the fact that they tended to be lower cost, with flight times that avoided 4am starts etc. We used others, in fact we were due to fly Monarch a few days after they went bang, but the latest ruses by Ryanair did the trick and made us look harder at alternatives.
The following clip from Fascinating Aida contains a lot of swearing on the subject of cheap flights and makes me laugh quite a bit..
https://youtu.be/ZAg0lUYHHFc
Thank you for your observations on Ryanair Holdings (LON:RYA), Graham. I agree with them apart from giving credit to Michael O'Leary for starting the era of cheap air fares. Easyjet (LON:EZJ) started up around the same time and Stelios Haji-Ioannou freely gives credit to Southwest Airlines in the USA for their innovation in this area many years earlier, and which he copied. I'm not a frequent flyer but I've used Easyjet quite a lot and Ryanair when I have to. I've always wondered why other airlines didn't just copy the Easyjet web-site for booking flights. In my opinion it beats the others hands down, and always has. I hold no shares in airlines but wished I'd bought Easyjet when I started using their services many years ago. Not as much as I regret not buying Apple shares when I started using Macs in the mid-1980's mind you.
I always thought it was Freddie Laker who started the "heap flights revolution. UK to USA for £32. (admittedly, back when £32 was worth something!)
Thanks. Very much agree on Ryanair. The internet allows customers to go online and compare prices, and companies respond by making their pricing less transparent.
Companies think that they are being clever. But eventually consumers will vote with their wallets, and avoid the worst companies. For instance, I have flown Ryanair in the past, but it is really a last resort and has to be a really cheap price for me to go through the horrible customer experience.
CMC Markets (LON:CMCX) profit warning at 2.21pm today. Can't understand why they couldn't do it at 7am.
I'm not a holder but considering IG Group (LON:IGG) who are 6.3% down at time of writing
Cheers
Francis
it does look like IG Group (LON:IGG) shareholders like myself are having a tough time climbing back up from each market blow. Hopefully Jan Interim results guidance will not be blown off course.
Been cut quite a bit by falling knives on this one
IG Group (LON:IGG)
Looking at the stockopedia numbers the 2019 and 2020 profit expectations have been steadily declining for some time now with even lower numbers appearing this month.
with regard to january guidance holding good - did they not just say they expect sales to be lower and expenses would be the same - that doens't exactly seem any kind of useful guidance whatsoever without a range for their estimates of earnings. Perhaps more info is there and i failed to find it by looking at the outlook section.
Naughty intra day trading update just out from CMC Markets (LON:CMCX) .
https://www.investegate.co.uk/cmc-markets-plc/cmcx/trading-update/201902221421059064Q/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=CMC%20Markets%20Plc%20Alert
Effectively a profit warning and shares have dipped 10% in reaction. One would have thought a spread betting company might know better/behave differently, especially in light of the recent sector volatility engendered by Plus500 (LON:PLUS) .
Gus.
Re Non-Standard Finance (LON:NSF) reverse takeover of Provident Financial (LON:PFG)
Wow. Blindsided again! NSF is my largest personal shareholding and I agree (with NSF !!) that the NSF management team are excellent; that the NSF business is undervalued; and that the the reverse is true at Provident Financial (LON:PFG). However, I need to think if I like the plan to do a reverse takeover of PFG which was never mentioned in any of its investor presentations which I have seen or read. Interesting to read they approached PFG last year about a deal! Much bigger and riskier bet IMHO.
For me NSF was a relatively small, successful and specialised business with good management and steady prospects of high dividend returns from an unfashionable area for many years. By end 2018, it had reached the end of its major investment phase for the 3 businesses it bought. All have been developed well and hold leading positions. I was confident it would be in very good shape in 2-3 years.
Taking over PFG relatively cheaply MIGHT be a great idea if it goes through smoothly and the plan works out. But there is a risk that the transaction does not go through (costs to write off) and the execution may not work out.
Certainly, getting into credit cards is certainly high risk at the moment after the consumer card debt build up of recent years. The reason I liked NSF was that I thought its areas (branch based unsecured lending, guarantor lending, home credit) were relatively lower risk segments which as a distinguishing factor had face to face interviews to reduce risk of impairment (vs remote & online peer competitors, not prime lenders). Is the extra risk worthwhile??
At the end of the day, the proposals look sensible and I trust the NSF management.
I like the streamlining of PFG from spinning out i) the vehicle finance arm, Moneybarn. Aside from recent regulatory issues, this is a good business that is only lightly related to the consumer loans business. It will do better on its own or be bought by an insurance specialist and will sell off well. Selling off Loans@Home consumer credit is I think is a sop to the regulators (it was no 3 and a challenger so combining it with 50% segment share leader Provident and will not get a great price since if NSF mgt really know what they are doing they will remake Provident Home Credit into a better competitor and have x5 the scale in Home credit. Perhaps Morses Club (LON:MCL) will look to take it over in time since it would expand their core offer and arguably increase competition ( by making them 30% market share vs Provvies 50% segment share, with smaller players exiting as the segment shrinks and increased regulation makes it unattractive to small players)
However, the bigger bet is that integrating EveryDay Loans (branch based lending) and the Gurantor lending Division(Trust Two for consumer facing and George Banco for brokers) with Vanquis bank and Provident's credit card make sense. I think it does and could make EveryDayLoans unique national network of (sub prime/non-standard) branches a small goldmine with lower financing cost and a bigger scale. Equally, Amigo Holdings (LON:AMGO) showed the potential for guarantor lenders and NSF is already no 2; this takeover would turbo charge its ability to grow share in this space and block other new market entrants probably leaving a very profitable duopoly.
NSF management have kept it simple and focused on creating a positive culture in a difficult, highly regulated area.
Interesting that Woodford and Invesco have so publically backed the NSF management team. If it does not work out then shareholder meetings between them and current PFG Board will be difficult - so much so I think there is a risk they may become sellers.
After reflection, I am coming round to being excited by the deal. PFG has a great history but been a recent train wreck. Biggest risk may be that the 'glue' for the deal is the ex PFG CEO and Chairman, now NSF CEO John van Kuffeler is aged 72. Will he have the time and energy to see through both the takeover and the subsequent planned changes?
Lack of News (2) today, how about Provident Financial being approached in a sort of reverse take-over? It's big news for me at any rate as I could, and should, have sold the shares I hold when they were worth six times as at present.
Good luck getting Ryanair to pay out any compensation for delayed flights, whatever you may think the EU laws say! Ryanair take a different view of their obligations.
My daughter and boyfriend were returning from Luxembourg to London last year. The flight was delayed many times and eventually it would have needed to take off after midnight which is not permitted by the Luxembourg airport authorities. So Ryanair would have had to book everyone into a hotel for the night.
Instead they diverted the incoming flight from Stansted to Frankfurt for unspecified safety reasons. Frankfurt is further away than Luxembourg. They then bussed everyone from Luxembourg to Frankfurt and left them in the airport till 6 in the morning when they returned to Stansted.
So my daughter and boyfriend put in a claim. Ryanair sent an unsatisfactory response. Then they went to the Avation ADR alternative dispute resolution service. Ryanair didn't respond to the arbitrator. Then Ryanair withdrew completely from the arbitration service, which was supposed to have been binding on them. Now the case is with the CAA who are considering enforcement action, but can't say how long that will take.
Never been with Ryan Air, and I don't think I ever will. It's like buying a car, only to be asked if you want wheels, seats and a steering wheel with it.
I'm sure your comments about Ryan Air have struck a chord with many of your readership Graham. As for asking if Michael O Leary is listening to the criticism: Well, he's an intelligent man, I'm sure he's perfectly well aware of it. I just don't think he gives a damn what anyone thinks. He's simply hell-bent on screwing as much money out of his customers by fair means or foul.
I have long thought Ryan Air were OK, but they lost my goodwill last year when their website was trying to charge about £32 for my carry on bag which met their previous size spec and always fitted under the seat. I found a cheaper and more convenient alternative (Flybe !).
Their new pricing structure simply is a way of gaming the flight price comparison websites, as they always show a good Ryan Air price, but you never get to pay it.
Well done to the Italian authorities for fining them. I am also impressed with the way the Italians fined a couple of the big phone makers for slowing devices down, which is another area in need of some major fines for malpractice.
Disclosure: I have a no airline stocks policy.
What I can't understand, is that Ryanair have been fined, but doing a dummy booking (Milan Bergamo to London Stansted) reveals the same type of pricing that Graham was moaning about - a low price for a small bag, but £10 to bring on the old-style luggage.
So Ryanair have been fined but still continue to operate the same way, it seems to me.
I kind of sympathise with Ryanair, in some of my previous experiences people tend to take the proverbial with the policy and their fleet of 737s were not designed for a full load where 80%+ have a roll-on. The new policy heavily favours bags which are more efficient to stow, in a Tetris-type of way.
On the other hand, it does seem like a fare raise by stealth. I do wonder if there will be EU-wide regulations against this type of thing, or even for there to be a standard definition of what is considered hand luggage.
Seems to be if Ryanair fall a bit short, they could simply reduce the size of what is considered 'carry-on' and more people would be forced into paying.
Maybe they stopped for Italian customers only?
In any case this nano-fine is far too small, someone like Michael O’Leary is just going to do a back of the envelope calculation whether the estimated benefit of this behaviour is greater than the fine, which is likely the case if you don’t count externalities. Developed economies rely on trust, where you can assume you get OK terms by default, the cost to everyone of contributing to destroy this is enormous.
I agree. It's meaningless, and perhaps might be only a window-dressing type thing.
Can't see the Italians pushing too hard in case O'Leary threatens to take his planes away. Some of the secondary airports in Italy have Ryanair as their largest customer.
Booking airflights and holidays has become increasingly stressful I find. This all comes down to a plethora of 'choice' issues presented in a complex way it seems.
I know we are supposed to be fans of choice, but you have to be dedicated keyboard warrior in most instances.
British Airways website is not particularly clear about the choices they offer, and its all about chiselling extra value in a low margin business. Pre-booking seats has now become monetised, and when they offer their flight prices, it isn't wholly clear what the total price is because of the sundry other prices that are listed. I wonder how many inadvertently book a transfer, hotel, hire car or other, or don't realise they are only allowed to take hand baggage, because they clicked the wrong box.
We have all had to become part-time travel agents. No wonder UK productivity has dropped. Ok, most people historically spent some time at work booking their holidays, but now it could be their principal occupation with side dish of work, just to finance the holiday preparations!
Lack of News? How about Dairy Crest's recommended sale to French Canadian Sabuto?
Graham commented on the slightly unusual type of acquisition/funding by Duke Royalty (LON:DUKE) this week and i have been looking at the company concerned.
MRDB Holdings is described as trading as Miriad Products. Looking up Miriad in Companies House its latest data (to 31 Dec 2017) shows that Miriad only has sales of £8.17mm as opposed to the £21.2mm stated for the group in the announcement.
The balance of the sales appears to be in Liberty Leisure (£13.0mm) so it is not entirely clear how the trading moves here but perhaps there are tax advantages for this arrangement.
Although Liberty is 100% owned by MRDB it is of interest that Miriad is only 89.5% held by the parent.
There is no suggestion that there is anything untoward in these arrangements but in any dispute - and this is a 30year deal - the problems most usually arise in the gnarly details and I would be interested if anyone has looked at this in more detail
Look at the group accounts
https://beta.companieshouse.gov.uk/company/06772302/filing-history
Revenue figure is ok
Ryanair have certainly ruined their reputation with me. I flatly refuse to even look at the flights they are offering. Having had three unpleasant flights with them. That were unpleasant purely because of the way they operate and not beyond their control, they have struck out as far as I am concerned.
Have had no trouble with Easyjet, Norwegian, BA, Emirates or any others even Georgian airlines with 25 year old
planes and a pitiful budget made it simple and pleasant earlier this year.
New styling from Boohoo (LON:BOO) ?
https://www.thesun.co.uk/fabulous/8485328/boohoo-dress-size-12-vagina-exposed/
Is there something I don't understand abut the Flybe (LON:FLYB) situation?
The RNS is clear - sale of the trading assets has completed. Either accept the 1p/share on offer or the shell company will be liquidated and you will get nothing. Yet shares are being bought this morning at 1.54p. Why? If I held shares I would be rushing to sell this morning at 1.41p rather than wait in the hope of 1p!
It does seem bizarre. I can think of a few possible reasons, non very convincing!
- Some people believe that Flybe have hidden assets they are lying about, to promote acceptance of the deal. Those "brave souls" who hang on think they will end up with more than 1p or zero.
- Or they think that the deal completed today will somehow be reversed, the CC companies will suddenly decide Flybe is much more financially sound than they thought and everything will be OK.
Unicorns seem to be in season at the moment.
re: Flybe (LON:FLYB)
It's pretty obvious isn't it! Markets aren't rational...
Hi Graham
re Flybe
The rational for continuing to hold the shares may be to qualify to vote at the forthcoming general meeting as announced in the rns released at 5pm this evening. The hope is that an independent new Chairman be appointed so he can scrutinise the actions of the current board in respect to how the sale of the trading subsidiaries came about. However, if in the meantime enough shareholders vote to accept 1p per share, then the company will be wound up before a new Chairman can be appointed.
A more general point is that the board gained shareholder approval to move from a premium listing to a standard listing. This means shareholders have no opportunity to vote to oppose the disposal of assets or the winding up of the company. However, I imagine very few private shareholders would have taken part in the vote to approve the move to a standard listing as it seems many brokers were not contacted by Flybe and therefore the brokers did not contact their clients to invite them to vote by proxy.
Many shareholders will most likely be more proactive chasing their brokers to allow them to vote to get a new Chairman appointed and hopefully to kick out the incumbent before it is wound up. Then there may be some hope that the board can be held to account for their behaviour as outlined by Hoskings in part 3 of today's requisition of a general meeting circular.
On an otherwise quiet day, Non-Standard Finance (LON:NSF) launching a reverse take over bid for the CEO's former Company Provident Financial (LON:PFG) is quite an "interesting" situation.
Would be nice to hear Paul's views on Inspiration Healthcare (LON:IHC) somethime (which I believe he holds).
Any comments on these two beauties from Haydale Graphene Industries (LON:HAYD) would be appreciated:
https://www.investegate.co.uk/...
https://www.investegate.co.uk/...
Massively dilutive placing at 2p. Shares were trading at over 20p at the start of the week.
Thanks as always for the excellent reports this week Graham.
Gostevie
Haydale Graphene Industries (LON:HAYD)
I have zero interest in Haydale but isn't it time that action was taken against individuals deliberately disseminating confidential information regarding forthcoming placements.
On his website on 19th https://guerillainvesting.co.uk/2019/02/19/haydale-graphene-huge-placing-closes-tomorrow/ Daniel Levy proudly announced a forthcoming placing at 60% discount (the price was about 23.5p and a price of 5p was mentioned elsewhere) . Needless to say, the price then plummeted about 50% to 11.5p. Obviously, the brokers would then have had no choice but to renegotiate the placing price with their clients resulting in the massive dilution seen today.
I make no comment about the need to make such a heavily discounted placing in order to persuade investors to subscribe but the deliberate driving down of a share price just to look big is surely inexcusable but I assume perfectly legal as the continued absence of action against offenders seems to indicate.
Maybe there was a bit of a whisper - he cites a a rumour circulating amongst the "bucket-shops." (whatever they are in this day and age). However often with these story stocks it's not hard to project their cash-flow and cash-balances and predict with a reasonable degree of accuracy the need for further fund raising. I haven't looked at Haydale Graphene Industries (LON:HAYD) to see if this were the case here, but I wouldn't be at all surprised.
Just glancing at the Stock Report - it shows they had £3m of cash at the end of June, down £2.9 in 6 months, despite raising £8.8m from issuance of shares in the 6 months. It seems a bit of a no-brainer that they may have to come back for more.
Whilst the company did see fit to comment on the rumours, I can't honestly see that there was anything terribly clever about the prediction.
Thanks Stevie!!
Sorry I'm not going to look at Haydale Graphene Industries (LON:HAYD). Sounds like rubbish!
G
Haydale Graphene Industries (LON:HAYD) latest results very poor. Losses widen, cash running out, taken a loan from Development Bank of Wales (blimey! Is that the tax payers money I see disappearing down the drain?). Placing to raise more funds to keep going. On the way to pico cap territory.
A Friday for wider topical investment news Graham?
Or as suggested a day off?
My morning smallcap tweet: Bye bye Flybe, Flybe goodbye*.
Mediazest (LON:MDZ), Flybe (LON:FLYB)
MediaZest (MDZ) keeps the lights on with £100k placing at 0.1p, a surprising nil discount. Mind you, 0.1p is the nominal value of the shares so they can't go lower.
Flybe Group (FLYB) sale of airline complete, leaving a worthless shell. Holders will vote to get 1p (or nothing if they reject) for the shares in March. And yet shares were still over 2p yesterday. * Bay City Rollers
Reckon you can go back to bed - Have a great weekend Graham.
There's no bed in the office I'm afraid! Only a soft, comfortable carpet.
(thanks - good wk/end to you too)