Small Cap Value Report (Fri 22 Jan 2021) - TEG, LUCE, CALL, TET, CCT

Good morning, it’s Paul here with the SCVR for Friday.
Timing - today's report is now finished.
Agenda -
Backlog items to start with (written up last night)
Ten Entertainment (LON:TEG) - full year trading update
Luceco (LON:LUCE) - FY 12/2020 trading update - strong Q4
Cloudcall (LON:CALL) - FY 12/2020 trading update
Today's trading updates/results:
Treatt (LON:TET) - Materially ahead of expectations update, but looks very expensive now
Character (LON:CCT) - 4 month trading update to 31 Dec 2020. Looks good value to me
Sorry I didn't get round to covering Works Co Uk (LON:WRKS) - I'm tired out after a really busy week, and have a Doctors appointment this afternoon. See a brief comment on it from me in the comments section below. I don't think it's madly exciting, is the quick summary!
Same with Zytronic (LON:ZYT) and Mysale (LON:MYSL) - I had a quick look at both this morning, and can't see anything interesting at the moment in either.
Ten Entertainment (LON:TEG)
205p - mkt cap £140m
Ten Entertainment Group plc ("TEG" or "the Group"), a leading UK based operator of 46 family entertainment centres, today announces a trading update for the 52 weeks to 27 December 2020.
"Strong growth potential, well positioned to take advantage of tailwinds on reopening"
Monthly revenues - the table below is very interesting, as it shows performance at the various covid stages in 2020. Key points;
- It was doing well before covid struck, with strong +LFL performance
- Full shutdown in April to July, so zero revenues (but support from furlough & business rates relief will have helped)
- LFL sales negative, and a worsening trend from August to year end, due to social distancing restrictions (only able to operate at 50% capacity) and regional lockdowns, I suppose.

.
Clearly that’s not encouraging information. I’m comparing this with some retailers, who saw a bounce-back of pent-up demand, and positive LFLs in the autumn. Not so here. Plus of course, a leisure business like this cannot move transactions online. The booking is done online, but it still is a physical experience to visit a bowling alley.
TEG’s sites were closed for 49% of the available time in 2020, and total revenues were down 56.9% on 2019 - pretty grim.
Loss-making - we’re told that (unsurprisingly) TEG will be reporting a loss for 2020, but it doesn’t tell us today how much the loss will be - a key omission.
Liquidity - is it going to run out of money? It raised £5m equity in March 2020 (doesn’t seem very much), and got cash burn down to £1.4m per month. It’s not clear if that means just for lockdown 1, or for the full period since then?
It closed the year with £12.4m liquidity headroom, enough to last for “at least another 8 months” if sites are still closed.
CLBILS term loan of £14m has been agreed with RBS - new information today.
Covenant on existing £25m RCF has been reset. Sounds like RBS are being very supportive, helped by a taxpayer guarantee on the new loan.
This assures liquidity well into 2022 should the Lockdown continue.
This sounds OK for now, but I imagine another placing might be a possibility at some stage, maybe once it’s re-opened fully?
Interim CEO Graham Blackwell has been appointed permanently now, with his performance praised by the Chairman.
Outlook -
- Pent-up demand
- Lane dividers mean that it can operate at 100% capacity in future (as opposed to 50% in 2020 mid-year re-opening)
- High 75% EBITDA margin, once allowed to trade again
- Reduced market capacity from competitors & casual dining closures
- No guidance, as little clarity on when they can re-open
- Expect rapid return of profitability, once allowed to re-open
My opinion - I previously held shares in Hollywood Bowl (LON:BOWL) and this one TEG, over the summer, and managed to catch a bit of profit on the vaccine re-rating you can see on the chart below.
However, given that the balance sheet will have taken on a fair bit of new debt over 2020, and only £5m equity was raised, then it stands to reason that this share should probably be worth a bit less than pre-covid levels, once it is able to trade normally again.
Plus we still have some uncertainty over how the future plays out.
For that reason, I think the share price looks about right.
I could see another, say 30-40% upside on this share price, if the sites are able to re-open smoothly and generate good sales & profits again. That’s not enough upside to tempt me back in, and take on the risk that something might go wrong, e.g. if the vaccine doesn’t suppress covid as quickly as we hope.
Also, I feel that the company should concentrate on reducing or eliminating debt, rather than paying divis, which means that it could be a while before it starts paying meaningful divis. Whereas I’m seeing other companies which are already resuming divis, and have more robust, less geared balance sheets. Those appeal to me more than this.
TEG was a good trade at around 130p a few months ago, but not so much now at 200p, where risk:reward is less favourable.
.

.
Luceco (LON:LUCE)
273p - mkt cap £440m
Luceco plc ('the Group' or 'Luceco'), the manufacturer and distributor of wiring accessories, LED lighting and portable power products, is pleased to provide the following trading update for the fourth quarter ('Q4 2020') and the year ended 31 December 2020 ('FY 2020').
This company has had an excellent 2020, with lots of positive updates. I covered it 6 times in SCVRs for 2020, and have been tremendously impressed with the company’s performance.
Strong trading continued in Q4 (revenue growth of +23%) -
The Group traded strongly in Q4 2020 and we expect to report record full year profits at the top end of the most recently guided range…. Adjusted Operating Profit of approximately £30m (FY 2019: £18.0m), primarily driven by significant margin improvement:
There’s lots more detail in the announcement, which I won’t repeat here.
Net debt - £18.3m, which looks modest, at 0.5x EBITDA
Dividends - reinstated, as previously announced
Diary date - 23 March 2021
Outlook - interesting that it mentions inflationary pressures, which is something we’ve been discussing here lately -
We have started the new year with good momentum despite tighter social distancing measures. Increased home improvement spending is likely to continue and new business wins, superior channel access and product availability should sustain further market share gains. Whilst we are now entering a more challenging inflationary environment, we aim to defend the significant margin gains we have made. Unless future lockdown measures severely disrupt our sales channels or distribution operations, we are confident of further revenue and profit progression in 2021."
My opinion - this company has done brilliantly in 2020.
Thanks to Liberum for providing an update note on Research Tree.
It has pencilled in 15.0p EPS for 2020, and 16.6p for 2021, PERs of 18.2 and 16.4 respectively. That looks a reasonable valuation to me.
The divi yield is 2.3% to 2.5% for 2020 and 2021 - worth having, but not the main reason to buy the shares.
Looking at LUCE’s history, I’m still not entirely sure what went wrong in 2018, when it had a very bad year, and the share price dropped about 80%. That does worry me. Could similar problems happen again?
After such a stellar share price rise in the last 2 years (justified by strong performance), I’m wondering if the best of the gains might have been had for now, possibly? I’d need to see a strong reason to expect profits to continue rising strongly, to persuade me to buy at this level. Although Liberum does say the Q1 order book is up strongly, so there could be another good update in a few months, from LUCE.
.

.
Cloudcall (LON:CALL)
(I hold)
103.5p (down 2.4% yesterday) - mkt cap £40m
CloudCall (AIM: CALL; OTCQX: CLLLF), the integrated communications company that provides communications and contact centre software that integrates with Customer Relationship Management ("CRM") platforms, announces the following trading update for the year ended 31 December 2020.
A YEAR OF TWO HALVES, GROWTH RESTORED IN H2, TOTAL REVENUE AT UPPER END OF REVISED GUIDANCE, RECURRING REVENUES UP 13%
The company says it’s traded broadly in line with market expectations -
The Group is pleased to confirm it has achieved total revenues at the upper end of the revised guidance issued during the second half of 2020, whilst cash, operating expenses (which include one-time COVID-19 related savings) and losses before tax are all expected to be broadly in-line with market expectations, subject to year-end financial close and audit procedures.
Net cash is down to £3.6m, which is lower than I was expecting, given that it did a much bigger fundraise than previously a while back.
My opinion - we knew from previous updates that covid knocked the company back by about a year (repeated in today’s commentary), because it mainly serves recruitment companies, and they suffered badly in H1, but have since been recovering.
The KPIs look quite good, but it’s not feeding through into the P&L yet - e.g. H1 revenues were £5.8m, and H2 was only a slight increase to £6.0m.
I think the company needs to move up a gear, as I’m not impressed with this update. We need to see much stronger growth in 2021. Less talk, more action, in other words. Sorry to be blunt, but I tell it how I see it, regardless of whether I own the share personally or not. I’m prepared to run with it, for reasons previously mentioned, but patience is beginning to wear thin.
.

.
Treatt (LON:TET)
866p (up 13%, at 09:03) - mkt cap £519m
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, today updates on trading since the start of its financial year ending 30 September 2021 ("FY21").
Things are going well -
Overall, the Board is cautiously optimistic that the current strong momentum will result in profit before tax and exceptional items for FY21 materially exceeding the current market consensus* of £15.1m.
* Treatt compiled consensus of analyst forecasts for FY21 of profit before tax and exceptional items.
Very helpful to provide a note of what market expectations are - many thanks.
See the RNS for more information, I don’t need to go into all the operational details here.
Valuation - this is the crux of things. Yes the business is trading well, and we might be heading for say £17-20m profit this year, at a guess? I can’t find any broker research notes. Is that enough to justify a mkt cap of £519m? That’s nearly 5-times FY 09/2020 revenues.
By my calculations, taking into account today's positive update, we might see c.25p EPS this year. That’s a PER of 35 times. In other words, the market is pricing in a doubling of EPS to about 50p, to get to a more reasonable PER of 17 times in future. So we’re being asked to pay up-front for about maybe 3-4 years strong earnings growth, to eventually get to 50p EPS (it was 20.5p EPS last year).
My opinion - a high quality company, and it has expanded capacity, so the hope is clearly that revenues & profits can really take off from here. They need to, otherwise the current very aggressive valuation doesn’t make sense.
Personally, I cannot get anywhere near this valuation, so I wish shareholders well, but won’t be joining you. We’re in a very frothy market for growth companies at the moment, and I don’t really want to be holding things on very ambitious ratings, because they could be vulnerable when a market correction occurs, as it inevitably does when valuations get this extended. Nobody went bust banking some profits.
.
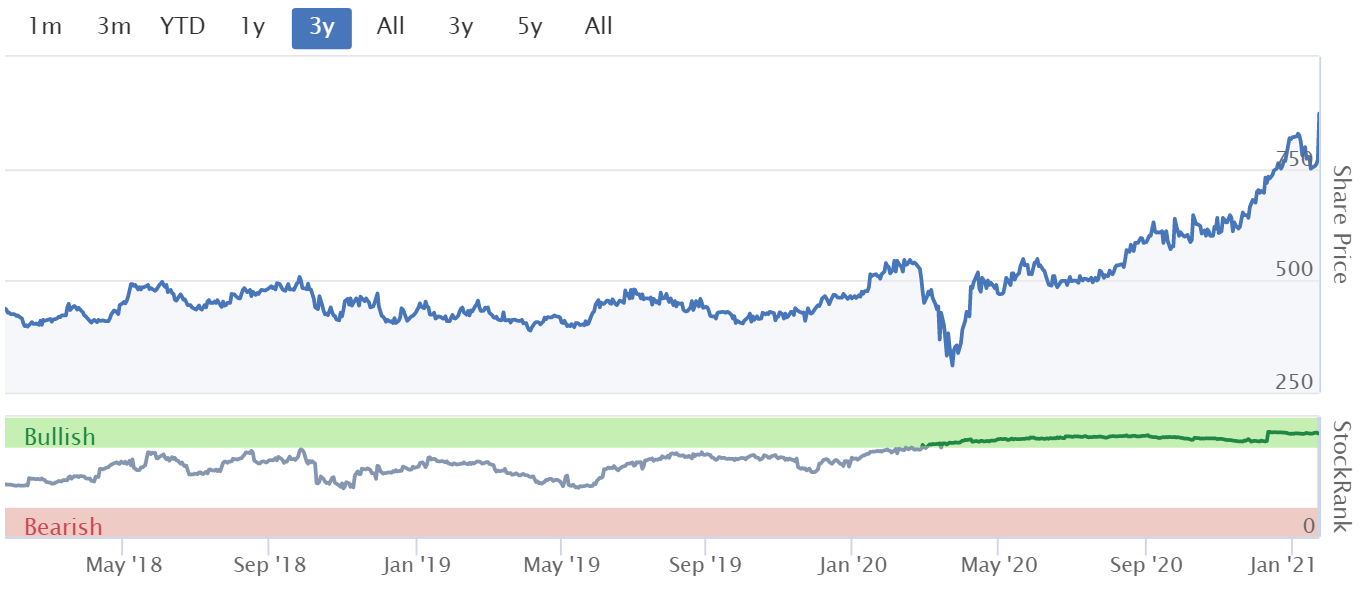
.
Character (LON:CCT)
410p (down 3.5% at 11:02) - mkt cap £88m
Designers, developers and international distributor of toys, games and giftware
Its financial year ends 08/2021, so today we’re being briefed on Sept 2020 to date.
Background - Character had a bad year FY 08/2020, with underlying EPS down from about 43p prior year, to 18.1p. Fair enough, as that period included covid/lockdown 1.
Previous trading update - outlook comments with the results, published on 10 Dec 2020 sounded very positive, including that Q1 sales (Sept, Oct, Nov 2020) were up >30% on LY, and prospects for FY 08/2021 “looking extremely positive”, and benefitting from deferred demand from LY. Ahead of expectations for H1, and FY 08/2021.
Today’s update -
Buoyant market conditions over Christmas, sector up 5% Y-on-Y
Group sales up >30% vs LY, for the 4 months to end Dec 2020, so that’s consistent with the same growth rate previously reported for the first 3 months previously.
All our major brands and hero lines have sold exceptionally well.
Lowest inventories in a decade, due to strong sales, and “judicious” purchasing (this is good for cashflow, but could lead to lost sales, if in demand items are not in stock, so not necessarily a good thing, especially given current problems with Far Eastern shipping).
Outlook -
Despite the extended lockdowns and logistical difficulties that have arisen from container shortages, delays with shipping from the Far East, congestion at UK ports and the fall-out from Brexit, underlying profitability for the six months ending 28 February 2021 will be significantly higher than for the same period last year.
Looking beyond this, we expect that the second half year of this financial year to be challenging due to the continuance of the lockdowns, restrictions and the continuing effect that the logistical difficulties are having on freight rates from the Far East (at times quadrupling since September 2020).
Assuming no further worsening of these conditions, the Board believes the Group will achieve current market expectations for the year ending 31 August 2021.
That’s a bit mixed. Also a pity they didn’t include a footnote to specify what market expectations are. Allenby to the rescue! They’ve helpfully published an update note on Research Tree today, many thanks for this.
Allenby’s estimate for FY 08/2021 earnings was raised 51% in Dec 2020, to 37.6p EPS. That looks reasonable, and would represent a recovery back to a bit below pre-covid level of profits.
I make the forward PER 10.9 - good value, if forecasts are achieved, and it sounds like the company is on track.
Character has a lovely balance sheet too, so it’s very securely financed, no worries there at all - I've just checked back to the last published accounts.
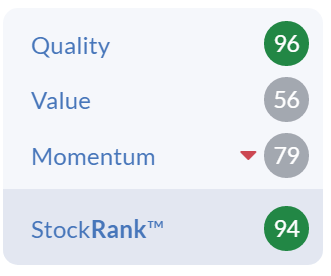
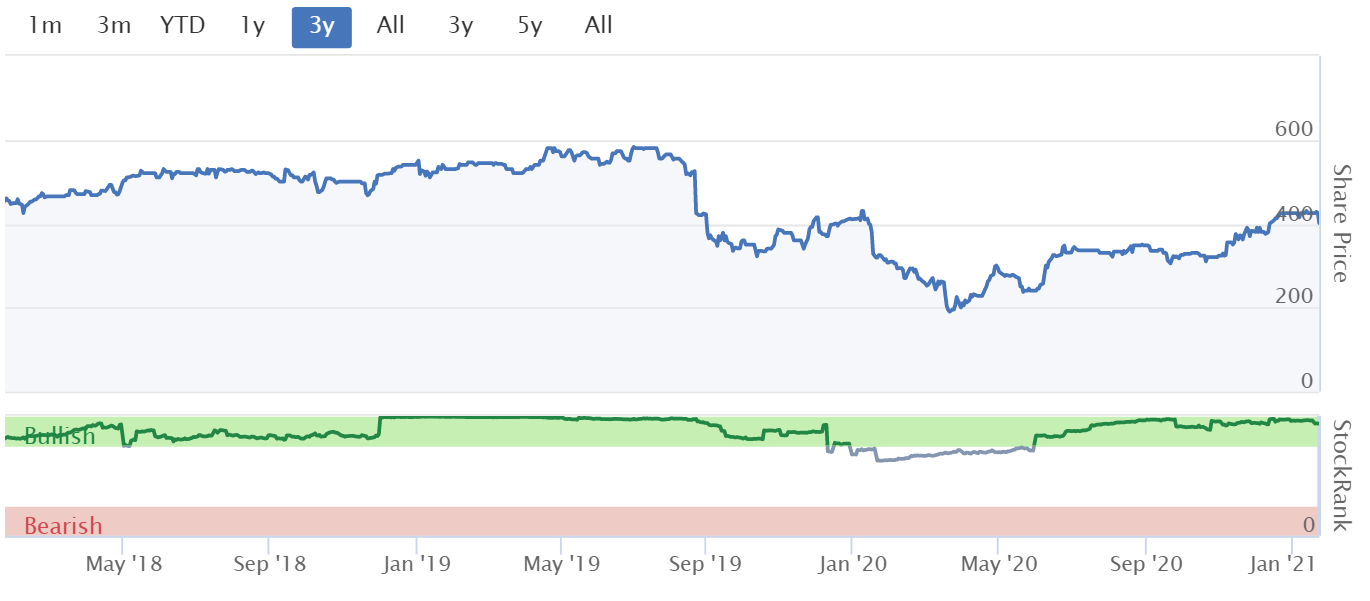
Overall, a thumbs up from me. For value investors, this looks, well, good value! Stockopedia loves it too, with a very high StockRank. Not infallible, but a very good pointer I find. Also, note that the latest broker forecast hasn't found its way into the data yet, so the Value score is likely to go up.
.
.
.
What a busy week! I'm signing off now, so wishing you a restful weekend.
See you next week!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
It's interesting isn't it that female execs are said to be more cautious. Yet not long into the hot seat Ig Group (LON:IGG) has made a significant acquisition which does not immediately look accretive.
Hewlett Packard's female CEO exec made a disastrous acquisition of Autonomy.
The new exec at John Lewis has a difficult task ahead, and we will see what will happen there.
Ref vaccine effectiveness.
I have been waiting keenly for the data to start coming through from Israel now that they have vaccinated a mateial amount of their older population. I wouldn't exactly say that good news has been quick coming - but at last the data is starting to show material declines in infectection for over 60's. I think perhaps at present the market overall may be presuming that the vaccince will be a magic bullet - so i suspect if the vaccince does fall short so that if for example materially over 10% of oldies still have problems after having two shots the market may not take this well?
The linked data shows a 60% drop in infections from a very early sample - so certainly trending very much in the right direction - albeit 60% drop still leaves 40% of the whole. Hopefully longer term the decrease rate will continue to increase.
https://www.dailymail.co.uk/news/article-9179677/Israeli-healthcare-group-says-coronavirus-infections-plunged-vaccinated-60s.html
Overall moderately positive news with much more data presamably on the way soon.
I have been waiting keenly for the data to start coming through from Israel now that they have vaccinated a mateial amount of their older population
The signs are positive but to put it in context let's include the rider to their report:
Our opinion is that at this level of efficacy, there should be no exemption from performing Corona tests, isolation, or the enablement of crowded gatherings, until additional convincing data is obtained. And, of course continue to wear masks and keep social distancing, as recommended.
And here are the thoughts from the Israeli health minister this morning:
"We’re just in the beginning of the campaign, we unfortunately do see cases that after getting the first dose, people do get sick, get the coronavirus. At the same time there are some encouraging signs of less severe diseases, less people hospitalised after the first dose. At this stage its very difficult to say, its not a clinical trial yet ... We sincerely hope we will have better information soon ...
Vaccination is not a panacea ... Corona is still with us and we’ll have to live with this reality for a long time."
We can say, with reasonable confidence, that the vaccines are making a difference. It's an important step - but just a first one. Even if the vaccine efficacy is not as good as hoped for it will help to drive down R0 and infection rates. It's a step on the road to normality, at least.
EDIT: and the data coming out of Israel for the Pfizer vaccine suggests no effect on immunity for 14 days after the first jab and then a 33% improvement. The hope is that that will continue to improve, but we have no actual data. Israel is following the Pfizer recommendation of a second jab after three weeks.
timarr
EDIT: and the data coming out of Israel for the Pfizer vaccine suggests no effect on immunity for 14 days after the first jab and then a 33% improvement. The hope is that that will continue to improve, but we have no actual data. Israel is following the Pfizer recommendation of a second jab after three weeks.
This is important data to continue to monitor - as it does on face value perhaps suggest we could be having some problems in the UK if we continue our current policy of delaying second jab - hopefully if evidence continues that stats for first jab are that bad then we will quickly change our policy if needs be. I am reasonably confident we are monitoring this closely and and decision made will be done on scientific needs and quickly - its very hard though if it literally is a 50/50% decision numbers wise if you are weighing up those that die due to not having had second jab v thjose that die due to having had first jab and not second jab - either way one of the two 50/50 groups is being given first dibs.
On a more positive note the same article (daily mail being reasonably balanced for once perhaps??) said the following.
It was reported yesterday that a single shot of the Pfizer vaccine had led to a 'major presence' of antibodies in 91 per cent of doctors and nurses who received it in Israel within 21 days.
So hopefully the 33% stat is one that really is being quoted out of context (tooearly) by some as its known that we should probably only start counting any numbers from day 22 onwards if we have to wait 3 weeks full weeks generally speaking before waiting time is over. I also doubt its as simple as "it always taking 14 days to start working ??" then working after that - would be intesting to see how big the variability is in getting up to the high levels of antibodies being in the body. I guess even then the fact we can measure them early does it mean they are in sufficient numbers where they need to be to do their job at that time. We will hopefully have a treasure trove of stats coming our way in the next 4-6 weeks - i am semi hopeful our route taken in the UK will not turn out to be completely the wrong one - i however i do want the most vulnerable to get their seconds jabs asap though as soon as we are at the point where the "equally vulnerable on lfl basis not vaccinated" have had their jabs to get them in an equivalent position.
So hopefully the 33% stat is one that really is being quoted out of context (tooearly) by some as its known that we should probably only start counting any numbers from day 22 onwards if we have to wait 3 weeks full weeks generally speaking before waiting time is over. I also doubt its as simple as "it always taking 14 days to start working ??
Well, most vaccines take a little while to start generating immunity and most get "better" as time goes on. So I don't think the 33% is out of context, nor is it particularly surprising, nor is it particularly alarming. Hopefully, the effect will continue to strengthen beyond 14 days.
The 14 day trigger point looks like it's real - the data suggests that there's no difference between vaccinated and unvaccinated groups until day 14. This is raw data and not a clinical trial but the UK scientist are looking at it carefully.
Because Israel is following the 2-jab Pfizer recommendation then we won't get any further data about the UK strategy after 21 days, we'll be conducting our own mass trial and keeping our fingers crossed. But the Israeli data will show if the 2-jab strategy really does provide high levels of protection at a population level, which is obviously important for everyone going forward.
The 12 week gap in the UK is a calculated gamble based on how other vaccines work and the desperate need to bring the death and hospitalisation rates down. I think the best way of viewing it is to hope that it will protect a lot of people but assume it won't cover all of them or as fully as the two jabs would. So as a vaccinated individual I wouldn't change my behaviour because I wouldn't know if I was safe - but overall we can still hope to see death and hospitalisation rates in the vaccinated cohort fall over the next two months.
I think the Israeli data is very positive, but also far from conclusive.
timarr
Boohoo (LON:BOO) ASOS (LON:ASC)
Bit non-small cap I'll admit, but reports from Sky coming out that ASOS (LON:ASC) is frount-runner to buy the Topshop brand for £250m.
I hold Boohoo (LON:BOO) and I would seriously not like them to get involved at that level.
Next has pulled out of the bidding.
(Reuters article on news feed for Boohoo - and presumably ASOS )
It has been a greatly disappointing week for me.
IG Group (LON:IGG) had a high of 910p early yesterday morning, announces their acquisition of "Tastytrade" (US), closed today @ 787p. Ouch. -14%.
https://www.stockopedia.com/share-prices/ig-group-LON:IGG/news/ig-group-hldgs-plc-directorpdmr-shareholding-urn:newsml:reuters.com:20210122:nRSV6672Ma/
The only ray of sunshine is a Director buy today of 6,300 shares by a Director who doesn't show up on StockReport.
The 14% haircut on the price raises the Yield (on today's StockReport) to 5.22% (up a 1% on yesterday).
IF investors are lucky (and I don't feel like a lucky nor a clever investor right now), may be it will bottom out of this fall soon. We may have a month of further falls and repricing to come. The divi is held. The stated uplift from the acquisition is single digit. Its going to take some quarters for the management to execute this, and the shareholders carry the risk.
The other fly in our ointment this week is Boris's comments that lockdown may not end in Spring.
IG Group (LON:IGG) had a high of 910p early yesterday morning, announces their acquisition of "Tastytrade" (US), closed today @ 787p. Ouch. -14%.
I'm not surprised, frankly. They're giving away over 25% of the company for an acquistion that will be low single digit accretive to earnings next year, that's outside of their immediate domain of expertise, in a market that's notoriously difficult to crack and at a time where we're seeing a lot of speculative froth.
As a shareholder I can't see anything in this I like at all, all of the perceived benefits are in the future. And, as an added kicker, the existing tastytrade shareholders walk away with all of the cash in the business - about $112 million - and we have two new institutional shareholders holding 5.7% of the company on a mere 6 months lock-in, virtually guaranteeing a stock overhang for the foreseeable future.
As ever, this shows the importance of sizing portfolio positions correctly. If I were holding IGG as part of a concentrated portfolio I'd be spitting feathers. As it stands I'll ride it out and see where we go, but it'll be a few years before we know whether this was a good deal or not.
At the right price this would be a decent bit of diversification but this isn't the right price, or the right time.
timarr
Ig Group (LON:IGG) (I hold)
Hi Timarr
"And, as an added kicker, the existing tastytrade shareholders walk away with all of the cash in the business - about $112 million"
How do you know this? All that's stated in the press release is that cash to a certain level needs to be left in the business. We don't know what that level is.
My hunch is that most of this cash will remain in the business, probably for regulatory requirements.
Also, keep in mind that lock-in for current tastytrade management is 5 years, released on a straight line basis (as per the investor's call); for exactly the same reasons you have mentioned, they therefore have an incentive to keep momentum going in order for the enlarged group's share price to go up in that time period.
Well, I hope so anyway.
Cheers
A
RE: Ig Group (LON:IGG)
How do you know this? All that's stated in the press release is that cash to a certain level needs to be left in the business. We don't know what that level is.
Note 14: Financial information for year ended 31 December 2020 is on an unaudited US GAAP basis. The terms of the transaction stipulate that tastytrade will be acquired on a cash free / debt free basis subject to a minimum agreed level of cash to be retained in the business. Prior to closing, it is expected that tastytrade will distribute to tastytrade shareholders any cash that is on the balance sheet at such time in excess of this amount. As at 31 December 2020, tastytrade had $112.0 million of cash & cash equivalents.
Note 21: As at 31 December 2020, tastytrade had a regulatory capital requirement of $500k
timarr
Ig Group (LON:IGG)
Thanks Timarr
I clearly missed Note 21 (why would a privately held company leave $112m on it's balance sheet?), though I still don't understand what it has to do with Note 14.
Are you implying that the cash that has been mutually agreed to be left in the business will be $500k or close to it?
Cheers
A
Are you implying that the cash that has been mutually agreed to be left in the business will be $500k or close to it?
Hi abtan
No, but I'm suggesting that the capital needed to run tasty is on the low side. That's a good thing in general, of course. I suspect the bulk of the $112 million will go to the shareholders though. I really like the look of tasty as a business, but when I read this type of thing I shudder:
Common entrepreneurial ethos combined with a culture of regulatory compliance and client-centric focus.
I always like to compare the management board pages when we have one of these slightly off-the-wall mergers.
Here's IG Group's: https://www.iggroup.com/about-...
Here's tasty's: https://www.tastytrade.com/abo...
Lots of interesting content on tastytrade: https://www.tastytrade.com/sho...
"Learning about markets, trading and taking risk has so many benefits it’s highly likely that the next generation of superstar entrepreneurs just made their first stock trade on Robinhood or lost money on their first speculative option trade. Who the f*** cares? I made money on my first option trade and then lost all my money, all $2000, on my next ten trades. Nobody thought Drexel Burnham was being careless nor did they care they were charging me $25 per contract in commissions. In fact, every amazing talent in the world of finance today, probably started out the same way. Experimenting."
This is going to be interesting.
timarr
IG Group (LON:IGG)
There is probably some presumptions on my part but culturally i see America and UK as completlyl different. From what i have seen americans seem to take pride in not blaming others for their decisions that go wrong and the UK seems to take the viewpoint that sometimes people do need to be protected from themselves and also certain organisations that may be perceived to target the vulnerable. I can't argue with anyone who says that says bods in the UK like to shift blame at the earliest opportunity :)
I don't think there is any problem here we just need to understand the differences - the IG board would be damn stupid to go in and try and change things too much (if at all!!) culturally in the US - and i would be gobsmacked if they don't know the exact score on this point. All i see IG board's job to do is be conservative guardians of the new business - learn from each other and and advance all sales opportunities and be as efficient as possible.
The differences of the two board pages linked are very stark - but the IG board does seem to have decent international experience and it looks like the CFO is a yank himself.
Interesting times ahead. Watch this space.
There is probably some presumptions on my part but culturally i see America and UK as completlyl different.
Oh yes. I've worked for UK divisions of US companies and for a UK company running a US division. Chalk and cheese. We typically make the mistake of thinking Yanks are Brits with a funny accent but they're not. Americans are ultra competitive and very entrepreneurial, although they can also be insane rule followers, especially in the rank and file workforce.
Managements are typically very highly motivated by financial rewards to the point where staff are often treated like any other resources - the fire at will culture is central to the way they work. Job security is very low, but because of that companies are willing to make risky hires, so the employment market is very flexible. Good for the economy but arguably less so for individuals.
The general environment in the US is that you're free to do anything that's not prohibited but if you get it wrong you'll get sued. In the UK and Europe it's more preventitve, stopping things going wrong in the first place. Regulation here is along the same lines, in the US it's more light touch - although I gather even across the Pond it's been seriously tightened since I was last involved, pre 2008 crash.
timarr
The dilution of shares I believe is around 16%, so no wonder the share price has dropped.
The day before this was announced I was querying why IG Group (LON:IGG) and CMC Markets (LON:CMCX), did not have a share in the US markets, that is the largest market, so it makes sense to be part of of it.
I feel they have overpaid but it may look a good deal in a few years time.
If the shares fall below 750p I will be topping up.
IG Group (LON:IGG)
herbie
The dilution of shares I believe is around 16%, so no wonder the share price has dropped.
But the deal actually increases the "adjusted" EPS (being accretive) so IMHO the extra shares in issue is not the problem as there is increased profits being brought immediately into play that compensates for the extra shares - its more the worry that the future prospects won't justify what was spent i would guess.
I must admit the fact they released results the same day somewhat complicates the picture - the outlook statement wasn't over frothing with optimism so its probably impossible to factor in if all the drop is due to the acquisition or whether the shares may have somewhat been sold of anyway.
Per interims
Should we see further normalisation in financial market volatility, or a stabilisation in the macro environment we would anticipate some reduction in the level of client acquisition and activity.
IG Group (LON:IGG)
timarr
As ever, this shows the importance of sizing portfolio positions correctly. If I were holding IGG as part of a concentrated portfolio I'd be spitting feathers. As it stands I'll ride it out and see where we go, but it'll be a few years before we know whether this was a good deal or not.
I think you either trust management or you don't i have always seen IGG managemnt as being a safe pair of hands - i can certainly see the attraction of the deal and particularly if there are any cross selling opportunities and/or if this enables the tasty network to expand their offering easily outside of the US or IG to more easily expand in the US. I think anyone that runs a concentrated portfolio should be looking at themselves if they don't like the end results of their decisions - rather than pointing figures elsehwere.
And, as an added kicker, the existing tastytrade shareholders walk away with all of the cash in the business - about $112 million - and we have two new institutional shareholders holding 5.7% of the company on a mere 6 months lock-in, virtually guaranteeing a stock overhang for the foreseeable future.
I am really not sure what you expect here - the previous owners have sold up to IGG - that was always their cash - its fairly common to structure deals like this and its completely a zero numbers game - would you have preferred IGG paid $112 million more to buy the company just so they could keep the cash that simply a crazy viewpoint that the $112 has any relevance when its simply te overlal price paid that matters not how its presented.
The stock overhang issue is probably unavoidable however i suspect the cash consideration paid (and the $112 mill they may walk away with on top) will be more than sufficient that these locked in bods will have no near urgency to sell - they should be able DYOR and work out they own part of a sound business however bad the tasty acquisition turns out to be.
I'm not surprised, frankly. They're giving away over 25% of the company for an acquistion that will be low single digit accretive to earnings next year, that's outside of their immediate domain of expertise, in a market that's notoriously difficult to crack and at a time where we're seeing a lot of speculative froth
I am not sure what you are expecting here - the fact that this acquisition is earnings accertive immediately when you factor in good growth stats of what they are acquiring is a plus. I would have expected that as they are purchasing a quickly growing buisness they may have to wait for any payback from an eps standpoint. If growth continues at anything like the rates listed below then the deal should be extra accretive over time - if thats a proper term?
o tastytrade's revenues grew at a CAGR of 49% between financial years ended 31 December 2018 and 31 December 2020[26]. tastytrade's active accounts grew at a CAGR of c.64% during the same period.
o tastytrade generated an adjusted EBITDA margin of 47% in the year ended 31 December 2020[27]reflecting the highly scalable nature of its proprietary platform.
o tastytrade is well positioned to benefit from any recovery in US interest rates through higher interest income earned on client balances.
At the right price this would be a decent bit of diversification but this isn't the right price, or the right time
I guess you could well be right here - but we simply don't know. I do sort of agree that the american stockmarket has been in a bit of a bubble the last couple of years - but should we always presume a crash is coming? - looking at the growth rates and the customer numbers i kind of think they should be around for the long term their customer numers have the critical mass. I am not even sure what the standard trade is on this site ? is it mostly going long shares - not convinced it is - so if thats the case they have other bubbles that would also need to pop. In some repscts is their core market of moeny forlm trading not so similar to IGG that its the same risk of the parent company which you were happy to have risk on?
I think the main worry other than this being for me which i am guessing you fully share would be the complete abject failure of uk companies expanding in the US generally (i am still bitter about Fresh and Easy and thats nearly ten years ago) . One would like to think that the change in ownership structure should necessarily impact the prospects of tastytrade - although there is probab,y little to stop the main bods leaving and starting a competing site. So folr tis reason i see why the market will take some convincing - i could be wrong but with the growth rate they have previously had i suspect the market will quikcly warmk to the acquisition IF short term they can evidence that the bought unit is still showing say 20% annual earnings growth,
You may have gathered the nice (for me as a non holding lurker) drop in price despite the uplift in expected eps from this deal may be enough to tempt me back into thei company.
I must admit i had never heard of tastytrade - so i did my own internal checks of googling "best option trading sites" and clicking the first decent link that i saw which was via invetopedia who i have heard of before - and lo and behold tastyworks was first on their list of providers - so thats a pass in that regard that they do have some decent web presence if you are trying to find an option trading platform. Just a shame that tastytrade just makes me think of food rather than shares.
https://www.investopedia.com/b...
Hi rmillaree
I don't think it's possible to be uniformly positive about this deal and I would be concerned if any shareholder was, as there are clear risks. If this goes well the IGG directors will be very well rewarded, if it doesn't then they'll still be handsomely remunerated. CEOs don't tend to be short in the animal spirits department and IGG's board don't have a huge amount of equity skin in this game so I'm not convinced their ambitions are aligned with shareholders'.
On the positive side the deal adds diversification in terms of market and services. They're buying an excellent company with real and growing earnings in the most important market in the world.
On the negative side we have a company in a market that's undervalued, an issue made worse by currency depreciation, buying one in a market that's frothy. IGG's management have a hurdle to overcome to start with.
Beyond that you have to consider the culture clashes - not just UK v US but regulated v unregulated. IGG is a heavily regulated business dominated by compliance rules. tastytrade is an unregulated, freewheeling entity. As anyone who's worked in the sector can confirm, these are not naturally synergistic businesses.
The idea that tastytrade can operate standalone from IGG and they can still benefit from the synergies is illusory. At some point, there will have to be integration and there will be strain across the businesses as IGG's rules start to be applied to tasty. If growth stalls then that will be exacerbated.
This can all be managed but, in general, most businesses attempting cross-border acquisitions outside their core businesses fail to generate shareholder value. And IGG are paying a full price.
Personally I wish the management had stuck to growing the business organically, as I'm happy to diversify the risk myself, but I understand the management's desire to diversify outside their core regulated markets. That said I rate the odds of success as no more than 40-60. But the upside is significantly greater than the downside so, weighting the probabilities, I'm willing to stick with it.
timarr
IG Group (LON:IGG)
thanks for adding your comments timarr
Beyond that you have to consider the culture clashes - not just UK v US but regulated v unregulated. IGG is a heavily regulated business dominated by compliance rules. tastytrade is an unregulated, freewheeling entity. As anyone who's worked in the sector can confirm, these are not naturally synergistic businesses.
Thanks for that - i did not know that. Slightly surprising fact considering US is normally shot hot at financial regulation and ensuring compiance. Unless your initials are EM its probably best not to mess with the SEC. I suspect this may not be too much of an issue as long as both entities are acting in the law their interests arent that unaligned - one just has to look at how the gambling has gone from complete free for all to fully regulated in US - so to see the future picture - it is that they simply need to be compliant with every country the deal with (customer located in) to avoid blacklisting or backdated fines - as an IGG owned entity now i would expect they should do fine in that regard - although one never knws what nasties may be under the bonnet. I suspect companies like Plus Markets may have dabbled in the darker side of regulation and they seem to have got away with it so is it really clear cut that regulated and unregulated are two completely different lines of thinking?
As for the rest of the stuff you say i am not 100% convinced i agree but we really don't know how this will pan out so i will simply wait to see how the mop flops - good management should though know how to align the two to make the whole better without destroying the best bits of either entity one would hope - but thats just hope.
A couple of things. I see that Next (LON:NXT) has dropped out bid to buy Topshop. Could there be an opening there for £BOO.
On Treatt (LON:TET) which I owned from October 2014 until I sold in March (now wished I hadn't and did not get back in) it has delivered a share price return of 40.1% CAGR over the past five years and 29.7% CAGR over the pas 10 years so they have certainly delivered growth wise. I am not sure it is overvalued (I need to investigate) but price anchoring is holding me back from buying.
I sold at 332p.
Lord Lee must be a happy chappy. I believe it is still his largest holding!
When the last comment was made on TET I said it is a high quality company, and expected continued growth. It has just built a new HQ and significantly expanded capacity, as well as looking to increase it's presence in the drinks market. To achieve these results during covid times is extremely encouraging.
Re TET
Parkinson’s law states that once an organisation completes its grandiose, distinct, “perfect” headquarters building, that organization has reached its peak ...!
I appreciate the sentiment but most of $TET expenditure on the new UK site is for new plant in modern buildings specifically designed from scratch, consolidating some old and knackered buildings from different locations. State of the art kit etc.
RNS from Maintel Holdings (LON:MAI)
"Daisy confirms that it does not intend to make an offer for Maintel.
For the purposes of Rule 2.8 of the Code, Daisy, and any person(s) acting in concert with it, reserve the right to make or participate in an offer or possible offer for Maintel (and/or take any other action which would otherwise be restricted under Rule 2.8 of the Code) within 6 months of the date of this announcement:
a. with the agreement of the board of directors of Maintel;
b. following the announcement of a firm intention to make an offer for Maintel by or on behalf of a third party;
c. following the announcement by Maintel of a proposal for a "whitewash" (as referred to in Note 1 of the Notes on Dispensations from Rule 9 of the Code) or for a reverse takeover (as defined in the Code); or
d. where the Panel on Takeovers and Mergers has determined that there has been a material change of circumstances".
As you were!
For any holders of Maintel Holdings (LON:MAI) (I hold), I've just seen this in the announcements section:
MEDIA-Daisy Group approaches Maintel Holdings with a takeover proposal - Sky News
...no RNS yet from the company. Sky reports the "preliminary" offer is 450p.
It has been steadily rising lately. FinnCap had a 600p PT on it having recently reintroduced forecasts. Recent interim results were in line and outlook was positive. Recent new CEO.
Lets see if this progresses.
RE: Maintel Holdings (LON:MAI)
Announcement:
Further to press speculation in relation to a possible offer by Daisy for Maintel Holdings plc ("Maintel"), Daisy confirms that it does not intend to make an offer for Maintel.
https://www.investegate.co.uk/...
timarr
Angle (LON:AGL) (I hold) Interesting presentation given last night to Proactive ONE2ONE Investor Forum. Some new items include potential use of Parsortix in triage of the cancer patient backlog caused by C19. Also some good questions from audience – so many that the sponsors are having to make a second video.
https://www.youtube.com/watch?v=NVpVcsRxO6o&feature=emb_title&ab_channel=Proactive
PS Some Stocko members may be interested in the subsequent presentation by Faron Pharmaceuticals Oy (LON:FARN)
Thanks Jim. As a long term financial (and ethical) supporter of Angle (LON:AGL) as you may know from my postings - ethical was the first reason to buy and main reason to holdall that time of 7-8 years - I really want it to succeed because if it does and justifies itself scientifically and practically, it is a wonderful step forward. A win/win/win/win on identification/pre-treatment/continuing treatment aid/cost, There are few situations in the markets where we can say that. Good luck to the dedicated CEO who has stuck with it too. Dont know why it is regarded so lowly compared with apparently - remember, I am not a medic/scientist - inferior offerings from very highly valued, principally US companies. Perhaps one day someone will tell me why in words I can understand, or hopefully it will take off and the recent presentation targeted at N American investors will bear fruit.
I completely disagree with the comments on Treatt. They ignore the transformation in the business, the management and business performance, the returns on investment. I understand people who simplistically rely only on price earnings ratios - they are a useful starting point - but that is all.
WDWombat,
I completely disagree with the comments on Treatt. They ignore the transformation in the business, the management and business performance, the returns on investment.
Re Treatt (LON:TET) we've covered all that before, in a lot of detail, in previous articles here. Those positive factors are why the price is so high.
As I said, if you think the business will perform a lot better than forecasts, then it stacks up as an investment. I'm just pointing out that this is baked into the price already.
Paul.
Sorry I don't have time to re-read your comments on this today but would ask at what stage it came under your recommendation umbrella?
I don't have a "recommendation umbrella", whatever that is!
This column is just me digging through the numbers, and giving a personal opinion. Then the readers add their views & additional information, and we have discussion about the shares that are reporting news on the day.
You've been around here for a while, surely you already know this? Sounds like you're having a bad day, so let's just leave it there.
Hi WDWombat,
It's normal for posters to be more positive on one's own book on the SCVR including the comments section. It's best to take everything with a pinch of salt and assume a level of personal bias by posters. Try not to be annoyed if someone has a different view.
I find it best to DYOR and ignore the noise.
BSV
Re Treatt (LON:TET) - I agree with WDWombat that a PE ratio on current profits on this occasion is not so helpful. We have to look to 2023 when management's increased ROCE guidance (see the November investor presentation) kicks in and they will be operating fully from the brand new UK plant - with lower variable cost (=> margin), better product mix (=>margin) and larger volume (=>revenues & margin).
Furthermore, this is a segment where international comparables - especially the growing ones - are trading at high multiples. This is Lord Lee's #1 holding for a reason - very well managed with a great culture and outlook in an attractive market - a class act. I hold.
But that’s 3 years away, which is exactly Paul’s point. Why pay now for something they have three years to get wrong.
IGotPoesJacket: I am not paying for Treatt (LON:TET) now, but I am holding onto most of a stake bought in 2015, 2016 and 2018 with a very long term time horizon, meaning a couple of decades. AGMs in Bury St Edmunds with direct discussions with a stable and excellent management team have helped limit the "urge to slice" what for me is a proven winner. I will forgive occasional (potential) overvaluation as that helps me stay in for the long term, and I would be surprised if this conservative team does not (over)deliver - so prefer to hold continuously. Several margin expansion levers and long runway should help this snowball get nice and big for patient holders.
Does anyone understand the Surface Tranforms placing, I read through the RNS which I didnt find very clear. Now two options have appeared on my trading platform at AJ Bell, neither of which are functioning yet. I'm currently not sure what i'm entiled too and at what price
I can rarely resist looking at the details of a fundraising, even when I don't have an interest as in the case of £SCE
I think this may be the key paragraph from the RNS of Wednesday:
If AJB are showing two options I would get that one might be your "entitlement" the other the option to bid for excess.
Neither an investor in Surface Transforms (LON:SCE) nor a client of AJB so this is just a (hopefully) educated guess.
Thanks Gromley you are a gent
I'm not sure what i was reading but it didnt make much sence, however since I've found this which helped
https://static1.squarespace.co...
Trading update from Learning Technologies Group (LTG) . Positive update. SP currently up 8%. LTG has same Chair (Andrew Brode) and major shareholder as RWS. I am big fan of Andrew Brode who has lead significant expansion (both internally and by acquisition) of both RWS and LTG.
Hi Paul,
Please would you have time to look at Vr Education Holdings (LON:VRE) (I hold) that has released a very positive trading update this morning.
Thanks
Vishal
Hi vishalg,
I don't know how you arrive at the idea that the trading update from Vr Education Holdings (LON:VRE) is very positive, it looks weak to me. The company only managed E1.4m revenues in 2020. Cash & cash burn;
Year end cash balance of €2.03 million, with net monthly cash burn of approx. €0.2 million
So looks like a placing will be needed later in 2021. The £34m mkt cap seems to rely entirely on hopes for future growth, as there's nothing to support that valuation on historic, or 2020 numbers.
In this type of market, it could be a nice speculation, but there's nothing I can add on that front - I just examine the fundamentals here, and they look poor for VRE.
It's a jam tomorrow punt - good luck! VR is certainly an interesting sector - I bought an Oculus device recently to try it out, and was amazed at the video quality. But not suited to people who wear spectacles, so little use for me. Bit of a gimmick for the over-50s, obviously they're targeting younger people.
Regards, Paul.
Thanks Paul, appreciate your feedback on this.
Another down day this is getting tedious what a rotten 2 weeks
Hi MikeBianchi
I guess the question is are you "trading" or "investing?"
Then again it does not really matter on days when the portfolio shows red on the front page are always an initial :( and then there is a read to whichever index you prefer as your marker, so is your move better or worse than index today mine is worse than index so double :(:( whatever that is meant to be in emoji language I have no idea.
But overall I am in a much better place than last summer with my investment so :)
Is it where I want to be no (overall still down from 01 Jan 2020) so :(
But right now, do I own the companies I want to own, yes.
Are there some companies I should own that I don't, yes but still DMOR and being very nervous from the results of last year.
Do I suffer from the dreaded Fear of Missing Out, yes
Have I missed out, loads of times
But in about 53 minutes I will switch the work laptop off after another tough week at work, go downstairs and get myself a G&T whilst I cook dinner for my wife who is having an even tougher week at work (NHS) and the girls and try to remember the positives in life, and find some time to do a bit more DMOR on the weekend, and maybe sell something on Monday, or buy something, or maybe just do nothing as my work diary is rammed for another not very good week.
All a bit random, so no answer to the question, but chin up as I am assuming that you are down but have not lost everything, so you are still in the game. Keep thinking, keep looking and if it needs to be sold, sell it!
Tommy
if time permits, would you be able to give us your brief thughts on Works Co Uk (LON:WRKS)? it seems their online sales are doing fantastic but not good enough to make up for the lockdown measures. (EDIT - i see you've responded to another commenter about this - apologies!)
thanks for the write ups this week, they have kept me busy whilst stuck in bed after surgery!
In these days of lockdown I am very grateful for the Stocko family and in particular, this column where fellow investors mostly offer cogent advice and opinion. With this in mind I recommend Anna Coulling's book Guide to Volume Price Analysis. (it can be downloaded for free as a PDF) Without it I would have bought Saga yesterday. Look at the chart, it shows that there were too many sellers in the market. Same this morning.
The moral? As I only knew of the book a few weeks ago, it proves that you are never too old to learn.
Thanks Anna
Downloaded it, saved in my Stocko pdf folder. does no harm to read it.
I have also been reading this recently, a really excellent book, I genuinely wish I had found it earlier. If you read reminiscences of a stock operator as well you start to get a very good idea about pricing anomalies within the market.
For example see how Ten Entertainment (LON:TEG) has consolidated recently, within a very tight range but not really sold off. On the 29th December it spiked up to 218 with very small volume (although its important to remember volumes are traditionally low at this time of year) which suggests there may not be many sellers up there to hold it back.
On the fundamental side I like the fact it has given itself more liquidity for the future, and we need to remember not all families will have the funds to jet off on holiday when conditions allow.
Or it could be the sector is down because of the news? I note quite a few in the travel sector are down today such as JET2, SSP (LON:SSPG),not just Saga (LON:SAGA).
I've had a brief look at the book, not studied candlesticks before, so I may learn something. I hold Saga (LON:SAGA) already but I was not considering buying yesterday.
Thanks for pointing this out. From where can you download the Coulling book?
https://www.pdfdrive.com/a-com...
I am not intending to brag when I say I managed 115% last calender year as a result of overweight holdings in Avacta, ITM and Best of the Best (thankyou Paul)! I find the challenge is to get over myself quickly, forget about it and now focus on this year because it can be very quickly given back. Today is an example, I have holdings in Record which looks great following the announcement. However my reason for holding has always been the rock solid bal sheet, management investment and very solid dividend. Also I like the sector. On the otherhand I hold Zytronic. I fear I have fallen in love a little with the stock, which we all know is bad news. But why did I like them strong balance sheet, honest management and very solid dividend up until Covid. Also I like the sectors they are involved with (gambling in particular through Covid). I knew touch was not good in Covid times but couldn't sell and the opportunity cost has hurt. My point being two stocks which are in my portfolio for the same reasons with 2 different outcomes suggest my process needs to develop and sit and hold isn't always an answer, as a rabbit caught in the headlights will tell you. Thanks for bearing with me just writing that has helped focus me for change today.
Knights Group (LON:KGH) H1 analysts' presentation from Tuesday. Presentation by David Beech, CEO, Kate Lewis CFO & Richard King, COO who discuss the results, and the scalable business model, with their strategy going forward.
Video & podcast.
I don't think I will personally have time to look at it today, but would be really interested in thoughts on Works co uk (LON:WRKS) which I recall Paul has looked at before.
Share-price down around 5% so far on news that as a high street retailer they struggled when their shops were shut (DOH!)
Looking beyond the obvious, however, at first glance my view on the metrics they presented was pretty positive. Online is okay (not sure how much of their business though).
I did not go into any of their stores during the brief period that shops were still open, but anyone that has visited them will know that social distancing in their stores would be a massive challenge so maybe they have a harder job re-opening effectively than other retailers?
Hi Gromley,
Yes I'll be covering Works Co Uk (LON:WRKS) interim results later. Have had a quick skim, and it looks better than I expected. However, the balance sheet/cashflow look stretched - they've squeezed working capital hard to move into net cash, which I think looks temporary.
Also if the leases are only avg 2 years to break/expiry, why does it have such humongous lease liabilities on the balance sheet?
That's a teaser, I'll be back with a full section later!
Regards, Paul.
Sorry I didn't have time to cover WRKS in the end. Will look at it over the weekend, and hopefully post something more next week. My apologies.
No problem Paul re Works co uk (LON:WRKS) - I did manage to take a couple of minutes out to have a quick scan and I could not immediately work out why the lease liabilities were so high either.
Have asked their IR if there is a quick explanation - if they get back to me before the weekend I'll post up here.,
Gromley have you been able to work out what proportion of sales is online?
Works co uk (LON:WRKS)
Well they don't disclose a figure, but by providing us with the relative growth rates and by splitting the half year into the 7 weeks of Lockdown (V1) and 19 weeks of shops being open, they give us enough information to have a stab.
Assuming revenue during the 7 weeks of lockdown to be all online, during that period they were delivering online revenues of c. £1.07m / week (up around 140% on the prior year.)
During the subsequent 19 weeks of stores being open, I think they were doing around £880k week online (up c. 100% YoY) and around £3.7m per week in store (roughly flat YoY).
There's quite a margin of error in these numbers but roughly it looks like nearly 20% online up from just above 10% last year.
There are two ways I think to look at that :
1. As an occasional customer of the Works, I was scarcely aware they had an online presence, so I would not even expected the proportion to be this high.
2. For a company that includes ".co.uk" in it's formal name these figures seem pretty low.
We don't know how much of the 20% might be temporary, with people avoiding the stores (all of the stores I have visited are incredibly cramped and you routinely have to squeeze past people - not a comfortable thing to contemplate currently.)
This has actually demotivated me from looking any further at this time.
There is such a dislocation between what the business actually is and the ".co.uk" moniker. They are about 20 years to late for "dot com" to earn a stock market premium - perhaps if they renamed themselves "the crypto works" it might be better.
Less cynically, if they are on a journey to become an online led business, then I do not know what that pathway looks like for them so I think there is too much execution risk and scope for focus drift.
There is nothing in the numbers (other than perhaps Price to Sales of 0.1x) that inclines me to wat to take that risk currently.
I will though keep an eye out for their progress going forwards.
Hi Gromley,
Pretty much my assumptions. Don’t forget they would do considerably more online in the much busier H2 so online sales could be higher than we think, 30-40m. Surely a 20m m/cap is too small for a retailer with such a fast growing online offering?
I'm not really convinced how fast Works co uk (LON:WRKS) online business really is 'growing' up 100% YoY yes, but how much of that is sustainable growth and how much (possibly temporary) dislocation from their high street offering?
They describe this as 3-5 years worth of growth, so unless it is a catalyst to a change of pace in growth then it is probably not as exciting as it looks.
They say their online growth was about 70% for the 11 weeks to 10th January (again including periods of lockdown). Overall during that period they were down 25% although up 24% when stores were open.
It's too inconclusive for me, so I'll sit and watch.
Works co uk (LON:WRKS)
Thanks for keeping tis conversation going peeps. i have just had a look and the market cap of this one at only £22 mill compared to potentially £200 mill sales does seem to suggest there could potentially be very good upside here.
Initial question if you don't mind - have they come through covid without diluting shareholders and do you think they have enough cash to see see them through to the end of covid without dilution? probably an impossible question to answer perhaps but worth askling nontheless.
Yes, with Government help and cost cutting Works co uk (LON:WRKS) cash and liquidity seems to have actually improved over the period, they also say they think the business will exit stronger than before.
I agree that P:S looks very interesting, but not convinced about the other metrics at this point.
Works co uk (LON:WRKS)
Yes, with Government help and cost cutting Works co uk (LON:WRKS) cash and liquidity seems to have actually improved over the period, they also say they think the business will exit stronger than before.
Cheers tThats good to know - i guess the market is simply slightly skeptical this business will either be able to get back to decent annual profits - lets call that satrting at something apporaching £3-4 mill per year. Or perhaps that cash will be consumed with working capital. Or a mixture of the two.
Roll on next month when i don't have to think about tax returns and will have more time to my proper DYOR.
Worth remembering Dean Hoyle ( ex card factory) is a major shareholder here. He’s ruthless and doesn’t do failure. I think he could take this private.
Worth remembering Dean Hoyle ( ex card factory) is a major shareholder here. He’s ruthless and doesn’t do failure. I think he could take this private.
Private for a pittance or pay a reasonable takeover premium ? - i guess the word ruthless may answer that one ?
I donb't really know the background or anything about Dean Hoyle - but was he part of the team that brought this to market in 2018?
Out of interest I just looked this up and to answer my own question - Yes Dean Hoyle was part of the team that brought theworks to market in 2018 (@ I believe £1.80 per share). Having made a big investment and becoming chair in 2015.
Wikipedia article
If you want to bet on the view that he "doesn't do failure" you would I think have to decide what means in this context and in particular whether "failure" would be measured in terms of his personal bank balance or in terms of his reputation.
As I say I know nothing about the man, but even if I thought he was the best thing sliced bread, I would want to understand if his interests are aligned with other shareholders.
There's a huge price movement for Treatt (LON:TET) this morning from a positive trading update.
Looking at LUCE’s history, I’m still not entirely sure what went wrong in 2018, when it had a very bad year, and the share price dropped about 80%. That does worry me. Could similar problems happen again?
Hi Paul, I had this on my watch list for a few years and watched the share price unfold as the company reported on the 15th December 2017 there had been £3.5m reduction in pre tax profit due to an incorrected assessment of the value of the groups stock. The financial controller had then resigned as a result.
The strengthening of the Chinese RMB against the US dollar hadn't been considered correctly by the sounds of it. This was probably compounded by the weak pound as well.
They then released a flurry of statements suggestion how they had put procedures in place to prevent anything from happening again. I have kicked my self for not picking any of these up, but just lost confidence in something similar happening again.
I believe they also hedged against copper badly, hopefully lessons learn't surprised at how they fell away yesterday
Luceco (LON:LUCE): This mistake is unlikely to be repeated. Nearly 70 % held by II and directors. I believe it is also well run. I am concerned how the pandemic will affect its future.
US Executive Order 13959 which prohibits US Persons from purchasing publicly traded securities of 35 Chinese companies identified as Communist Chinese Military Companies ("CCMCs"). I wonder how many and which companies and portfolios we follow will be affected directly or even indirectly.
US resident retail investors can't directly invest in foreign companies unless those companies are registered under the US Securities Act of 1933. I do not know if any foreign companies without a US listing would do this.
Mutual Funds, etc. would, of course, need to sell.
Dunno if it's just me but the last week or so seems to have brought an extraordinary run of companies reporting earnings beats? It seems it's not just a post-Brexit, end of pandemic in sight relief rally.
There are a few more that I hold today - Record (LON:REC), Treatt (LON:TET) and Kooth (LON:KOO) - to round off an fairly remarkable week. Kooth looks particularly interesting, although there's little detail in the trading update, we'll have to wait for the results to see how this is feeding through to profits. It's a John Lee stock, too.
On a rather gloomier note there's Zytronic (LON:ZYT) (which I don't hold) which sees no prospect of profits this year. They've rather been broadsided by the pandemic - touchscreens aren't flavour of the month, ATM usage is falling dramatically and gaming (aka casinos) isn't exactly booming either. I just don't see that business line ever recovering, which is a shame because it's a perfectly good company.
timarr
I don’t think it’s just you Timarr. I’ve struggled to keep up with all the reports this week but when I’ve found time to review them have been surprised by the number of ‘beating / significantly exceeding’ type statements - with more of the same today.
Maybe an element of managing expectations accordingly and then over-delivering.
Thanks for highlighting Kooth Kooth (LON:KOO) - going to take a closer look.
Re Kooth (LON:KOO), thanks for the reference. I can see how Wey Education (LON:WEY) can do a lot on the web. Less sure about helping mental health, but we will see. Interested to see the lack of information on the website in the Investor info side. Anyone any ideas about where the I might find out who are the major shareholders?
On their website:
https://www.weyeducation.com/investors/significant-shareholders/
For Kooth see the https://investors.kooth.com/shareholder-information/ section - Aim Rule 26
Major shareholders
Significant Shareholders: Shareholders with shareholdings greater than 3%
1. Name
2. % of issued share capital immediately following admission
3. % of issued share capital immediately prior to admission
Root Capital Fund II LP 50.2% 86.2%
Canaccord Genuity Wealth Management (Hargreave Hale Ltd) 7.9% -
Gresham House AM Limited 7.2% -
Stancroft Trust Limited 6.1% -
Premier Miton Investors 4.9% -
The assumptions of what Kooth (LON:KOO) is and can achieve are quite astronomical. So much costs of development and expansion too that is impossible to to project. The requirement and cost to provide counsellors with expansion is high....of course they claim AI will do some magic.
Its notable that capitalised development eased off in the year before IPO. Its seems likely this was IPO prep rather than permanent step back and this investment is likely to accelerate. only 11 developers on board at IPO is light.
The costs of scaling child and adult mental care with linked through NHS funding does not appear to have the scale tech platform profitability characteristics that should be discounted at high valuation into the long distance.
The workplace mental health interface could be scalable and highly profitable with scale (due to the truncated nature of care it provides...rather than what must be quite open ended in NHS setting) but it is a marginal contributor at the moment and is very difficult to see how they can grow it quickly and independently.
I'd guess that in 5 years from now revenues will still be comfortably below market cap and no profits. I suspect the child and adult mental health components will be sold to NHS or some form of public-private venture with low premium (maybe some forward marginal revenue share) and the company will be seeking to expand its corporate wellbeing biz (which is likely to be sub £10m revenue)
mojovision out
Obviously with a market cap of £2Bn Computacenter (LON:CCC) (I hold) is outside of the scope of these reports.
However, there was one interesting thing in their update today that may have broader implications, and to be perfectly honest I had not even thought of it before.
I don't think I have read anything similar from other companies thus far.
Just thinking out loud really, but if this becomes a broader practise what might the implications be? If it could be leveraged as an effect, it might allow companies to reduce their apparent net debt by encouraging early or pre-payments?
However, on the flip side, if this were to happen and companies were to become reliant on early customer payments it could cause a significant risk as and when interest rates unwind.
There's possibly nothing to this at all, but just in case I will looking more carefully at unusual changes to Working Capital going forwards.
I noted that too.
It basically says organisations are refusing to hold cash within the Eurozone. We need some smart people to work out the second order effects. But, some obvious things that must be happening...
Money leaves the Eurozone as people park cash offshore. Eurozone investment in non Eurozone locations must be rising.
Not onshoring cash - one wonders what the likes of Apple with Billions in non repatriated cash are doing. Can’t send it to the US can’t keep it in Euros.
Balance sheet stretch as buying assets (possible bubble?) becomes more attractive.
Borrowing is better than saving. What will this do for the PIIGS nations that had to be bailed out 9 years ago.
All in all, I don’t see this ending well.
Can anyone help me understand $ POLR rns this morning. CFO awarded employee options from 2016. Then sells 30k shares at current SP.
Should this be viewed as a negative as its the CFO selling immediate after receiving options? Or I'm I misunderstanding this.
Thanks
Hi Michael
It all depends what they are planning on doing with the money really, which rightly they should not have to explain.
I think the easier way to put this is like many people on here I have been awarded performance bonuses in shares, and also been part of multiyear share save schemes too. Sometimes I continue to hold these as I firstly have no immediate need for the money and believe that there is a potential further upside of the share price, or the share price is in the doldrums so trying to avoid selling in the dip. Though there were times that I immediately sold as we needed the cash and I did not care about what the price was or timing, just give me the cash.
Thank you
Tommy
ps. I hold Polar Capital Holdings (LON:POLR)
Polar Capital Holdings (LON:POLR)
The Company has issued 30,013 ordinary shares of 2.5p each ("Ordinary Shares") in full satisfaction of the option exercise and 30,013 shares were then sold at the market price of 669p per Ordinary Share.
Well it isn't exctly a great advert for the companies prospects these freebies/cheapos being ditched almost before they were lining the dudes pockets. Its possible there is an attached tax bill and he perhaps thought if im gonna sell some i might as well sell the lot.
There are some company officers (CFO's??) who don't really play the shares game and simply see stuff like this as their yearly bonus - so if thats the case it probably infers didly squat.
Never really come across this company before but the stocky numbers (particularly future profits) look pretty nice - looks like there was a bargain to be had here last march! for those that weren't in "Ostrich mode" like me at the time.
He’s improving liquidity :)
My morning smallcap tweet:
Directa Plus (LON:DCTA) Zytronic (LON:ZYT) Advanced Oncotherapy (LON:AVO) Trackwise Designs (LON:TWD) MySale (LON:MYSL) International Personal Finance (LON:IPF) Countrywide (LON:CWD) Treatt (LON:TET) Journeo (LON:JNEO) VR Education Holdings (LON:VRE) Kooth (LON:KOO) Works co uk (LON:WRKS), Character (LON:CCT)
Directa Plus (DCTA) contract with OMV Petrom extended and increased by €260k, to be delivered by June. [SP=88 Cap=54m]
Zytronic (ZYT) H2 downturn has now levelled out at approximately £2m in Q4 and Q1. EBITDA is positive "and we have seen a slight increase in orders in the new financial year to date. However, with the constraints imposed by the Coronavirus pandemic, that are affecting our major overseas markets such as Gaming, it is difficult to foresee a return to profits in this financial year" [SP=150 Cap=24m]
Advanced Oncotherapy (AVO) £5.9m placing at 40p, an 8% discount, to keep the lights on. [SP=43.5 Cap=145m]
Trackwise Designs (TWD) guides FY(Dec) rev £6.1m, lower than expected, op loss £0.2m - in line with market expectations. Year-end sales in both the IHT and Advanced PCBs divisions hit by lockdowns. [SP=330 Cap=94m]
MySale (MYSL) guides H1(Dec) EBITDA A$2.5m (-A$3.6m), ahead of management expectations, rev up 14%, reflecting "focus on its 'ANZ First' strategy and inventory light marketplace platform." [SP=8.95 Cap=84m]
International Personal Finance (IPF) Dec collections effectiveness 96%. "We are encouraged that the modest reduction in collections effectiveness we expected during Q4 did not materialise, but we continue to plan for a softening in performance in Q1 2021." [SP=79.7 Cap=178m]
Countrywide (CWD) Alchemy confirms it won't counter-bid. [SP=391.2 Cap=198m]
Treatt (TET) guides pretax in first 4 months ahead of mgmt exp. Optimistic that FY21 pretax will materially beatmarket consensus* of £15.1m. [SP=770 Cap=459m]
Journeo (JNEO) wins orders worth £1.3m with £1m for delivery this FY. [SP=48 Cap=4m]
VR Education (VRE) guides FY(Dec) rev c. €1.42m up 38%. Profit? "With minimal investment in marketing, sales and business development to date, the Group has closed deals during 2020 in excess of €1.8 million which should be recognised over the next 36 months." Sets target of €10m annual ENGAGE rev by 2025. [SP=12 Cap=29m]
Kooth (KOO) guides FY(Dec) U/L rev £12.5m to £13m, ahead of market expectations. Profit? [SP=267.8 Cap=89m]
TheWorks (WRKS) H1(Oct) rev down 8%. LFL up 10% in period when stores were open, significantly ahead of the Board's expectations. Adj pretax -£4.1m (-£7.8m). FIrst 11 weeks of H2 rev down 25%. [SP=34 Cap=21m]
In line: Character (LON:CCT)