Small Cap Value Report (Fri 22 March 2019) - VLE, SPE, PMP, TFW, XAR, SFE

Good morning!
News today has thankfully calmed down a little, at least as far as UK small-caps are concerned.
This means I can go back and look at some of the stories I've missed this week:
- Volvere (LON:VLE)
- Sopheon (LON:SPE)
- Portmeirion (LON:PMP)
- FW Thorpe (LON:TFW)
- Xaar (LON:XAR)
- Safestyle UK (LON:SFE)
From today's news, I might look at:
- Henry Boot (LON:BOOT)
- Robinson (LON:RBN)
Volvere (LON:VLE)
- Share price: £11.25p
- No. of shares: 3.1 million
- Market cap: £35 million
(Please note that I have a long position in VLE.)
I've been slow to update on Volvere. This might seem strange, given that it's my biggest holding, at 16% of my portfolio.
However, I felt there was little to say, since not much had changed as a consequence of Tuesday's trading update.
This update was the first piece of news since October. Things move slowly in Volvere-land!
Results for the year ending December 2018:
- revenue from continuing operations improved to £18.6 million from £16.2 million. £18.3 million of revenue is attributable to Shire Foods. The rest to Sira Defence.
- underlying result before tax from continuing operations is £100k.
Segmental Analysis
Shire's profit before tax and intra-group charges was £790k.
Volvere plans to invest £2 million into Shire in 2019, in the form of new plant and equipment.
Francis wrote a great comment on Wednesday after attending the company presentation, explaining that the focus is now on expanding Shire's vegan/vegetarian and healthy pies. The product range has already expanded a lot over the past year.
I still have a pretty good impression of Shire: could it be worth £10 million+ on eventual disposal, or is that too much to hope for? It has a freehold property in Leamington Spa, blue-chip customers and a decent track record. I'd like to see it generate PBT before intra-group charges of £1 million+ this year, but I know that it operates in a fairly competitively sector so I'm not going to get carried away at this point.
On top of that we have Sira. Up until now, its results have been too small to move the needle. It remains small: revenues of £300k, profits of £60k.
Nice comment on Sira in the trading update, suggesting progress could be seen in 2019:
Although the company's financial performance was very similar to 2017, a number of reseller partnerships were signed in the period, which are expected to make a contribution in 2019 and beyond. The company continues to invest in its intellectual property which it believes is unique.
I'm not in a position to assess Sira's technology. Dozens of police forces are said to be using it, at least. If it does turn out to be a winner, I will see that as a bonus. At any rate, I'm confident that Volvere management won't lose money on it!
Cash
So that's where we are in terms of the operating businesses.
As far as the balance sheet is concerned, Volvere has net assets of £40.3 million, of which cash is £34.1 million. These numbers translate to NAV per share of 1292p and cash per share of 1100p.
I suppose the main problem for prospective investors might be the spread: there seems to be very little liquidity available in the shares, with a 1050p bid and a 1200p ask. Making a quick turn on this share is unlikely. If we hang around for a long time, however, I think we might do well. I've been here since May 2016.
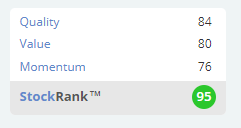
The StockRanks love it, calling it a Super Stock. This is before the Value Rank gets updated for the much higher book value following 2018's success!
Sopheon (LON:SPE)
- Share price: 915p (-6.6%)
- No. of shares: 10.1 million
- Market cap: £92 million ($121 million)
This share was near 1150p on Wednesday. A nasty fall over two days.
I've written about this software company before. thinking that it's strong performance justified a share price in the region of 1000p.
2018 numbers are great, as expected. They are "comfortably in line with already upgraded market expectations".
- Revenue $33.9 million (2017: $28.5 million)
- PBT $6.4 million (2017: $5.1 million)
- Net cash $16.7 million (2017: $9.5 million).
The enterprise value (market cap minus the December 2018 cash balance) is therefore $105 million.
Customer wins keep growing (18 versus 13 last year) and the company remains bullish on the widening applicability of its software for innovation and strategic management.
Current year revenue visibility is $20.6 million, 7% higher than a year ago. Two-thirds of revenues are coming from existing customers, suggesting some robustness to the company's income streams.
Outlook - confident that the company has a big opportunity. There is a significant increase to the proposed dividend. And there is the possibility of M&A deals, "provided they align with our strategic priorities".
Scary prospect - "over 40% of companies on the S&P 500 will no longer exist within 10 years due to their inability to operate with agility and speed in today's hyper paced changing markets". If that's true, it shows the importance of finding companies immune from the disruption (or which cause the disruption!).
Clear writing - I applaud Sopheon for writing clear and understandable prose throughout the results statement.
Why the share price fall?
It turns out that FY 2019 forecasts were slightly reduced as the Chairman signalled an intention "to accelerate investment and solidify our leadership position". The adjusted EBITDA estimate was reduced by 1%.
That might not seem like much, but when you have a company rated at a high level, I suppose there is always that risk of a re-rating lower, if growth starts to look a little weak. Revenue growth in 2019 is forecast at 9%, and adjusted EBITDA is expected to reduce year-on-year.
It's not the end of the world by any means. Long-term, the outlook here still sounds bright (though I've not had a close look at the company's products, so take that with all the necessary grains of salt!).
The problem is just that the rating demands the quick resumption of growth:
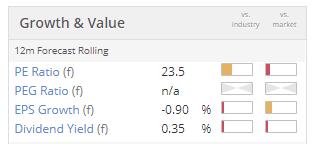
Considering the cash balance, which supports the valuation, I would think that this is worthy of further research at the current level. EV/trailing EBIT is c. 16x.
Portmeirion (LON:PMP)
- Share price: £10.70p (unch. today)
- No. of shares: 11 million
- Market cap: £117 million
This tableware group keeps making steady progress. 2018 was another record year.
It runs an efficient operation with good margins (around 11%) translating to even better ROE and ROCE, thanks in part to strong asset turnover (I discussed this metric earlier this week in relation to IQE (LON:IQE), and wanted to give a counter-example of a company whose asset turnover is actually rather good!).
Average assets at Portmeirion during 2018 were c. £66 million, from which it generated revenues of almost £90 million.
Only modest borrowings were used, and the current ratio finished the year with a very secure reading of almost 3x.
In other words, this looks to me like a solid copany earning good returns, in a safe way.
It has five brands: Portmeirion, Spode, Royal Worcester, Pimpernel and Way Lyrical.
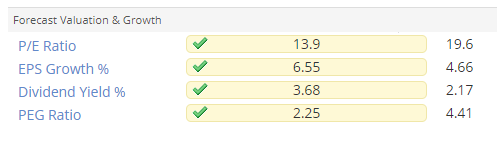
There currently seems to be a mismatch between the valuation of Churchill China (LON:CHH) and the valuation at Portmeirion (LON:PMP), with PMP being the much cheaper of the two. Does anyone know why? CHH does earn a higher operating margin.
Looking at some valuation metrics, PMP is on the left-hand side and CHH is on the right-hand side (using Stocko's comparison tool):
FW Thorpe (LON:TFW)
- Share price: 325.5p (-0.2%)
- No. of shares: 116 million
- Market cap: £377 million
FW Thorpe Plc - a group of companies that design, manufacture and supply professional lighting systems - is pleased to announce its interim results for the six months ended 31 December 2018.
This is a highly-rated, family-controlled business.
These H1 FY 2019 interim results aren't great - a 10% decrease in operating profit - but the company says that most of the subsidiaries are trading around their H1 FY 2018 levels.
The company which lagged behind in H1 (Thorlux) is also said to be "back to 2018 levels".
However, results at some international sales offices are disappointing.
Outlook - this year won't be as good as last year, but it won't be a disaster, either. H2 should be better than H1. Conditions are "more buoyant than we previously predicted".
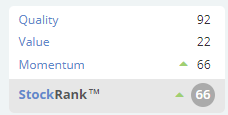
My view - not motivated to look into this any further, as the valuation looks very full and I think it will be difficult to find ways to justify this.
StockRanks agree with my assessment:
Xaar (LON:XAR)
- Share price: 118p (+1%)
- No. of shares: 78 million
- Market cap: £92 million
Xaar makes a big loss in 2018, as expected.
The cash balance has fallen a lot, too, due to investments in new technologies (3D printing!).
The old revenue stream, based on unstable demand from the Chinese ceramics market, has collapsed. The company says that 79% of 2018 revenue was derived from products and businesses introduced in the last 3 years.
Outlook - an "exciting future, even with some risks plainly in view".
My view - I'd be interested to buy into this on a deep value basis, i.e. the valuation fell so low that a competitor or larger business could buy it up "for free".
The balance sheet shows net assets of £132 million, or net tangible assets of £94 million.
More losses are set to be incurred this year and next year, so unfortunately it's probably still too soon to get into this as a deep value play. I might keep an eye on it, though.
Safestyle UK (LON:SFE)
- Share price: 72.7p (+3%)
- No. of shares: 83 million
- Market cap: £60 million
Safestyle UK plc (AIM: SFE), the leading UK-focused retailer and manufacturer of PVCu replacement windows and doors for the homeowner market, today announces its final results for the 12 months ended 31 December 2018.
Another share with predictably bad results. I mention it just out of morbid curiosity.
There is an underlying loss of £8.7 million (2017: £15.1 million profit) and a statutory loss of £16.3 million (2017: £13.8 million).
What an amazing deterioration in performance. The cause was "an aggressive new market entrant", i.e. SafeGlaze.
SafeGlaze has itself gone into administration. It went into administration shortly after it signed a commercial agreement not to compete with Safestyle.
The founder of Safeglaze also happens to be a co-founder of Safestyle, and it sounds like he will be very handsomely rewarded by this commercial agreement.
Outlook - the turnaround is underway and the company is striving to get back to profitability.
My view - not something I'd want to invest in, seeing how easily it was disrupted by a former employee. But I'll be interested to see how it does now that the former employee has promised not to dirsupt them for the time being.
That's all for now. Thanks for dropping by and for your comments.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Even if it's only 30% this underlines the attraction of a tracker ETF like VOO where our abilities as the pickers of winners are not tested - decisions on promotion and relegation are out of our hands. The S&P 500 is up 50% in the past two years who among us can claim to match that?
I need to go away and have a serious think about what I have just written.
Bonitabeach
Hi, thanks for the Sopheon perspective. I wonder if the share end 2017 share issue has caused some confusion. The 2018 Diluted eps was increased by 16% BUT the Basic eps actually declined by 6%.
I also need to re-read the comments on challenges hiring US software engineers - is overcoming this a cost hit or revenue opportunity for 2019??
Thanks Graham.
For sharing that stat that 40% of the S&P 500 will not be around in10yrs time, shows you that with technology change just how tough investing is,let alone trying to beat the market on a consistent basis.I've read hundreds of books & haven' once come across that. ,
Love the comments about slow pace at VLE. I guess if buying IAL for £1.3m in March 2015 and selling it for £31m in Oct 18 is your idea of slow paced you have been smoking something extraordinarily good :)
A possible takeaway from the Safestyle UK (LON:SFE) debacle could be the danger of investing in newly listed companies. As has been pointed out before, the promoters of these companies know far more about the nuts and bolts of the business than almost any private investor. They can choose their moment very carefully to maximise returns. I would suggest that it may make good sense to give these enterprises a grace period of, say, two to three years so that any skeletons can fall out of the cupboard.
Re Churchill China (LON:CHH) vs Portmeirion (LON:PMP) - not an explanation just an observation - the former is primarily B2B the latter B2C. Portmeirion (LON:PMP) caters more to discretionary spend? Neither of these are good reasons, I admit. I have been a long-term holder of Churchill China (LON:CHH) and management are solid. But you have made me question my position!
Just to add to Mammyoko's correct observation:
Op margin CHH `15.2% PMP 10.7%
Net cash CHH £13.7 mn PMP -£ 1.25 mn
Data from Stocko. Could explain some of the higher P/E for CHH.
I hols CHH and am thinking about buying PMP again.
Many thanks Graham re sopheon.
Thanks for the report on Volvere (LON:VLE) Graham. Are you suggesting the Volvere Landers move slowly ?
Fine by me as the last thing I want is management who cannot wait to throw the money at the first opportunity that comes along. I have a small position in this.
I did have a quick look at their property in Leamington via google. On an industrial estate, which I guess would be the old AP Braking site. Although it's opposite housing, I doubt the site could be developed for any non-commercial purpose.
[And google maps shows a Trabant parked on the drive of one of the houses opposite].
Hi Jason, thanks for the comment and insight. I am perfectly happy with the pace at Volvere - suits me fine. G
Debenhams (LON:DEB)
Possibly below the SCVR market cap limit, (and probably not the 'value' part either), but more news on an oft mentioned share:
https://www.bbc.co.uk/news/business-47666249
"Debenhams seeks £200m in new funds"
A few RNSs too, regarding bonds and MAshley's offer for Magasin Du Nord, Debenhams' Danish business
Oh ! It's near-doubled since from today's low, so could be big enough now !
p.s. @purpleski (#6) - my name's not Debenhams ;^)
p.p.s. I'd like to add to other recent comments, in that although there's not been any/many shares in the SCVR that interest ME, the reports and comments have been very interesting TO me - Thanks P&G and Stockopedians (that could also be construed as a nudge for your thoughts on Volvere (LON:VLE) lol)
Hi DJCP
Gosh do I feel stupid.
Thx.
Graham, I would very much appreciate some comments on Sopheon. Although their results seemed quite good, they are now down 20%. Perhaps got ahead of themselves?
Hi Roger, I plan to look at Sopheon (LON:SPE) today since the news is a little quieter (ignoring b*****).
That was my reading too - no further positive news since the update. Revenue visibility, recurring revenue, new clients all flat on previous update from a stock where market (expected and valuation demanded more.
I initiated a starter position recently, which is now underwater, but find it more attractive now than when I purchased
Growth/ new business I expect would be lumpy for a business such as this but did not see anything in the results that was concerning
Eagle Eye Solutions (LON:EYE) reported H1 results last week. Here's their results presentation.
https://www.piworld.co.uk/2019/03/22/eagle-eye-solutions-group-eye-h1-2018-results-presentation-13-3-19/
A very clear presentation by by Tim Mason CEO & Lucy Sharman-Munday, CFO
Gives a great overview of the business. What they've already achieved. Where they’re headed. And how they're going to get there. With comprehensive detail on the financials at half year. The Waitrose contract sounds very positive.
Henry Boot (LON:BOOT) (260p)
Had a quick look at this company - can't remember having looked at this one before which is strange.
Initial thoughts are wow this is a company i could buy some shares in immediately.
EPS 28p - estimate was 26.7p so looks like a slight beat, although estimates during the year dipped from 28p to 27p. So bang on the money.
Estimated 2019 EPS 27p
Outlook statement seems fine
We anticipate that 2019 will be a challenging year, as the UK real estate sector adapts to the marketplace in anticipation of the UK's departure from the EU. In advance of this, we have taken the opportunity to reduce gearing through 2018 to take advantage of any opportunities which may arise through 2019. Henry Boot Construction has started the year with a strong committed order book, certain commercial developments anticipated to start during 2018 have now commenced and one sale expected to complete in 2018 completed in January 2019.
Ok thats pe of 9.6 - seems cheap - but they deal in land so that may be pe of 999.99 come the next recession.
Whats the debt
Net debt reduced to £18.4m (2017: £29.0m) with conservative gearing at 6% (2017: 11%),
Ok thats pretty much dream numbers from a risk point of view.
Looks like the net tangible assets looks like 297 mill - shares in issue - hmmmm prefernce shares make this confusing. Lets turn to market cap per stocky 346 mill. So TNAV covering 855 of the shareprice.
Is there a secret piggy bank that will "guarantee" or at least help substantiate future earnings? (one can but hope)
The two key profit drivers within the Group are: Hallam Land and Henry Boot Developments. In 2018, Hallam Land, our land promotion business, performed exceptionally well, selling over 3,500 units on 24 sites to help replenish the UK housebuilder's development land inventory. It retains a site portfolio of 14,325 acres and still holds 16,489 units with planning permission, held at cost with no planning gain value recognition, that are working through the sale process.
Wowsers they hold 14k sites that looks like 4 years worth of future business just waiting to be actioned.
Hmmm - well they make a profit on these unit sales though?
As our strategic land portfolio is held as inventory, accounting policy requires these assets to be held at the lower of cost or net realisable value. In accordance with this policy no uplift in value can be recognised within our accounts relating to any of the 16,489 plots over which planning permission has been secured. Any increase in value created from securing planning permission over these assets will therefore only be recognised on disposal.
Ok thats about as good as on can hope for profit not booked till sale and they have great pipeline of sales - looks like a nice secret piggy bank to me.
Other than land prices / recession fears i can't think of any reason not to snap up some shares right now - can anyone else - hmmm what are those preference shares though?
Oop forgot about the divi - is there one ? - yep 3.7% seems about right
Morning Graham
I would be interested in your views on Henry Boot (LON:BOOT), which you have previously reviewed. This morning's results are I think overall pleasing, although the immediate future, as with many UK smallcaps is clouded by the current political chaos. However Henry Boot (LON:BOOT) reports a positive start to the year and if one subscribes to the maxim of never wasting a good crisis it looks interesting.
Also if you have an opportunity, perhaps you might at look at Portmeirion (LON:PMP) that produced very creditable results yesterday.
Robinson (LON:RBN)
It's hard to get any enthusiasm with regard to this company based on the current level of profitability, the debt (substantially up by the looks of it) they have and the amount they seem to need to be investing in plant etc to generate the profit they do.
Ok they could sell the surplus property and possibility/presumably be debt free but looking at the earnings history over the last 5 years it's simply way to patchy to be worth taking the risk of owning the shares from my perspective.
Having said that it looks like good news today and i could easily imagine the shareprice doubling if they can continue to progress the business forward. I just don't think they have a solid enough downside protection if things get tougher again in the future.
Hi Robinson
"It's hard to get any enthusiasm with regard to this company..." Which company please?
Thx
Best accidental comment ever. Especially on a Friday! :)
Hi rmillaree
Gosh do I feel stupid.
Sorry
Thx.
Graham I wondered if you have any thoughts on XLM. I appreciate you have commented on them in the past and I do appreciate they are an overseas business listed on AIM with all the beware signs flashing. BUT they have a momentum rating of 14 (so noone is interested) but quality and value are good leaving them with an overall stock rating of 77. That's decent. They have an A+ in the magic formula. Bal sheet looks strong with total assets minus goodwill and intangibles just under double the total liabilities. Cashflow looks healthy and the bit I like is they are using it to buy back shares, 10% of the total issued. The price appears to below the issue price 5 years ago. With the exception of being an Israeli company listed on aim I am struggling to see why this share isn't cheap. MArgin 30%. Yield 8% covered nearly 2 times. I am naturally cautious, I don't hold these shares at all but I am starting to lean toward a small purchase. Arghhhhhh................I think I will think about it a bit longer.
XLMedia (LON:XLM)
Is the trendy in reducing sales not a big worry with regard to this share?
$137 mill 2017
$117 mill 2018
$94 mill estimated 2019
In the last month alone 2019 profit estimates have dropped by $5.5 mill from $32.7 mill to $27.2 mill.
However, the strategic shift away from Media is expected to reduce 2019 revenues by approximately US$30 million. This, together with increased Publishing investment, will largely account for an expected reduction in 2019 adjusted EBITDA of between US$6-7 million.
What about 2020 - is this trend going to reverse itself?
I guess the main question is how confident are you in the stability of the companies main profit generating streams to be confident that it will be churning out a similar level of "easy" profits over the next 5 years or so.
This just seems such a hard sector to get a decent handle of exactly how they make their profit and how sustainable this is. If there are future headwinds coming up shareholders with no sector knowledge will probably be the last bods to see any bad news coming (like last months news). It maybe that the price is so low purely down to bods not taking the chance as they think something is wrong when it isn't - but i am not sure this is the kind of share that i would want to be betting that the shareprice is actually below its true worth.
Thank you rmillaree. The points you make are sound. I got the impression that the hits from the regulatory issues are now behind them but perhaps I am premature there. I like that they are refocussing on marginMy understanding is with a margin around 30% they have a moat . But I take your point and with aflash pointing out they will report on 26th I think i will adopt a wait and see policy. Thanks to both of you.
Upcoming XLM Events
Tuesday 26th March, 2019
Full Year 2018 XLMedia PLC Earnings Release
This information is from the Stocko page. Go to the bottom left hand side.
XLM should provide some info next week and the SCVR people should comment.
My morning smallcap tweet: Friday sees Robinson crew so confident
Robinson (LON:RBN)
Robinson (RBN) FY rev up 10% to £32.8m vs F/C £32.2m. EPS 4.2p vs adj F/C 4.8p (comparable?). Outlook: "we feel the business is in a much stronger position to face the challenges in front of us and we expect to achieve double-digit sales growth again in 2019. We also expect a marked step-up in profitability, ahead of market expectations, arising from our "Strategy into Action" program."