Small Cap Value Report (Fri 22 Sep 2017 - Part 2) - PURP, TFW, COG

Good morning! Paul here. I didn't manage to finish yesterday's report, so thought I'd resume reporting on a few more companies from yesterday. Graham is putting together a separate report for today's results - which will be quite short I think, as there's not much of any interest.
Purplebricks (LON:PURP)
(at the time of writing, I hold a long position in this share)
Audiocast - for a bit of fun, I've decided to record an audiocast today with Lucian Mears, a well-known bear, who I've got a lot of time for. I'll publish it on my QualitySmallCaps.co.uk website later. EDIT: Here is the link.
The share price is certainly dropping heavily at the moment. Although it's difficult to know how much of that is the impact of negative publicity from bears, or how much is due to the general profit-taking in growth shares at the moment?
I feel that the bears do actually have some valid points. Although I remain bullish, because there is no doubt that online estate agents are disrupting the sector greatly. PurpleBricks is by far the market leader in the UK. If its new operations in California start doing well, then the market cap could go through the roof. Although it's already eye-wateringly high.
Going back to some announcements from yesterday, here goes:
FW Thorpe (LON:TFW)
Share price: 347.5p
No. shares: 115.7m
Market cap: £402.1m
Preliminary results - for the year ended 30 Jun 2017.
F W Thorpe Plc, designers, manufacturers and suppliers of professional lighting systems for the specification market
By "specification market", I presume they mean for construction projects?
The company issues very few RNSs, so the last update was the interim results, which I reported on here, on 16 Mar 2017. Interim results were good, and the outlook used the company's usual phrase of being "optimistic of a satisfactory overall result for the year".
There don't seem to be any brokers reporting on this company, which is very surprising for a £402m market cap company. Although it's effectively a family company, which happens to have a listing.
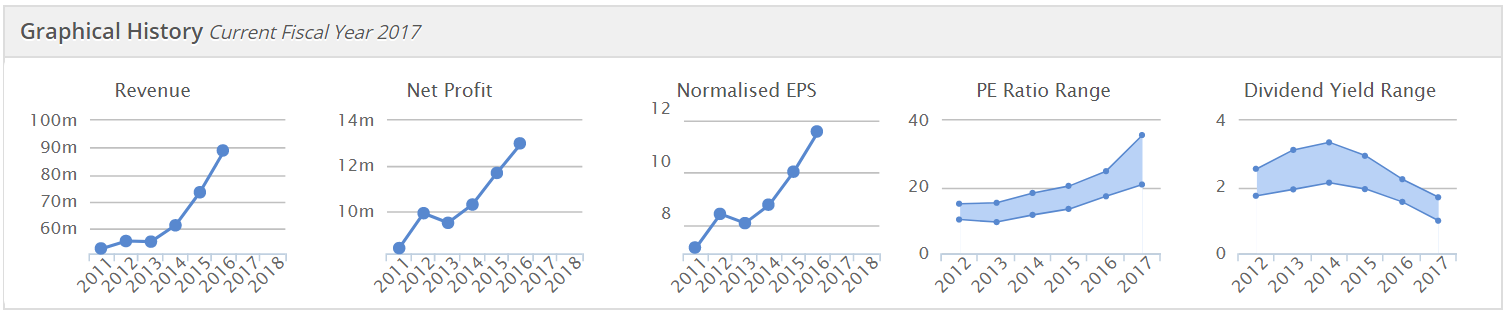
As you can see from the Stockopedia graphical history above, the company has performed well for several years. However, as graphs 4 & 5 show, the PER has gradually been going up, and the dividend yield coming down. So the key question now is surely whether the shares might now be too expensive? It's undoubtedly a good quality company, but everything has a price.
Here are the highlights from today's full year results;
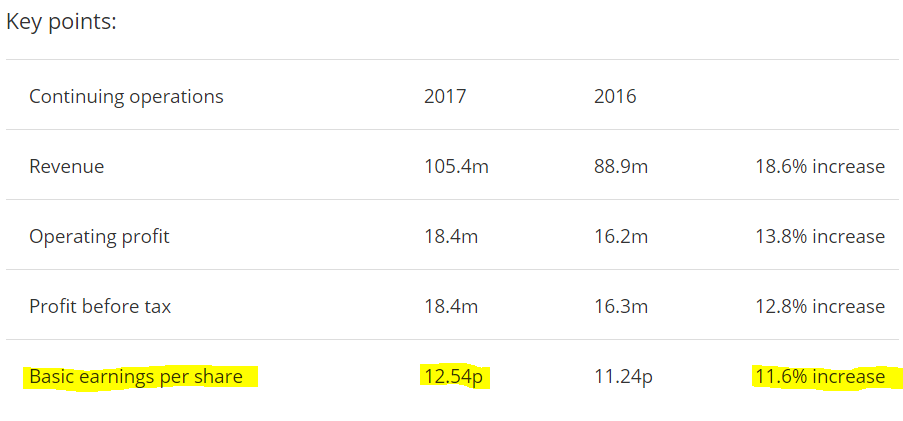
Valuation - with the share price currently at 347.5p, the PER is 27.7 - that strikes me as considerably too high. Does EPS growth of 11.6% justify a PER this high? I don't think so. I imagine that results have probably been helped by favourable forex movements - since its European operations profits would translate into a higher sterling reported amount.
Dividends (interim + final) are up 21% to 4.9p - giving a yield of only 1.4%. The company has also occasionally paid small special dividends. Given that it has so much spare cash on the balance sheet, I cannot understand why the dividends are not more generous? What's the point in hoarding cash, which earns little to no return?
Outlook comments don't sound particularly confident. Although I think the company tends to have an under-stated style of communicating.
This year's excellent performance will be difficult to replicate, as we will have to contend with ongoing economic uncertainty from Brexit, government instability and exchange rate variations.
We see ourselves better placed to respond to these issues nowadays, with manufacturing facilities in the UK and in mainland Europe, as well as revenue generated in a number of different countries from our own local sales offices.
We continue to review options for further acquisitions. We have the financial capacity, so it could be said that it is easy to acquire, and there are indeed frequent options for us to review.
To find the right acquisition - one that meets our criteria and does not become a future liability - is not as easy as it might seem. The general management team remains the same experienced group, and our intention is to continue on the same path of steady, sustainable growth.
Balance sheet - this is very strong indeed.
NAV is £101.3m
NTAV is £85.4m
Current ratio (working capital) is 4.34, which is amazingly high. The company has excess working capital really, which includes £17.0m of "short-term financial assets", which I think are cash term deposits. There's also £24.7m in cash. There's no interest-bearing debt, so net cash is £41.7m, or 10.4% of the market cap.
Acquisition - if, say £30m of the surplus cash was used to make an acquisition on a PER of, say 12, then that would bolt on £2.5m in extra post-tax earnings. 2016/17 earnings were £14.5m, so such an acquisition has the scope to increase earnings by c.17%. This goes some way to explaining why the PER is so high.
The difficulty of course, is finding the right acquisitions. I think the management at TFW are very grounded, and won't risk buying anything unless it fits the bill.
My opinion - this is undoubtedly a very nice, family company, with strong management and a great long-term track record. However, as you probably gathered from the above, I feel that the shares are now significantly over-priced. To my mind, a PER of about 15-18 would be more appropriate, even when you factor in the surplus cash.
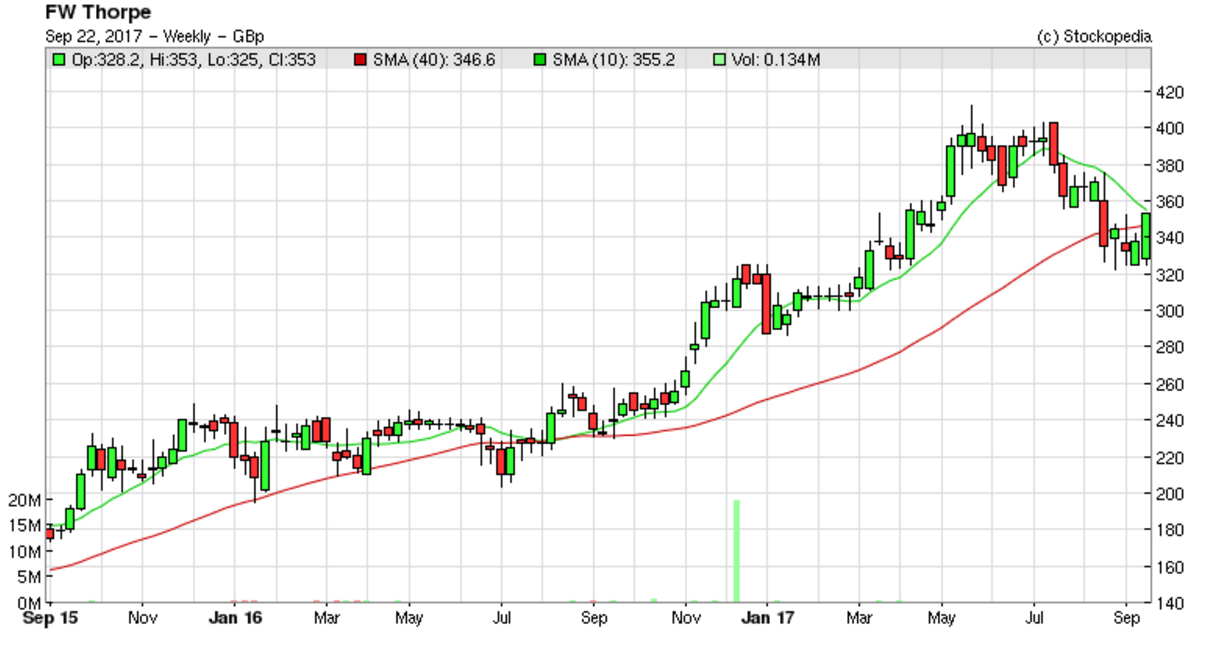
Earnings have risen steadily in recent years, but a lot of the share price appreciation has been due to multiple expansion - i.e. the market being prepared to pay a higher & higher PER for the shares. That won't last forever, and would likely go into reverse in a bear market. For that reason, I can't consider this a sensible investment at the current price. It's done very well historically though, but at some point you do have to consider whether the valuation has become too stretched?
Cambridge Cognition Holdings (LON:COG)
Share price: 152p
No. shares: 20.5m
Market cap: £31.2m
Half year report - for the 6 months to 30 Jun 2017.
The neuroscience digital health company Cambridge Cognition Holdings plc, (AIM: COG, 'the Company'), which develops and markets software products to improve brain health...
I've covered this company quite a lot in the past, as it always looked potentially interesting, albeit in a jam tomorrow kind of way. The share price has doubled this year, so the interim results must be good? Sadly no, they're really not.
- H1 2017 revenue down 1.7% to £3.2m
- Still loss-making - with a loss before tax of £386k in H1 (worse than £145k loss in H1 2016)
- Net cash of £1.8m, which looks adequate, providing losses don't worsen
So why have the shares doubled this year? Partly I think because we're in a bull market, where investors are very receptive to positive newsflow from growth companies. Partly also because the outlook seems to be improving, so there might actually be some jam served up in the future, possibly?
Sales order pipeline increased by 65% to record levels
Outlook comments;
With modest investments in commercial infrastructure and R&D activity we have transitioned to an improved blend of product and service revenues. Both the sales pipeline and the innovation pipeline are stronger than in recent history at a time when there is substantial appetite for both neuroscience and digital health solutions.
We expect a strong second half to 2017 as we continue to convert our order pipeline and we are confident in the growth potential of Cambridge Cognition into 2018 and beyond.
I do wonder what the company's idea of "strong" might be? Historically performance has been lacklustre, with only a tiny profit being eked out in good years, and losses the rest of the time.
My opinion - this is a share I held for a while in the past, but got bored at the slow pace of progress, and moved on. There's definitely something good here - the company is highly experienced in its sector. I'm just not convinced that the company can deliver enough scale, or profits, in a reasonable enough timescale, to justify parking some money in its shares again.
That's it for this week, have a lovely weekend!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
In all the discussion about the PURP launch in the US there seems to be no mention of the likely competition from Redfin(RDFN) which recently had a successful IPO. It has been going several years in the "broker disruption" market, and on a recent visit to the US I found it to be a recognized, national name. Their model is somewhat different to PURP notably in that it's experts are full time employees and its fee rebates are still percentage based rather than the fixed cost model that PURP is making its business model.
But it has been successful in lowering fee percentages and the recent IPO will give it some significant financial firepower.
Paul, I haven't completed listened to the webcast yet. However, I think generally investors can confused growth prospects and market shifts with profitability and long-term prospects. This kind of logic is built on false thinking. I.e. we are going to shift online, Purplebricks is the leader therefore it will do well. It is like saying we will shift to electric cars, Tesla is currently the leader and therefore it will do well.
The truth is that almost any company can buy growth by investing heavily in marketing or by having a price point that makes no money. The crux for Purplebricks is that there isn't any competitive moat here. Can I suggest you look at the book: The Little Book that Builds Wealth: Dorsey. All Purplebricks does is take an instruction and advertise it on Rightmove. This is pretty basic stuff. You could set up a business doing the same thing tomorrow.
Just to give other examples there was a company called Outsourcery that basically said computing is going to the cloud and we are a pure play on that area. Investors bought in at an inflated price and I think it went insolvent a few years later.
There needs to be a good business franchise and product. Purplebricks is just a generic product with a lot of heavy advertising behind it. The only way a business makes excess profits/returns over the long-term is by having significant barriers to entry. Where investors go wrong is equating growth with a long-term competitive franchise.
The idea that Purplebricks will somehow conquer Australia and the US with no competition is just laughable. If it is an easy way to make money everyone else will copy it. There are already dozens of competitors in the UK. In the Australia there are also a few. I agree that Purplebricks has done some catchy advertising and has successfully differentiated itself as a "hybrid" online agent. But that is just marketing BS. The market share of Purplebricks in the UK could easily come down when consumers see that it is an emperor with no clothes.
I scored it 6 - 1 to Miers in the Purplebricks face-off. A bonus point to Paul for his graciousness in defeat : )
Good discussion on Purplebricks. Clearly the current valuation depends on them making a success of the US market, where total costs (buying/selling agents) are indeed horrendous. But they have been like that for many years. The service the US agents provide may simply be a lot better than the typical UK estate agent so folks are happy with the fees and whether Purplebricks can establish a different model remains to be seen. I do not currently hold the stock but I have in the past. I'm waiting to see, but the speculation in the stock tends to put me off. Any stock debated so much on bulletin boards, and where valuing the company is so tricky, likewise.
Hi Paul
Very interesting discussion between you and Lucian Miers re Purplebricks (LON:PURP). What I found really interesting is how Lucian appears to discuss the company as a story rather than in financial terms, he was light on facts and figures and heavy on description of the business. His view that Purplebricks (LON:PURP) do not act in a similar way as a bricks and mortar estate agency is in my experience incorrect, I have used them and they carried out the viewings and acted as go between on price discussions, their open website give customers complete oversight on potential buyers and progress. That said, I'm not convinced by their charging method and their online conveyanceing services are in my experience quite poor, not to be used by me again.
I have bought (refurbished) and sold a considerable number of houses and I am of the view that many estate agencies use the housing stock on their books to leverage their business ahead of doing what is right for the seller. A simple example of this is to channel new listings to their own clients in order to complete a chain, thus not giving other would be buyers a viewing thus does not beget the best price for the seller.
Prior to your discussion I viewed Purplebricks (LON:PURP) as a good shorting opportunity but found your arguement based on fact and figures to be much more convincing than Luciens story approach, although I wont be purchasing any myself.
As always, keep up the good work, your contributions are always very much appreciated.
Edit: I think the 6% estate agency charged in the USA is absolutely absurd, PB's impact in this territory could lead to an increase stock turnover should their business plan work as it would make moving so much cheaper.
Who was it that said "your margin is my opportunity"?
Peterthegreat
I was going to post something v similar about highly priced IHT favourites - there are a whole bunch where the share price seems self supporting. Halstead & Nichols are 2 that spring to mind.
One point though - I don't think you lose the IHT benefit if you sell after 18m and reinvest in another IHT qualifying stock. If I'm wrong, I'd be v grateful to be told!
Garbetkib
Yes I agree with your understanding of the IHT benefit.
Any other similar stocks that come to mind??
Mrken
James Latham (LON:LTHM) is another very well-run, family-owned company with a conservative balance sheet. The shareprice has also done well (up 45% in 12 months) and it is looking similarly expensive... these are great companies to buy and hold, but starting in 2009 not now. There will be better entry points in the next few years I feel.
Sorry, should have said that F W Thorpe was founded by Mr. Thorpe the Elder rather than Mr. Thorpe the Younger!
Hello Paul,
Re: Thorpe, I would suggest that the explanation of its apparently high rating is because this is a classic example of the type of AIM company bought in order to provide 100% inheritance tax exemption after the shares have been held for two years. Family type companies are popular with investors seeking this tax advantage as they are perceived as being stable and good reliable bets which is important as you clearly would not want to sell after 18 months as you would never gain the inheritance tax benefit. I hold quite a few such companies (although not expecting to die soon) and they are nearly all highly rated and have been this way for years. You will also find that Hargreaves Hale is a major shareholder in many of these companies as they run funds which provide investors with the inheritance tax exemption and there are other managers who run similar funds and I am sure this helps keep the share price high so perhaps you could regard them as a play on the aging population! Nearly all these investments have been successful over the past 8 or so years but the obvious downside would be if HMRC removes their tax advantage, although I can see no sign of this happening at the moment. You ask what is the point of Thorpe hoarding cash when it provides so litlle return? Well of course I can't be certain of the answer, but one possible reason would be that they are looking out for acquisitions and expect it to work out cheaper to retain this cash rather than paying it out to shareholders and then needing to raise further funds when the acquisition turns up. Another reason would be to provide a large safety margin in the event that the company's business is hit by a major downturn. In other words I would suggest that, like nearly all family companies, they are run with a boring, long term outlook which perhaps explains why the company has been running successfully along similar lines since it was founded by Mr. Thorpe the younger in 1936. I accept that such companies are not to the taste of most investors, although their share prices do suggest that they have a following.
Hi,
Thanks for clarifying on that point. So I guess that the key thing for FW Thorpe (LON:TFW) is to build relationships with architects, etc, to ensure that they specify its kit.
Regards, Paul.
Hi paul,
Re Thorpe, the specification market is when items are specified in tender documents (by architects, design engineers etc). So contractors quote to the specification, which can be for new-build or refurbishment contracts (such as social housing and commercial/ industrial buildings etc).
Spot on IE. The other notable point is that the specification market should allow higher margins as contractors have less room to push costs down on a specified product.