Small Cap Value Report (Fri 23 Mar 2018) - Macro Thoughts, RBN, CNKS, BOOT, SPRP, QXT

Good morning!
There was some discussion in the comment thread last night about the effect of reader suggestions on the SCVR, which I haven't had a chance to respond to yet.
If you do have any comments or suggestions for today, please fire away.
On the macro front, the FTSE-100 closed lower by 1.2% at 6953 yesterday, returning to December 2016 levels, and is set to open lower again today.
Small-caps on my radar today are:
- Robinson (LON:RBN)
- Cenkos Securities (LON:CNKS)
- Henry Boot (LON:BOOT)
- Sprue Aegis (LON:SPRP)
- Quixant (LON:QXT)
There have also been announcements for the big-caps Next (LON:NXT) (which I hold) and £AV.A.
Graham
Macro Thoughts: The market is worried about trade wars after Trump announced $60 billion of tariffs on Chinese steel and aluminium. Do we care about this story at the SCVR? For now, I don't think so. The success or failure of individual companies is still more interesting.
Something I do care about is the level of the FTSE, so to the extent that jitters send the FTSE lower, I do take notice.
Personally, I've been keeping track of the FTSE All-Share Total Return Index against my personal portfolio since 2011.
I also watch the FTSE-100 Index as a measure of how invested I should be. Ideally, I will increase my equity weighting as the index falls. And if the falls become extreme, I would even be willing to take some leveraged long positions in stocks.
Stockopedia has helpfully saved the lines I drew on the FTSE-100 chart the last time I looked at it, during the big fall in early February:
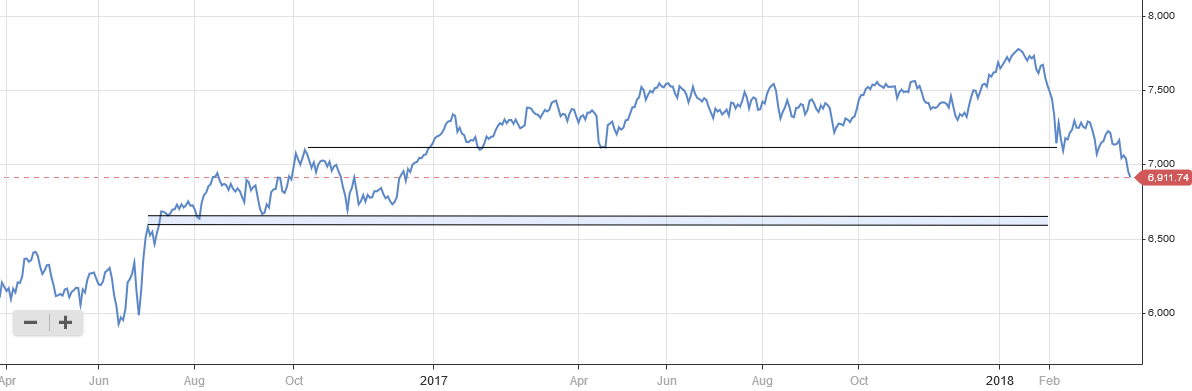
The 7100 level provided support for a while, but is out of the picture now and from a technical point of view we look headed towards the 6600 mark.
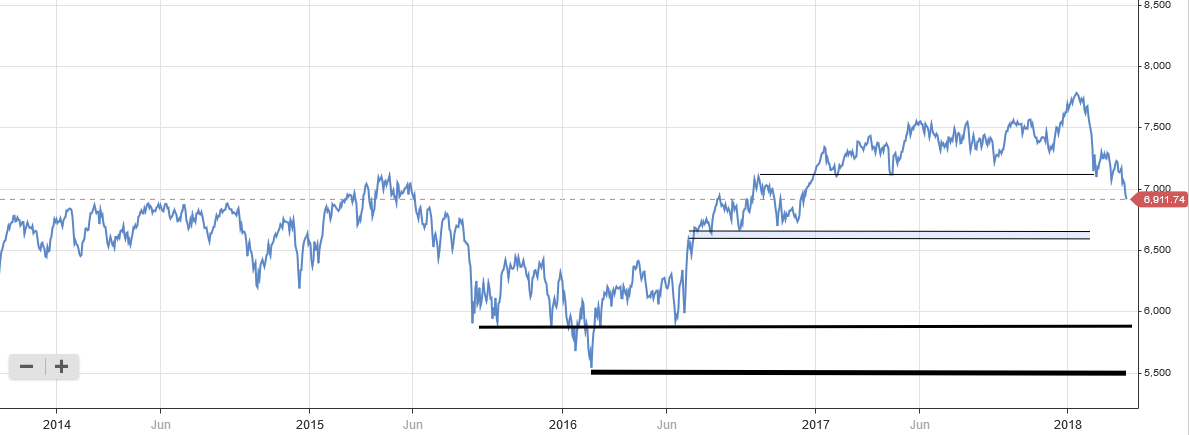
If we drift deeper into the 2016 range, we would be headed to 5900 and then the 5500 low:
These are the fundamental stats for the FTSE-100, according to Stocko:
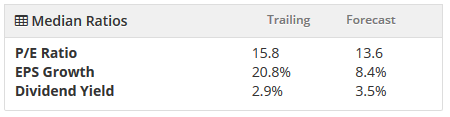
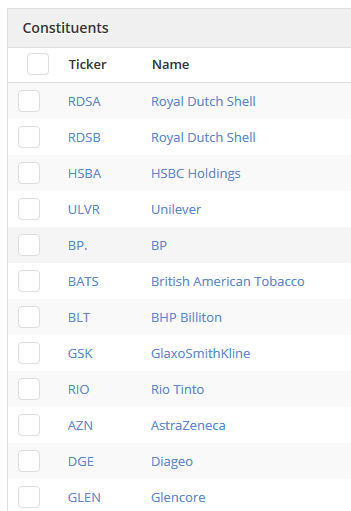
These metrics look fairly moderate, but some would argue that many of the index's heaviest components ought to be on lowly valuations:
Disclosure: I own British American Tobacco (LON:BATS).
A little bit of maths tells me that if the FTSE suddenly reached 5500, all else being equal, that the PE ratio would be 12.5 and the dividend yield would 3.7%.
If earnings and dividends were to take a hit, then of course these metrics wouldn't look quite so good. And everything would remain relative to interest rates, as they always do.
Even still, I think there would be some great value to be had in the market at the 5500 level, and I'd probably be adding a lot of equity exposure there.
For now, I'm just less than 80% invested and comfortable with that. Each person has to find a level appropriate to their risk tolerance, time horizon, liquidity constraints, tax situation, etc!
Robinson (LON:RBN)
- Share price: 81p (-11%)
- No. of shares: 16.6 million
- Market cap: £13 million
This is a family-owned packaging business, with manufacturing facilities in the UK and Poland.
I covered its results last year, when it correctly forecast revenue growth but did not signal that any profit growth would be forthcoming.
At 115p at that time, I thought the shares looked reasonably attractive. But profits have continued to slide, and with them the share price.
Some bullet points from today's results:
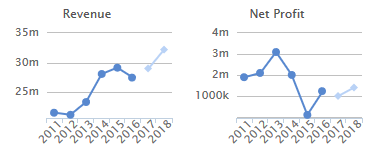
- Revenue up 9% to £29.8 million
- Gross margin falls to 19% from 23%
- Adjusted operating profit falls to £1.3 million from £2.1 million.
As these charts indicate, revenues haven't been doing too badly. But the operating margin has been weakening, and this year the gross margin has also reduced:
The RNS is very short for a final results statement, reflecting the small size of the company, the limited liquidity in the shares, and the general lack of hype surrounding it.
There are glimmers of hope among the commentary. 2017 is regarded as a "year of transition", with new business now replacing contracts which had been lost in 2016.
(As an aside: my personal portfolio is increasingly oriented toward B2C companies. Life is much less stressful as an investor when you don't have to worry about your company winning and losing lumpy contracts.)
On the expenses side of things, there has been a recruitment drive: this has meant higher costs in the short-term, but the purpose is to drive higher sales growth going forward.
My opinion
I don't feel familiar enough with the business at this point to judge whether it has the innovative capabilities to improve margins. An "adverse product mix" is mentioned as a partial explanation for the reduction this year. I wonder if there is a risk that the change in mix is permanent, rather than a temporary blip?
Other factors were beyond its control (e.g. weaker Sterling), so hopefully the margins will improve somewhat in 2018.
As others have noted, the balance sheet is strong, with net assets of £23 million.
There is a material amount of intangibles, however, and it's only right to deduct the intangibles from the balance sheet if the amortisation of intangibles is going to be added back to adjusted profits.
The tangible balance sheet value is £17 million, the same of the value of its PPE. Bank borrowings are used to fund the company's working capital.
On top of this number, we can add the value of surplus land, which I have heard is worth an additional £10 million (can anyone verify this?).
Unfortunately, the prospects for the sale of this land have significantly deteriorated. In August 2017, the company said:
The sale of surplus properties in Chesterfield is progressing and developments for the Walton Mill and Boythorpe Works sites are being discussed with prospective tenants and buyers. This process is likely to take several more months but we do expect some realisations in 2018.
In December, the company added that "progress continues to be made." But today, it says:
Finding suitable buyers for the Boythorpe Works residential site and Walton Works mixed use site has been challenging in the current market. Large retail developments are now in low demand and residential development opportunities in the locality are in good supply.
That must be a big disappointment for value investors who were expecting a property sale, and may explain the share price fall today. It also puts a question mark over how much this land must really be worth.
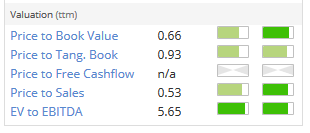
If the surplus land is indeed worth anything like an additional £10 million, then I can't avoid the conclusion that the shares are in value territory at the current level. But as is often the case with many value investments, the patience required to hold them for long enough to achieve the hidden value can be the biggest challenge.
Stockopedia agrees there is value to be had:
Cenkos Securities (LON:CNKS)
- Share price: 112p (-5%)
- No. of shares: 55.3 million
- Market cap: £62 million
This is an institutional stockbroker and corporate finance house. It acts as NOMAD (Nominated Advisor) to AIM companies.
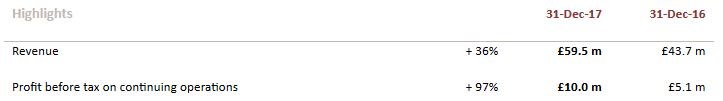
2014 and 2015 saw it earn bumper profits on the back of a couple of huge one-off deals (2014 revenues were £88.5 million).
2016 was quiet, as revenues almost halved compared to 2014 (£44 million).
2017 was somewhere in the middle:
I won't repeat my positive comments on how the business is run, as you'll find them in the archives here.
Quindell
Our old friend, Quindell, is mentioned.
In our 2016 Annual Report we reported that, following an investigation by the FCA into our role as sponsor to Quindell plc, we undertook an extensive remediation program. We have worked through 2017 to embed the recommendations and will continue to do so in 2018.
Curiosity got the better of me and I had another look at Rob Terry's latest venture. He is again trying to recruit investors with delusional commentary and talk of fairy-tale returns.
Astoundingly, he refers to prior involvement with The Innovation Group and Quindell as if it reflects well on him and his inner circle (both companies enriched him greatly, but were devastating for many shareholders).
Indeed, events at Quindell were still being investigated by the Serious Fraud Office as of January, according to the FT.
As far as Cenkos is concerned, I think most investors accept or at least are aware that AIM is a lightly regulated marketplace (some would argue that it is not regulated at all), and that it's up to investors to do our own due diligence on the companies and management we put our money in. I don't envisage any further repercussions for Cenkos over this.
Revenue Analysis
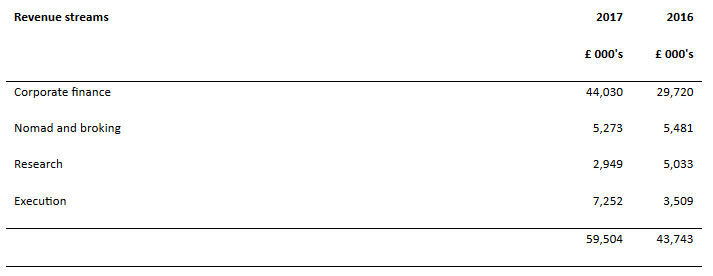
Corporate Finance - a really strong improvement this year. Equity finance raised for clients increased by 90% to £2.5 billion, and Cenkos' market share in terms of AIM fundraising increased to 21% from 13%.
Research - the research coverage has been reduced this year. The company acknowledges "there is some uncertainty following the roll out of MiFiDII".
Execution - a very strong performance boosted by exceptional gains on shares received in lieu of cash.
Outlook
Cenkos never enjoys much visibility:
We live in an uncertain geopolitical environment that makes it very difficult to predict either the direction of the markets or health of investor sentiment. There has been significant market volatility leading to a correction in all main global indices.
This market volatility does appear to have had an impact on investor sentiment with a pause in the momentum the Firm experienced in the second half of 2017. Despite this, we remain ranked as one of the leading brokers in London for growth companies, institutional investor appetite to fund high quality companies is likely to return and our business model is resilient. Consequently, we look forward to the future with cautious optimism.
My opinion
I still think this is a nice company, and I'm pleasantly surprised by the results this year.
It's also worth mentioning that it's a financial fortress, now showing net assets of £30 million, most of it liquid or near-cash.
It will probably never generate compound growth, and it's always going to produce lumpy and unpredictable results. But if the ethos remains the same, it will keep paying out lots of cash dividends whenever it can afford to do so (the yield is 5% trailing, or 8% on a forward basis) and treat shareholders well.
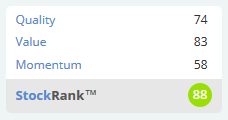
I agree with the StockRank:
Henry Boot (LON:BOOT)
- Share price: 304.5p (+0.5%)
- No. of shares: 133 million
- Market cap: £405 million
I started covering this land development company last year.
My only quibble with it has been on valuation grounds. I rarely pay much more than book value for property companies (e.g. my recent purchases of £INL).
That having been said, Boot is performing really well. NAV increased 15% in 2017, only using about £30 million of debt to achieve this.
And signs remain positive in 2018:
We have made a good start to the 2018 financial year, having already concluded a number of land sales. In addition, we have a strong pipeline of construction work, commercial development projects and strategic land sites working through the marketing process, on which to capitalise through the year.
NAV increased to 203p by year-end. The share price reflects a 50% premium to this.
I guess the market is thinking we could get another very large increase in NAV this year, given the increase in acreage and plots with planning permission. And with a number of deals having already been completed, the NAV is probably higher again now compared to the year-end value.
So I appreciate that the premium to NAV is now probably less than 50%, that the company is performing very well, and that it has an admirable focus on achieving 12-15% ROCE over the business cycle. If I was a shareholder, I probably wouldn't bother selling it out of my portfolio.
For someone like me who's interested in a potential entry price, I would want more of a margin of safety, i.e. the opportunity to buy it at or below NAV.
Sprue Aegis (LON:SPRP)
- Share price: 146p (-23%)
- No. of shares: 46 million
- Market cap: £67 million
DA Termination Notice and Update re final results
This is a home safety company, primarily known for supplying fire alarms.
Relations have broken down with one of its main partners, BRK, with whom it had a distribution agreement (DA)
Under the DA, Sprue paid a fee for the exclusive right to distribute BRK's products in Europe. BRK says that Sprue broke the terms of this agreement, and is ending the agreement immediately. It was due to end at the end of this month, anyway.
Strangely, BRK also happens to be the biggest shareholder in Sprue. They are related parties. BRK even has the right to appoint a member of the Board of Sprue!
As you might have guessed, it's a very complicated set of relationships.
US giant Newell Rubbermaid ($NWL) owns BRK, which owns 23% of Sprue.
Newell also owns DTL, which supplies BRK's smoke and carbon monoxide alarms, and supplied Sprue's own-branded fire alarms under a manufacturing agreement (MA). Newell has been the single largest supplier to Sprue, through a French subsidiary.
Are you confused yet?
My opinion
This problem relates to agreements which were already set to expire, so you could suppose that whatever costs it inflicts will be temporary.
What's bothering me about it is the fact that BRK is a big stakeholder in Sprue, even with Board representation, and yet it has decided to take this potentially damaging action against its investee.
We don't have much of an explanation of what has happened, so it's impossible to tell who is in the right. And potential damage has not been quantified at this early stage.
It's probably just a temporary problem, so the shares should recover in time, but I think the uncertainty and the questions raised by today's announcement easily justify the 23% hit to the share price. today.
Quixant (LON:QXT)
- Share price: 411.5p (up 8% yesterday)
- No. of shares: 66 million
- Market cap: £272 million
Circling back to cover this company, which I missed yesterday.
It creates the hardware platforms for pay-to-play gaming machines. In the words of the company itself, "you simply add the software". Separately to this, it manufactures monitors specifically for gaming.
It claims to be "the highest volume manufacturer of computer platforms for gaming", with 10% market share.
HQ is in Cambridge and manufacturing takes place in Taiwan. There are further offices in Las Vegas, Italy and Tokyo.
Besides posting excellent 2017 results yesterday, it announced that the outlook for 2018 was "ahead of our previous expectations" after a robust start to the year.
It's nice to see that one of the main co-founders is still heavily involved. He owns 18% of the shares and has only recently moved from CEO to Exec Vice-Chairman with responsibility for "technology leadership and product innovation".
His replacement as CEO was hired internally and was also involved with the inception of the company as a design engineer. This also looks positive.
The statement from the new CEO is written in a very clear style, and I haven't come across any standard red flags or other reasons for concern yet.
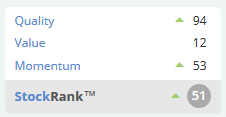
So I agree with Stockopedia that this is probably very high-quality company:
That was a busy day!
There was strong input yesterday about the role of comments in this report.
My own plan is to choose some stocks myself each day (the ones I'm most interested in), and take requests for a few others. Your requests have been a rich source of investment ideas for me, and I welcome them.
Paul has his own views on this. I'll wait for him to come back instead of putting words in his mouth.
Anyway, that's it for this week. Have a fun weekend and I'll see you next time.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Re Sprue Aegis (LON:SPRP), i wonder if this could be a bizarre attempt to drive down the valuation, and then bid - remember BRK's parent tried and failed in a bid that became hostile a while back. Highly opportunistic at the time, the acceptances came to virtually nothing, but it did galvanise the company, which moved from OFEX to AIM, prompting a major revaluation of the company and it's prospects. I believe the 29% stake is still held by BRK's parent.
If they have largely fallen out, then there is an issue of a potentially large overhand. It's all a bit baffling - and Graham rightly asks why a 29% shareholder would behave so aggressively when doing so is potentially loose/loose?
Hi Graham
Re: Discussion on comments to the column.
I'm the guilty party who started yesterday's discussion on this topic in the comments.
Thanks for giving this thought. Hopefully taking "requests for a few others" will work. Either way I enjoy the main articles and really appreciate all your hard work, and as far as I'm concerned, having voiced my input, what you say goes!
Many thanks.
Re Cenkos Securities (LON:CNKS) How is it they were not barred from being an AIM Nominated Advisor ('NOMAD') after sponsoring Quindell? How is it that Rob Terry and his friends (known fraudsters) can still, after all this time, be doing what they do a third time around, with Quob Park Estate? Why does the City of London and the London Stock Exchange etc not care about serious fraud (serious crime), its victims (the victims of con-artists), or even the City's own reputation? Rhetorical questions really, but it's truly shocking for those of us that came to investment from professions with high standards of integrity to witness how utterly devoid of ethics the City really is; how very highly paid financial professionals care only for themselves, are happy to get rich very probably understanding they are sponsoring fraudsters (and if not, through gross negligence) and then facing no serious sanction. And why do the fraudsters, after all this time, still have the proceeds of their crimes? And their liberty?
Not sure I agree on Cenkos Securities (LON:CNKS). They made a serious of terrible mistakes with regard to Quindell if I recall correctly. Also I believe they floated the AA (LON:AA.) I think I read some Cenkos note that was very bullish on AA (LON:AA.) It is surprising to me that this poor track record hasn't hit them. It does look cheap but the companies it lists appear to be poor. Comptoir (LON:COM) is another one that is ending badly.
Hi Graham
I am trying to improve my investment performance, which until these last couple of months has been pretty decent but has taken a bit of a kicking lately; probably like many. I find Stockopedia excellent, constantly finding other avenues of information hidden away to further my research. Ideally I am looking for stocks with high rankings but also "Super Stocks". Is there any way I can save time and find all the Super Stocks grouped together without dipping into many shares to see whether or not they qualify?. I would use this as an additional tool for my research and wouldn't rely on it totally.
Many thanks for your hard work and Pauls'.
Regards
CM
Go here:
https://www.stockopedia.com/st...
Then click on "Style" and then click on "Super stocks" and there are all the super stocks in one place.
Many thanks Nick. I thought there must be a way. Much appreciated.
Regards
CM
Hi Graham,
Big thanks for all the various analysis you do for us.
On the macro views - I tend to agree - and waiting for a real panic driven crash before putting new money to work.
I specifically wanted to express my gratitude for the report from 16th March - personally I think the PRA ought to make your analysis on CEDEX mandatory reading!
I got a cold call from what I would describe as a boiler room - telling me about low volatility crypto strategies (4% max drawdown with 3% per month returns) - I directed him to your report from 16th March and the insights to explain why I am avoiding the asset class.
Many thanks Graham.
V
Ps for those interested the company that called me was CryptoBit - maybe they are totally legit and I am unnecessarily cynical.
Hi sharmvr, you're welcome! I appreciate your comments here.
Yes, the crypto-space is full of sharks and con artists at the moment. I don't blame everyone involved and I know that there are plenty of very smart and honest people working in it, but economically speaking it is primarily a wealth transfer mechanism from those with a little bit less sophistication to those with a little bit more.
In other words, it's an extreme version of the financial system as a whole, and with negligible underlying value creation.
Just my €0.02.
All the best
G
Hi Graham. Thanks for your write-up on Cenkos. One small query: in respect of dividends, how do you get "the yield is currently about 5%"? Full year dividend for FY17 will be 9.0p (interim 4.50p; final 4.50p) which by my calculations is 8.0% based on the current 112p offer price?
Hi browner, thanks for pulling me up on the Cenkos Securities (LON:CNKS) dividends. I simply used the figure on the StockReport, which I think in this case is the trailing twelve month yield (ttm). I'll see if I can update the article to put your numbers in. Cheers
What a brilliant piece of research on the markets via trade war. I do wish certain CEO’s would speak and write as clearly.Thank you Graham.
hi, any views on Utilitywise Utilitywise (LON:UTW), other than sell... I've held these right past my stop and regretted it of course however I have just read all the material released and the plus points are:
* New CEO & chairman uncovered the mess and have worked to fix it.
* the revised accounting policy changes affect the timing of revenue recognition rather than the absolute value of the energy procurement contracts that the Group places,
* has had no impact on the cash flows of the Group
* banks have been very supportive throughout
*they seem to have headroom on committed lending so safe in respect of working capital etc.
So is this a major bump in the road and fundamentally an investable business?
One big negative is this:
DIRECTORS’ SHAREHOLDINGS
Geoffrey Thompson (direct and family trust) – 8,559,414 (10.91%)
Brendan Flattery – 60,000 (0.08%)
Richard Laker – 0
Brin Sheridan – 0
Simon Waugh – 0
Kathie Child-Villiers – 0
Richard Feigen – 10,000 (0.01%)
Paul Hailes – 35,001 (0.04%)
Jeremy Middleton (direct, company, pension) – 3,287,559 (4.19%)
So ignoring Thompson, who set the company up, and lost his way it would seem, unbelievably bad shareholdings by directors. So for me, if heavy buying in the next couple of weeks, a big positive, as, if you were an insider and the business looks good, what a bargain. I'd be pleased to hear from anyone else who has looked through the accounts and has a different perspective.
Graham, this may be of passing interest to you and the collective...
https://www.bloomberg.com/news/articles/2018-03-21/jim-rogers-says-trade-war-is-making-his-bearish-view-even-darker
Looking forward to reading Graham’s Cenkos update.
Results were excellent. What was surprising was the half pence cut in the final dividend. Directors gain from the dividends on their large share holdings, and Cenkos usually pay out a large chunk of profits in dividends. I had expected excellent results (got those);AND a big increase in final dividend. So a bit surprised at the cut as dividend payments have always been lumpy and current results and 55% increase in cash would suggest they could easily have afforded an increase.
Outlook statement and dividend disappointment and other negative vibes including negative Brexit comment have hit the share price. They could have included a warning about future dividends along with their other warnings.
This suggests they really are very gloomy about prospects, or is this a rather devious way of attracting a bid?
@kenmitchell - Agree with much of what you say re #CNKS. On the dividend cut, the full year has of course increased by 50% from 6.0p to 9.0p, even if the 4.50p final dividend is slightly less than the 5.00p paid lasy year. Like yourself I have been mullng over possible reasons for the full year dividend not meeting the 11.0p consensus forecast. The company will of course been aware of this when setting the final payment. I wonder if it might signal the relatively new CEO taking a slightly more conservative approach to dividend payments than his predecessor? Or are they retaining some cash with an M&A target in mind? Or are they merely anticipating tougher times ahead? It would seem that Q1 2018 figures in terms of funds raised for clients will struggle to match those achieved in Q1 2017.
As an aside, I note they also closed their Singapore office in Nov 2017 & have reduced their headcount in Edinburgh.
I would love an opinion on Sprue Aegis (LON:SPRP) please,
I've just been reading into today's RNS and past RNS with regard to Newell Brands and the associated distribution agreement with BRK, from what I understand from today's news I'm seeing it as Newell having a final spat at the closure of the distribution agreement with Sprue which they gave notice of last year, they seem to be throwing their toys out of their pram by stating that Sprue are "in breach of certain provisions" and will not be purchasing unsold stock. The distribution agreement was due to end at the end of March 2018 with Sprue having given 1 years termination notice last year, from what I can make out Sprue seem to be buying a cheaper alternative from the Far East (improving margins) but the association is a little unclear to me.
From the half yearly:
"Stock
Following receipt of 12 months' notice from Newell to terminate the 2010 BRK distribution agreement as announced on 31 March 2017, any remaining stock of BRK products held by Sprue as at 31 March 2018 will be repurchased by BRK at the price Sprue paid for the goods. It is expected that this will result in a cash payment to Sprue of at least £3.0m assuming that in the meantime Sprue has not sold the remaining BRK stock. As at 30 June 2017, the gross book value of BRK stock held by Sprue amounted to £4.8m (as at 30 June 2016: £7.7m)"
Also in the half yearly they mentioned that debtors have "significantly increased", I'm now wondering if this is related to the BRK issue and Sprue could have a potential large bad debt on their hands.
Sprue will be saving an annual distribution fee of £2.9m with the closure but what will they be losing as a one off if they have to write off a BRK bad debt, and will this be disclosed in the (delayed) accounts due "late March" ?
I dont have any Sprue shares but I am always eyeing up a potential long term opportunity, I'm hoping Paul/Graham might be able to defog this, and propose what's really going on here
Re Sprue Aegis (LON:SPRP) alleged breach of BRK distribution by Sprue Aegis (LON:SPRP) note that Sprue Aegis (LON:SPRP) have not denied the breach (though perhaps they are still investigating). Also, to clarify, they say the results, that were due in late March will not now be released in late March - there will be a further announcement on that in due course. If there is merit to BRK's claim then I think Sprue Aegis (LON:SPRP) would start to look very careless, which would be unfortunate for me because....
(I hold.)
I am also long Sprue Aegis (LON:SPRP) and found the statement a bit bizarre. It strikes me that BRK are being opportunistic....ie they don't want to buy back the stock and believe it is cheaper to simply claim breach of agreement timed conveniently a week before the agreement finishes anyway, leave Sprue with the stock and walk away. Is this material - well we don't know!
Does strike me (ironically for a safety company) that they are accident prone, which is irritating me since I bought them for the opposite reason. I suspect the fall is well overdone given the horrid market conditions but an unquantified write down (which is presumably where the accounts delay comes in) is unhelpful.
Aside from being a management distraction and a one off hit to the cash pile I can't see that it has any real trading impact since they will have prepared for the termination in 7 days anyway and will now be in transition to the new arrangements.
What was noticeable in the announcement was that whilst strong language was used (ie breach not remediable etc.) there didn't appear to be a legal threat, though one can't rule that out. It sounded more like they were walking away and setting out their defence should Sprue try to take action. I would expect Sprue Aegis (LON:SPRP) to have insurance against lawsuits anyway.
hmmm.....a bit more colour would be useful
Re Sprue Aegis (LON:SPRP) quite possibly that's the scenario David, yes. I certainly hope so, though the lack of an immediate denial from Sprue Aegis (LON:SPRP) struck me as unusual as well as disappointing. Yes, if BRK's claim is without merit, the plaintiff will be Sprue Aegis (LON:SPRP) of course.
yes, of course the key problem is we don't have enough damn information from the company!!!
I wouldn't necessarily expect them to refute until they've taken legal advice, and of course if they are playing by the market disclosure rules properly they have to report immediately the issue becomes known and not when it is quantified/understood, so let's see what they say next week.
Re: Sprue Aegis. Comment from threeputt and others.
I used to be a holder of Sprue Aegis shares but sold them over a year ago because it seems to me that the company is not in control of its own destiny and is vulnerable to unfavourable decisions taken by its Chinese supplier.
@threeputt. Small point of order. It was Newell that initiated the termination of the BRK distribution agreement, not Sprue, even if it will have most likely been welcomed by Sprue who seemed to have agreements with alternative suppliers ready to go upon the intial announcement.
Crawshaw - a prime example of what happens when big corporate execs are parachuted into a much smaller company.
Lack the skill set needed to operate without huge teams supporting them and drain the coffers dry with their over inflated packages. Quite what the chairman is thanking them for isn't exactly clear, you can be sure the wiped out shareholders aren't.
Thanks for the Quixant (LON:QXT) suggestions, guys. Noted.
I will second the Quixant (LON:QXT) request, please Graham, if you have time.
I'll have one more go at asking for a comment on Quixant (LON:QXT) please Graham - they seem to be growing at a good pace, gaming in general seems to be only growing, and interestingly the price isn't down today despite the bloodbath elsewhere.
I notice also that the Investors Chronicle has tipped Quixant (LON:QXT) as a buy after the results... though this could be as much a curse of death as me acquiring a holding :-)
I look forward to Graham's views on Robinson (LON:RBN) which has reported today. On a quick scan, they seem to have NTAV almost twice the market cap, a maintained 6% dividend, reduced profits and margin, a need to invest in new plant and a difficult outlook. The pension deficit has been eliminated. I hold, The market has marked them down 12% this morning.
Hi Graham,
I would really appreciate your take on Produce Investments (LON:PIL) 's interims from yesterday if you have time to add this to your list for today. A positive six months tempered by an outlook where weather conditions may impact full year and the use of the dreaded word "broadly" in the context that the "the Board currently expects underlying trading profit for the full year to be broadly in line with its expectations".
Some interesting comments yesterday on PIL's business model from readers which were also insightful.
James
By no means a small cap, but often discussed here as a bellweather for the state of the UK retail sector (and also a paradigm of quality reporting) Next (LON:NXT) released their Final Results this morning.
https://www.investegate.co.uk/next-plc--nxt-/rns/results-for-the-year-ending-january-2018/201803230700056906I/
One word summary? - “Challenging”.
Gus.
An interesting snippet from the Next (LON:NXT) report:
“Looking at last year's numbers it appears that every Pound of full price sales lost in Retail cost us 60p whilst every Pound gained Online delivered only 19p of profit. ” Mainly because the retail cost base is fixed and online flexes.
On a more positive note their pension scheme surplus increased to £106m.
Re Next (LON:NXT) that's worrying, isn't it? Doesn't bode well for the future given that online growth rates will tail off over time. Thanks for highlighting it.
(I have a few shares.)
My morning smallcap tweet:
Crawshaw (LON:CRAW), Sprue Aegis (LON:SPRP), UK Oil & Gas Investments (LON:UKOG), Pipehawk (LON:PIP), Grafenia (LON:GRA)
Crawshaw (CRAW) Choose one resignation and get another one for free! CEO & CFO resign. CFO leaves in May, CEO will stay until they find another. Board thanks them even though CEO has destabilised the business. Recent trading challenging.
Sprue Aegis (SPRP) Customer terrminates contract already due to end in 9 days, alleges breach of agreement. Termination may result in unsold stock issues. Accounts delayed.
UK Oil & Gas (UKOG) meets planning conditions to re-test Horse Hill 1 and drill a new well, Horse Hill 2. "If You Can't Ride Two Horses At Once You Should Get Out Of The Circus." And what a circus it is!
Pipehawk (PIP) H1 "I am pleased to report that the Company’s turnover in the six months ended 31 December 2017 was £2,310,000 (2016: £2,999,000)." That 23% down. I must try that at home. "I'm pleased to report that I lost £300 down the bookies." Yes, that'll work. However in H2 "orders have flowed in and we are now extremely busy."
Grafenia (GRA) warns pre-tax loss no better YoY despite rev up 40%. "Wholesale prices for print have continued to decrease, despite increasing costs of raw materials. Volume and margins in our trade divisions were below budget in December and January and are sharply down in February. Whilst there is oversupply and discounting in the market it is difficult to see this trend changing." Investment to move away from printing "may impact our short-term earnings." May = will here.
Morning Graham,
There's a couple I would probably under "normal" market conditions be interested in taking out an initial position in today (great EPS increases) and would appreciate your comment on them should you have an interest and time.
Henry Boot (LON:BOOT)
Results For The 12 Months To End December 2017 – Looks good indeed - Revenue up 33% to £408.5m (2016: £306.8m), PBT up 40% to £55.4m (2016: £39.5m) and EPS up 49% to 32.1p (2016: 21.5p). The FY Dividend will be 8.00p (2016: 7.00p), a 14% increase. NAV is up 15% to 203p (2016: 177p). 2018 has started well.
Cenkos Securities (LON:CNKS)
Results For The 12 Months To End December 2017 – Revenues up 36% to £59.5m and PBT up 97% to £10.0m (2016: £5.1m) with Basic EPS from continuing operations up by 154% to 15.0p (2016: 5.9p). Outlook is (correctly) called as “difficult to predict”.
I would like to thank Matylda and MrContrarian for their excellent and frequently very funny in the case of MrC, contributions to this board.
Hi matylda, thanks for your suggestions (and all your output on this site!). Always look forward to reading your comments.
I've done Cenkos Securities (LON:CNKS) and am on Henry Boot (LON:BOOT) now.
Cheers
Graham,
Thanks for the kind words and of course the analysis - Which I am quite sure I look forward to reading more so than you do mine :)
Have a great one.