Small Cap Value Report (Fri 24 May 2024) - IGP, NEXS, SCE, BMS, ENSI, AVAP

Good morning from Paul!
That's it for the day, and the week. Have a lovely long weekend!
Breaking news! No not another takeover bid, this is just to flag that my weekly roundup podcast has gone up early, as I'll be busy returning to the UK tomorrow. (EDIT: multiple background sound effects, I realise on listening back. Typical Gozo - there's a bird's nest just above my head, building site next door, under the flightpath for Luqa Airport, and swimming pool constantly refreshing. Maybe some cannons or guns going off too, that's usual?)
I hear that Mello was very enjoyable, and sorry I couldn't make it this time (I extended my trip to Gozo due to a lingering chest infection, which is now almost sorted).
Troll
I see we had a trolling outbreak again yesterday. Just when you think it's all sorted, another one pops up! Ignore them, is my advice, because they feed on and enjoy the disruption they cause. I look forward to the developers adding an "ignore user" facility, which I think we need. I've added an extra bit to the explanatory notes below, to emphasise that with the resources available (me, and 3 hours of Graham 4 days pw), we obviously can't cover everything! Although we're getting close to having reviewed c.500 unique companies so far in 2024, so there's no hope if you can't find anything of interest amongst that lot! We're not machines, we're human, so we have the occasional off day, offset by plenty of out-performing days. If people moan at me, then it stops being fun, and if that happens I'll hang up my keyboard and do something else with my time, to be blunt.
Market thoughts
Dismissing UK small-mid caps is now going out of fashion, I'm pleased to see.
NVIDIA (NSQ:NVDA) has 5-bagged in the last 3 years, which is truly remarkable, what an extraordinary company and share. But so has Warpaint London (LON:W7L), also 5-bagging (well, almost) over the same period (which we flagged early on here in the SCVRs, and all the way up with GREENs). So we've got plenty of opportunities over here, and much less competition for the shares, as people have drifted away from the UK market., on shares that are quick & easy to analyse. I can almost hear all that cash starting to flow back into UK small caps!
EDIT: I did play around with the starting point on the chart below, to show the most favourable outcome that supports my case here, just to prove you can show almost anything with statistics by selecting a supportive starting date, lol! -
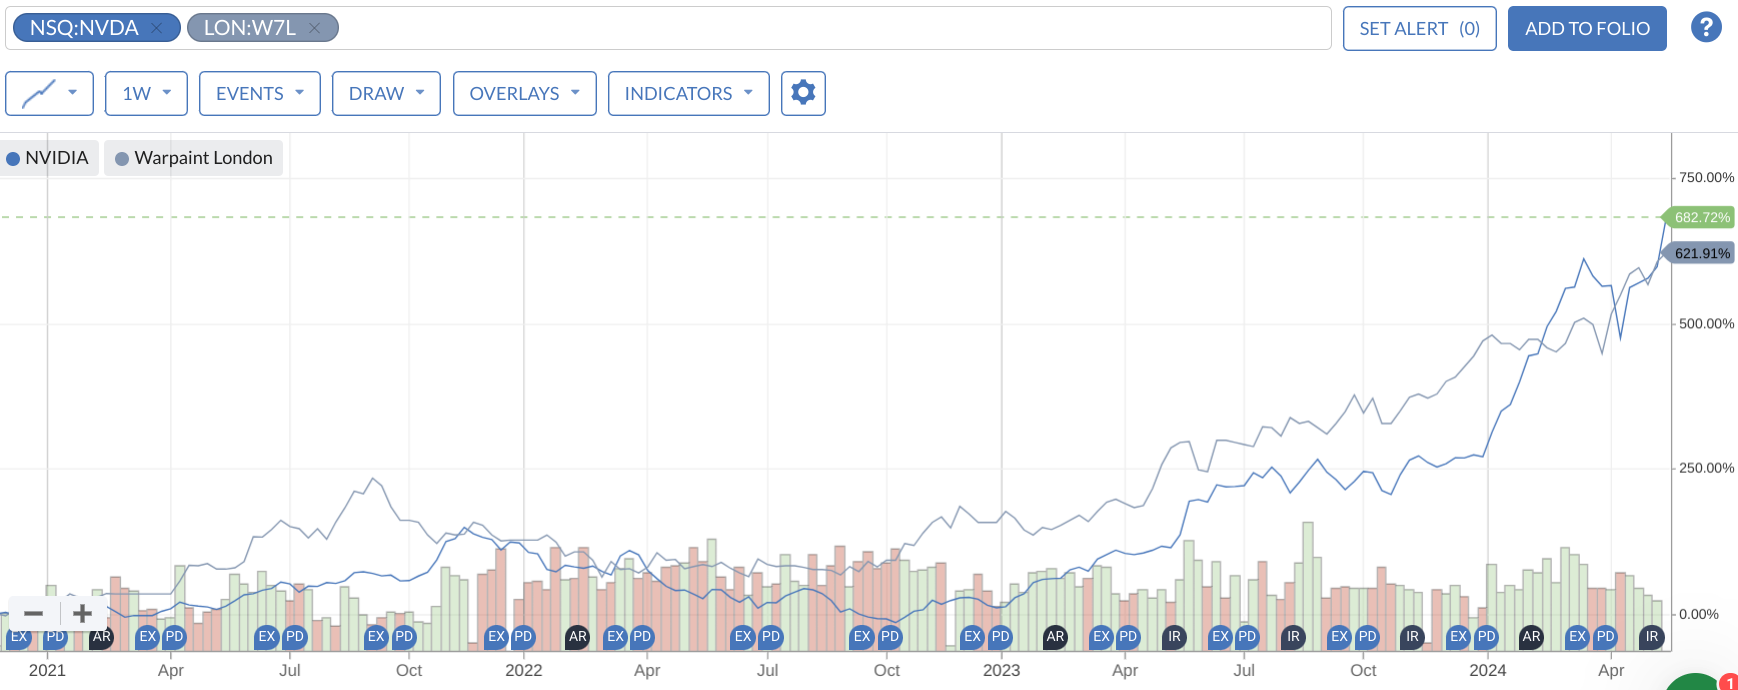
Although the almost vertical moves on lots of shares recently is starting to look a bit frenzied - is it time to take some profits on things that have bounced excessively? I'd say so, yes. Then we have the pot of cash to redeploy on new ideas. As my mentor says, "If you're going to sell, make sure you're the first to sell" - ie don't wait for the price to go into freefall because others got there first. Good advice that I keep front of mind.
Or, if you're a long-term holder, then the short term price gyrations don't matter, especially if there's a nice income from divis flowing in. Everyone has their own way of doing things, and "Do more of what works best for you" is what my mentor told me, and I pass that on to investors I talk to.
I find at the start of a new bull market, there's a lot of money to be made by being quite nimble, and rotating big winners into similarly good companies whose shares have not yet moved upwards (maybe due to a lingering institutional seller that's nearly finished). They tend to join the party soon afterwards, giving a double benefit. I saw that in both 2003 and 2009, both very good years for me. People start to take on more (perceived) risk in early bull markets too, so it's important to be flexible I think, and consider taking positions in companies with perhaps more debt than I would like, but no signs of actual distress. Those shares are often the biggest % gainers.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech). Although if something is newsworthy and interesting, we'll comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
List of Companies Reporting Today
Very quiet today, so I'll have a look back to see if we missed anything noteworthy Mon-Thu this week.
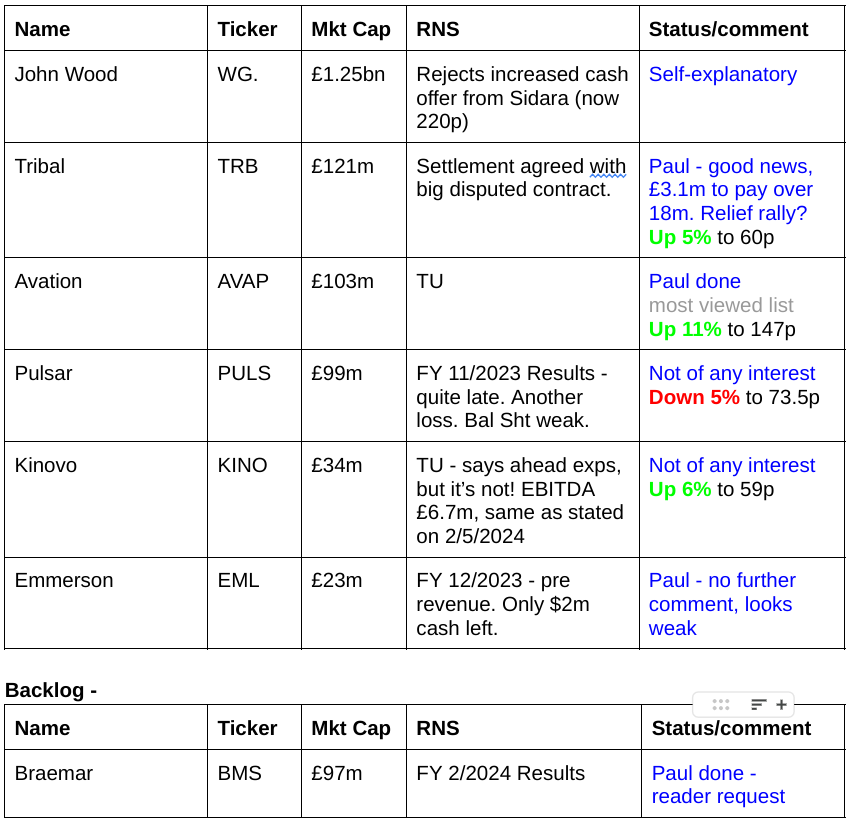
Other mid-morning movers (with news)
Surface Transforms (LON:SCE) - up 6% to 1.32p (£17m) - Open Offer Result - Paul - AMBER/RED (speculative punt possibility?)
Good news today of the open offer being over-subscribed for new 1.0p shares. So they’ve upped it from 200m to 300m. By my calculations that will now increase the share count to 1,302m (allowing for the latest placing, plus the enlarged open offer). That gives my manually recalculated £17m market cap above. When there’s huge dilution, you have to be careful not to chase up the share price too high, by referencing previous share prices when much fewer shares were in issue. So for example with SCE a share price of only 3.0p would be a £40m market cap.
Management today confirm an order book of a huge £390m (although that’s spread over multi-years), and a pipeline of another £400m. That’s great, if they can actually figure out how to manufacture the brake discs in scale.
They also confirm that they’re confident they now have enough funding. I’m fairly sure they said that in the previous 18 fundraises too.
Paul’s view - my policy of steering clear of anything that obviously needs to raise fresh equity has dodged lots of speculative bullets, as 1p seems to now be the default price for last chance saloon placings & open offers. Once a fundraise is done, then that’s the time to have a speculative punt on it, in my view, but only with money we can afford to lose, and keeping a close eye on the exit. With this latest fundraise now in the bag, immediate financial risk has receded, so I’ll shift up from red to AMBER/RED. I imagine flippers from the 1.0p open offer are likely to keep a lid on the share price, as banking a say 40-50% gain will be tempting to the many private investors who will have taken part in the open offer. Good luck to holders, I hope this time it finally works! Tempted to have a little flutter myself actually, as mentioned last time!
EnSilica (LON:ENSI) - down 17% to 45.5p (£39m) - Equity Fundraise - Paul - AMBER
Announced after hours last night a placing. Today confirms it has raised £4.9m of new equity at 45p (a hefty 18% discount to last night’s closing price of 55p). Trivial amounts subscribed for by the Board, who also have trivial existing holdings, apart from the CEO who is not buying any shares in the placing, instead accepting dilution from 18.9% to 17.2%.
There’s also a tiny retail £0.3m offer through a platform I’ve not heard of before called WRAP. Googling it, this seems to be something set up by leading market maker Winterflood, called Winterflood Retail Access Platform, so I’d be interested to hear more about this. We’ve already got a couple of others, including REX (from Peel Hunt, I think?) and what’s that other one that’s been going a while (will edit this when I remember the name, it's two words). EDIT: Primary Bid, thanks to AstonGirl!
I flagged here 3 times (14/12/2023, 26/2/2024, and 28/2/2024) that ENSI would need to raise more equity. Hence why it’s so important to not be the cannon fodder that chase up the share price on the rampy news, but then get slammed with dilution when they use the good news to raise more funds, as has predictably happened here.
Now that it’s better funded, I can safely go up from amber/red to AMBER, as risk has now reduced, and the price is cheaper (but more shares in issue of course). There were some interesting elements in previous RNSs, so this might be something speculative to have a look at, for the more adventurous amongst us. It’s a chip designer of some kind. Let’s hope it doesn’t end up crashing like the disastrous Sondrel (shortly to de-list after being bailed out by a private equity firm).
I think our process here of steering clear, and flagging the risk of dilution/insolvency/de-listing at many under-funded micro caps is working very well - we’re getting nearly all of them right, and I hope that’s saved readers a bob or two in avoided losses.
Summaries of Main Sections
Braemar (LON:BMS) - 295p (£97m) - FY 2/2024 Results - Paul - AMBER/GREEN
Readers subject me to an hour's torture trying to unpick the FY 2/2024 results from this shipping broker. Problems are unchanged - excessive share option dilution, inadequate explanation of historical transactions that caused shares to be suspended for months last year, little balance sheet support, also some funnies in the accounts, and numerous EPS options to choose from! All that said, the valuation now looks so attractive, I'm pulled magnetically towards AMBER/GREEN, despite my unease over the various issues.
Avation (LON:AVAP) - up 11% to 146p (£103m) - Trading Update - Paul - AMBER/GREEN
Ahead of expectations trading update today, and interesting value in the aircraft order book. Thanks to readers who have been flagging up this interesting special situation previously. I do a brief review below, and conclude that the discount to NAV looks worthy of a closer look.
Paul's Section:
A couple of quick comments on company webinars -
Intercede (LON:IGP) (I hold)
This niche software company, which specialises in online identity management (eg 2-factor logins), held a Capital Markets Day yesterday, which was also broadcast live on InvestorMeetCompany (the recording is now available here). So if you find yourself with several hours to kill over the weekend, this is worth checking out. I learned more about the company, and particularly enjoyed hearing talks from IT specialists, and a glowing report from one of IGP's main systems integrator partner. A cybersecurity (friendly hacker) explained how easy it is for hackers to break into IT systems, even for major corporations. I made that rookie error of buying more shares during the webinar, which I know shouldn't be done - having a cooling off period after presentations is my personal most frequently ignored golden rule!
Nexus Infrastructure (LON:NEXS)
I've previously mentioned how my two questions on this webinar were not answered. To be fair, they have now been answered. I've never looked at the Q&A tab on InvestorMeetsCompany presentations, but this is where they subsequently give written replies to questions that were not answered live for whatever reason. Here it is - if you click on the Q&A tab at the top of this page. I had queried why receivables are so high. The reply says that this is partly due to retentions on contracts, which can take c.2 years to be received. This has rather put me off this share, since as revenues expand again, then it seems likely that more cash will get sucked into receivables. It's only getting a c.13% gross margin, and then has to wait 2 years for the profit element to be paid, which seems the worst business model I can think of - very low margin, and very slow payments from customers. So I decided to let my shares go, which had only been a small starter sized position. My second question was about de-listing risk, where they replied something like there are no plans to delist, but I can't find that in the Q&A section.
Reader request -
Braemar (LON:BMS)
295p (£97m) - FY 2/2024 Results - Paul - AMBER/GREEN
A reader request that got over 20 thumbs ups, so I’ll take a look.
Braemar Plc (LSE: BMS), a leading provider of expert investment, chartering and risk management advice to the shipping and energy markets, announces its audited results for the year ended 29 February 2024 ("FY24"), which are in line with market expectations[1].
[1] Company compiled consensus as at the date of this announcement: FY24 revenue of £150.4m and FY24 underlying operating profit (before acquisition-related expenditure) of £18m.
Webinar forthcoming - 11am, 30 May, on IMC.
Checking my previous notes confirms a nice summary from TortoiseInvestor here, that there were significant problems previously at BMS in several ways - excessive share options (I also flagged this here on 22/3/2023), and BMS shares seem to have been suspended from June-Nov 2023 due to investigation into $3m of historical transactions - which seemed bizarre at the time, given $3m is not anywhere near enough to jeopardise the company’s solvency.
On to the FY 2/2024 results, which it says were in line with market expectations, but the adj EPS is 21% down on FY 2/2023. Also note the large different between statutory and underlying results, and that it shows basic, not diluted EPS below -
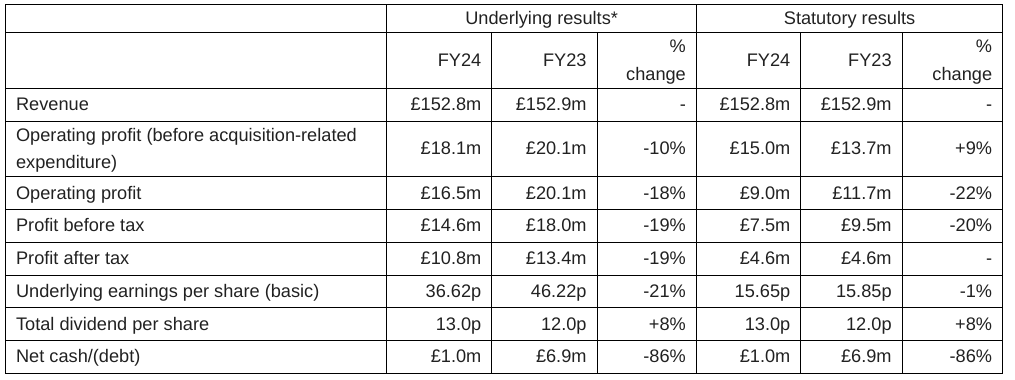
Further down we find out that underlying basic EPS of 36.62p becomes 29.96p adj diluted EPS (and 12.8p statutory diluted).
Adjustments - are they reasonable? They’re in note 2.2, with the main ones being £2.6m investigations costs of the $3m historical transactions, not expected to recur. So it cost more to investigate them, than the actual transactions, how does that make sense? It says these are not going to recur, so I can see why it is fair to adjust out as a one-off, but I would still like to better understand what actually happened.
The other main adjustment is the dreaded “consideration treated as employment costs”, which I struggle to understand wherever it crops up (eg at Begbies Traynor (LON:BEG) and S4 Capital (LON:SFOR) ) - it’s something to do with acquisitions, where accounting standards require deferred consideration to be classed as employment costs. The CFO at BEG tried to explain it to me on a Zoom, but I still didn’t properly understand it. Not many accounting concepts defeat me, but this one has I’m afraid! So I take the view you either just accept the adjustments, or you don’t. Sorry that’s not much help!
Dividend yield is 4.4%, and the payout of 13.0p is up 8%.
Outlook comments sound reassuring, especially the big increase in order book, although I wish companies would specifically confirm (and quantify in a footnote) market expectations instead of less precise (some might say) waffle -
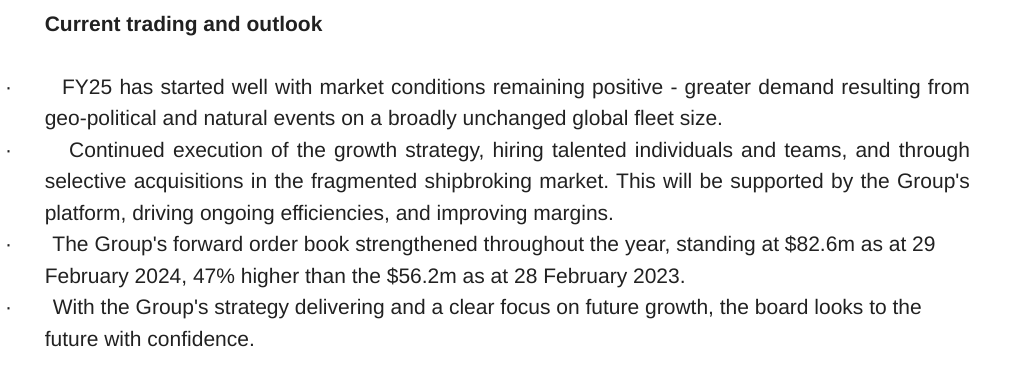
(sorry I can’t highlight anything on this travel chromebook)
Balance sheet - a few items in there to note, but nothing particularly big (e.g. pension surplus £1.4m, convertible loan notes £3.0m [what are the terms?], long-term receivables explained in note 4.1 of £4.6m). Cash of £28m roughly offset by long-term borrowings of £27m (I’ve knocked off £3m in lease liabilities), see note 4.6.
NAV is £80m, but intangible assets are the bulk of this, at £74m, giving NTAV of c.£6m - so effectively there is hardly any asset-backing to this share underpinning it, which may not matter providing earnings and divis keep coming out.
Forecasts - thanks to Cavendish for an update today. Muddying the waters further, it reports FY 2/2024 adj diluted EPS at 34.1p, when I was just getting comfortable with the company’s 30p above!
It assumes a rise to 38.1p in FY 2/2025, so a PER on that basis of only 7.7x - that looks appealing cheap, and might be enough to help me shed some of my general sense of unease about this company and its accounts.
Paul’s opinion - the key issues remain the same - excessive share options (although taken into account in diluted EPS), the long & seemingly unexplained suspension of the shares last year. Also note 4.2 shows unusual receivables collection, so I hope on the webinar people ask management why some customers don’t seem keen to pay on time, or at all?
Overall, I can see why some investors will be attracted to the low PER here, and a pretty reasonable dividend yield. With the company also talking about favourable market conditions too (how much due to geopolitical crises?), the low valuation metrics definitely appeal.
I didn’t really want to go above amber, and am uneasy about giving a view here, but I think the valuation numbers are pulling me towards AMBER/GREEN, but with some reservations as noted above.
Avation (LON:AVAP)
Up 11% to 146p (£103m) - Trading Update - Paul - AMBER/GREEN
There have been some terrific reader comments lately on this aircraft leasing company, from davidjhill and others (sorry I haven’t name-checked everyone). So thought I’d give it a fresh look. We covered Avation a lot years ago, especially in 2015 & 2016 when affable Aussie, former CFO Richard Wolanski used to turn up for pretty much every private investor event that was held!
The pandemic obviously caused chaos in the airline industry. Graham did a quick review most recently here on 15/9/2022, concluding that the “value could be substantial” at Avation, and that it deserved a closer look.
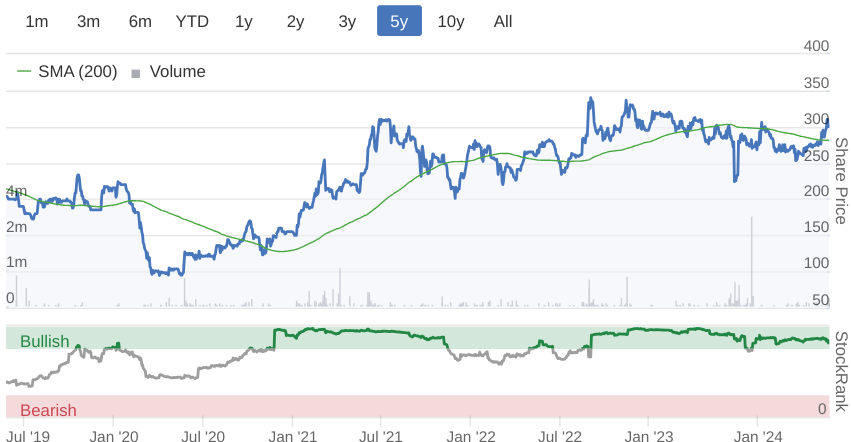
I particularly like the point that readers here flagged up, that AVAP’s order book now contains hidden value apparently, due to the market value of aircraft it has on order being higher than its contracted cost. So this looks a special situation worth investigating further, if we haven’t missed the boat already, given the big recent upwards share price move? Although zooming out to 5-year view below, shows a move that’s within the normal range, and also bear in mind it got through the pandemic with only about 10% expansion of the share count, hence maybe pre-pandemic share price of c.300p might not be a pipe dream?
Latest news starts off very nicely -
Avation PLC (LSE: AVAP), the commercial passenger aircraft leasing company, provides the following trading update as of 24 May 2024:
The Company expects to report a profit for the year ending 30 June 2024, which is significantly ahead of current market expectations.
Avation's fleet comprises 34 aircraft leased to 16 airlines in 14 countries. The fleet includes 19 ATR turboprop, 13 narrowbody jet and 2 widebody jet aircraft. As of 30 April 2024 the average age of the fleet was 7.2 years and the average remaining lease term is 4.3 years
All aircraft are currently leased with the fleet currently generating total monthly lease rentals of US$7.9 million which has increased due to fact that the fleet is now fully utilized.
It quantifies what the purchase rights for aircraft on order might be worth -
Following the exercise of purchase rights for the ten aircraft, Avation was granted six additional purchase rights and the expiry date for all 24 remaining purchase rights has been extended to June 2034. Avation believes that these purchase rights have significant value. The Company uses the Black-Scholes pricing model to value aircraft purchase rights. The pricing model is volatile and sensitive to changes in underlying asset valuations, interest rates, time to expiry and other inputs. At current market conditions the estimated purchase rights value is US$115m (unaudited).
Bear in mind that the market cap of the whole company is £103m, so that US$115m hidden asset is highly material! Although I see from the 31/12/2023 H1 balance sheet that an $88m asset called “aircraft purchase rights” was already recognised within fixed assets. So maybe the “hidden value” isn’t actually hidden, most of it seems to already be on the balance sheet. That needs careful scrutiny.
NAV was 256p according to Avation at Dec 2023, which hardly includes any goodwill or similar intangibles.
Note that the $699m net debt caused $31m in H1 finance charges, which more than consumed $18m operating profit, resulting in a loss in H1.
Paul’s opinion - sounds interesting, but it would take me lots more time to dig fully into all the detail, but so far I quite like what I see. You’d need to do loads more work, inspecting the terms of the debt, competitor valuations, etc.
Thanks to Canaccord for a more detailed note out today, which highlights a big NAV discount to peers, although I’ve heard that a lot before with AVAP and it didn’t seem to make much difference in the past.
Anyway, I like discounts to NAV and special situations, so purely on my brief review, let’s give this the coveted “worth a closer look” SCVR conclusion, and AMBER/GREEN. Nice spot readers, and thanks for sharing your more detailed work with us.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

110 comments
To: Mr Paul Scott & Stockopedia team, thank you for transforming my life and opening the world of UK stocks/trading/investing to me. As a health professional leaving the NHS (sadly!), you have given me confidence to pursue a new career - so far it’s going okay (made up my losses and back in profit thankfully and enjoying my first bull market!)
Ignore the trolls , love the reports !
I only get chance to catch up at night, but looks like a lot to get stuck into tonight - so thanks for the great variety today Paul - good advice on the troll(s) too to ignore. Good to see the thumbs up approaching 200 on a Friday too - a sign of solidarity against the trolls. We are incredibly lucky to get this content (and reader feedback) - of course there are always companies in our portfolios covered but anyone who doesnt accept that should fine a different resource. What we get with SCVR & all the other content, info, screens etc etc for considerably less than £1 a day is ridiculously good value. So a huge thanks to you and Graham (and Roland and the team too). Look forward to the podcast this weekend too which is also a very informative and enjoyable listen.
Redcentric (LON:RCN)
On a quiet Friday afternoon before a Bank Holiday weekend the share price jumps at 15 17 and then 10 minutes before close we have "The board of directors of Redcentric (the "Board") notes the recent press speculation and confirms that it is in the early stages of discussions with Wiit SpA, regarding a possible offer for the entire issued and to be issued share capital of Redcentric".
Watch this space! (RCN provides in-demand cloud storage but the sp is still recovering from an accounting scandal in 2016 for which the then CFO was jailed for five and a half years).
Hi Paul, I want to say how much I enjoy Graham and your company reviews and the way you analyse companies. Your traffic light system is excellent! I really enjoy your podcasts too but would like to know why you don't like Kinovo (LON:KINO) - it is one of my largest holdings and has performed well. The stock rank is high, their revenues and net profit are growing well and they are sorting out their legacy issues. They are in my opinion on their way to £100m revenues and £10m NP.
Hi Chrisp,
Many thanks for the positive feedback, much appreciated!
As regards Kinovo (LON:KINO) I've covered it here 3 times so far in 2024, so that link provides all the detail. I've reflected that the fundamentals are improving with a move up from RED to AMBER/RED. Why still negative? Because I see balance sheet risk, with it looking under-capitalised and having stretched creditors, therefore above average risk of it needing to do an equity fundraise, hence dilution.
Also the legacy issues are getting resolved gradually, but bear in mind there are still significant risks, with receivables and creditors on the balance sheet still quite sizeable relating to these problems, which still has potential to deliver more nasty surprises, as has happened in the past, several times. I can't see the appeal in taking a gamble that their legacy problems have now been resolved, when that might not necessarily be the case.
The core, continuing business at KINO looks OK, moderately good, but in a sector where I suspect it might struggle to be valued at more than a PER of say 10-12? So it's currently on a forward PER of 7.6x, a rating that seems about right to me, given balance sheet weakness, dilution risk, and the (hopefully reducing) risk of legacy problems delivering another nasty surprise.
Shares have indeed rebounded strongly in recent months, from a low base though. But still less than half the twin peaks in 2017-18.
Overall then it would be AMBER here, if there were no remaining legacy issues and all the drs/crs had been settled, so providing there are not more problems then that's where I'll probably end up with KINO.
It's your money, so your choice, but with so many other good companies to chose from, I find this a very strange choice to latch onto and make one of your largest positions! But each to their own, our different perceptions of risk:reward is what creates a two-way market.
Good luck with it, hopefully my caution will be unnecessary. As always, we're not saying our view is necessarily correct, as we can't predict the future (and don't try to). It's just my current assessment of risk:reward today, and that will change in future as the facts develop.
Also why did they put out another trading update this week, which sounds like it's ahead of expectations, but actually is reiterating the same £6.7m EBITDA number that they told us already on 2 May!? I found that a bit misleading, but hey it worked and the shares rose!
Regards, Paul.
My thanks too for the commentary on Braemar (LON:BMS) . Paul's write up was thought provoking as usual and very helpful, but it was also interesting to read further information by 'topvest' and 'tortoise investor'. I feel better informed, if not totally sure what to make of this tricky investment! I do at least draw some comfort from the small stake bought by an industry rival a month or so back.
International Distributions Services (LON:IDS) Released their results after hours, delayed a day by their auditors.
Non carborundum illegitimi Paul, there's always a few that will disagree with you and try to blame you for their investing mistakes. After all nobody holds a gun to your head to buy shares, you pays yer money and makes yer choice. I have known of you and followed your comments since 99 when I knew nothing. There is still a lot I don't know but I have always found you to be honest and forthright, I don't share all your views but I respect your right to have them. You brought me and I am sure many others to Stockopedia. It wouldn't be the same without you. So please do whatever you can to deal with this problem, don't let the rude idiots win!
Yu (LON:YU.) (I hold), yesterday's AGM update:
Following the passing of resolution 9 in relation to the capital reduction process, the Company confirms that it will progress, subject to formal approval from the Court, the cancellation of the Company's share premium account which currently stands at approximately £12.28 million. It is currently expected that the hearing by the Court to confirm this capital reduction will take place on 2 July 2024 and that the capital reduction will become effective on 3 July 2024. Such capital reduction, if effective, will reduce the share premium account and increase distributable reserves of the Company by £12.28 million.
No indication of whether they plan a one-off distribution or to hold the cash as a hedge and raise the dividend on an on-going basis.
Braemar (LON:BMS) - thanks for the write-up Paul. Maybe I can help on deemed remuneration as I came across it a few times when I was a statutory auditor. If you buy a company, and there is contingent consideration or an earn-out that depends on the seller working for the company, for say the next 3 years to earn the consideration, then that element of the consideration is "deemed remuneration". So, the earn-out is treated as an employment cost and not capitalised as goodwill - it hits the income statement over 3 years. This is correct really as the vendor is still the manager of the acquired business and so this cost is really part of the staff costs. I had a few issues with clients on this topic, as obviously they don't like taking the cost through the income statement. There are some detailed technical rules on the topic, but this is the basic explanation. Hope this helps!
It's the main reason I lost confidence in the valuation of Begbies Traynor (LON:BEG) and eventually sold as they add this cost back, but its a real cost of running the business, particularly if the vendors salary cost is artificially low because of the earn-out.
Brilliant, thanks topvest! That makes sense. I remember one of the things that confused me, was that there was some tax advantage to doing it this way, so that the vendor of the acquired business reduced their tax bill by staying on? Does that ring any bells with you?
Thanks for the reply, appreciated :-)
P.
Hi Paul - I'm not 100% sure on the tax treatment, but I suspect its probably treated as a capital gain (at 20% or less if it attracts Business Asset Disposal Relief or the like) as opposed to being taxed at higher rate income tax rates. Have a good weekend all.
A little light reading about bricks for those with brick related shares https://www.theguardian.com/en...
Bricks, CO2- and bricks imports. Will be interesting to see where this goes in the medium term. Both Ibstock (LON:IBST) and Forterra (LON:FORT) have recently put in big new factories which are more efficient (cheaper but also less energy intensive) and close older ones. Some form of actual or de facto carbon tax would be a way for Labour to square a circle of needing more tax revenue whilst satisfying its voter base's desire for 'green measures' and nationalist pandering. There will certainly be new, much stronger new build regulations favouring low CO2 emissions......but also much more house building. (Remember Starmer's promise to bulldoze NIMBY opposition and the dreadful record on housebuilding of late under the Conservatives; brick consumption has been at historic lows). Brick-makers are about to get interesting but I prefer local producers over importers like Brickability (LON:BRCK)
Braemar (LON:BMS) PIWORLD have a BMS webinar on Tuesday 28th May at 1pm. Register here. Not sure why they're doing both us and IMC. Anyway if the earlier day/time suits you better do join us.
Nice to see XP Factory (LON:XPF) finally have some good days, +16% this month, inflation dropping, Euros in the summer could be turning a corner.
Not sure if anyone saw them at Mello? Apparently they were presenting there.
I think it depends on the venue, BBB Cardiff for example is a big sports venue.... Just a shame Wales didn't get through... XP Factory (LON:XPF)
Nice 16% up close, been waiting a long time for it to 'break out'! Happy days
Long may it continue
I think the football could be a plus for Boom Battle Bars, because many have very large projection type screens for sporting events. I asked the CEO about these a while ago, and he said they're very cost-effective, pulling in loads of customers who want to drink lots of beer whilst enjoying a group experience of watching a big sporting event on a very large screen. He mentioned that it's completely incremental beer sales.
A lot of the BBB sites are particularly large, so they're well set up for things like big sporting events.
On the subject of retail access platforms, do read the t's and c's to ensure you will get treated equally with bigger fish regarding being able to trade on the day the shares list. You don't want to miss out on price movements on opening day.
Thank you for your comment Paul but they are hard to ignore. I think a three strikes and your out (with no refund) is what is needed.
I will reiterate what I wrote here yesterday. I sometimes think you must be machines; how you and Graham manage the output that you do, five days a week 52 weeks of the year is beyond and actually
cannot comprehend the efforts that you must go to, on our behalf, to analyse the news flow, gather their thoughts, put it down on “paper” and then come to an opinion. All for about a £1 a day, with the rest of
Stocko thrown in for free.
Thank you.
Regard
Michael
Did I miss something ?
EnSilica (LON:ENSI) I suspect you’re thinking of the Primary Bid platform Paul
EnSilica (LON:ENSI) I suspect you’re thinking of the Primary Bid platform Paul
Brain fog earlier, that's it, thanks Reb! :-) I'll edit article now with your correction, thank you! :-)
Paul.
Mello feedback ?
Anyone get any warm fuzzy feelings . I managed to make it in the end
Few thoughts
Velocity composites -
Quite liked it , very impressed with two of the board members who were in attendance and were very switched on.
Took a while to understand what they were offering to customers but the case appears to be “we can do it better than in house and save you hassle on production and stock “
CEO and founder very “in” the business and he will hopefully be empowered with good board .
Should be cash generative from now on and USA looks wide open and “in play” with revenue coming in first year circa 10 million .
Probably a long on boarding / runway with aerospace contracts .
Technology makes sense definitely rising tide .
I took a starter position just so I don’t forget who they are .
Christopher mills
Nothing new or startling re enforcing the value in the market , liked animalcare , Marlowe , Trifast , centaur , tribal and others he’s talked about before .
I’ve jumped back into centaur on the long term value , dividend, bid possibility and breakup value .
Rockwood / Staveley
as impressive as ever . Unveiled new holdings capital and funding circle .. Looks like they bought funding circle right at the bottom and a compelling case it’s very undervalue .
grabbed him after for 2 min on titon which sounds like they are now getting pretty active with as that’s a long term turnaround after years of going nowhere . So don’t expect anything to happen there .
didn’t bump into anyone maybe stocko attendees should all wear a carnation or something to make each other known
I’m easy to spot as I’m the scruffiest in attendance
I concur that Mello was excellent, there was a real buzz amongst attendees which was great to see. It’s such a good environment to talk markets & stocks
Companies attending were still low but this too will hopefully improve as the small cap market improves. Richard Staveley was as excellent as always. Sorry I missed meeting you PlanetX- we’ll coordinate a Stocko bar slot for November
Good news for publishers (Reach (LON:RCH) Future (LON:FUTR) ) as Digital Markets Bill pushed through:
The UK has paved the way for Australia-style payments to news publishers from tech giants as the Digital Markets, Competition and Consumers Bill was passed by Parliament.
The legislation was rushed through on Thursday in the “wash-up” process following the calling of a UK general election on 4 July.
The law will enable tech companies such as Google, Facebook, Apple and others to be given “strategic market status” and be regulated by the Digital Markets Unit (a division of the Competition and Markets Authority).
The DMU could compel tech companies to pay for the news content which appears on their platforms and will work to establish codes which ensure companies serve the best interests of consumers. It will have the power to fine tech companies 10% if annual turnover if they abuse their market positions.
https://pressgazette.co.uk/new...
Did anyone else read the announcement from Brave Bison (LON:BBSN) this morning on the Notice of the AGM and Proposed Capital Reduction. I was confused by this statement: The Capital Reduction, if approved by Shareholders and confirmed by the Court, is expected to increase the distributable reserves of the Company by £158,379,042. How is that possible for a company with a market cap of £32m?
I didn't realise that you can combine different shares on the charts for comparison.
Thank you Paul for demonstrating this .
That will give me something to have a go at over the long weekend.
Keep up the good work Paul & Graham.
Nor did I.
Just had a quick stab with Yu (LON:YU.) IQGeo (LON:IQG) and Warpaint London (LON:W7L) [hold/sold post bid/hold]
Lots of tools in the top and you can expand/shrink time period on the axis.
To save you squinting, performance is in the same order as above
Small note to development team - can you amend the formatting of the arrows on the right to match the stock selection, ie white text on colour?
Hi Pimlico,
True, Yu (LON:YU.) shares have been amazing on the timeframe you chose.
However, and just for fun, I added my biggest holding Plexus Holdings (LON:POS) [ignore the ticker, it's an unfortunate coincidence, not a description of the company] onto the chart, and played around with the x-axis, and discovered that POS trounced Nvidia, YU, and Warpaint over this specific period below ;-)
And indices, or indexes if you prefer, too.
Congrats Warpaint London (LON:W7L) holders.Wish i had bought.The whole beauty/makeup sector seems to be doing well both sides of the pond.elf Beauty (NYQ:ELF) posted results yesterday and has multibagged from a billion dollar company to a 10 billion dollar company since the pandemic pretty much.Don't ignore the business model and compoundng power of the beauty sector once mostly women i'm still guessing (?) like your products!Another one Ulta Beauty (NSQ:ULTA) 's performed pretty darn well over the last 10-15 years just from examining the chart too.
DFCH - Fcst p/e 6.5 and p/tb 0.53
Distribution Finance Capital Holdings
2023 Highlights (Results were 9th April)
• Over threefold increase in pre-tax profit to £4.6m, an improvement of £3.3m on prior year (2022: £1.3m)
• 10 consecutive quarters of loan book growth since receiving banking licence in September 2020
• New lending up 20% to a record £1.2bn (2022: £1.0bn); supported by a 26% increase in total facilities to £1.0bn (2022: £0.8bn)
• Loan book up 32% to all-time high of £581m (2022: £439m), including £18m from new lending products
• Added 330 new dealers, taking the net total dealers served to 1,182 (2022: 998) and supporting 89 manufacturers (2022: 90)
• Unlocked capital capacity for further loan book growth
• BBB ENABLE Guarantee extended to £250m with further £100m extension potential; obtained £20m Tier 2 capital facility from British Business Investments
• Potential aggregate capital capacity provides option to deliver attractive loan book growth to in excess of £800m, without the requirement for additional dilutive Tier 1 equity raise
• Scale improves returns: adjusted earnings per share increased to 1.8p (2022: 0.4p) and tangible net asset value per share to 55.6p (2022:53.2p)
Blackrock declared 5%+ holding end of April. SP ticked up sharply on May 21st when 1.65m shares were traded.
I have added.
Intercede (LON:IGP)
Cavendish have issued a note this morning summarising yesterday's CMD :
https://www.cavendish.com/rese...
Andrew Darley sounds very upbeat (but note they are IGP's Nomad and broker).
Just to say please please keep up the great work in the reviews, it really is appreciated.
Hi Paul, Good morning and a quick note on Emmerson (LON:EML) which you included in your list of companies reporting today
Please note that as per the B/S it did indeed have cash of $2m at the end of December as you note, but as the company states, it then raised $2.5m in April this year.
Its a resource stock which is usually outside the scope of the scvr and I see it as a special situation as its waiting for an Environmental permit (ESIA) which is long delayed due to water scarcity in Morocco and the concerns of local authorities on this topic.
The company recently revised their proposals to cut water use by 50%, appealed the first decision and have submitted a revised proposal, so shareholders are now hoping this gets it over the line.
I don't see the stock as one you are likely to wish to review, but did want to highlight the cash is better than you noted and its certainly an interesting special situation for anyone who likes to research companies in this sector.
Morning 1James1n1,
Good points, thanks. I only noticed that Emmerson (LON:EML) was a junior resources project once I'd finished looking through the numbers earlier today, so thought I might as well put up a quick comment anyway.
Thanks for flagging that it did a small fundraise more recently. I probably won't comment on it again, but it's at least another notch on our quest to get to 600+ companies this year!
I noticed that the chart of the price of potash within the RNS shows it has collapsed. So do you think their project in Morocco would still be viable at this much lower price? I think there was a disastrous UK potash company that a lot of people lost money on some time ago. Not my area of expertise obviously, but I'll punt on anything if I think risk:reward looks good.
Regards, Paul.
Sirius Minerals (SXX). Last week it was reported that up to 80% of jobs at the Woodsmith project could be risk. So Anglo American can't make money on it either!
Thanks Paul for replying.
As with all stocks in this sector, there is a story behind Emmerson (LON:EML) and like Copper where the story in recent years has been about demand/ supply imbalances (which now seem to be finally showing up in pricing for copper), the story on Potash is increased need for higher yields on farm land to feed a growing world population, which is where Potash comes in.
At the moment, the share price is depressed due to delays in the ESIA approval and while some regard it as a binary outcome, the share price should respond if approval finally comes through.
Having shed most of my resource stocks, this is the last one standing and I hold as I think this could come through, but its pre-production, pre-funding, pre-ESIA approval, subject ultimately to commodity price volatility and therefore very risky!
Pennant
Slightly strange situation at Pennant
Announce a fund raise at 4.30 yesterday and result of fund raise at 8am this morning so basically raising 1.3 million at a 15% discount in a raise that only gave a few of the existing presumably top 5 shareholders, directors and brokers to fill their boots which was quite annoying
Interestingly a lot of shares suddenly now available to buy at 26.75 p
What’s even more bizarre is that even with the 1.3 million added cash Mr Market now believes the entire company is worth less than it was yesterday (think my numbers are tight ,
By my fag packet a raise of 1.3 million at a 16% discount should knock 2% off the previous valuation but it’s dropped SP from 29 to 26.75
Best price in recent weeks has been circa 28p
Buyable now at 26.75 p
So as a “weighing machine not a voting machine “ the company has 1.3 million quid extra and is worth less as a whole than it was at anytime in the past month.
Nothing has changed at the company recently apart from chairman getting kicked out and a new chairman presumably after some abortted corporate activity that cost 300k
I’ve taken this as a buying opportunity there are sone smart cookies on the shareholder register
Presumably there will be RNS's shortly if the top 5 subscribed.
Not sure as may not have affected overall % they hold .
I had a slight moan to the advisor and had a chat , asked him to get CEO to call me as I’d like to visit and fair enough got a call 30 minute later which was pretty good .
I’ll go down have a look mid June .
The new chairman is a definite Rockwood guy so I think there’s some action in the pipeline in the next year or so .
As it looks like a quiet Friday, I wonder if Paul might be able to take a quick look at Braemar (LON:BMS) results from yesterday. As I said, this looks cheap and potentially interesting as a junior Clarkson (LON:CKN) . However I find it tricky to analyse due to its complicated accounts. The high level of staff bonuses is off-putting but operating margins are usually reasonable and cash flow is good in this business (although hampered by 'one-offs' in 2024). A critical eye would be helpful, as it was with another of my holdings, Concurrent Technologies (LON:CNC) a while back. Thanks.
Morning sparkler,
I just had a quick look, and Braemar (LON:BMS) results for FY 2/2024 were only in line with expectations, and were weak in absolute terms vs previous year, adj EPS down 21%.
If other people want me to look at it, please give sparkler's post a thumbs up, and if it gets more than 20 thumbs, I'll write a short section on it later this morning.
Regards, Paul.
Yes please Paul - a long time holder (20+ years) of Clarkson (LON:CKN) and Braemar (LON:BMS) have been on my list (that I never seem to have enough time for) for some time so your opinion would be very much welcomed.
OK, I'm on the case, as we're up to 27 thumbs above on the original post. Give me about an hour to recap on BMS, I've already spotted that it's not simple!!!
EDIT: Right that's BMS done. What a pain, I did not enjoy that one! ;-)
I have been in and out of Braemar (LON:BMS) over the years as I trade it now and again where it had a habit of going up a lot on results day at least until people realised the massive discrepancy between statutory and adjusted earnings.
Some issues to be aware of from my notes although I did not look at yesterday's update:
Go on then, I will put the 20th thumbs up. I bought into Braemar (LON:BMS) a few weeks ago thinking that their results would have been much better than they ended up being, and also the investigation results clarified more fully than they have been. Upon the results I sold out, but in my opinion it is still undervalued and perhaps does not deserve to be (shennanigans aside). Too much SCVR space already taken up by the subject, so just a quick note from me, thanks P&G.
It's the bank holiday weekend coming up. An extra day to do some shares research!
Lots of shares have gone up in the market rally but there are usually some (especially small caps) that get left behind in these events, and catchup a bit later. Has anyone spotted anything good?
Jupiter Fund Management (LON:JUP) (I hold) has stayed put despite other fund managers going up - but there are some concerns about the ability of the business to grow at the moment so that might be justified.
Some of the high end fashion brands like Burberry (LON:BRBY) have gone nowhere in last few weeks but I think I'd prefer to look at that properly once there are clearer signs the rich aren't cutting back on luxury goods anymore!
If you like property companies Supermarket Income REIT (LON:SUPR) (I hold) is also worth a look as that hasn't risen during the market rally either. Decent dividend, reasonable discount to NAV, low risk tenants, playing into a trend (owning out of town supermarket stores which have capability to deliver online shopping locally), debt interest was already a bit higher than some REITs so less risk of upward increases in debt costs.
easyJet (LON:EZJ) looks cheaper lately but I own Jet2 (LON:JET2) and On Beach group (LON:OTB) already so I don't think I will research that one too.
Mincon (LON:MCON) I used to own years ago and looks depressed. I might look at Graham's recent commentary although it does look like it's not really grown significantly for a long time!
National Grid (LON:NG.) looks much cheaper now and could be a good long-term dividend payer. I saw some of the helpful reader comments yesterday so assume all the investment it's announced isn't cheap.
Jarvis Securities (LON:JIM) I assume looks depressed as I assume it's still under investigation by FCA. I've not looked at that at all but my gut instinct is long investigations rarely have good outcomes!
After recent stocko commentary I also have on my radar to look at Nexus Infrastructure (LON:NEXS) - so today's addition from Paul is helpful - and Costain (LON:COST).
I'd welcome other ideas! I probably only have time to look at 1 or 2 this weekend.
I've also been on the lookout for things that have lagged the rally over the last month or so (and for no obvious reason, so not including anything which has reported soft trading) - some of the key ones that stand out to me are:
Ramsdens Holdings (LON:RFX) - this looks to have been held back by a fund selling up their position
Sanderson Design (LON:SDG)
Chesnara (LON:CSN) - hugely lagged the other life insurers recently
Card Factory (LON:CARD)
Newriver Reit (LON:NRR)
Whitbread (LON:WTB) - this one has been strangely weak for last couple of months, although not clear why. Possibly disappointment that they're not going to get rid of their restaurants as quickly as expected?
Why are Jarvis under investigation?
The word investigation always implies some wrongdoing and who dunnit. The FCA decided to audit all financial companies to establish whether internal processes were proof against money laundering. Jarvis Securities (LON:JIM) have a some Model 'B' customers, including big names like Goldman Sachs and Yorkshire Building Society, for whom they provide a white label service . I understand that some of JIM's other Model B clients haven't been checking out their customers sufficiently and Jarvis have terminated the relationship. The process is nearly over according to latest reports from the company and I have bought more on weakness. Do your own research or go with baseless assumptions from posters who haven't.
Earlier this week there was a question on what might benefit from base rate cuts. Now the election has been confirmed, that helps pull the search parameters a little tighter.
I have a watch list of infrastructure and energy trusts plus alternative energy (blue sky) stocks and some of these seem to be close to their inflection point, with some already on their way to recovery. Most of the non-blue sky stuff has decent yields.
I had a look at GSF a few months ago. They don't present consolidated accounts which makes analysing them very difficult, although I don't think this is unusual for the industry.
Most of their assets are still under construction. They revalue the assets periodically using a discounted cash flow model and as they get closer to completion, the value increases (of course).
At holdoco level almost all their profits come from these revaluations rather than cash flow so it looked to me like I'd effectively be buying a construction company that will over time morph into an energy storage business. They are in the late stages of completing a number of their projects so their capacity is expanding fast but for now the cash flow doesn't seem to be there.
Another thing that stood out to me was their large dividend. It doesn't make sense to me to raise equity then spend that money paying dividends. I feel the money raised should be spent on their construction projects and dividends should be paid when they are generating sufficient cash to pay the dividends (which they don't seem to have). The fact that all this is hidden underneath unconsolidated accounts is disappointing to me.
There's very possibly money to be made here. There's enough cash to maintain the dividend for now, their storage capacity is expanding quickly and their valuation methodology seems reasonable, using a 10% discount from memory (which I hope isn't failing me) so the discount to NAV may well be unjustified. Understanding the underlying assets and cash generation however is very difficult.
Hi Paul,
Just remember that for every troll there are many of us who find your analysis of companies a great addition to their own research. Quite how you and your colleagues manage to cover so many companies is beyond me, so I can only express my thanks and admiration to the efforts which deliver so much to so many.
Chris.
Agreed Chris . Frankly, I think the best answer to trolls is to ignore them and hence I 100% agree Paul that an ignore option should be available on the platform as it is on others I use such as www.wine-pages.com/forum .
I think Paul et al do an amazing job and the comment this week was quite rude, attention seeking and unhelpful. It's all just an unnecessary distraction. Maybe there could be an official policy whereby anyone who wants to comment on the level of service they think they're getting then they could email Stockopedia direct and leave this board free for what its purpose is. I'd be happy if any comments on service could be taken down immediately and the subscriber reminded to contact Stockopedia direct.
Avation (LON:AVAP)
As I noted here a few days ago the $10m cash profit on the sale of new ATRs had a strong read through to the balance sheet value of the rights on the other 34 options. Trading statement today confirms the value is indeed basically all of the current market cap. (Before any rise today).
Ahead of expectations update with company moving back into profitability and having reduced debt right down to $600m (remember it is all more than asset backed) also comes with an upgrade from brokers to a target price of 280p being a discount to an increasing NAV of 310p
That’s double the current share price.
Importantly financing sector has returned which suggests a refinance of the 2026 bonds should be view constructively. That should also lower cost of debt further.
Looks very strong and unloved to me but I hold so I’m also biased.
Thanks David so do I and also flagged here a few weeks ago it looked very strong value with the last aircraft being leased. Surely the SP should be starting with 2 very soon so continuing to hold.
Slowly the value of all my small caps seems to be being realised, it's been a great market last 2 months.
Avation (LON:AVAP) thanks so much davidjhill for commenting on this. I took a look after you posted and it really seems to be under the radar. Perhaps because people are not confident of understanding the details of the lease arrangements? Anyway, today's results are pretty outstanding, with improvements in all areas and every prospect of better to come. A geared play on the air industry recovery I would suggest? Many thanks (I hold as of three weeks ago!)
Hi doctor dave
I think people don’t understand the debt structure. Previously when stressed through covid they refinanced some bonds which obviously weren’t done at the optimum level (though changes in interest rates since have made that look much less onerous). Whilst most debt is secured against aircraft on same terms as the subsequent lease (ie no interest rate risk and no capital gap) the bonds hang over the shares. I think this debt structure was a mistake by mgmt about 8 years ago as they previously did everything back to back.
However, with the debt market reopen and net debt down to $600m the refinancing of $250m of bonds should be straightforward. The capital value of the planes far outweighs the debt so LTV margin is very favourable and they have a good track record of paying down debt in probably the worst cycle for aircraft lessors you could imagine.
ATRs look like a future proof plane given their emissions and fuel economy and with air travel surpassing pre Covid I think demand will remain strong. Given the problems at Boeing impacting supply then I see good quality and well looked after aircraft having very strong 2nd hand value.
Thanks David
I followed your advice and added to the “blame game” portfolio which is outperforming my DYOR portfolio .
I’m pretty much fully invested so Couid only muster up a few shillings
Paul, IMC is a great resource, my preference is to wait for them to come out on YouTube - Watch them on 1.25x with captions enabled - Watch 5 of them in the same time as 4 of them - Assuming they're all the same length - Keep up the great work, it's much appreciated - Have a great weekend!
Card Factory (LON:CARD) under £1 with 4.5p ex divi next week…. Seems too cheap?
I wouldn't disagree with that however until Teleios complete their exit the stock overhang will continue to be a major drag on the share price.
Agree investwise Card Factory (LON:CARD) is too cheap but for me it's a matter of opportunity cost v patience. I sold when the needle barely moved a week after the divi announcement. It's not that it probably won't recover (see COYS61 and Teleios issue) - it will - but for me there are plenty more rewarding destinations for my capital especially in this market.
Would welcome your thoughts on better opportunity out there at the moment?
Trident Royalties (LON:TRR) announce one of their gold royalties has had first pour. The value of these can be hard to assess, as what they actually get is the right to buy gold within a time window. So the profit they make depends on the volatility of gold within that window. Historically, a 1.5% return is typical. So with a 5 year royalty over 58,500 oz a year, assuming gold at 2,300 and a 1.5% turn this should generate $2m a year for the next 5 years.
They were at Mello yesterday and I had a chat with them. At the end of the show David Stredder said how difficult it was persuading companies to bother coming, and so can I suggest that people who did attend consider sending an email to those companies who took the time to engage with private investors, so they know it is time well spent.
A good thought dp and Mello was certainly well worth attending. Thank you David Stredder.
That is an excellent idea dp....Most of the companies had very full presenting rooms and Warpaint had to do three presentations in front of 65 investors each time so they were certainly appreciative and enjoy attending to meet shareholders and potential new shareholders.
I think readers are getting confused with the difference between trolls and people with a grievance.
I guess it's very easy for those in the wrong to say 'oh no it's trolls again', purely as a smoke screen...
My Appolologies Paul if I hit a raw nerve yesterday, but please, if you post that you are giving your 'expert' analysis on a stock, then maybe actually finish the list??
Not a troll to hide behind, but a genuine feeling which I know others would say, if they new this board wouldn't label them trolls...
Have a lovely weekend everyone, and let's hope my well meaning criticism can be taken on board.
CHRI55,
I think you have a valid point. Sometimes, a company the I hold is on the Small Cap list to review, but due to bigger news, gets forgotten. It can be frustrating, but the tone of your comments yesterday were poor.
I’d like to know which company you were looking out for? Maybe it will still get looked at.
All the best.
Sadly, whilst I am sure you feel they are well meaning the majority do not agree, and your comment history shows that this is your usual approach, which appears to be attention seeking (and sometimes in BOLD for added attention). The history of your comments is in your profile - very rarely a positive comment in many months and almost always a dig at Paul and Graham.
That said - everyone is entitled to an opinion, expressing yours in a respectful manner might achieve more.
Have a lovely weekend and, as you say, let's hope my well meaning criticism can be taken on board.
Last month you wrote in the comments that "Keyboard warriors don't like to give away their true identities..."
Looking at your previous antagonistic, trolling posts, it's quite clear that you were referring to yourself and take pride in being a "keyboard warrior".
Nothing you have posted is helpful or constructive, let alone polite.
Your justification for such rudeness is that you have a "grievance". I must have missed the part at the top of the SCVR where it states that every single share listed will get covered or that every single share that CHRI55 wants covering, gets covered.
Furthermore, why should Paul or Graham or anybody else provide you with useful analytical insights, when you have posted absolutely nothing of value or insight yourself?
As somebody noted yesterday, your sense of entitlement is hilarious, although for my money, it's tragic.
Please do allow your subscription to lapse. This platform will be better without you and you will be far happier.
I don't believe you're a troll. I just believe you have unrealistic expectations of the SCVR and a total lack of diplomatic skills.
Thank you, that's appreciated.
IGP, I did too Paul - dash!! They look a tad toppy on valuation but I was left with the impression they have plenty of opportunities, they do it well and the people are good.
AJ Bell (LON:AJB) Andy Bell placing stock last night... fair enough after rise.
As it's Friday.....
After Paul shared, I read the Woodford Views thing and thought hmm interesting....does it stack up?
As always, kind of.... we all manipulate stats to make points.
Here is the Lloyds Bank balance sheet. £298bn of mortgages back by £298bn of retail deposits ...but £103bn of non interest bearing current accounts. This is where NIM comes from. The rest which is generally high margin lending is backed by an excess of commercial deposits. In banking it's actually harder to get paid on £100m than £1k .....so I would hope positive NIM here too....actually that's the name of the game isn't it.... generate a margin.....so the maths wouldn't really work if banks were Net Net paying more out to customers than they received as income. Ofcourse Neil focussed on the mortgage interest bill not the total. It explains why things haven't collapsed .... the mortgage market is much healthier than in the past....mainly due to much lower percentage of interest only lending. We have seen how much money Hargreaves Lansdowne and AJ Bell are now making that deposit rates have risen..... this is similar in Banks actually... traditionally they make margin on deposits and mortgages.
An offset under appreciated as rates rose was the traditional margin could be earned, reducing the margin on mortgages which helped offset some of the pain. ( rates rose less fast).You then had a huge chunk of money that wasn't earning interest that suddenly is. Im not sure net net its actually much of a benefit but it certainly softened the blow, particularly coming off zero rates.
Personally I think there were so many distortions in the market from zero rates that were under appreciated. We drifted into a policy we really didn't understand and now we are only beginning to understand the benefits of moving away from it. Capitalism survives on creative destruction and in a way ZIRP stopped this working.....as we move away from this policy the invisible hand is working again, and so the collapse everyone expected never happened. I wouldn't go as far to say the price of money doesn't matter though....it's a central tenet of capitalism.... which is why we all crawl all over the Fed minutes ( not that helpful this week). IT was a thought provoking piece so FairPlay to him .... and we all want to see the UK doing better.
Woodford can't even do basic arithmetic.
"The average mortgage is £150,000, and those customers refinancing will typically be going from a rate of 2% to about 4.5%. This will increase monthly payments for these households by around £200 per month, or close to £2,500 a year. In aggregate, that will take £3.5 billion out of their pockets."
£150,000*(4.5-2)/100 = £3,750 a year. 1.6m refinancing with his erroneous £2,500 figure gives £4bn not £3.5bn!!
And 1.6m at the correct £3,750 per year gives £6bn. So he's way out.
He lost people a lot of money and you can see why.
Yes but a 2.5% increase in mortgage rates will not lead to a 2.5% increase in monthly mortgage payments as per your calculations - unless it's an interest only mortgage. So I think Woodford looks about right on this one
eParo was right, this is a rise in interest payments of £3,750 and hence mortgages go up by this.
You're only looking at interest payments - nearly all mortgages have a capital component - you need to take this into account when calculating how the monthly mortgage payment is affected.
If you put Woodford's figures (150k mortgage, rates going up from 2% to 4.5%) into this calculator you can see the monthly payment goes from £636 to £833, so a roughly £200 increase.
Mortgage Calculator UK: Repayment & interest only mortgages - MSE (moneysavingexpert.com)
The opposite compounding effect of a repayment mortgage means the effect on annual repayments is much less than the nominal * interest rate change due to the ever decreasing capital amount. you can roughly more than halve your annual interest calculation when translating to monthly repayments. Woodford maths stack up I’m afraid in this instance..
Fair enough. Nonetheless there's no way I can ever trust Woodford to manage money.
He's not managing money any more and probably never will again - but I think the recent commentaries he's doing are pretty good and worth signing up to.
:-) well can’t argue with you on that point eParo
https://tools.moneyhelper.org....
You can do the maths here.... £150k over 25 years .... repayment mortgage ... repayments go from £635 to £833 = +£198 mth .....
I was really just looking at loans to deposits and thinking about this deposit interest multiplier idea though....
Paul, Graham, thank you for the coverage of the companies, it's a hell of a job to get this number of companies covered in just a few hours. Let's hope the trolls are back to the cave, this forum is a good source of knowledge from people with a deeper understanding/knowledge of some companies.
The relentless RNSs of "Transaction in own shares" continues. Been going on for months - shows how depressed UK valuation is currently. The worm is turning though!
Yes, the worm is turning. But when USA catches a cold, we follow.
So the advice is to sell when the worm starts sneezing?
Paul, you are special in what you do here. Normal people will know the amount of companies you analyse and how quickly you comment on them is little short of amazing. Truly value your insights and your humour. Please don’t let one d#*^head Spoil it for the rest of us. Be strong and keep smiling
I don't make hardly any posts here, but would like to add my thanks to the writers of the SCVR in general and to Paul in particular for also doing his podcast. The depth and breadth of knowledge and wisdom shown by many of those who comment BTL is also appreciated.
I have read a lot of investment books, but I have probably learned just as much from this blog.
So let's celebrate what we have. It really is something special.
I too do not post very often but fully appreciate the time, effort and bloody hard work Paul and the team put in day after day. Many thanks from the silent majority!!
Just to say that I agree wholeheartedly with these comments and also that I am finding the SCVR summary spreadsheet very useful.
Hi all, on the subject of trolls and how Stockopedia can handle them, I have a YouTube channel (nothing to do with shares), and that brought it home to me that there are an awful lot of very sad people out there who really should try and get out more, anyway, YouTube allow a content creator to remove a particular post, and or, block access to that user from your channel. Couldn’t Stocko offer the same facility to the owner of a blog - blocking access to the SCVR, or maybe blocking the ability to post comments. Anyway, many many thanks to Paul & Graham for their fantastic analysis and of course Paul’s podcasts that keep me company on my long walks.
Agreed. Great work by P&G . In my experience banning trolls just encourages them to come back with a different pseudonymn (espec when they are venting/angry). Very frustrating. Never never feed the troll. Ban move on. Ban move on.!
P&G - sounds like a detergent manufacturer! Well our pair do an excellent job of washing the dross out of the small cap sector.
Why can't we use the red flag for some kind of Stocko offender de-rating?
- more than 3 = 1 week posting suspension
- more than 10 = 1 month posting suspension
- more than 20 = 3 month posting suspension
- 2 suspensions within 2 months = 6 month posting suspension
As was said yesterday, those who have nothing constructive to post should consider X and ADFN.
Paul, Graham and Rowland provide fantastic analysis with balanced commentary, providing starting points for new ideas and raising red flags against stocks in our ideas lists.
Paul's contributions in particular go beyond the call of duty, bringing us the weekend podcasts, mystery forecourt wash tests and impulse trades in the Mary Shelly, whilst blowing his own crumpet to buy the cannons last October. Today we have his clarion call to consider taking profits as surging stocks gain white caps. Nothing like a damp bank holiday weekend for this analysis.
Finally, I would like to thank other subscribers who are generous enough to share market updates, macro and micro analysis and share clips, links and tools.
I think that it would be better if we just ignored rudeness and unhelpful comments. I am never in favour of cancelling people I don't agree with.
Unfortunately many only appreciate their own point of view, and therefore label that other view a troll..
Anyway, Appolologies for not replying any further, as very happy from all the comments that I received my point was received and hopefully will create some change...
I also have a very happy and busy life with a long weekend ahead.
Hope everyone enjoys their own equally as well..
"Couldn’t Stocko offer the same facility to the owner of a blog - blocking access to the SCVR, or maybe blocking the ability to post comments"
I think that this is an excellent idea.
You should suggest it with the little green Intercom button
Cheers Michael - I will indeed do that.