Small Cap Value Report (Fri 27 Nov 2020) - BOO, SAGA, LOOP, RCH

Good morning, it's Paul here, with the SCVR for Friday. Jack's busy with other work today, so this is all my work.
I'm hoping for a quiet RNS today, as is usual on Fridays, so I can have a big catch-up day - with a long list of things on my note pad from earlier this week, that I still want to look into. So I've cleared the decks today, got up early, and have the whole day allocated to writing this report.
I saw there was some bickering in the comments yesterday, over a subscriber chasing me on De La Rue (LON:DLAR) . Relax, he's a friend, and he didn't mean to sound abrupt! I will be looking at DLAR, because it's an interesting company, and I'm wondering whether to put it back on my personal buy list or not. I try to prioritise companies that look like they may be profitable investments, that's what it's all about after all! Although obviously I have no idea what short term share prices are likely to do, that's down to market sentiment. We just stack the long-term odds in our favour, if we buy strong companies that are growing, and are priced attractively. Although markets have been chasing growth at any price in recent years, so valuation doesn't seem to matter that much at the moment.
Agenda -
Boohoo (LON:BOO) - quick comment re valuation, and forecast from Zeus (done)
Saga (LON:SAGA) - safety accreditation of cruise ships (done)
Loopup (LON:LOOP) - Trading update (done)
Reach (LON:RCH) - Trading update
After that, I'm hoping to cover backlog items from earlier this week.
Frustratingly, I got bogged down in today's announcements, and didn't managed to make inroads into the backlog. It takes a lot of time & energy to unpick complicated & ambiguous updates like the ones today from LOOP & RCH. Hounding me because I haven't got round to covering some other company, is really unhelpful, so please don't do it. Today's report is now finished.
.
Update on Paddy
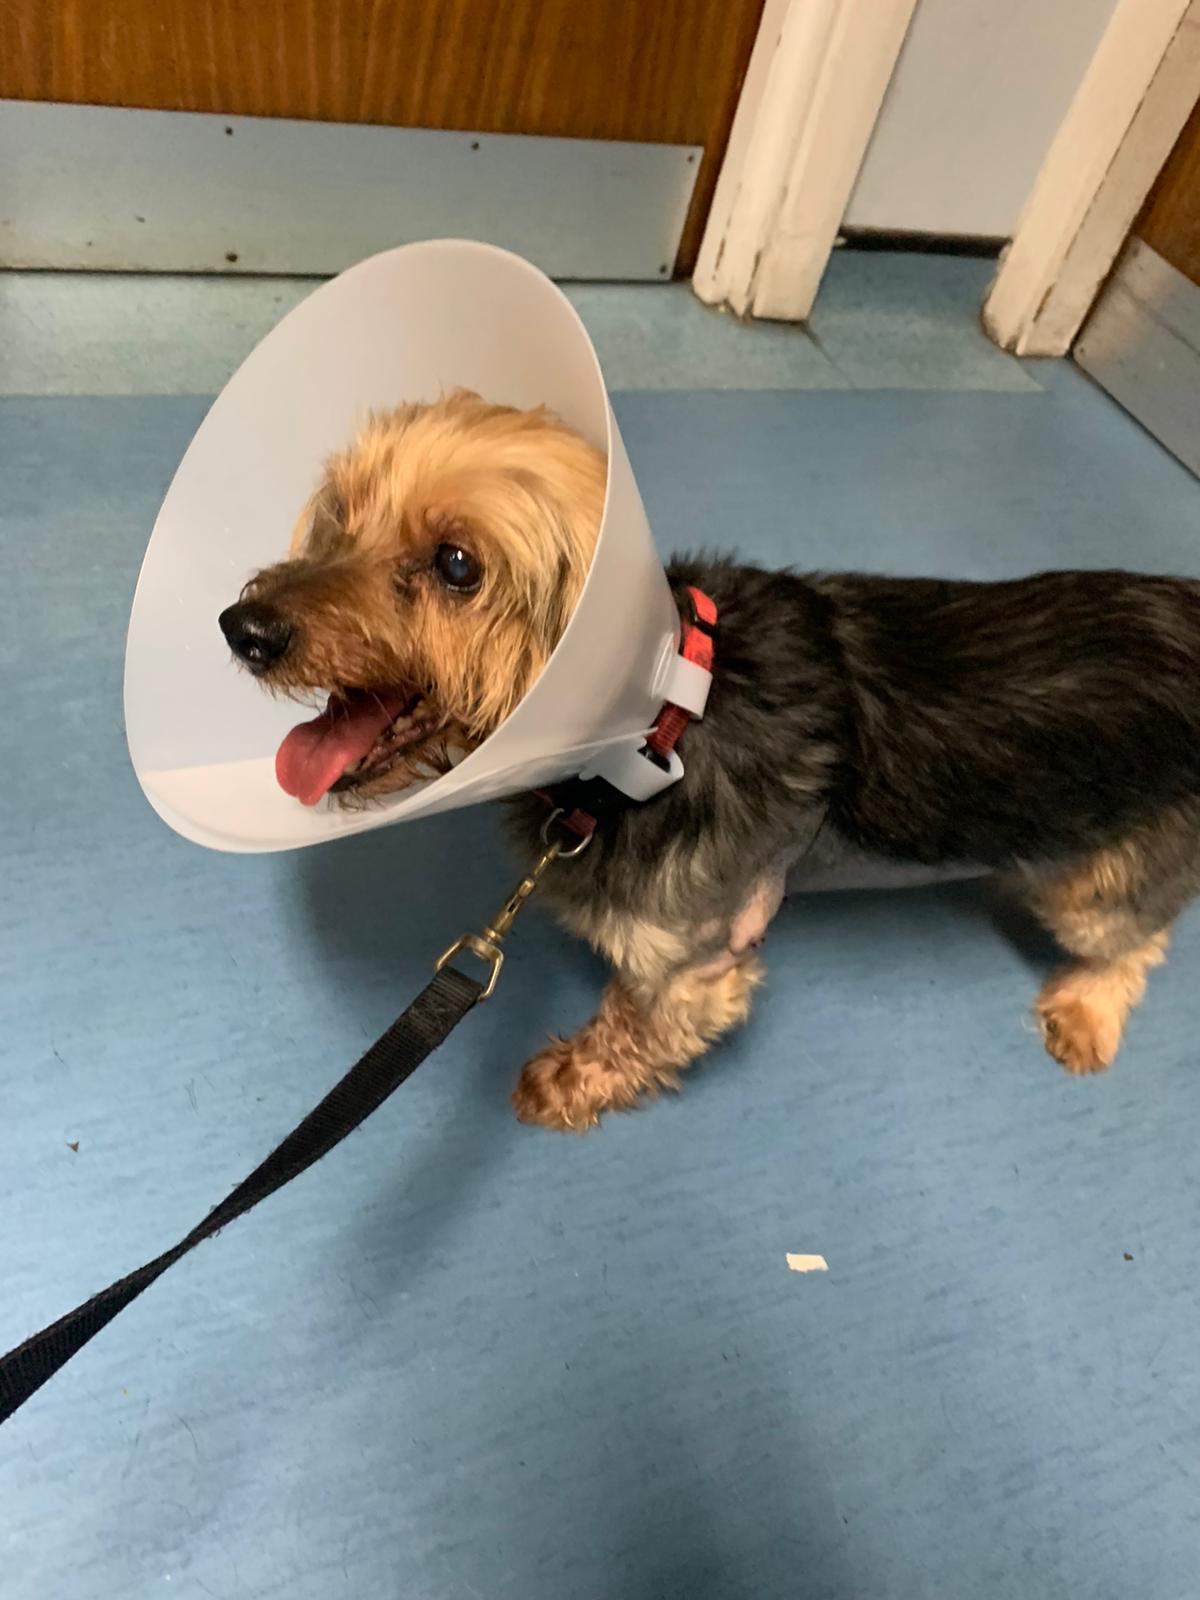
My little canine friend had an operation yesterday, to have a large cancerous lump removed. He's feeling a bit groggy, but survived the operation, thank goodness (he's about 13 years old, so it was risky. He has to wear the "cone of shame" for a fortnight! So I'm mightily relieved, and should be able to focus a bit more on shares now.
I know we're not meant to let personal worries affect our work, but in reality, we're all human, and sometimes these things do.
Boohoo (LON:BOO)
300p - mkt cap £3.7bn
(I hold - Paul - my largest position)
An update note from Zeus, the firm which originally floated BOO, came through on my email yesterday (via Research Tree, so available to all). It's titled "Actions not words", to emphasise how meaningful the "Agenda for change" programme is. The appointment of Sir Brian Leveson PC is the latest, highly significant step in the right direction.
I spoke to the company, and commented that surely nobody can now question BooHoo's commitment to completely cleaning up its supply chain. The response was (I hope they don't mind me publishing this);
I don't understand why anyone doubted why we weren't serious about fixing it. We will be the next Zara, and to achieve that, we must fix anything & everything on our journey. Very simple.
Forecasts - from Zeus are higher than the broker consensus. They know the business better than any other brokers, I would suggest, since they floated it originally. BOO has a track record of beating forecasts.
FY 02/2021: 8.2p EPS
FY 02/2022: 11.4p - a PER of 26.3
I suggest to subscribers, that being able to buy one of the best growth companies out there, for a PER of 26.3, is a tremendous bargain. Particularly as the issues which have caused the relatively low PER (for a rapid growth eCommerce business) are being comprehensively fixed.
It's only a matter of time before the press, and brokers, recognise reality, and start looking forwards, not backwards. Then the ESG fund managers are likely to want to buy back in, when they see the strong growth ongoing.
I note from a Telegraph article today, that even they (one of BOO's harshest critics) seem to be softening their stance a little. That article also points out that a previously bearish analyst from Shore Capital is softening his stance (behind the curve, in my view). Why on earth would anyone sit on the sidelines, to wait and see how the supply chain reforms progress, given that the likelihood is you would then have to pay more for the shares?! That doesn't make any sense to me at all. Surely the time to buy is when the shares are artificially cheap because of ESG concerns, but those concerns are being addressed seriously?
As mentioned yesterday, I see this as a superb ground floor investing opportunity, and make no apologies for vigorously flagging it to readers. I want us to make money! At 300p I see BOO shares as a golden opportunity, and have personally filled my boots (my largest holding). That sounds rampy, but it's the truth as I see it. No speculation, just facts. A superb growth company, on a PER of 26. What's not to like? Obviously you need to do your own research, e.g. take a look at the bearish view too.
.
Saga (LON:SAGA)
Share price: 270p
No. shares: 140.1m
Market cap: £378.3m
(I hold - Paul)
Saga awarded industry-leading accreditation
This is quite an important announcement, because worries about covid, and cruise ships, are key to the valuation of Saga, since it owns 2 brand new mid-sized cruise ships, which cost roughly £300m each (funded by c.13 year ship loans, costing about 4.3% p.a. in interest). Therefore the share price is highly leveraged to the resumption of cruising.
If you’d done your research, then you would already know from the recent presentations, that extensive work has been done by Saga to make its ships covid safe. Remember it's not just covid. Other outbreaks of viruses are quite common on cruise ships. Floating petri dishes, as they are sometimes described! Saga's 2 ships are brand new designs - e.g. all cabins having balconies, and fresh air ventilation systems (not recirculated air) are key advantages.
Here is today’s announcement in full, which is self-explanatory -
Saga awarded first industry-leading COVID health accreditation
Saga has become the first cruise operator to be awarded new COVID-19 health assurance accreditation by Lloyd's Register, the maritime safety experts. The move is a crucial step ahead of the planned return of cruise operations in spring next year in a COVID-secure environment.
Lloyd's Register has awarded Saga the Shield+ accreditation, the highest category of health assurance they have. The new framework has been created to reduce risk and provide greater confidence in the safety procedures of operators against the introduction of infectious diseases onboard cruise ships, including COVID-19, Norovirus and common flu, as the industry works with government to restart an industry that employs 88,000 people and is worth £10bn a year to the British economy.
Being awarded the accreditation demonstrates that Saga exceeds the compliance criteria in every category set out by the UK Chamber of Shipping in their guidance for COVID Secure Cruising, which has been supported by the government.
The safety accreditation is assessed against six key categories covering every aspect of ship safety where health risks are elevated: medical, policy, food, ventilation, accommodation and water.
Award of the accreditation follows months of detailed planning from Saga, designing and putting in place detailed new procedures to meet the highest standards of health and safety. Saga's ships have been surveyed and inspected in all key areas and the accreditation has been awarded for both the Spirit of Discovery and the Spirit of Adventure, Saga's brand new ship, which is due to set sail for the first time in May 2021.
My opinion - an important announcement I think. As mentioned before, demand for cruising is not the problem - customers are itching to get going again, and forward bookings are high. It’s just a question of when they will be allowed to sail. Saga’s website says they’re looking at April to May 2021 to re-start, which ties in well with what the Govt, and other companies are saying - i.e. there should have been good progress in vaccinating the elderly by then, we hope.
As well as being positive news today for the safety of customers & crew, it’s also clearly a significant marketing opportunity, to trumpet that Saga’s ships are best in class for health & safety.
Another important marketing advantage that Saga has, is that it’s changing over to putting customer funds in a completely segregated account, i.e. there is no risk to customer deposits in the case of insolvency. Therefore Saga is also in a position to give cash refunds immediately to any customer that wants them - key for reputation & customer service. Given how problems are emerging with customers struggling to get refunds from some other travel companies & airlines (e.g. being pressurised into accepting a credit note instead of cash), then I see this as being a key advantage that Saga can capitalise on. A slightly stuffy image could be a big plus, when other sector companies may be struggling with solvency.
For investors who are prepared to be patient, then I think there could be a serious re-rating on the cards here, once the ships are earning their keep again. In the short term, maybe it needs to pause for a bit, as we had a spectacular rebound on the covid vaccine news, and I suppose it’s inevitable that some holders might want to bank a short term profit. There’s an institution selling down too (see holding in company RNSs recently). Having strong nerves, to get through the recent irrational low, certainly helped!
The price volatility doesn’t bother me, as I focus on the medium to long term with nearly all my holdings.
.
Loopup (LON:LOOP)
Share price: 92p (down 41%, at 10:32)
No. shares: 55.4m
Market cap: £51.0m
(I hold)
LoopUp Group plc (AIM: LOOP), the cloud platform for premium external communications, provides the following trading update.
I read this announcement first thing, and thought it didn’t sound too bad. How wrong I was! The price has taken a battering this morning, and bottomed out c.77p. I also note that there has been huge volume printed already, in a normally illiquid share, 8.1m shares, or nearly 15% of the company, probably with more large trades yet to be printed (as bigger trades can be disclosed on a deferred basis). That looks like one or more institutions bailing out.
Previous updates from LOOP looked fantastic, which was why I picked up some shares in it between July and November this year. My average buy price is now 173p, so am currently sitting on a very unwelcome 42% loss. It happens. Small cap investors need to get used to profit warnings, it’s an occupational hazard. Keeping a clear head is vital, to avoid compounding errors.
What to do, buy, sell or hold? Well I’ve already picked up a few more today, which is usually a rookie error of catching the falling knife. Sometimes I just can’t help myself! To put it into perspective though, the total position is only about 1% of my portfolio now. I’m mentioning this, because it might cause unconscious bias in what I write below, but hopefully not.
Here are my notes, summarising today’s profit warning -
- Previously stated that unstable market conditions made guidance challenging
- Core business PS (Professional Services) has “continued to trade robustly versus pre-pandemic levels”
- Strong momentum in Cloud Telephony business since July 2020 launch
- Remain confident in growth prospects for the above
- Non core business seeing accelerated churn rate - due to greater competition - but this is only 14% of revenue
Revised guidance for FY 12/2020 -
In light of this, the Group now expects FY20 revenue to be no lower than £50 million (c.18% growth on FY2019) and EBITDA to be no lower than £15 million (c.134% growth on FY2019), moderately below current market expectations.
That’s hardly a disaster.
However, it looks as if 2021 revenues could be lower, although I’m not sure how ARR would compare with actual revenues?
The Group's annualised revenue run-rate (ARR) currently stands at c.£34 million, made up of c.£28 million of LoopUp Platform capabilities (Meetings, Cloud Telephony and Event) and c.£6 million of Cisco resale, which represents an estimated entry ARR for FY2021 trading
Some KPIs are then produced, which show that the business seems to be sharply diverging, with PS doing well (compared with pre-pandemic), and but non-PS doing badly. I think what this is telling us, is that the non-PS business is falling away, due to competitive pressures, but PS business (the core business) seems to be doing OK, or well even. Hence it looks as if LOOP is becoming a top end, niche player in the market.
Our decision to focus our strategy on PS sectors remains the right choice, demonstrated by the increase in demand for LoopUp Meetings in those verticals. Looking forward, our priority is to cement and grow the strong position we have built in our core PS market, where external communications are business critical and warrant a best-in-class capability.
Cloud Telephony - detail is provided on why management is optimistic about this new service. It says the sales pipeline for this specific product has grown rapidly, up 68% to £84m total contract value - sounds interesting, but a pipeline is just that, it’s not actual sales yet. Sales cycle is expected to be 6-8 months. A private banking group is trialling (for 3 months) the product globally from next month. This all sounds potentially interesting.
Outlook & cash position -
While trading is expected to remain challenging in the non-PS part of our Meetings business, this now represents just 14% of our total LoopUp Platform revenue, and with a continued focus to drive forward our PS business, it is expected this will have progressively less impact on overall trading going forward.
By contrast in our core market, we remain confident in our ability to drive attractive, sustainable and profitable growth of our premium external cloud communications platform, and therefore plan to invest to maximize growth and shareholder value creation within the constraints of our strong £11.6 million cash balance (at end October 2020).
That sounds like costs might be increased. Hmmm.
The cash position is is misleading, because the company fails to mention its bank borrowings, which were £13.6m as at 30 June 2020. So if we assume that borrowings might be unchanged now, then the £11.6m cash balance is actually net debt of £2.0m. Modest, so it probably won’t be a concern. But I would have preferred clearer disclosure (unless I missed it, in which case I'll happily correct this article).
Broker downgrade - there’s been a savage downgrade from Numis, which likes to keep the facts away from private investors, so that institutions & HNW individuals only get privileged information. This is totally unacceptable, given that the broker gets its information at least in part, directly from the company. Therefore house broker notes really should be publicly disclosed. This issue really annoys me, as it’s so blatantly unfair, why is it allowed?
Everyone should see the revised forecasts, for a level playing field, so here they are;
FY 12/2021:
Revenue forecast reduced from £55m to £35m
EBITDA forecast down from £13m to £6m
PBT from £5.8m to £1.3m
2021 cash outflow of £3.5m, vs previous forecast of £3m inflow
My opinion - I think there’s enough positive stuff in the update to motivate me to continue holding, or maybe even buy some more, given that the core business is doing OK. There seems little doubt that LOOP enjoyed a bumper period during lockdown 1 that’s not likely to repeat. So I can see why some investors would want to bail out.
That said, the high end (Prof Servs) side of things seems to be doing well still, and I like the section about cloud telephony premium services, integrating into MS Teams.
Overall, I’m leaning towards holding, because it doesn’t look as if solvency would be a problem (LOOP could cut costs if necessary). A £50m market cap could make it an acquisition target possibly? It’s not an enthusiastic hold though, so I can’t really say that I’m positive about this share, neutral and too stubborn to sell, is probably more accurate. However, on reading the RNS again, it's made me want to buy more! Therefore "genuinely perplexed" is probably my overall view on this share at the moment.
.
Reach (LON:RCH)
Share price: 149p (down 3% at 14:51)
No. shares: 312.1m
Market cap: £465.0m
Reach plc is today issuing a trading update for the 52 weeks ending 27 December 2020, covering the period from 29 June to 27 November 2020 ('the period').
The headline says -
Digital momentum drives performance ahead of 2020 market expectations...
Strong digital growth, resilient circulation
I’m surprised the share price hasn’t risen today, but it’s had a spectacular run recently, and the rest of the update does sound some notes of caution. As you can see, it’s tripled in price since August;
.

.
Digital is growing, and print is falling fast. I do wish they would put the actual numbers in a table, rather than giving percentages;
Overall Group performance has exceeded market expectations, with continued strong digital revenue growth of 16.2% for the five months to 22 November 2020, assisted by increased customer engagement.
Circulation sales have remained resilient despite the recent lockdowns, supported by management action on availability and increased cross-promotion of national and regional titles. Overall, for the five months to 22 November 2020, a decline in print revenue of 19.6% contributed to a Group revenue decline of 13.9%.
Assuming that print, and digital, are the only two categories of revenue, then we can work out the split, which drops out as follows;
Last year
Print revenues 84.1% of total
Digital revenues 15.9% of total
This year
Print revenues 78.5% of total
Digital revenues 21.5% of total
If my spreadsheet has worked out the figures correctly, then on this year’s forecast revenues of about £584m, it looks as if digital revenue might be around £126m this year - a significant sized digital business then. Although I would like to know the split of profits between the two divisions. There are likely to be a lot of shared overheads, so that might be difficult to calculate.
Costs - are being constantly cut, over many years now. This means an improved operating margin, vs. H1, impressive. Further cuts are in the pipeline, with consultation started on possibly closing 2 of 6 printing plants.
Customer sign-ups look impressive, this is on the digital side;
Customer registrations have now exceeded 4.25m, and the company is on track to deliver the 10m registrations it is targeting by the end of 2022. Reach retains its leading scale audience in the UK with 42.1m unique monthly visitors accessing its sites during October.
The idea seems to be to accumulate information on each customer, then sell more targeted & expensive advertising to them, like a mini-Facebook. As the bulls point out, that could be very valuable, if it works.
Cash & cashflow are described as strongly positive, and healthy, respectively.
My opinion - no strong view either way. I can see the merit in the bull case, with RCH becoming potentially a valuable digital advertising platform. Although digital marketing experts have told me that the ROI from advertising on Facebook and Instagram is so much higher than anything else, that these are the only platforms worth using. Facebook/Instagram can apparently localise ads right down to individual postcodes, so I'd need some convincing that Reach can beat that.
However that needs to be offset against the newspapers gradually withering away to nothing, in the coming years. There’s then the negative value of the pension schemes, which look fine on an accounting basis, but could be eye-wateringly large on the next actuarial valuation (apparently it was over £700m last time, and interest rates now seem near-zero permanently, maybe even turning negative?). It depends whether the pension scheme assets have gone up enough to offset the increased liabilities caused by ultra low interest rates? This matters more than ever, because it’s looking more likely than ever that interest rates could be near-zero forever. Therefore the pension deficit is not likely to just melt away, as they have done in the past.
At this stage, I feel RCH shares are a leap of faith, that the digital business could become worth a lot - i.e. over £1 billion. It would need to be, just to justify the £465m current market cap, plus the maybe £500-1000m pension deficit (actuarial), and writing off the newspaper business as worthless in the long run.
We’re not given the information we need to value the digital business. I think the company needs to start reporting them as 2 separate divisions, with a P&L for each division. Only then could we meaningfully value the shares. Until that happens, then it’s largely guesswork in my view.
It’s a good story though, which has caught the imagination of lots of investors recently, as the chart above shows!
.
That's it for today. I hope you have a lovely weekend, and looking forward to seeing you again here next week.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

241 comments
Best wishes to Paddy, he looks a tough little terrier!
It could be alleged that NUMIS note to selected clients helped destroy LOOPS share price at the opening (dropped from 155 to 110 instantly).
Trades were going through at one every three seconds (18.7 per minute) speed during the first hour which is at Flash Guys direct access speed and swamped. the market. Normally brokers notes, issued under embargo, are released to the press the day before, Fair practice is RNS officially released at 7.00 am along with notes becoming unembargoed
Break down of Day by the hour
Deals
Deals
Sum of
Sum of
Sub Set
per min
Volume
Value
Inst Values
Hr 08-09
1,083
18.05
7,210,151
£6,162,006
£441,940
Hr 09-10
422
7.03
2,329,730
£2,124,923
£350,877
Hr 10-11
385
6.42
2,286,928
£2,133,701
£341,241
Hr 11-12
233
3.88
1,566,794
£1,387,797
£220,702
Hr 12-13
248
4.13
1,794,928
£1,544,352
£59,990
Hr 13-14
153
2.55
698,758
£602,215
£165,065
Hr 14-15
204
3.40
1,884,621
£1,625,373
£127,950
Hr 15-16
379
6.32
1,992,548
£1,579,110
£100,516
Hr 16-17
238
7.93
3,265,847
£2,471,812
£690,640
Late deals
-
-
1,376,092
£1,091,017
£0
3,345
-
24,406,397
£20,722,307
£2,498,921
First hour trading is usually the busiest of the day but a deal every three seconds is often close to what is considered the limit.
Sub set of values is for Negotiated Deals which are those associated with institutions which can be used as a normal pace for dealing. These were 160 out of 3,340 of all varsities. All the trades were “Off book", not through Direct Access
Median size of individual trades was £5,750 whilst only top one percent of trades were over £49,000 value (roughly £1 million total value). NUMIS note to selected clients painted the picture for instant share price collapse taking advantage of institutions and blind-sided private investors in my opinion.
re: Loopup (LON:LOOP)
Where's the Moat?
other than client inertia, I'm struggling to see what the competitive advantage / niche is. The other providers could easily roll out a premium security enhanced offering and could afford to undercut Loopup (LON:LOOP) indefinitely. Takeover is a possibility but doubt any big player would overpay as they could develop their own product easily.
Interesting stat for the weekend that the Tesla valuation now exceeds that of Berkshire Hathaway ! - I know it won’t happen but it would be hilarious if musk used the high shareprice of Tesla to make an offer for BH - Buffett is getting on a bit after all and the decent cashflow and cash pile of BH would certainly come in handy for musk.
For anyone who is interested but who hasn’t looked recently the new Tesla Full Self Driving Beta mode really is a step change in the march towards full autonomy - plenty of demos on you tube if you type in Tesla fsd beta.
Re Reach (LON:RCH)
Hi Paul,
I think it's a mistake to think that the print and digital sides can be separated. Any attempt to do this accounting wise would be dominated by the cost apportionment policy. Probably, assigning costs to digital would make it appear loss making unless the business development costs were capitalised.
Far better to regard them as two sides of the same coin. People look for the sites because they know the print papers.
Essentially what the company is doing is investing some of the cash thrown off by print into a digital business that spreads the necessary costs of that business over a larger income. If they find a cost effective purchase of other print newspapers, they'll buy those as another way of spreading costs.
There are three big factors determining the actual value of the shares: when will the pension fund become self sustaining and how fast will it get there; when will the print business need to be closed to avoid losses, and how much profit will it produce before then; and what will the residual be worth when all that's happened. One of the things that have changed over the last few years is that there may be a significant value in the residual.
Re: Boohoo (LON:BOO) - seems The Guardian is not ready to hand in the towel just yet:-
https://www.theguardian.com/business/2020/nov/27/critics-slam-pretty-little-things-8p-black-friday-dress-deal
Don't suppose any/many Guardian are potential customers anyway otherwise I'm sure they'll all be logging on to PLT website to stock up for Christmas
Hilarious! They're pretty thick the Guardian writers, aren't they! They don't understand marketing, loss-leaders, LTV of clients once you've surprised & delighted them with an initial offer, etc. Just plain thick.
Wait for the next BOO trading update. I'll eat my hat if it isn't good to very good.
Guardian readers want expensive recycled hemp. BOO is giving people on a low budget what they want - affordable fashion, excitement, fun. Let the snobs carry on with their virtue signalling - nobody cares. It's just like telling poor people in India that they can't have cars or aircon, as it will hurt the planet. Whilst the people lecturing them from the West, enjoy those things routinely.
Hypocrisy. It makes me sick.
Regards, Paul.
Without this article and the comments it generated here, I would never have gone on to the website to find a bargain. I ended up buying 5 items (I have teenagers) with an average 40% discount. No 99% discount for me. I would love to know how many Guardian readers actually logged in to take advantage of the discounting. Not sure it was that many, but nothing would surprise me. I actually think this was free advertising - it worked on me. So, thank you Guardian for making me aware and for bringing in more sales to my wonderful company. ;-)
Wow 5 teenagers and presumably all girls Mark. There must be at least one pair of twins surely. You certainly have an excellent opportunity to DYOR on Boohoo (LON:BOO) and PLT with a family like that!
Does anyone have access to the Progressive Equity update today on Loopup (LON:LOOP) ? I can only find the below synopsis on their website and annoyingly nothing on Research tree yet.
LoopUp has published a trading update detailing a modest miss for FY20, but a materially lower-than-expected run rate as the business moves towards FY21. The shortfall is attributable almost entirely to a faster-than-expected and more dramatic decline for the LoopUp meetings product in sectors outside the core focus Professional Services segment. We make reductions in estimates to reflect this revised outlook – clearly this is disappointing, but there are a number of positives within the parts of the business likely to drive long-term value.
It is there -5 pages - you need to click on 'Download' under the para you have printed
UK_Investor closes the week, a little crest fallen, at exactly the same closing value of this time last week, £3K short of the special fund manager's club.
On Tuesday, I hit an all time high +5.1% on tonight's close, a significant sum.
I chose to HOLD, accepting the retrenchment, but expecting higher in the future.
Question for the experts:-
Is there a way to duck out at the peak, grab the capital?
There's a number of problems with this: we don't know when the rally fizzles out, when the rally exactly resumes.
And a personal reluctance for me: every sell creates Capital Gains accounting paperwork, bureaucracy, and more complex affairs, and time lost, and the possibility of more mistakes.
And to be "out" in cash means you then need to manage the cash and retime buying in.
Is it better to trade rather than invest-long?
You never included NRR in today's report after you ran out of time yesterday.
We all want more of Paul's inputs sometimes we just have to a accept he has run owt of time
True. I didn't get round to covering NRR today or yesterday, because there were more important things to cover. I'll look at it when I can.
There were some quite tricky things to cover today - e.g. both LOOP & RCH took a lot of time to unpick & work out what's going on.
I'm more frustrated than you, that I couldn't get on top of the backlog, having worked flat out since 6:30 this morning.
An incredibly unhelpful comment from you.
Great work this week Paul (& Jack) thanks for all of your efforts.
I wouldn't lose too much sleep over the very few who find reasons to be dissatisfied.
Have a good weekend with Paddy.
Thanks Gromley! It drives me mad that I bust a gut all day, most days, and some d@#khead comes on here and complains. It makes me want to just throw my keyboard at the wall, and walk out.
Thankfully, the feedback from everyone else is amazing, who do appreciate my hard work. The boss, Ed, suggested I print off the best feedback & put it on the wall, to remind me that most people do like my work & find it useful.
We're all human. I'm not here as a punchbag for someone who's had a bad day & wants to lash out, usually due to their own inadequacies. So they can get stuffed!
Anyway, let's relax and have a lovely weekend. It's very stressful doing this.
Best wishes, Paul.
Paul - you do a great job and many readers KNOW that. Love to your doggie for a speedy recovery !
Paul, I suspect there is a large group of people who (like me)are normally silent readers of your writings on Stockopedia who always look forward with keen anticipation to reading your contributions. Perhaps a thumbs up and thank you from us might go some way to balance any unduly negative comments here :)
I suggest that you ask Ed to take the hit and give him his sub back. Then ban him/her from signing up again! :o)
These reports are Best endeavors level as far as I'm concerned. We as investors should be doing our own homework on companies. These reports are an additional resource. I suggest the subscriber should apologise if they want to remain or clear off if they don't.
Paul, Jack, thanks for all your work this week. And the long hours you put in. I’m for ever grateful if time is found to cover stocks I may hold or be interested in, but as we all should know, the SCVR is not an on-demand service!
Glad to see Paddy on the mend
For all the criticism Paul you have made many silent friends out here who value what you do and respect you as a person and the standards you live by.
Evening Paul +236 thumbs as I reply says it all.
Darts players go nuts for one huuuunnnndreeed and aaaaateee!
Just keep doing what you do YOUR WAY
Paul, with regard to your comments on advertising, Facebook is amazing in that they can target not just people in specific post codes but also those with particular interests. If I had something appropriate to sell, you might receive from me an advert perhaps directed at the owners of small dogs in your location! Having said that, not everybody has Facebook and I find that a lot of those who do have an account do not use it all that often after the novelty wears off. The other point is that it can be very expensive to advertise. I think it is good for those who are going to obtain repeat orders without further adverts. The customer acquisition cost is then spread over the period the customer is retained. Without repeat orders you may well find that the only people who make any money are Facebook. The same applies to Google but more so.
So what I am coming around to is that I think there will always be various ways of advertising and I don't think Reach are aiming to rival Facebook! It is going to be down to the management but they have the basis of a great business. I did say yesterday that the price had got ahead of itself!
Apparently, BookFace has shadow accounts to track none Facebook users. There is some debate on whether attributes from their ubiquitous Whatsapp purchase is also used to cross match "marks".
I don't like The FAANG companies. There are too many underhand and dishonorable business practices by all of them. (Share ownership is a different matter.)
LoopUp (LON:LOOP)
shares magazine has a little article on loop today
https://www.sharesmagazine.co....
Unfortunately the 2021 numbers quoted in this article are even worse than the numbers mentioned by Paul earlier, there is mention of Numis though so i have to admit i don't have the foggiest if shares mag numbers are a different broker or may be wrong or what is going on quite frankly.
Anyway the numbers for 2021 quoted by this article are as follows
2021 revenue of £32 mill
EBITDA £6 mill
Loss of £1.3 mill - or as they put it "1.3 million hole"
"that where a £5.8 million pre-tax profit was meant to be, a £1.3 million hole will now sit."
Perhaps someone has been on the funny stuff when copying and pasting these numbers as it looks like the numbers equivalent of 6 year olds playing chinese whispers.
Hi doublelutz, Paul or others will correct me, but I had read the Numis note to also be forecasting a net loss of £1.3m for 2021 (re Loopup (LON:LOOP)).
Loopup (LON:LOOP) I picked some up today (probably wrongly) but I'm scratching my head at the falls.
The broker has slashed revenue expectations for next year to £35m but the company say they already have an ARR of £34m so the broker is saying that the business will add just £1m new business in the whole of 2021 !!
Really? That doesn't make sense and seems completely at odds to the statement made by the company. So either the broker is deliberately guiding expectations lower on the basis of being able to upgrade later as the business outperforms or the company statement is disingenuous. I don't know what to make of that; Neither is particularly palatable behaviour so maybe I shouldn't be in this stock after all. Or am I missing something?
I also bought some Loopup @ 78.5
David I'm a disinterested observer but do you really understand the company's business, how it makes money and its balance sheet? It cant have lost half its value without a reason. That may make it cheap or at least cheaper than yesterday.
I don't understand either why the LoopUp (LON:LOOP) Group revenue is 32% down but the stated reason for this is due to a 32% drop in revenue in the non PS division but this represents only 14% of the Group?
One thing to note re. Loopup (LON:LOOP) - is the Quality Rank of 82. If you remember our profit warning research from a few years ago...
You can get a copy of the Profit Warning Survival Guide here.
It’s funny Ed - I reread that guide a few weeks ago as someone flagged it here. The bit that has been playing through my head is the chart right at the start, showing how prices begin decreasing before the warning comes out. I can’t help thinking there should have been a warning in there for me as I have been gleefully filling my boots (as Paul would say) as the price decreased over the past few weeks - hohum
Loopup (LON:LOOP) - warning signs - it was in an 'ascending triangle' looking nice for a breakout and then dropped out. No reasons, no news, but if a trend does not work out then have to accept it and move on. Pfizer news muddied the waters. I sold 50% before the fall, so reduced the paper loss. Had Centamin not so long ago as well - you can expect that from miners but this thought was a bit more robust. But contributors have noted its a very competitive space some IT purchasers had not even heard of Loopup - so hindsight.
Mcro seems to have done quite well recently on the recovery front. I have a PIA that routes me via Melbourne although I live in UK. I was amused to get loads of Australian adverts including one to sign a petition to ban shorting in Australia. In MCRO's case shorters did me a massive favour I think as it has risen about 80% from recent lows. Its ranked around 50 in quality and a good example of Ed's theory about how shorting can help slow the demise of an SP whilst flagging up problems. I do find it hard to believe that without city packs of hedge funds aided by thousands of tiny BOT trades would have got MCRO as low as they did (sub £2.00) and thats after persistent director purchasing over the year. I didn't really look at Saga until I heard Sir Roger was interested in sorting them out. Again shorting may have been responsible for slowing the rate of fall, but former Aiva boss's effort to snatch the company away for presumably an unfair price and the subsequent panic by institutional holders left it vulnerable to shorting.
MCRO's woes seem to stem partly from the Autonomy/Hewlet Packard takeover, with a court case still going on years later. Would have thought the buyer beware clause would have prevailed by now.
Saga was hit by specific events such as the Thomas Cook collapse (twice) and a cessation of cruises related to COVID and years of inept management.
Not sure what Loop's excuse is, but must be more than just a fear of an end to COVID. I think its lack of size is attributable to the rate of fall as anything, and therefore lack of liquidity.
Anyone know if the six managers from the Halifax have finished their jail terms for shorting their own bank and back on the rampage yet? I thought lots of banks shorted themselves. I know shorting has been around a long time but I don't agree with it, and I suspect BOT trading has a lot to do with how it can be manipulated and used to unfair advantage. Its not right.
thanks Ed... very useful!
Hi Paul, I hope Paddy recovers well.
Best regards,
Andrew
Anyone know why Flowtech Fluidpower (LON:FLO) has risen more than 14% today? Is it just some kind of rotation into value stocks? I don't see other value stocks going up like that though.
"Anyone know why Flowtech Fluidpower (LON:FLO) has risen more than 14% today? "
I was asking myself the same question. It looks like a tipsheet - very quiet with 10 trades up to 10 40 then nothing until 12 38 when an explosion of trades - 164 from then to close.
I am more worried that we have not had a Q3 trading statement, which has been issued towards the end of October in the last 3 years,
Re. Loopup (LON:LOOP), a part of the market that I work in every day.... the profit/revenue warning here is described very openly in the trading update. I sometimes think that companies are punished disproportionately for being direct rather than padding things out using management speak.
My own experience is that far more of the value of a business like this is embedded in its customer book than in its technology. Customers are very resistant to switching from one form of communications technology to another, even if the alternative is both cheaper and better. Switching carries both risk and significant user adoption costs, and these mean that once you've won a customer you are likely to have them for a long time.
For example, landlines have been a legacy technology for nearly two decades (in that there are cheaper and better alternatives available to both PSTN and ISDN in the market). But customers still kept on using them and paying for them nonetheless. Even now, with the withdrawal of PSTN services being communicated to the marketplace by Openreach, the rate of migration away is surprisingly slow.
For this reason, I worry relatively little about things like whether Microsoft will offer a competing technical solution for outbound and inbound voice integration. They might do so, but that doesn't mean that the customers will instantly switch to it. I would value the business based on the future free cashflow available from its customer book, plus or minus its new customer acquisition costs and churn.
You say that customers will remain sticky because of the cost/effort to switch.
But that's exactly why Loopup share price is declining - as is Zoom - Microsoft's Team app is very good and has most of the capabilities of these dedicated platforms, and will only get stronger. And Microsoft Teams has much lower cost. If senior management and finance in a company wanted low hanging fruit of cost savings to be made, switching from Loopup to Teams would be it, and IT would just be given an edict to get on and do the migration.
Plus, the migration wouldn't be too onerous, as the infrastructure for Teams is built on the MSFT platform (Outlook, Sharepoint, etc) which many companies use anyways!
The fact that Loopup is highlighting they will pivot to a telephony solution that integrates with Teams.... yes, they might still keep their PS customers, but they can only charge for the telephony services, no longer the web/video services, and revenue/customer will decline over time.
Loopup (LON:LOOP) My situation and reaction is similar to yours Paul. Perhaps naively I feel there is a reasonable chance the MS Teams hook-up could be a huge winner. It's effectively a switch that allows Teams to use high quality comms and voice for important conferences. Once available, people in the corporate space will find it hard to carry on with volatile voice and frozen images.
On your related point that price sensitive facts should be available to the public at the same time as institutions, absolutely! I have no problem with institutions and HNW's paying for exclusive professional opinion (indeed welcome it!) but PI's must be allowed onto the same playing field.
I'm no expert in Unified Comms (I do desktops) but I thought the video channel was seperate to the audio channel. In that I thought Loop was only necessary to enable dial in / dial out services via phone lines. Microsoft have a huge amount of core networking and dark fibre capacity and I don't think Loop do anything to improve that, once you're in the Teams meeting I thought everything was routed / processed through MS datacenter the only thing that isn't is the routing too and from your location to the ISP and then onto the datacenter. Loop provide a route from the public phone system into / out of the datacenter if you don't have an internet connected way in. Happy to be educated.
Loop up offer both voice and video conferencing as integrations with Teams. So, when you do a video conference with Teams you end up using the Loopup infrastructure for both voice and data.
this isn’t really an advantage when all users are in the same country/geographic area, as the weakest link is the internet connection from a user to the data centre. But it is an advantage If the users are spread around the world, where the connections between datacentres matter more.
Which is why they tend to be more successful in industries like law firms, accountancy companies and consultancies that often operate internationally.
Of course, that doesn’t mean that Microsoft can’t and won’t compete with them, but it does mean there is a distinct niche in which being Microsoft isn’t enough on its own to guarantee success
I doubt this is true. I'll ask around at work. Thanks for replying, I'm open to being wrong.
I should have been a bit more precise... the two integrations (voice and video) are available separately. In product terms they are described as Cloud Communications and Remote Meetings. So,
- its possible to use Loopup Voice within MS Teams whilst using Teams conferencing for video.
- but if you choose to use the remote meetings product as an integration with MS Teams, you will use the loopup infrastructure for both voice and video.
If you are particularly concerned about security on conference calls (e.g. lawyers, investment banks, police/security) then the first option requires you to implement consistent security controls across both Teams video and a third party voice direct routing solution. The second option doesn't, as you are using the same solution. Both options are possible technically, of course, but there will be customers will prefer to have a single provider who is responsible for both.
Ok, that makes sense. All Teams traffic is going to be certificate backed so I'm not sure what extra security you're going to get offloading that capability. One assumes the Remote Meetings are going to use identity Single Sign On, the tenant is still going to be operated by a third party and your team still need to administer a solution - I personally can't see any benefits in Remote Meetings over native Teams. Especially as the security controls for identity and access are (usually) monitored in real time against emerging threats by Microsoft, and frankly, you'd be ludicrous to not let them or a serious dedicated third party (with massive real time, automated monitoring and data gathering capabilities) do it. I suppose there might be some argument for saying "our IT team is so small we don't think they're well placed to manage identity and access" but if that is the case, one has real problems with more than just meetings security. Maybe I'm missing something as I don't do UC, but I do work as a consultant for a major player assisting with desktops across multiple industries that care about security, and have provided services to all the industries you mention so I'm not completely naïve. But I have stated many times, my industry knowledge might be working against me for both Loopup (LON:LOOP) and Intercede (LON:IGP) .
For voice, security isn't going to change, people dialling in from a public exchange can be eavesdropped and there's little to no certificate based protections.
More importantly I doubt if MS would ever want to be on their own in this space. Just isn't worth their time.
As someone from the industry, at these levels, if I may ask, what is your opinion of Loopup (LON:LOOP), Kevin?
I'm not sure, to be honest. My instinct is that the sell off has been overdone and this could be a good time to buy.
But my instinct is an unreliable, emotional moron and I've learned never to do what he says without giving the thinking part of my head time to research the situation properly. Which is what I'll be doing this week before making my mind up!
as a further addendum to this. After having had a bit of time to reflect and review the annual report and the trading update, I've decided to have a dabble. The free cashflow generated from the existing customer book combined with the annualised growth over the last 5 years make the current price look compelling.
One point that came out a bit more strongly once I'd looked at the customer acquisition cost numbers was the fact that Covid isn't that strong a tailwind or headwind in the professional services market. These customers already made extensive use of remote working because the nature of their operations are international.
Good reading as always. Thank you.
Any thoughts on Motorpoint (LON:MOTR)
LoopUp (LON:LOOP)
Excellent analysis Paul - as you say its all about the 2021 numbers that are only really accurtaley estiamted in the broker note that is not made publicly available. Should shareholders not fully castigate the company directors if they are giving a nod and wink to brokers that next year profits as of today are expected to show a 75% decrease compared to the day before without explicity mentioning this in the formal news released today! Obviously if the brokers are independent and make up their own numbers thats not of the nod and wink variety but i would start from the default that it is all a bit of a nod and a wink. Based on the 75% expected reduction in profits expected next year its reasonably clear why the price is down so much and there is an argument that the fall is deserved - that info based on what the company released not so easy to compute sigh.
One other item to mention is that the trend in direction of shareprice is starkly clear well before todays date - have the directors been caught sat twiddling their thumbs when they ought to have updated the market sooner that trading was taking a turn for the worse? I am not particularly a believer in mystic tealeaves but i am a believer that unless companies are 100% on the ball its easy for info to leak out that has not formally been announced. I would guess teh volume and trends ref their billing and the like would be starkly obvious to the most junior member of staff in the finance team that had access to the numbers coming through.
Quite interesting that Arcadia are rumoured to be going into administration. It's telling that they need £30m yet the Greens are not paying it.... I think its inevitable that it'll end up disappearing.
Could this yield more brands for Boohoo to buy? Not sure that the likes of Burton are trendy enough any more or even if revitalising them takes away customers from their own offering.
Dotty P probably has some value.
And, it's not just the brand that is of value - the CRM database has value of its own.
The only brands that really made money were Topshop, Topman and to smaller extent Dorothy Perkins. The first two still have some brand credibility. DP sits in the space Sosandar (LON:SOS) are pushing into, so you could see it as a credible bolt on but one that’s outside both BOO and ASOS’s base.
Well, Topman (I'd forgotten about them) might make an interesting more upmarket BoohooMan. One of the lads I work with came in with a BoohooMan shirt to work and I didn't think it was good enough for that function. Throwaway shirt for a Friday night, fine but professional environment, not so much - it was only £8 or something though. So maybe there's a market there, better quality shirt for £15, under cut the likes of TM Lewin - probably not as good quality as them but good enough for your junior office worker just starting out without them looking like a scranbag.
I see the workplace of today rarely matches that of when I was a young lad in the city, and I'm still 40. No one I know these days buys Lewin and increasingly, people are buying shirts for an occasion or season and binning them, which actually makes me think that there is a lot of untapped value in BoohooMan, especially if they can start to appeal to the older, ex topman crowd....
Totally agree. Even in City offices, sloppy dress is a daily common event amongst man. Esp women. I am female.
Man is many....
Hi Paul, first of all great to see Paddy up and about, it's always a worrying time when our four legged friends are unwell! Many thanks for your insights as ever, always enjoyable to read. I don't usually comment or make a request and I know you aren't too keen on them but could you, or maybe Jack, take a look at Morses Club, (results and annual report out today)? Many thanks,
Nick
An interesting statistic in the Personal Assets Trust newsletter. in the ten years to end 2019 inflation was 33% and the return on cash was 5%. If you had kept your money in cash it would have lost 28% of its value in real terms. This is pushing us to invest in more risky investments, particularly now that government bonds have negative interest rates.
What might we learn from this? To remember that our benchmark should be to at least beat inflation on our investment and to manage risk with that in mind, particularly on what PAT calls our 'precious' money - that part of our portfolio we depend on for our current and future needs. In my case my wife's SIPP lost 33% by end March and we haven't got it all back yet.
Return on cash only 5%, really, many instant access accounts were over 1% pa, so how can it be only 5% over 10 years? I was getting rates around 5-7% ten years ago.
That was before the crash, if you remember. But you are missing the point. even if you got 1% you would have lost 23% against inflation. Its just about impossible to match inflation on your 'precious money' without taking on risk and that must be managed. Its useful to remember that in the general euophoria that is accompanying this stock market comeback - which has only retrace half its losses in the UK.
I was getting around 5% pa 8-10 years ago, not just 5% over 10 years, what are these figures based on, bank base rate? Savings rates are higher, especially if you do longer term bonds. Even now I'm getting 0.9% on an instant access account. Yes rates have plummeted in the last year, but even earlier this year it was easy to get over 1% pa.
No you weren't.
https://www.bankofengland.co.u...
Here's the proof. BoE base rate has not been above 0.5% since 01.01.2010. Actually if I could have got 5% on cash I wouldn't have put so much in stocks. But because I didnt and couldn't I, like many others, invested more. For example my wife wouldn't touch stocks until all return on cash disappeared. Her first investment was Fundsmith luckily.
It does not prove anything apart from the base rates, I had some long term investment, I got some good rates. Some I took out before 2010. 5 year bond was 4.6% with Birmingham in 2010.
Th is from 2009: "However, the top one-year bond pays 3.75 per cent, with two-year bonds offering up to 4.25 per cent and longer-term fixes paying higher rates of up to 5.25 per cent over five years."
I give up. Cash has underperformed inflation for 10 years and this will get worse. So the only place you can get a return is shares but this can be harmful in a crash. Surely you can agree with that?
Those rates you quoted you must agree are nonsense, bank base rates are not the same as savings rates. I agree interest rates are now very poor. Shares are not the only place to invest money.
Glad to hear Paddy is doing well, Paul
Paul
If Saga is placing the cash received upfrom for bookings in a segregated account, does it not mean that they cannot use the cash in the business eliminating, negative working capital. Isnt the negative working capital part of the investment case for cash flow and higher returns on capital? I have not studied the business model enough to know the answer so appreciate some thoughts.
Hi Yusuf,
In the recent interim results presentation, Saga (LON:SAGA) said that there isn't much difference between the old & new arrangements re their customer cash. Hence going to a fully segregated basis was a no-brainer. From memory, I think it was something to do with bond or card processing deposits being released, if they move to segregated cash, largely offsetting the opportunity cost of not being able to use the funds within the business.
I recommend looking at their results webinar, if still on the website, as it was a mine of useful information.
Regards, Paul.
Here are my heat maps for today (prices as at 12:10am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than the 20d EMA of ATR):
Big movers today in the SCVR world (moving more than 20d ATR EMA against either yesterdays close, or today's open):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many as part of my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria ('T': profitable, low-debt, reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the individual instruments further using the Stockopedia Stock Report.
How (or indeed if) you use the heatmaps is up to you, I contribute them here in the hope that others may also find them interesting or useful.
greensiax
To check, stronger shades of blue means more positive?
How do you decide what gets a Green, is that automated?
And out of interest how do you assemble all this data.
Great work though.
Thanks lengthsmen,
Yes the intensity of the blue / red is an indication of the strength of positive / negative sentiment. Green is ‘automated’ in that it’s applied when the instrument passes all my minimum ‘tradeable’ tests (profitable, low debt, reasonable liquidity - i.e. a ‘T’ in the top right corner of the heatmap tile) and has strong positive sentiment.
As for how I pull it all together... lots of research and lots of coding ;-)
Cheers,
greensiax
Can you post a tutorial on how to create them.
Good news on Paddy. Some people think that dogs / pets are as important as human friends....but lots of us know thats rubbish. They are much more important than humans, and the list of reasons why is long - too long ot go into here. So good on Paddy, and good on you. Keep the faith.
I see Ab Dynamics (LON:ABDP) final results are out today, they don't look too good but shares are only down 3%, seems strange given the reaction with some other shares recently and considering the good run with the price doubling since March.
Ab Dynamics may have only gone down 3% today, but it might be worth looking at the chart which shows it has shed 18% this week, it appears the insiders already expected todays announced results . . .
Ab Dynamics (LON:ABDP) Yes I did notice the drift down recently, thought the news was maybe a bit leaky. Shares are still up around 100% from March but profits are down around 50%. I think directors sales/buy might be worth watching in this company.
I'm not currently a holder.
Ab Dynamics (LON:ABDP) announced their results two days ago (25th, 7am)
twiggytwo,
I'm afraid that your post about Ab Dynamics (LON:ABDP) is nonsense. The results came out at 07:00 on Wednesday 25th November. The shares closed the previous afternoon at their highest level since February.
I do believe that you have a basic responsibility to check your facts before posting accusatory messages of this nature.
Hi Paul
Thank you for all your commentary on Boohoo (LON:BOO) over the years. I have never previously owned any and appreciate that buying several years ago would have worked out well. Anyway, today I was finally persuaded by your argument that the valuation is modest and there is a lot of overstated bad news in the price. So have this morning bought what for me is a standard size position in Boohoo (LON:BOO)
Obviously all decisions are entirely my own.
I guess on Loopup (LON:LOOP) looking at the chart it's probably right for it to be trading back at pre-pandemic levels at the moment... looks like revenue is back to pre-pandemic, disappointing growth even in PS and clearly disappointing non-PS
Also a bit disappointed on the cash position they don't point out borrowing as £12m cash balance is a substantial chunk of market cap now but clearly not with the debt!
Did pickup a chunk at 80p earlier simply because the fall looked too big at 50% off and it nearly got back to 100p an hour or so ago before falling back which would have helped with the 'averaging down'! As you say, you can't always call them right just a shame you mentioned at the time this company had disappoined before and has done so again so recenlty after the last positive update. Terrible BoD here. All that said if they can secure new revenues in 2021 then for the sector it is a very cheap multiple but not without risk. [moves to long-term hold part of portfolio!]... tbh though it was always a med-long term hold anyway.
Loopup (LON:LOOP)
As someone pointed out on another board, profit warnings usually come in threes. Plus I remember reading some articles here that said stocks that plunge usually keep falling for a while, so for that reason, only having bought in on Wednesday, I reluctantly decided to sell at -40%. It normally takes months for me to achieve that level of performance :/
Only yesterday I was saying I'd reached an all time high in my portfolio. Hubris is a *****. Serves me right!
"As someone pointed out on another board, profit warnings usually come in threes."
That may be true dependent on region & timescale, but the 'Profit Warning Survival Guide' (published by Stockopedia) looked at 245 UK Small cap profit warnings in the period 2013-16 & observed that profit warnings tend to mostly be one-offs:
https://assets.stockopedia.com...
"profit warnings usually come in threes"
Actually they don't, I suggest you read Stockopedia's article on the subject.
Hi Paul. Thanks for your £boo rant. I bought it before I even knew you existed and it is by far and away my largest position - 37%. I had a few sleepless nights but the data was so compelling, I could not understand why it was so cheap - even with the issues that were in my mind completely repairable. Being of a nervous disposition, I did at times entertain the idea that I was completely bonkers and had made a huge and terrible mistake. Reading your analysis comforted me in the knowledge that I was not alone. For this I owe you your body weight in your favourite tipple if we should ever meet. It would be my privilege sir. I am very thankful to you and your parents to have given me and us the opportunity to read your insights. Long may it continue.
In the most heartfelt possible way, if you really think you are of a nervous disposition, seriously consider whether you want 37% of your portfolio in a single stock. I don't know your personal circumstances or how big your portfolio is relative to your other assets (if you're 21 and have £10k in play money it's a bit different). But do honestly sit down and ask yourself what you would do if the stock gaps down 50% at some point for whatever reason - the market - fraud allegations - whatever - and how you would take it mentally and financially.
Thank you for your concern. All my money in my investments is forever money. I don't need it and have positioned myself to never need it. This enables me to make contrarian decisions of which I think, I am well aware of. I really don't care if the stock market was to close for the next 5 years. I treat my stocks as I would my property. Very long term. If the fundamentals of a company changes or the market price is well above my own valuation, then i will sell. Otherwise, I enjoy buying stuff when it is on sale. I do, sometimes suffer from self doubt which is why I enjoy writing down my thoughts and analysis to read in times where the sellers disagree very strongly by their actions, with my valuation. With respect, I know I think very differently to most people, but my actions have provided me and my family with a very comfortable life.
Again, thank you for your genuine concern.
A valid point. Must admit Boohoo is about 25% of my total portfolio which I appreciate is larger than many would advocate . However, it would not be the end of the world if I lost the lot so it’s a risk worth taking for me. I like to think an educated risk based on my own research and,of course, comments by Paul and others .
I would agree entirely with what EV above writes. I had 45% of my pf in Anglo Asian Mining (LON:AAZ) and Rockrose Energy (LON:RRE) going into March and the drawdown (-40%) nearly killed me mentally and financially. I have somewhat recovered (-7% YTD) but if my portfolio management had been as disciplined as it is (or at least trying to be) now, things would be lot different.
Portfolio management (asset allocation and portfolio weightings) is so important if you don’t want to risk your portfolio blowing up.
The weighting must depend on risk and reward. But whatever your situation in life and however much of your financial assets you have invested in stocks, I would urge you to consider whether 37% of a pf in Boohoo (LON:BOO) is prudent.
I hold 12.5% (so already breaking my new maximum holding size rule of 10% in any one stock) of my pf in Boohoo (LON:BOO) having owned since 2015 at 33p, save for a short hiatus in the middle of this year.
Regards
Michael.
surely it depends what your financial circumstances are.? I have 25% of my portfolio in BooHoo but if I lost the lot it would not affect my life. Obviously I would be unhappy for a short time but certainly would not dwell on it.
Mind Gym (LON:MIND) H1 investor presentation given to analysts and investors earlier this week. Outlines the period (hit by CV19), but more importantly goes into quite a lot of detail on their digital strategy and the commercials going forward. Video & Podcast.
Panoply Holdings (LON:TPX) share price is up 65% following a Midas tip on Sunday, but unusually rather than spiking and retreating, its momentum has continued. H1 results are on Monday. Management are giving an investor presentation at 12 noon (30.11.20). Register here.
On the same link register for results webinars by:
Sosandar (LON:SOS) - Tuesday 1st December, 12 noon.
Creightons (LON:CRL) - Wednesday 9th December, 2pm.
Shortly, we should be publishing results presentations from the week: Ig Design (LON:IGR), Tracsis (LON:TRCS), Calnex Solutions (LON:CLX), Benchmark Holdings (LON:BMK), and a special overview of £RAI. They will all be posted here on SCVR when ready.
Finally, published over the last week:
Argentex (LON:AGFX): H1 presentation
Dotdigital (LON:DOTD): FY20 presentation & overview
Ig Design (LON:IGR): H1 overview
Appreciate we haven't had any educational interviews - it's been a bit busy with results, but we've got a corker coming up on 17th December! Shortly to be revealled (clue here). In the meantime, here's the educational webinar on Silicon Carbide, for those interested in its effect on technology.
Paul,
May I say at the onset, that I value your 'write-ups' on the SCVR and I have made a substantial profits (on paper so far) as a result. I was talking to a colleague re SCVR, and taking 'devils advocate' thought maybe there could always be an element of 'egging your cake' so to speak. With this in mind perhaps when mentioning your holdings you could perhaps disclose specific details ie currently holding in BOO is £x, and I added/sold another £y at a price of £z. Just adds clarity.....Thanks Mate
PS Paddy looks great and hope he gets back to full strength soon
I think you are asking too much of Paul (or anyone?) to reveal his specific share transactions - from a privacy and a time point of view. Personally I would rather he spent his time writing up the SCVR rather than revealing specific details.
Ypu ,night want to delete this.
Why should he tell you this?
Paul recently wrote on his top holdings, down to .1%
Would you like him to tell you every time he goes to the toilet too?
Paul, could u pls also list down everything that you eat as well as the times! ;)
Re: disclosure
Paul said "At 300p I see BOO shares as a golden opportunity, and have personally filled my boots (my largest holding). "
I don't see how we could reasonably ask for more information than this. Our private financial affairs are our own business. A poster recently revealed that he had (briefly) reached a milestone in their portfolio value and told us the figure. That is their choice if they want to share that type of information. It should not be an expectation.
Personally I think a simple (I hold) at the end of a post is enough.
I also think this is a bit much. Paul divulges a lot - I do not need to know how often Paul goes to the loo.
.
how about asking Paul to even place orders for you? Why would I ask someone to disclose his number of shares etc? It's like asking someone how much do you have in your bank account I just wanna know.
Hi voodoobar,
No, I'm not interested in going into granular detail about my own personal portfolio. It would be too time-consuming, and would run the risk of people blindly following my trades - as happens with NakedTrader for example.
I'm primarily a medium to long term investor, so my big positions usually remain in place for several years.
I recently published here a top 10 positions update (with percentage of my portfolio for each one) because I've made some quite big portfolio changes lately, for the first time in a while, which I thought people might find interesting. Am happy to do that again, if there are any major changes in my portfolio.
What I agreed with Stockopedia, when we started these reports 7 or 8 years ago, was that I would disclose for every section, if I hold a long or short position. Then people know if any unconscious bias might be there (although I try to avoid this).
The most important thing, in my view, is that what I write in these reports accurately matches my views on the shares. Therefore, if I'm losing interest in a share, I'll say so! And have frequently done so over the years.
For me, the absolute red line, which I have never, and will never cross, is to write bullishly on a share, whilst selling it. To me that is unforgiveable. People who do that are commonplace on Twitter, and other sites such as advfn, and to me they are just total scum. And people always see through them, because their stories don't match up. Liars forget what they've said, and then contradict themselves. You won't see that happening here.
Sorry your post got lots of thumbs down, that's just people saying they disagree with you, rather than that they hate you! ;-)
Regards, Paul.
Just announced that Arcadia are set to appoint administrators next week - surely a couple of brands Boohoo (LON:BOO) would be interested in? Given the amount of jobs that would be lost if the store estate went though, could be reputationally difficult (and they certainly don't need to be adding fuel to the fire!)
Hi danjamesbaker,
Thanks for flagging the news re Arcadia. What a remarkable situation. It wasn't that long ago when Philip Green sold a quarter of it for £750m. A few years further back, he was king of the High Street, and making billions. Another reminder of how online fashion has crippled the High Street.
Also, I feel that Green's bullying/arrogant style slowly kills his businesses, because after a while the good people get fed up with being disrespected, and move to a competitor.
That said, if you stand up to him, like all bullies, he respects you. He's also hilariously funny, in an un-PC way. I worked on an abortive deal with him about 25 years ago, and as I left the room he whispered to me, "If ever you want a job, call me first!", which I was very pleased with, and used it as leverage to get a pay rise from my existing boss!!
Regards, Paul.
P.S. It would be amazing if Boohoo (LON:BOO) manage to snap up Top Shop and Top Man, and Miss Selfridge to a lesser extent, from the administrators. I bet they're working on it as we speak! Wallis & Evans possibly, but only for tuppence ha'penny.
Up with Paddy Power!
No, not the gambling company.
All the best for the lad, he looks like a proper little smasher.
The sell off of Loopup (LON:LOOP) looks massively overdone (I hold & am looking to buy more). Growing rapidly, profitable, core business doing very well, against a disappointing fall in their smallest division, which is now just 14% of the business. And the MS Teams project has not had time to show in the results but looks very encouraging.
Agreed. Disappointing update yes, but 50% drop overdone!
Was expecting 15/20% drop max...
I have now been a customer of Stockopedia for 6 months. Before I joined my portfolio consisted mainly of blue chip FTSE shares such as Shell,HSBC,Aviva and Unilever . Predictably,they all dropped like a stone with Covid news in March but am very pleased to advise that after spending a month reading Paul and Jack’s posts plus of course the excellent discussion notes,I dumped all of my portfolio and started buying shares I had never heard of before I joined Stockopedia .
Now my portfolio is up over 15% in the 5 months and has the potential to at least double in the next 6. Shares bought include Boohoo,Saga,Reach,Games Workshop,Volex,Polar Capital,Redde and Wynnstay .
Frankly it’s the best £200 odd I have ever spent and I would like to thank everyone who participates on this superb site.
Beware the herd
2020 is a weird year and all lessons from it should be questioned and many junked.
I feel like I've stepped through the looking glass. How many of us are up overall on the year, I'm guessing the majority of you! personally, I didn't even trade very well, I missed my stoplosses on the way down and initially didn't trust the bounce back and came late to the party.
GDP is tanking 12%, unemployment is about to rocket. All that stimulus money is going straight to people, not banks like it did in 2008 where the stimulus just raised asset prices.
That most of are up, seems strange
I shouldn't bemoan my good fortune, but I would like to understand it, as Gandi said a man must have his thoughts, words and deeds in alinement.
And yes I did just quote Gandi in the small-cap thread even mad Mojo has not achieved that :-)
ambrosia
GDP has already tanked (largely because of the action of the government, the duplicity of the media, not the bug itself).
GDP is probably going to rise quickly for the next 3 years.
It is possible the unemployed might find employment more quickly than what the media and opposition politicians sooth-say.
The moment The Public can spend money liberally, with mega low interest rates, I think they will.
GDP has already tanked (largely because of the action of the government, the duplicity of the media, not the bug itself).
Inept though our government undoubtedly is I doubt they could do much about GDP collapsing when the rest of the world is also shuttering businesses and borders. Sweden, which tried to avoid major economic shutdowns, has also seen record drops in economic output. Ditto the media - if the government actually published understandable information then people could make up their own minds instead of relying on tabloid headlines.
For GDP the official ONS prediction is a very strong rebound with recovery to pre-pandemic levels by Q3 2022. But that's conditional on the speed at which the virus is brought under control and assumes some kind of Brexit deal.
timarr
The fall in GDP is largely due to "socialists" and "socialism".
Europe, especially France, Germany and Spain, is full of "socialists", as are The US's coastal big cities.
Socialists believe in "the big state". The all protecting fatherland big state loves to micro manage people's personal lives, deny freedoms in the cause of safety and "bio security", prescribe ever expanding and bizarre volumes of "rules".
People who actually work (suffer risk, even hardship, in spite of the lockdown) were effectively outside of "socialism" and this protection bubble.
Sadly, and wrongfully, the people who suffer most from "lockdown" are the poorest, most vulnerable members of society, as well as students missing education, the sick not receiving the same medical treatment normally available. The "furloughed" especially the hospitality and travel sector have been particularly and wrongly affected by this.
Had we not followed "lockdown" and nanny state rules AND had we left The EU say 5 years ago AND had we forged more trade arrangements with more "capitalist" less "socialist" trading partners AND not had interdependency on The EU (predominately "socialist") then we would have had a lower fall at the expense of marginally high deaths.
What about the mortality: COVID @ 50,000 deaths, approximately is still only 10% of The UK annual mortality of 550,000 which the powers that be seen unable to talk about.
However the physical geography, that France, Germany, Spain, Portual, Italy, the EU are still are closest trading partners, is that Lockdown was going to be no different a hit to GDP no matter what we did or how libertarian and freemarket our policies.
Its worked out exceedingly well for Stocko investors though, hasn't it.
The fall in GDP is largely due to "socialists" and "socialism".
Europe, especially France, Germany and Spain, is full of "socialists", ...
So why is the GDP hit larger in the UK than those countries? Is Johnson a "socialist"? I think we should be told!
Because our Government over-reacted.
Because we have the biggest City and financial services sector in the region.
We are a makor shipping, aviation and tourism "hub". We are big in aviation and oil, to a smaller extent big engineering and manufacturing.
Because as one of the leading european economies with the highest rates and numbers in useful employment.
Of course our fall is going to higher than a dysfunctional economy like Greece or Italy.
GDP is probably going to rise quickly for the next 3 years.
There will certainly be a post covid bounce back, but since Brexit is likely to lead to a larger, and maintained, hit to GDP, that's likely to be short lived. Add in short term distruption for import/export and it may be very short lived indeed.
"Likely". Only in your opinion.
We're net importers and most of the stuff we export to Europe doesn't incur tariffs and, much of it won't be affected by loss of access to the "Single Market" as there isn't a single market for services. I'm not saying there won't a Brexit impact, but there's much discussion, even amongst Remainers, how big it's going to be.
Also worth noting, that once we lose the Common External Tariff, many imports are likely to become much cheaper. I suspect most of the world is looking forward to being able to import produce on fair terms to the world's 5th biggest market economy.
Only in my opinion. No
ONS, BoE, IMF and govt's own estimates. I wouldn't claim to know better than any of them, but there seem to be plenty happy say their own views and wishes override them.
Let's rewind. You said it's "likely" Brexit will lead to a "larger and maintained hit to GDP". GDP is down 11% or so right now.
In a world trade orgasnisation Brexit, IMF says 8% down, less depending on various trade deal scenarios. I didn't bother looking up the rest as one is enough to suggest you didn't actually go and look at what they said, but I doubt the others say -11%.
Some of your others are in the chart included in this blog.
The Uneven Path Ahead: The Effect of Brexit on Different Sectors in the UK Economy – IMF Blog
You are quite right, IGPJ, I was wrong to write "larger AND maintained". It looks like being smaller, but indefinite in duration, so the overall impact will be greater, since we are likely to lose 8% or so for many years, in case of a No (Australia!) Deal, rather than 11% for a year or slightly more.
Remainers see falls.
Brexiteers see opportunities.
I see many things we can do far better at than The EU members.
We could (should) exceed EU environmental, consumer protection and quality standards.
Even The Californians beat The EU on vehicle emissions.
GDP has already tanked (largely because of the action of the government, the duplicity of the media, not the bug itself).
There is a very strong correlation between the health impacts of covid in a country and the economic impact. Those that have controlled it well have had less economic impact. The UK is near the top of both tables. GDP damage is far more likely primarily due to failure to act fast and hard enough early on. GDP damage would probably have been much greater had they failed to control infections at all.
ambrosia
I'm disappointed in myself not to have quoted Gandhi.
Over the past few months I have become more disagreeable than normal and have not sought to restrain it. I believe you are all mad and that great hubris has grasped UK small cap investors (as represented by the Twitter and Stockopedia)...I'm not trying to be rude, its a matter of self preservation IMO.
Many complex reasons can be given for why we are where we are. I think it can be reduced to very simple meta redux. We are on the cusp between two distinct polarities - deflation (so depression) and inflation (so something else that we really don't relate to emotionally or intellectually).
All rational backwards looking evidence points to the inevitability of deflation and has for many years. Simple momentum blindness and over optimism stops us from acknowledging this and to some extent ever since 2009 we have played a game of its the end of the world but the next X months will be alright due to stimulus/QE/China growth/etc...but it'll be dire when that cools off. A great narrative around low rates, free capital and the supreme power and durability of some great platform companies has grown up within this heuristic. So much of the 'wisdom' of the small cap crowd is looking for offshoots of this platform power. Anything else is trash. All this is a strange contortion and pessimism powered by the great deflation, and so depression and end of good days, is coming.
But the above will never be allowed. All our economic, political and even social beliefs will be set alight to avoid the deflationary-depression outcome. They must be as to accept it is to accept the end of society as we know it. A rerun of the 1930s depression or prior depressions is no longer tolerable or possible within our proletarian-capitalist democracies in the West.
And so inflation is the only route. But what the hell is that? Its most clearly not what most people think it is....so I want to ignore external wisdom and make my own mistakes even more than normal....sacrilege -> I even caution against QVM....particularly QvMMMMMMM.
One polarity will win and that will form the intellectual and emotional basis for the 2020s...its 100% certain it will be inflation as it cannot be anything else. It seems like we will struggle to accept this though as no politicians yet show the willingness to adjust intellectual and policy to this reality. In the UK we have problem of Sunak who appears to believe that austerity is the road to the future. Mad!
Was that mad enough?
mojovision out
PS yes my portfolio follows the pattern you describe and I'm at ATHs despite not owning stocks that would generally fit with the SCVR and Twitter general consensus as to what is good and the future. How messed up is that....it should worry anyone that thinks 2020 demonstrates their genius ;)
That said, I felt end of 2019 was set up very nicely for my special sits and capital cycle turn plays very nicely and I was conservatively expecting a c.50-100% year (hahaha...conservative) and so I could say 2020 robbed me of that. Never mind, I haven't made my mind up on 2021 yet but I think I'm going for 100% plus
I meant mad in an endearing way, I quite like your long rambling posts, I even brought a book on one of your recommendations
Thanks. Don't worry, I wasn't in anyway offended...the tartness of response was a bit joking/banter/faux upset sort of thing. By and large I don't care what people say to me or about me (in a professional or public capacity sort of way, which I consider investment stuff)...as long as they reciprocate the freedom. I do have a dishevelled rambling mind which falls well short of the required standards. Its useful sometimes and annoying at others (to me). To me very little is certain and most things are blurry but within that we must choose our sides...I do...but then I also flip when I realise I'm wrong (which can just be stupidity on my part)...which sometimes infuriates or adds to the perception of some I've worked with of inconsistency or even madness given I might have resolutely argued the other way.
I hear you mojo.
I worry when I see so many of the community own the same shares as me. It doesn't feel like I have an edge........
Hee hee one eye. I get nervous when people agree with me...and I often like it a great deal when they disagree vociferously. TBC contrariness can be very dumb plus I buy low and high valued shared, but very rarely anything everything agrees is superb quality in a narrative sense. I like it when people are very sure in their narrative of dislike, even hate, as that tells me the dislike and disinterest is mature. Its a balancing act and buying 'crap' is not a good strategy nor is my approach to jump on falling knives routinely (sometimes though if I can see the craziness...can't remember the last one, think it was K3 Capital (LON:K3C) as it hit the low 100s and into double digits). It takes patience though and at times I can be left hanging around for a while in terms of share price action...but that's okay...winning all the time is oppressive ;)
Hi Caper4
I also hold all the shares you mentioned, except "Wynnstay" perhaps I should look into that one too.
Let's hope they all go up in the next six months
Wynnstay is a fine company as the Stockopedia ratings confirm. Others I hold include Venture Life,Up Global and Ig. Also took a punt on Carnival a month ago as I am fairly sure it will be a two or three bagger within a couple of years . So many of my vintage love cruising and have the time and money to do it. Don’t think Covid is going to be a major issue within a year .
We have a few portfolios - a SIPP, ISAs, trading accounts etc. I'm 67 and have been investing for a number of years. The events of March were maybe the worst I have experienced and it seemed like there was nearly a capitulation in the market. My policy has always been to stay in the market but this was difficult. I did but we were down a lot. I managed to pull myself together and sold the worst culprits like Lloyds Banking (LON:LLOY) and Easyjet (LON:EZJ) and reinvested in other shares.
Since April we have done over £5m of trades (buys and sells) with no real new money introduced. At the beginning of this month I worked out that my 'profit' on the trades was £150k and I thought I was clever. We regained all our losses and were slightly ahead (thanks Apple and some ITs). I looked at it again today and it was only £65k. This month some of those dreadful names that I sold have come back and some of our reinvestment picks trod water.
Our overall gain since April is £800k. Of this my great trading contributed less than 10% of the return.
Now there is another element - risk. I have greatly diversified my holdings - into Japan, the US and Emerging Markets. I think that when (not if) my new portfolio will not suffer such a large drawdown. And I would urge Caper4 and others to work out the exposure of their portfolio to another crash.
This crash and recovery was very unusual in the speed of its recovery, largely thanks to the intervention of central banks. Historically crashes lose you one third of your portfolio and take three years to get back to normal.
So pat yourself on the back and say well done - you have. But please be wary of Mr Market - he bites when you least expect it.
Come on Paddy!!
Hope Paddy has a good recovery. Is Leveson a policeman?
Come on folks, we are being a bit too ready with the thumbs down button! That's a perfectly reasonable jokey question from Inversornot1 about Sir Brian Leveson PC.
Initially when reading this in the Boohoo announcement I thought it must be a misprint and they meant to say Sir Brian Leveson QC - Queen's Counsel, a senior barrister. In fact it means he is a Privy Counsellor, a member of the Privy Council that nominally advises the monarch. In past times it was effectively the King or Queen's cabinet, now it has a more ceremonial role.
The usual designation for a Privy Counsellor is "The Right Honourable" and if you look him up in Debrett's rather than Wikipedia, they give him what I would say is the correct title, The Rt Hon Lord Justice Leveson. That tells you he is both a member of the Privy Council and a senior judge.
He is also a QC of course, as most judges are. Once you get promoted to be a judge most people stop using that title, it's just a matter of choice.
Thanks for clearing up the complexities of his title Whitbourne - it was meant to be a light hearted joke. Hopefully the humourless keyboard warriors are a minority here.
Morses Club???
No idea why this isnt up by 20% this morning. They literally just made a profit in the worst conditions ever.
Yes, Paul please add Morses Club (LON:MCL) to your list as they are confident enough to have allowed for a 1p dividend in February. Many thanks
Paul avoids home credit providers, thus does not commentate on International Personal Finance (LON:IPF), Provident Financial (LON:PFG), Morses Club (LON:MCL) and the likes.
From my super quick read of the prelims Morses Club (LON:MCL), I believe PIs are put off with the £5mn provisions / impairments going forwards into this FY.
I sold Reach (LON:RCH) on today's TU
I think this is a story to watch. However, I felt the analyst call this morning was a bit fuzzy in a few areas and revealed just how much work is to be done to grow and monetise what they have. They revealed they are pushing in the right direction but without specifically knowing what works for them. Its all positive direction but low specifics.
I don't normally cut and run like this and I happily wear the ups and downs on strategic basis but the move in Reach since October has been ridiculous on the back of some PI hype and I think its clear the steam comes out. Good analyst question re impact of lockdown end on digital in December too and how Dec 2019 provides hard comparison.
In addition to Ed's comment re site atmospherics being crap...I can vouch for that as a regular Daily Record reader (Scottish football)...it is the absolute worst for jamming crap on page plus they often make you answer an inane set of questions re brands and preferences before letting you read on....if I didn't need the Scottish football gossip I wouldn't stick through it.
Note: Reach (LON:RCH) I think there is risk of a negative surprise in the FY from the actuarial triennial valuation work that will be reported (the work is done for end of 2019 but the market assumption will be updated and liabilities should have deteriorated given yield and inflation numbers since then). Means not respite in cash from operations to fund and potentially pressure for more. Perversely, the announcement from Chancellor re new inflation measure from 2030 will be a positive but its unlikely to show through short term and even if they did incorporate the yield impact on liabilities will be more signif
I have been considering Reach (LON:RCH) for some time and understand their strategy to transform their income from print to digital. However one thing concerns me. They might well get their 10m subscribers and cover local news digitally but I do wonder how effective the massive number of ads plastered over each page are on these sites. The choices of digital advertising platforms is now vast and the agencies will choose the ones with the best ROI. Reach's platform will need to compete effectively in this crowded ever developing market and that is yet to be proven.
With regard to Reach (LON:RCH) advertising I searched for Macclesfield and Loughborough news being are the two sites relevant to where myself and my son live. I really cannot see the problem with the advertising that a few people have suggested obscures the actual news. On these sites the local news is presented in the middle of the page with advertising down the margins and at the bottom. If one just wants to look at the news and ignore the advertising that is easy. I would have thought that multiple websites then provide a means by which advertisers can easily approach customers in specific areas of the country. The actual news I found to be of interest to the people living in these localities which no doubt accounts for the high number of visits to the websites.
Its about how Reach monetise their website traffic. They are the 5th / 6th most visited sites in the UK, so huge potential. At the same time, they are cutting "print" costs, reducing duplicate staff on the different titles, etc...
I think their is still so much potential and they are only at the start of the transformation.....
Boohoo (LON:BOO) decided to pick some up for black Friday. Interesting to see some big names including B&m European Value Retail Sa (LON:BME) and Next (LON:NXT) are shunning it today: https://www.bbc.co.uk/news/bus...
Hi Paul
Great News about Paddy
For those that may have forgotten Cockney rebel (Richard Crow) did a piece for Piworld a couple of months ago, including De La Rue (LON:DLAR)
Link below is direct to that point. Hope it helps
Lloyd
Always good to hear other traders
As an argument that makes little to no sense.
How does Salesforce buying a desktop productivity suite have any bearing on Loop’s ability to sell teleconferencing?
Not sure where you saw it directly linked, but in my mind it is about vertical integration in the remote working space. You have a market leading CRM (Salesforce which is a platform which can support pretty much any business) and Slack, widely regarded as the best collaboration platform, (which grew out of the agile tech start up world). Pretty sure both offer conferencing plugins. But I think the threat is more directly toward Microsoft (Teams/Dynamics) and perhaps Zoom (which will eventually have an existential crisis without further integration).
With respect to companies like Loopup (LON:LOOP) (I still hold though down 60%....!) can they maintain their niche? In my mind I hope they have enough of a differentiator to be purchased by one of the big boys and I recupe some of my losses, or I think they will be squeezed out. Finding it hard to make a bullish case TBH.
Let's put it this way - companies that went with Salesforce almost certainly have a Microsoft desktop and other Microsoft services. Customers that have Microsoft desktops and other services probably don't have Salesforce. It's fair enough they want to buy Slack, but then they would also need to buy a whole load of other back end services to create a end to end service - they're missing so much and it's going to take them years if that their plan as they're starting about 10 years late.
Zoom is "proper" VOIP, like Whatsapp you don't need anything other than the app. But you have to have the app.
Slack I'm not sure about how it connects. Not sure it's widely regarded as the best collaboration tool either, but then I work mostly with the Microsoft stack so I haven't come across it directly. It is getting smashed by Teams in the market though,
Teams does both - you can make video calls on the app over VOIP, but you can also dial in to it and dial out from it. But here's the catch, to be able to dial in and out you need a connection to a public telephone exchange - that isn't there by default. Of course there's loads of companies out there doing it, but Loop's differentiation is they will host the connection to the public exchange for you and you don't need to buy a load of expensive kit from the likes of Cisco.
There is a lot to unpack in this IGotPoesJacket, and we are both seem to be in tech, so not going to dig into the merits of the various platforms (wrong forum imho), but a key point for me is when you say Loopup (LON:LOOP) 's differentiation is they host the connection to the public exchange. Unfortunately, that makes me feel more bearish as it is edging towards what I consider a low margin utility service. I believe the 'New Normal', whenever we get there, will be any device, any location. For me the companies which support that are the bets I want to make.
I think I need to spend a few hours this weekend mapping out Loopup (LON:LOOP) services on a Wardley Map and see how high up the value chain they are. Then it will be a case of deciding whether to jump ship with a bloody nose, or see if I can catch that falling knife without losing a finger.
I am with you - I just don't get the value add. I use Teams every day including on my mobile: chat, 1-to-1 calls and VC. All my clients use it too and we federate with the ones we are closest too. It is effectively free as part of our MS contract. Where is the value in the voice connection to the public network? I am genuinely super-happy to be educated...
I guess its along the lines explained in the case study illustrated on their website - note the Mclaren mentioned in the puff piece is not the F1 company or the company that makes buggies :).
Although Microsoft offer their own Calling Plans, McLaren decided to use Direct Routing with LoopUp as the managed service provider. Larger global organisations typically opt for Direct Routing as it offers greater flexibility, wider geographic coverage, lower rates and increased levels of support.
https://loopup.com/en/resource...
Re Boohoo (LON:BOO) , what I don't really understand is why KPMG are willing to audit their supply chain but not willing to audit their accounts.
Non audit work is higher margin
Hi Paul, re-posting my question last night here again ( hope you don't mind) as was not expecting Boo to be on the report again today.
***
@Paul - You mentioned about suggesting to Boohoo (LON:BOO) about transitioning from AIM to NYSE (or both I guess), do you see that as something that happens at all ?(Apologies I am still fairly new to this game).
Would it be costly for them, is it as simple as taking their share price and converting or is it a complex process ?
Very interested in your response if you get a chance
Thanks
Burford Capital have recently done it (dual listing). Completely different animal/sector, of course.
Hi Lee,
I honestly don't know what the process & costs are for having a joint (or sole) listing in the USA. It seems to be something that a few UK listed companies have done recently, or are considering.
For something like BOO, I think it's a no-brainer, as similar companies on NASDAQ are valued at multiples of what AIM investors value it at. I'm hoping that the clean up job with KPMG/Leveson, etc, could maybe be to make it squeaky clean, in advance of a move to NASDAQ? That's total speculation on my part, and I have suggested it to BOO management, who gave me a non-commital response, thanking me for my feedback & saying all options are on the table.
Regards, Paul.
Reach (LON:RCH) issued their much anticipated TU this morning and it's not as exciting as many had probably been hoping for, myself included (I hold). On the positive side, digital revenue grew by 16.2% over the 5 month period. In the HY results to June, digital revenue grew by 12.9% so this appears to show an accelerating trend which is absolutely necessary to offset the secular decline in print revenues.
Key to their strategy of monetising their digital assets is the registration of customers with a target of 10m by the end of 2022. Today they claim to have 4.25m (0.8m in January , 2.5m in July and 3.5m in September) so that trend is also positive.
YoY print revenue declined 19.2% (Q1: -10.7% Q2: -29.5% Q3: -19.9%). Overall revenues were down 13.9% for the 5 months but due to heavy cost cutting and efficiencies they state that "operating margin in the second half is expected to be materially ahead of the first half." Who knows what that means in this context?
H1 Revenue of £290.8m gave Adjusted operating profit of £54.9m and my very rough calculations would give a similar figure for H2. The question is can the digital revenues allied to the cost cutting (they are consulting on the closure of two of their six printing sites) continue to keep ahead of the decline in print revenues.
It's a race that I'm struggling to calculate if they are winning and I'd be very grateful to anyone with better spreadsheet and analytical skills than myself, who can shed some light on the likely outcome?
£RCH TU is clearly not a "numbers" TU but a "words" TU. And the wording is very positive, as the first line explains very well (emphasis added):
"Digital momentum drives performance ahead of 2020 market expectations"
My summary of it: Overall group performance has exceeded market expectations, costs have been significantly reduced, strong digital growth and resilient print circulation, positive balance sheet and strong cash flow, new efficient operating model. All despite Covid-19 and recent lockdown. (I hold)
I think Reach have a good opportunity and it's actually my 2nd biggest position... but ultimately the UX on the sites is appalling. They absolutely spam you with adverts. I'd really like to see some serious motion towards added value services. For me, RCH is a speculation, not an investment.
Reach (LON:RCH) has tripled in value over the past 3 months which is no doubt a lot more than even the directors expected. When Richard Leonard mentioned it he suggested they would be announcing ways in which they would monetise the large numbers of visitors to the websites around March, by which time he thought the price may be 150p. Looking beyond that he was hoping for much more but give it time! It all comes down to whether you get excited, as I do, by owning websites that attract a lot of traffic and imagining the income they could create in the future. They have a great basis with I think in excess of 150 publications most of which are local. These are what are important with people wanting to know what is happening in their area as opposed to what is in the national press. Of course, everything could be improved but the opportunity is there and no one else is likely to create 150 local online newspapers. In the light of this, even as someone who spent his whole career looking at figures, it is not the current figures but the future prospects that attract me.
Reach (LON:RCH) "Learning my trade" by developing my knowledge I recently started putting stop-losses on my larger holdings. Unbeknown to me Reach (LON:RCH) seems to have dipped a bit over the last few days and yesterday I was stopped out. Very frustrating at the time, but lesson learnt that if using SL's you need to keep an eye on them and adjust them if you feel they could be inadvertently used and you are happy with a drop in the SP and believe it will come back.
As it is I am frustrated at losing out on the most recent bounce, but in all honesty I cannot complain at a 90% return in a matter of months.
I feel that they have a lot of potential, but there is a huge amount of work still to do and whilst todays news is OK, I agree with some of the other comments above that we need to understand better how the monetisation is going to happen. Like Ed the inane questions and awful GUI is not great, but I fully understand the potential. I will come back to them and hope that a period of stagnation may allow me to review the position in a couple of months and see how we are then.
Regarding stop losses I tried them very many years ago and then found that I would be shaken out at the lowest price of the day particularly on smaller shares where the spread may widen considerably. I think stop losses are best kept in your head.
Stop losses can be a way for market makers to pick cheap shares. You also lose control of the selling price.
That’s why I use Adblock, gets rid of all those awful ads.
HI Ed, the UX is what put me off investing. I spent a good few hours trawling through their sites and found them pretty weak by todays standards. That said, I did this a few months ago and if I had followed my heart, rather than my head, I could have made a fair bit of money....
I held a few years ago but sold when I looked at their on-line content, it was awful. I bought back again (just before the pandemic unfortunately) on the grounds the new management will get that their on-line content is still very un-classy and do something about it. Hopefully that will include enhancing its appeal and stop annoying those who might actually spend money as a result of reading its content.
My objections to the Reach web sites are aesthetic rather than practical. Yes, they look appalling but you don't actually have to click through unwanted adverts to find the stories that you want. I am willing to have my aesthetic sensibilities offended in return for reading free news stories.
That UX you mention Ed is the main reason why I don't use their local newspaper website and don't register. My wife is registered and often sends me Whatsapp links to their news articles on covid. I received such a message yesterday on the tiers for our area (3) and reading the article on my phone was painful with so many pop ups etc. I guess stats don't lie and they are getting people to sign up, however for me at least the user experience is shocking and I'm not inclined to give them my data.
If Reach (LON:RCH) was sitting on a p/e ratio of 25 or 30, your concerns may be valid, but be careful you don't suffer analysis paralysis and miss an opportunity. The business is recording growth in all the right areas, and its profits are rising. H2 operating margins will be materially higher than H1 and this implies that H1 next year will be materially higher than H1 this year. Allow management the time to optimize what they have created.
Reach (LON:RCH) (I hold) - on the call today I've picked up on them mentioning the importance of proving the engagement of their subscribers. I believe this is what the advertisers are asking them to do, and what is driving the ReachID initiative they currently have underway. In essence, there is no point in having 10 million subscribers if you can't prove how much and how they engage with the content or digital ads.
I believe the ReachID will play a key role in driving advertising revenue, but it may very well point out gaps/shortcomings with their UX (e.g knowing where or how soon your engaged subscribers fall off).
The problem now becomes when the ReachID will be operational and how soon could it produce positive (advertising) results. Development, rolling it and beta testing will take anywhere between 3-6 months; there will most likely be a trial of sorts with some advertisers, but they will want to see data over a longer period of time (6-12 months?) before they commit more spending. If that will be the case, the question remains if digital advertising revenue will be able to balance out the negative impact of (potentially) lower print sales/circulation.
Paul Ill be very interested in hearing your comments on Loopup as Im watching them hot the floor. I do Hold.
Oh God, £loop is very bad today. Another overreacting IMO. I hold and it was shocking to wake up to a 50% plunge on share price in the morning on top of recent continued downtrend. I had bought at 230p and am now over 65% in loss.
Hi Paul,
thanks for your kind words about me regarding the comments and tons of thumb downs yesterday. After all, I'm happy that I have a great friend with great personality as well as great technical knowledge of shares in this strange challenging world.
Re Boohoo (LON:BOO) : I think any journalist who wants to now write anything will think long and deep. This appointment of one of the most respected high ranked judges in UK history was, as you mentioned, a coup; Head of UK criminal justice and Chancellor of the Queen's Bench (High Court). That's very different to me than even a number 1 audit firm or similar. Very different. Especially when his reports are going to be PUBLISHED to the public. It shows maximum commitment And transparency.
just to clarify, he is retired now; I meant former Head of UK Criminal Justice and QB High Court.
It says to me that they’ve had to agree a plea bargain and are serving probation under a very expensive high profile probation officer and his team.
A plea bargain for what and to who?
I don't understand the slating of journalists for reporting news about BooHoo that we (I hold) don't want to hear. BooHoo was found to be using suppliers who paid less than minimum wage and forced employees to work through the lockdown, very likely causing a COVID outbreak in Leicester. This was a bad thing. They reported it. Now it appears the BooHoo is getting it's house in order with talk about factory all of it's own (although less of that lately) and appointing Leveson (at considerable coin) to oversee a supply chain re-organisation review. This is a good thing. They report it.
No-one is out to get your portfolio. The journos and the press broohaha brought issues to light that Boohoo et al needed to fix. They are being fixed. BooHoo is now an even better investment. Thanks Journos! Thanks BooHoo!
Well, it isn't the reporting of companies doing bad things that's at issue. It's the fact the reporting was so badly researched and often failed to mention the true criminals making it out it that it was Boohoo themselves that were acting illegally.
One example - one of the broadsheet's online edition, it kept mentioning the "highly damning report" but wouldn't link the report because they knew if people read it they would see their article was based mostly on hyperbole and not reality. Several times I tried to link the report in the comments section the articles and the news publication removed the link every single time.
IncredibleMosesLeroy
I don't understand the slating of journalists for reporting news about BooHoo that we (I hold) don't want to hear.
I am 100% with you here IncredibleMosesLeroy , they print something - we read and make up our own minds. It should be appreciated journalists aren't experts - will get the tone wrong often and that is how it has always been - any youngster should pick up a an old copy of the sunday sport or one of the old tabloids to see the crapola they used to print. The one thing journalists by publishing do do is continue to question and probe and then is never a bad thing as long as it doesn't veer into intrusion in ones personal life. if they are factually wrong they can be held to account as appropriate. There may have been the odd story that overstepped the mark with boohoo but thats life and boohoo have semi made their own bed here by not having complete supplier chain acountability.
no complaints from me as I bought a shed load more on weakness
I've never condemned journalists for reporting the facts. My criticism was specifically the endless repetition of the same story, often presenting this as something new and scandalous, when it had already been in the public domain for a long time.
Also, many journalists failed to give any balance, or explain in any detail what the company has been doing for some time now, to remedy things.
Therefore, this has given an overall impression which is far worse than reality, in my opinion. I'd like to see media outlets give more prominence to the balanced truth. For example, in today's Telegraph article, it refers to BOO as being about to "break its silence" about the supply chain issues! What on earth are they talking about?! That's totally untrue. BOO has in reality been giving extensive and frequent updates to the market & the press about what it's doing to remedy the problems, for months now.
Regards, Paul.
Wishing Paddy a speedy recovery Paul.
Good luck Paddy, you have more people rooting for you than you know. Turn Paul's computer off so he can give you his undivided attention today: the market can wait.
Bonitabeach
The update from Loopup (LON:LOOP) is quite disappointing this morning. It notes that revenue in September and October actually fell by 9% compared to January and February this year although within this revenue in professional services (the market Loopup (LON:LOOP) is now focusing on) was about 6% higher - which itself is not exactly stellar given you'd expect a pandemic to boost demand for its products and a lot of people were still working from home in those months.
Revenue for the year is expected to be no lower than 18% up, with EBITDA up to around £15m compared to £6.4m last year. EPS was previously expected by Progressive Equity Research to be 17.2p this year before falling to 9.3p next year. I assume both those figures will now be a bit lower but the update does say EBITDA will only be 'moderately below' market expectations - Progressive had expected 17.3m EBITDA so that'd be a miss of about 2m. So at around 80p this may potentially be trading on a P/E close to 10x next year.
As noted in a previous update the company is also moving to fixed-price licence deals with long-term commitments, but lower pricing.
Noting all that the share price fall this morning looks a bit over-the-top and perhaps people are worrying that it will return to pre-pandemic mode when revenues were falling. It's a tech stock so shouldn't it be on a slightly better rating? However, maybe the worry is that the product is not great and the competition significant so perhaps this shouldn't be on a punchy rating?
I hold, now nursing a 65% loss. I did look to sell this morning but at these prices I think the fall might be over-done so will continue holding for now. What do others think?
Hi Patrick
Like you considered selling but the fall seems overdone for a company which still appears to be growing although it will be interesting to read Paul's take.
With hindsight the Stockopedia Investment Club's stop loss rule appears to have protected them well
Fairly new to LOOP but followed in quite big on all the stockopedia analysis and conviction. Can anyone help on why the Annualised run rate is just £34m. Feels quite low but guess depends on future contract wins. Fall does seem overdone but LOOP seem have a history of disappointment and is being punished. Bought more at 80p exactly hoping it may recover some of the falls
LoopUp (LON:LOOP)
Fairly new to LOOP but followed in quite big on all the stockopedia analysis and conviction. Can anyone help on why the Annualised run rate is just £34m. Feels quite low but guess depends on future contract wins.
I am reasonably new here too but its pretty much a given they must pick up a decent volume of sales each year so i would expect ARR to be materially below actual sales.
If they are only on target to hit £50 mill sales this is a stonkingly bad update when we factor in the H1 sales of £31.9 mill - that would gives us just over £18 mill H2. Note they did £42mill last year of which half that was H2. So they are now behind where they were last year or sales volume - sales isnt everything (actually is nothing really ) but i for one had it on my watchlist as i thought the excellent h1 would possibly stick around more than it has done and i was semi expecting another upgrade. To be semi fair to the company 2021 estimates were always much lower and it must be hard to work out the transactional volume going forward when there is such a big spike. I think the company have though in hindsight dropped the ball by not being more conservative in forecasts - its a bit ridiculous to have such a stonking H1 updated on 23rd September then have a profit warning 9 weeks later.
Is this a buying opportunity ? - if they are expected to hit £5 million profit next year anything under 90p looks at cheap as chips - i would be particulalry interested to see what the updated profit expectations are for 2021 year - if they remain in the £5mill range ish then the underlying business still seems in fine fettle.
I have held a small position in Loopup (LON:LOOP) for 6 months but the recent weakness seemed like a golden opportunity to me and I bought in twice more at around 150p over recent weeks, making it quite a sizeable position for me. Today's drop was a serious kick in the teeth for my portfolio.
Have I got something seriously wrong with this share? My underlying thesis was that even if CV19 is under control by the summer, working from home was a trend set to continue for at least the next year (or at least companies would be reluctant to increase travel budgets again now they have found a cheaper acceptable option). Therefore, the law firms and financial firms LOOP recruits now should remain sticky. The company has also been transferring those customers on to 24 month contracts - 30% in last update/ 40% today.
However, there is no glossing over the update today - sales appear to have fallen below pre-covid levels, indicating that new customers are not continuing to use. I'm wondering if the ease and network effects of large competitors like ZOOM mean that the technological advantages of Loopup (LON:LOOP) are not being seen as useful enough - MS/ ZOOM are reliable enough and maybe security advantages are important but not enough to pay extra for most users.
Going to have to think long and hard about this - for now I continue to hold as today's drop is way overdone in my opinion. But this may be a busted flush of a company - good tech but can't break the network effects of competitors.
LoopUp (LON:LOOP)
Phuntt
Have I got something seriously wrong with this share? My underlying thesis was that even if CV19 is under control by the summer, working from home was a trend set to continue for at least the next year (or at least companies would be reluctant to increase travel budgets again now they have found a cheaper acceptable option). Therefore, the law firms and financial firms LOOP recruits now should remain sticky. The company has also been transferring those customers on to 24 month contracts - 30% in last update/ 40% today.
I could easily have been in the same boat as you today - i had loop on my watchlist. I guess what has changed today is the abrupt reduction in their estimates of what they expect in the near future. The danger here is that this is the start of a drip feed of bad news over the next 12 months - if it turns out that they may be struggling to achieve what they were promising the market with regard to next year then that is a concern - if they have a good strong niche making 4-5 mill per year thats great. However if they struggle to convert the promise due to whatever reason - will they back where they were up to 2019? - looking at the historical numbers despite good revenue growth profits werent exactly flowing through to the bottom line previously - i don't know if this was for genuine reasons (invest for growth makes sense) . At some stage though a company should really be saying our plan is now clear and we will deliver 5% - 10% bottom line profits whatever the sales numbers and then you can trust the business shoudl leilly be there for the long term. At present more than anything else i am interested to know how todays news impatc what they think they can deliever for 2021 - if 2021 expectations remain fully intact i may still be tempted to add here.
Good post Patrick, thank you.
Like you, I am nursing heavy losses this morning but at 80p, I think this selloff is very overdone. Their client base is the key for me - law firms and wider professional services firms like and trust the product and actively choose it over ZOOM. They are less price sensitive and more loyal which means a PER of 10 makes this a steal. So I added a shedload at 80p this morning.
cheers
Francis
I hold £LOOP too and for the moment am still holding. But I think the fall in SP is justified. In essence, today's update is telling us the business is performing worse now than pre-Covid, despite the tailwind of working from home.
H2 revenue is guided at >£18.1m vs £20.2m in H2 2019 (which was pre-Covid and was weak anyway) and this is down <£4.8m from the broker guidance given in late September (when H2 was already half completed). EBITDA guidance has similarly been slashed.
The indications for FY21 are even worse. Indicated ARR of £34m (which is still going to be supported by working from home) looks bad, compared with a 2019 revenue of £42.5m.
Also I have trouble reconciling the statement in today's RNS, comparing revenue in Sept and Oct against Jan and Feb:
"which as a result is c.6% higher in PS, but c.32% lower in non-PS (a 9% lower net)"
with the statement that non-PS now makes up only 14% of the business.
Could that difference be because it is 14% of LoopUp platform (i.e. not Cisco resale (which is approximately 10% of revenue at half year)?
PS revenue in 2019 was 13.6m and Other 7.6, not disclosed in half year, but stated growth in PS was 80% versus 43% overall growth, which would suggest non PS was already in decline.
I hold and doubled up (DOWN!) today - what was it the guide said about profit warnings?
Maybe I am really scraping the barrel hear but the trading update is aligned with the chat/strategy outlined in half year report.
Note for future - on blow out half years/quarters, do not be dismissive of the full year forecast if it looks low in the context of the half year.
Now I need to think through Games Workshop (LON:GAW) again - which will be probably be a better use of my time than looking at what Loopup (LON:LOOP) is printing at!
Maybe some negative sentiment too following announcement that Salesforce is looking to acquire Slack. Comment suggests aims to be competitor to Microsoft Teams so that would be two big beasts in competition with £Loop. Their niche strategy would have to perfectly executed to survive and prosper. Trading update suggests there may be issues. Final point - does the fall mean Stocko Investment Club has to sell according to rules?
they sold a week ago - https://www.stockopedia.com/co...
though since they made a good pitch at a much higher price perhaps they might be frantically re-pitching given the massive discount on offer today... ? ;-)
The price topped in August and it was drifting sideways and down for 2 months before flashing a sell signal on 9th November when the first vaccine announcement came out. Once the 190 ish pivot was taken out, gravity kicked in and it saw the highest selling volume in 2 months. That was a major warning signal to lighten up or exit with 2 weeks heads up. You can't fight the price action and a stop loss below support is never a bad thing.
Over recent weeks I have been keeping a diary of charts that I looked at, to see if some of the things I think I see developing actually play out in practise.
Up until now I hadn't been paying any attention to LoopUp (LON:LOOP) (figuring that I had missed the boat on most of the Covid-winners).
Picking up on a comment by someone earlier in the week that the recent weakness might present a buying opportunity so I had a look at the chart on Wednesday evening. This is what I wrote :
As I say I hadn't been paying attention here, but I assume the drop on the 9th would have been attributed to the vaccine news.; but maybe it was something else,
I'm not about to come over all Mystic Meg, but maybe even if it was not directly predictive that prior fall may at least have indicated that sentiment was waning, which in turn might explain why the reaction today was such a sharp fall?
No position.
Hi Patrick,
Following on from fwyburd,I've had loopup on my buying list for sometime and thought it was getting too overpriced,like Francis I think 80p is a really good buying opportunity, don't loss faith and stay with it as you have potential, we just need to give the company time to prove itself.
All the best, Chris
As mentioned earlier - I really have not looked at LoopUp (LON:LOOP) so please take this comment as totally generic rather than specific.
As a (former) value investor in rehab ; I have to say that the four bolded words are crystal meth!
In my experience they can be true (but rarely) but I think you really need to understand 2 things :
1. PRECISELY what caused the market reaction.
and
2. Why the market got it wrong. In my experience you should (to misappropriate the words of Dr Ted) you should 'test, test, test' and retest your hypothesis here.
Is is entirely possible from market over-reaction but in my experience, but in my experience these opportunities are much rarer that you might (like to) think.
I will probably have a look at LoopUp (LON:LOOP) in due course, but these days I just don't see the urgency to get in before the market realises its mistake - certainly I might be too slow with my analysis, but that imho is no greater a risk than being too quick.
Hi Spongbob
For the sake of transparency, I ended up trading the shares I bought and sold them at a profit before they fell below 80p. Still nursing big losses in Loopup (LON:LOOP), just a little smaller than they were first thing Friday morning. I aim to review this position in the cold light of day and decide what to do long-term.
cheers
Francis
Re Boohoo (LON:BOO) (I hold), some pretty aggressive promos from PLT today which are attracting negative comments from journos on Twitter.
I noticed these as well but think it is just called "marketing". Personally, I find the whole "Black Friday" thing pretty sickening but them I am an old f@#t but if I can make money out of it (through Boohoo (LON:BOO)) rather than it costing me money I can live with it.
It also has to be said that with the extensions of lockdowns (oh sorry tiers one, two and three) just announced, things are pretty grim for so many people, I wouldn't begrudge them a bit of retail therapy.
As for journos? Well I'll keep my thoughts to myself.
Regards
Michael
Go Paddy, go, bow-WOW!
I know we're not meant to let personal worries affect our work
I think you got things the wrong way round there Paul. I doubt you’ll be on your deathbed wishing you’d written another SCVR article!
Best wishes to Paddy.
Paul, great news on Paddy
Good morning Paul,
Thank you for your sterling efforts on here and more importantly great news on Paddy!
Have a great weekend
I
important things first Paul, fingers crossed for Paddy.
Very disappointing with Loopup
My broker reckons it could open down at c.100p. Looks a strange update, I couldn't work out if it's bad, or neutral?
Loopup (LON:LOOP) didn't read that badly to me if you accept that they're shying away from high competition and focusing on their niche but the general tone was a bit downbeat. I hold unfortunately. #stoplosshardlesson!
Was that $LOOP update a long winded way of saying that everyone except the lawyers is using Zoom and Microsoft Teams?
I hold Salesforce (CRM) and see that they are in talks to acquire Slack.
Was that Loopup (LON:LOOP) update a long winded way of saying that everyone except the lawyers is using Zoom and Microsoft Teams?
It's bl**dy complicated, is what it is.
Basically they've gone from £32 million earnings in H1 to an expected £50 million for the full year - hence the drop. Although that's only marginally below the market forecasts it's clear investors were expecting a lot better.
There's lot of complicated percentages in the numbers, but basically the non-professional services side (where Zoom etc compete) is now contributing about £7 million of the £50 million and is dropping like a stone, while the remainder (lawyers, investment funds, etc) is growing steadily at about 6%, but that figure is hiding a transition from pay-per-minute to lower earning but presumably more sticky subscriptions (now up to about 40% of total earnings, up from 30% a couple of months ago).
So far from a total bust, just a lot lower than people were hoping for. It'll be interesting to see where the price settles at, but I imagine it'll take a few days to adjust. At this level it looks cheap, but really it's a guess at where post-pandemic earnings will finally stabilise.
timarr
Nice explanation :)
Exactly in line with my thoughts for £LOOP. Based on my calcs, (admittedly may be nonsense!) I expect very conservatively, £40-£45m for 2021 (@ H2 runrate), at a lower margin % (say 18%) to account for the move to subscription model + additional recruitment, giving £7.2-8.1m operating profits. That's c 12.4 to 13.9 EPS. At today's share price, that's between 6-8 P/E.
Even assuming ONLY the £34m ARR, and applying a lower operating margin gives 5.1m net income next year. Even that gives a P/E of under 11 at today's price.
You would need to however assume some growth with all the additional investment in Sales + Direct Routing.
I think, personally, considering Gamma (hugely successful and proven) has a P/E of close to 30. So let's' assume a P/E of 15 for £LOOP. That gives me a share price of 131p. Take off some for management incompetence.. even then, at around 90p, this is cheap. No two ways about it in my opinion!
Disclosure: hold at 220p so I hope this does bounce back for the sake of all us PIs!!
EDIT: an issue with the above is I don't know what the fixed SGA costs are. If it continues at around 20m/year & 8m depr/amort, that's another 28m . At 67% gross margins, to achieve 5m profits next year, you'd need c 52m Revenues to get this assuming 22m SGA and 8m depn & amort.
Excellent summary Tim of a hideously complex update. Very poor expectation management that has cratered the share price. I'm more concerned that the rate of growth in their Professional Services is pedestrian than the fall away in the general market. The one good thing I can find in this update is the progress and outlook on the new Direct Routing proposition. However, there is not enough detail to discern when this will start to move the dial - it's clearly a longer sales cycle and resource hungry to implement.
Feeling very bruised by this turn of events but on such a drop too painful to exit - and on c. 1x revenue potentially a bargain price. Probably need to reflect on these figures a bit more before making a decision.
Probably need to reflect on these figures a bit more before making a decision.
Hi Maddox
Well, I'd like to say I share your pain, but I have a max 2.5% of portfolio on speculative stocks so I probably don't. But I will buy you a pint the next time we're allowed out.
The Numis figure Paul quotes are probably the baseline now - they're the joint broker, after all. Which is a nasty point of departure although there's clearly room for improvement. I'd guess some the first half earnings were essentially brought forward from the second half and that the non-PS business is essentially dead in the water.
£35 million revenue for next year looks a bit low, but assume no non-PS revenue from here and lower PS revenue from existing customers due to moving to subscriptions and lower call minutes then you can probably get there. Doesn't look like there's anything in there for growth, though.
On the other hand, how much credibility do management have now?
Bah. I need a large glass of red wine and a spreadsheet to even start to untangle this ...
timarr
#stoplosshardlesson!
Re LOOP - not necessarily, because you couldn't sell this morning. My broker contacted me first thing, to offer me 5k shares, because he couldn't get a bid in the market at all. It was basically, name your price!
Usually stop losses only work with the spread bet companies at whatever price they can actually sell at in the market. So the danger is that a stop loss can result in you being forced out at any price they can get first thing, which can sometimes be the worst time/price to sell at. Unless it's a guaranteed stop of course, but they're quite expensive, and often can only be set at a deep discount to the previous price, thus not giving much protection.
Paul.
yoy growth at Gateley looks positive along with strong net cash positon. Was perplexed at share price weakness over last year so bought a few and still hold.
My morning smallcap tweet: LoopUp warns, Michelmersh cements progress.
Tungsten (LON:TUNG) Quadrise Fuels International (LON:QFI) LoopUp (LON:LOOP) Reach (LON:RCH) SPDR BL.BA.UK GILT U ETF (LON:GLTY) IXICO (LON:IXI) Symphony Environmental Technologies (LON:SYM) Michelmersh Brick Holdings (LON:MBH) Immunodiagnostic Systems Holdings (LON:IDH) Walker Crips (LON:WCW) Scholium (LON:SCHO) Mirriad Advertising (LON:MIRI), Aquila Services (LON:AQSG)
Tungsten (TUNG) warns FY rev flat and adj EBITDA not less than £3.2m, materially lower than previous guidance. Blames "lower transaction volumes, product mix of new sales, our new Total AR contracts requiring increased set-up costs, as well as additional costs related to our investment in the sales team." Good job they didn't have to replace the kitchen sink. [SP=33.7 Cap=43m]
Quadrise Fuels (QFI) long AGM stmt has nothing new but co "very pleased to be able to provide a comprehensive update to our shareholders" as if being able to write such a statement was a special bonus. [SP=1.8 Cap=19m]
LoopUp (LOOP) trading. Instability makes it "challenging to provide specific guidance on near-term expectations". Meetings and Event businesses robust and strong momentum in our Cloud Telephony but an acceleration of churn in non-Professional Services sectors. Guides FY rev at least 18% up, moderately below market expectations. "While trading is expected to remain challenging in the non-PS part of our Meetings business, this now represents just 14% of our total LoopUp Platform revenue." [SP=155 Cap=86m]
Reach (RCH) the go-go cigar butt of the moment beats mkt exp in last 5 months and expects trends of strong digital growth and resilient circulation to continue into Dec. Still on track to deliver 10m registrations by end 2022. [SP=154 Cap=481m]
Gateley (GLTY) guides H1(Oct) rev down only 3.5% and adj pretax at least £7m (£6.6m). [SP=63.97 Cap=NA]
IXICO (IXI) wins £1.9m contract for study. Already in FY mgmt exp. [SP=124 Cap=58m]
Symphony (SYM) NAV at Sept $0.653/sh up 3.14c in the half. [SP=21.4 Cap=38m]
Michelmersh Brick (MBH) guides FY U/L rev and profit above market expectations. Div will be 2.25p. [SP=104 Cap=98m]
Immunodiagnostic Systems (IDH) two covid Rapid Test kits now available for sale in the UK, EU and other CE-mark countries. Cites 99.2% specificity and 96.7% sensitivity for the better of the two tests. [SP=198.06 Cap=57m]
Walker Crips Group (WCW) H1(Sep) rev down 8%, pretax -£0.45m (+£0.62m). "Contrary to our worst fears, investor confidence and the financial services market remain resilient." H2 rev benefited from the rise in markets. Outlook "No doubt we have a difficult year ahead...[but] remain cautiously optimistic." [SP=27.9 Cap=12m]
Scholium (SCHO) H1(Sep) rev down 14%, pretax -£158k (+£64k). Better than mgmt expectations earlier this year. Guides H2 loss as well. [SP=35 Cap=5m]
Mirriad Advertising (MIRI) [last night] £3m placing at 40p, a 6% discount. [SP=43.85 Cap=94m]
In line: Aquila Services (LON:AQSG)
Mirriad Advertising (LON:MIRI) placing was £23m, not £3m.
from the RNS:
the Company has conditionally placed 57,600,000 Placing Shares at an Issue Price of 40 pence per Placing Share raising gross Placing proceeds of approximately £23 million.
Benchmark Holdings (LON:BMK) reported full year numbers today. Management are presenting to investors at 12pm today
https://zoom.us/webinar/register/4016064624924/WN_fqvcYVciQfmeR7MwP9D9oA
hi Paul, will you be listening in on the RCH conference call at 8.30am.
Thanks
Mark
Morning Mark,
No I haven't got time to listen in to the RCH conference call, as there's such a long list of companies for me to catch up on today, so I'd rather focus the time on rattling through those.
But I will review the trading update, I know it's a stock that lots of readers like, and we've discussed the bull & bear case here before.
Regards, Paul.
Will you be looking at Reach (LON:RCH)?
Yes.
a very poor quality/confusing trading update IMO. Why cant they just say what the numbers are rather than stating percentage changes (on what?) and referring vaguely to expectations.
Re £RCH Yes, I'm a bit surprised to see the price up 4% on the back of that and I've sold up and taken my profit.