Small Cap Value Report (Fri 29 April 2022) - BEG, SAA, UPGS, AO., CAR

Good morning, we have Paul & Roland here today, reviewing small cap trading updates & results. Today's report is now finished. We hope you enjoy the long weekend!
Agenda -
Paul's Section:
Begbies Traynor (LON:BEG) - Reuters reported yesterday that insolvencies have soared, as expected, with the withdrawal of covid support measures meaning large numbers of zombie companies are likely to need restructuring or insolvency. I haven't read it yet, but today sees Begbies publish its Q1 Red Flag Alert Report, always an interesting, if depressing read. It strikes me as illogical that BEG shares have sold off along with other small caps lately, given that it is limbering up for a probably multi-year bonanza of work. So at 110p per share, I think readers could do well on this one, and get a 3% divi too. I don't currently hold, due to lack of available funds, unfortunately. [No section below].
Up Global Sourcing Holdings (LON:UPGS) - I have a good rummage through its interim figures out today. Decent results, boosted by a large acquisition last year. I'm not so keen on the big increase in bank debt, which has continued in H1 despite the acquisition financing going through last year's accounts. The low operational gearing is interesting, and should mean profits being resilient, even in a downturn. Very interesting comments about supply chain/shipping improving. Overall, I like it.
Carclo (LON:CAR) - a mixed update, which is in line with exps for FY 3/2022, but with some negatives in the outlook comments. Not enough detail to help me form a firm view. Bank debt & pension scheme are still problems. High risk.
Roland's Section:
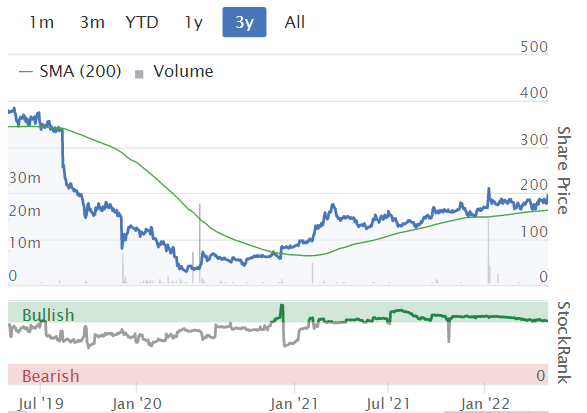
M&c Saatchi (LON:SAA) - a strong set of 2021 results from this advertising group. Trading performance seems strong and management have issued confident profit forecasts suggesting double-digit growth in 2022 and 2023. The valuation doesn’t seem unreasonable to me, either.
Ao World (LON:AO.) - a major profit warning from this appliance retailer, as customer demand weakens and the rising cost of living starts to bite. Liquidity concerns are growing and AO’s founder-CEO has decided to start selling his shares. One to avoid, I think.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Up Global Sourcing Holdings (LON:UPGS)
143p (pre market open)
Market cap £128m
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its interim results for the six months ended 31 January 2022.
A strong performance in a challenging environment
H1 revenue is £85.7m, growth of 13.7% - mainly due to the acquisition of Salter in July 2021, so it contributes to H1 this year, but was not part of the group in the prior year comparatives. Salter was a sizeable acquisition, at £32m, around a quarter of the current market cap, part-funded with a £15m placing.
Underlying profit before tax is up 28.6% to £9.9m - that’s a decent profit margin of 11.6%, surprisingly high, given the gross margin is low at 24.4% - suggesting that UPGS is efficient at moving things from A to B. Note also that it plans to introduce automation, to improve margins - that’s the sort of thing I’m looking for, i.e. businesses which are responding to higher costs by becoming more efficient using technology.
Seasonality - note that there seems to be an H1 bias to profitability, judging from last year’s numbers. This is confirmed in note 8.
Online - previous company presentations have stressed that online growth (direct to consumers) was a key aim, but there’s been a setback in H1, with negative organic growth of -11.9% (more than offset by the Salter acquisition). This is blamed on shipping disruption causing tighter stock availability. It sees this as a “temporary set-back”.
Outlook -
The Board anticipates a full year performance in line with current market expectations.
Supply chain - since UPGS is a big importer from China, its comments here should be relevant to many other importers, and are a lot more upbeat than I was expecting -
The Group has so far been unimpacted by the recent lockdowns in China, but continues to monitor the situation closely. The Board is confident in the Group's ability to navigate its way through any further lockdowns in the region, having done so successfully at the beginning of the pandemic…
During calendar year 2021 ('CY 21') and calendar year 2022 ('CY 22'), global shipping capacity was severely constrained because of worldwide port congestion. The drop in capacity caused a substantial increase in the cost of shipping, leading to downward pressure on gross margins, albeit we were able to offset this by actions elsewhere (see below for more commentary).
While shipping remains a challenge for the business, there has been an improvement in availability and reliability during CY 22. We believe that the Group has dealt with the shipping crisis and indeed the wider supply chain crisis much better than its peers. As the situation continues to normalise, we see this providing upside to the business in the medium-term through the reversing of the downward pressure on margins that it represented and the additional revenue opportunities that will arise from improved stock availability.
Valuation - thanks to Shore Capital for an update today, on Research Tree, there’s also a note from ED available.
Shore forecasts 13.7p adj EPS for this year (FY 7/2022), which should be fairly accurate as we’re most of the way through this year. At 143p/shares that’s a PER of only 10.4 - seems good value to me, but it depends on how you view the macro picture. If you think a recession is coming, then earnings could fall. Although recessions don’t last long these days, because Govts & central banks are aggressive with their stimulus measures. So company earnings would probably then recover quite quickly.
However, we’re in amazingly short-termist markets, seemingly dominated by traders not investors, so at the moment nobody seems to be thinking about the longer-term. Which provides nice buying opportunities, getting good companies valued on low multiples, if you’re prepared to be patient - which is meant to be the whole point of owning shares. Still, nobody owns the market, and we just have to deal with whatever the flow of money happens to be doing at the time. One person’s panic/despondent selling, might be someone else’s future multibagger, in some cases. The tricky bit is working out which shares fit that profile!
Balance sheet - a key focus at present, as I definitely don’t want to be owning shares in companies with too much bank debt.
UPGS had negligible intangibles on its balance sheet, but that rose to £36.9m in H2 last year, due to acquisitions (mainly Salter). There’s a danger that might weaken the balance sheet by making it top-heavy.
Net bank debt is £30.1m, which feels a bit too high to me, going into a potential downturn.
NAV is £38.2m, reducing to NTAV of just £1.3m if we write-off intangible assets, which I nearly always do.
I’m not ringing the alarm bells, just pointing out that bank debt is quite high for me, and I’d like to see the company retain earnings to reduce debt, just in case there is a recession.
Cashflow statement - isn’t great. A lot of cash has been absorbed into working capital in H1 - with big rises in inventories & receivables, and no corresponding increase in trade payables. It doesn’t look seasonal either, as the prior year H1 comparative was neutral.
I can see the sense in increasing inventories, to ensure decent supply. It’s worth raising this issue with management though, in any discussions.
Note that the large acquisition, and associated funding (debt & equity) went through last year’s numbers. Yet in H1 this year, a further £11.5m net bank debt was drawn down. So there’s a bit of a question mark over bank borrowings.
Going concern note - remember these have to be approved by the auditors, so are very useful, and essential reading.
In this case UPGS says even in a severe but plausible downturn, it would remain within its existing bank facilities and covenants. So that reassures on my above concerns. Although it doesn’t reveal what the assumptions are in that severe but plausible case.
Divis - there's a c.5% yield - maybe too high, given the level of bank debt?
My opinion - I like UPGS, it seems to be well managed, and the valuation looks decent value. My one reservation is that bank debt looks a bit high.
UPGS proved it’s skill at managing supply chain in the pandemic, so there’s no reason to believe it’s likely to come unstuck with current problems seemingly worsening in China, due to its bizarre zero covid policy, causing shutdowns.
We don’t know what impact the disposable income squeeze is likely to have. Although selling mainly small ticket household appliances, which are often bought when the old one breaks (e.g. kettles), I imagine UPGS should do OK in any downturn.
Also, as UPGS’s gross margins are low, there’s not much operational gearing to worry about. If we stress test today’s H1 P&L by reducing revenues by 10% (£8.6m reduction), this would only reduce gross profit by £2.1m. Leaving all other costs the same, would reduce PBT from £9.8m to £7.7m - hardly a disaster.
Try doing that same manual recalculation to businesses with high gross margins, and the results can be horrific! A 10% drop in revenues could wipe out profits entirely at some businesses with high gross margins. That’s why, with uncertain demand, likely to fall, there’s an argument for investing in well managed companies with low gross margins (providing they can pass on price rises), because their profits could be more resilient in a downturn. As always though, it’s not that simple, and every company is unique.
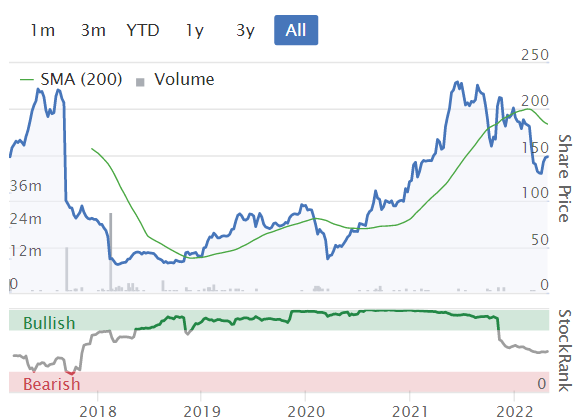
Whilst I’ve been typing this, UPGS shares have risen 8% to 155p, which looks justified. In current market conditions, I’m not inclined to chase it any higher. Long-term though, I reckon this company could continue to do well, so it looks a sensibly-priced long-term hold, providing nothing goes wrong again (look at the chart from 2017-18.
.
.
Carclo (LON:CAR)
24.75p (down 9% at 09:25)
Market cap £18m
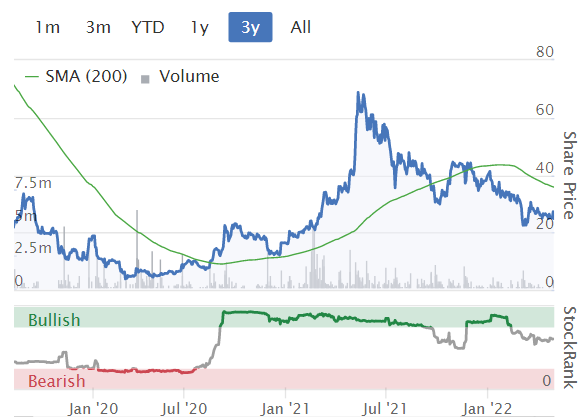
Background - This has been an interesting, very volatile mricro cap. It almost went bust in the pandemic, but staged a convincing recovery, shares then overshot on the upside, and it’s now back down more than half the way, like many other small caps, it has to be said.
I reviewed Carclo’s interim figures here in Nov 2021, noting a good recovery in performance, and lower risk, but a pension fund that was still sucking £4m p.a. out in cashflows for deficit recovery - very big for the size of company, and ruling out divis.
On to today’s update -
Carclo, a global manufacturer, principally of fine tolerance injection moulded plastic parts and aerospace components, today provides an update on trading for the financial year ended 31 March 2022 ("FY 2022").
It’s in line with expectations -
The Board is pleased to report that the business expects to report a strong performance for the year, with revenue growth ahead of, and underlying profits in line with, its expectations despite the challenging macroeconomic backdrop.
In addition, the Group balance sheet has strengthened considerably throughout the course of the year, in part driven by a reduction in the IAS 19 pension deficit. We have continued to invest in capital equipment to support long-term growth, largely financed by an increase in net debt.
Labour shortages & “significant cost inflation”
Cost increases can “largely” be passed on to customers, “albeit with some time lag” - this impacted H2 margins.
“Tripartite Agreement” between the company, Bank, and Pension Trustees - I don't like the sound of this - it's a reminder that equity is the weaker element, and may not necessarily be in control of the outcome here, if attitudes become less co-operative at the bank or pension scheme. So we can’t rule out equity dilution yet.
Outlook - mixed - and this could be interpreted as an H1 profit warning maybe?
Demand in the Group's key markets remains strong coming into the new financial year and this underpins continued confidence in strong underlying revenue growth. However, the Group is seeing significant headwinds largely due to the continued impact of COVID-19, in particular in our China and India operations. In addition, we remain mindful of the general market uncertainty related to the impact of the war in Ukraine.
The margin pressures that have been experienced in the CTP division in the second half of FY 2022 are expected to continue into the new financial year and it is anticipated that trading in the early months of FY 2023 will remain challenging.
A number of initiatives are underway to mitigate these impacts with the benefits of these making an increasing contribution to margins over the course of FY 2023.
For the Aerospace division, the strong order intake in Q4 and the increased focus on business development positions the division well for FY2023, with further growth expected in the current year and beyond.
My opinion - the way I read this, Carclo sounds as if it’s still financially distressed, but has very co-operative pension trustees & bank.
If things work out well, then equity could be a multibagger, as it gets all the upside.
If things turn sour, then equity could be diluted or wiped out - that’s the risk you take with highly geared companies.
Another issue is that the accounting pension deficit might have come down (we’re not told how much though), but that doesn’t necessarily feed through to the actuarial deficit, which is the more important number, because that drives what the cash outflows are.
Overall then, I would need to see the numbers before being able to properly assess this share.
So far, management has done very well to protect equity holders from dilution, with no new equity issued since 2018. If that can be maintained, then the % upside could be large. Risky though. Readers can make up your own mind whether you’re prepared to take on a high level of risk, for a share that could be a potential multibagger if things go well, or a disaster if things go wrong.
.
.
Roland’s Section:
M&c Saatchi (LON:SAA)
Share price: 200p (+12% at 08.40)
Shares in issue: 122.3m
Market cap: £219m
2021 Full-year results & profit forecasts
“The strong trading performance and momentum in 2021 has continued into the first quarter of 2022.”
Advertising group M&C Saatchi appears to be delivering a convincing turnaround. Today’s results show a strong recovery, with record headline profit and an improved net cash position.
New profit forecasts indicate that management expects momentum to remain strong in 2022 and 2023. Let’s take a look.
Financial highlights: Today’s results cover the year ended 31 December 2021.
- Revenue up 22% to £394.6m
- Net revenues (excluding pass-through costs) up 10.6% to £249.3m
- Pre-tax profit of £21.6m (2020: loss of £8.5m)
- Earnings per share of 10.5p (2020: loss of 9.1p)
- Net cash: £34.4m (2020: £32.7m)
Saatchi’s operating profit margin rose from -2.2% in 2020 to 10.9% last year as the group made a strong recovery from the pandemic and its own issues.
Dividends/net cash: The group’s balance sheet appears to be very strong and dividend payments are expected to resume in 2022.
However, I think it’s worth remembering that Saatchi still faces significant potential cash liabilities from historic share-based incentive arrangements with senior management who are minority owners of group subsidiaries.
According to today’s results, potential payouts of between £38m and £67m could be due between now and 2028, depending on Saatchi’s share price.
These payments are now being settled in cash, rather than shares, reducing the risk of dilution. But they place an additional burden on the group’s cash flow.
Trading highlights: The company says it’s won valuable new business and deepened existing relationships. These are some of the examples given:
- New business: PepsiCo, WHOOP and Mondelez
- New campaigns: Uber, De’Longhi and Franklin Templeton
- Expanded relationships: Reckitt, GSK, Lexus and Sonos
- Retained UK and US government contracts
The company’s new structure is based around the idea of specialist areas, all supported by a central core (‘Central Fuel’) that provides data and technology capabilities. All of the group’s divisions reported LFL net revenue growth last year:
- Advertising & CRM: +6% to £121.2m
- Media & Performance: +39% to £32.8m
- Global & Social Issues: +10% to £33.2m
- Brand & Experience: +17% to £30.9m
- Sponsorship & Talent: +35% to £24.5m
Trading update/profit forecasts: Current trading is said to be strong. Somewhat unusually, the company has issued the following profit forecasts today:
- 2022 headline pre-tax profit c.£31m (+15% vs 2021)
- 2023 headline pre-tax profit c.£41m (+32% vs 2022)
The comparative figure for 2021 was £27.3m, so these forecasts appear to suggest double-digit percentage growth over the next couple of years.
Takeover situation: Talks are said to be ongoing with Vin Murria and her vehicle AdvancedAdvT Limited. The deadline for an offer has been extended to 10 May, but no further offer has been made as yet. Paul covered this situation in January.
My view: There are a lot of moving parts here, but my feeling is that CEO Moray MacLennan is making good progress at simplifying and modernising this business. Cash generation seems good and the balance sheet is strong.
Today’s results price Saatchi shares at 16.5 times trailing earnings. Given the rate of growth being forecast by the company, this doesn’t seem unreasonable to me. I suspect that consensus forecasts will be updated following today’s revised guidance – I’ve not been able to find an updated broker note on Research Tree this morning.
One question mark for me is over the broader economic outlook. A widespread slowdown could dampen spending in some areas.
However, Saatchi’s larger FTSE 100 rival Wpp (LON:WPP) also remains positive about the year ahead and recently upgraded its own revenue guidance. So perhaps there is not yet any sign of a slowdown.
I’d need to do more research on M&C Saatchi to form a strong view. But based on today’s results and the company’s guidance, my impression is that the valuation and outlook for this stock could be favourable.
Ao World (LON:AO.)
Share price: 71.7p (-18% at 08.40)
Shares in issue: 479.5m
Market cap: £388m
Today’s full-year trading update from electrical retailer AO World claims a “resilient UK performance against a challenging backdrop”. But this is actually a major profit warning, with cuts to both revenue and EBITDA expectations.
To round things out, AO has also announced that founder-CEO John Roberts plans to start selling his shares.
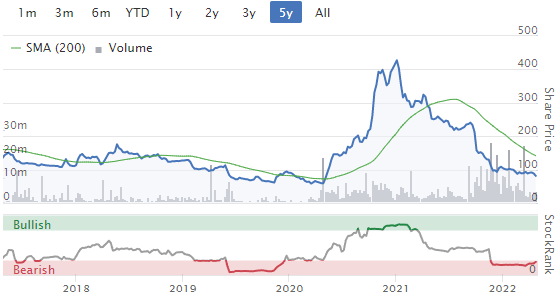
AO shares experienced a dizzying ascent to mid-cap respectability when online retail boomed during the pandemic, but they have since fallen back to earth.
Today’s statement has left me wondering whether the group’s financial situation could soon start to look precarious as well.
Key financial figures: AO says that full-year revenue for the year to 31 March 2022 is expected to be £1,557m. That’s around 6% below FY21, which included peak lockdown trading.
Today’s FY22 revenue figure is also below consensus estimates of £1,599m.
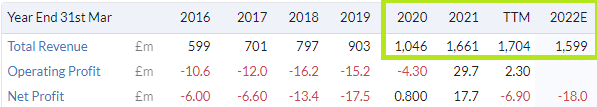
As a result of reduced revenue, group adjusted EBITDA is now expected to be £8m.
H1 EBITDA was £5m, so this tells us that AO’s EBITDA fell by 40% to £3m during H2.
Today’s figure also appears to be well below previous expectations. One broker forecast I’ve been able to find elsewhere suggests the company was expected to generate around £11m of EBITDA in FY22.
Clearly, AO World will remain loss-making at an operating level and below. I also expect to see negative free cash flow for the year.
Trading summary: To its credit, AO appears to have held on to most of the market share it gained during the pandemic. The company says its share of the major domestic appliance market is now 54%, compared to 43% pre-Covid.
Despite this, revenue is falling as customer shopping habits change in response to the easing of the pandemic and the rising cost of living.

UK: H1 revenue was said to be resilient, but problems emerged in H2. AO says that “customer demand progressively weakened”. This was compounded by supply chain problems which affected stock availability.
A second problem was that extended warranty cancellations have risen as customers have looked for ways to save money. As we’ve discussed here in the past, extended warranty sales have always appeared to be AO’s main source of profit. Margins on its product sales are typically somewhere between wafer thin and non-existent.
Germany: AO says that in Germany, customers have returned to stores to a greater extent than expected. I think it’s interesting to see that shopping habits are still varied across Europe. My understanding is that online retail penetration is still lower in most of Europe than in the UK and USA.
A strategic review of the German business is ongoing.
Net debt/liquidity: AO says its net debt excluding lease liabilities rose from £10m on 30 September to £32.8m at the end of March. Lease liabilities total £101m.
Available liquidity was £50m at the end of March, but this has now reduced due to seasonality. The company says it’s taking steps to improve cash flow in Q2.
This situation does not seem ideal to me, especially as we learn that founder John Roberts has decided that he wants to start exiting this investment.
Founder share sales: CEO John Roberts has decided to start disposing of his shares in AO World. Over the current financial year, he plans to sell £5m of stock from his holding of 107m shares (22.4%).

Outlook: AO says that it’s facing cost inflation, supply chain issues and weakening consumer spending. As a result, management are cautious about the near-term outlook for revenue and profit.
Over the coming year, the business plans to focus on cash generation to strengthen the balance sheet, while cutting costs where possible.
Sightly worryingly, full-year results are now expected to be delayed.
My view: Although I think the group’s pricing and service is attractive as a customer, AO is only a box shifter competing with much larger rivals. Now that revenue growth has stalled, its lack of profitability and cash generation has become a bigger issue.
Mr Roberts says he’s still confident in the long-term prospects of AO’s business model. But his decision to start selling the shares when they are near record lows suggests otherwise to me.
I have never seen much reason to invest in AO World, but after today’s statement I view this stock as uninvestable.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Interesting that the top 5 most shorted companies (caveat: declared shorts) are now all Consumer Discretionary type companies. The shorters are really bearish on UK Consumer discretionary spending this year.
(Caveat, some on the list like Cineworld and Boohoo have been on the top list for months, even before the latest bearish stats on UK consumer confidence and inflationary impacts on spending).
With Up Global Sourcing Holdings (LON:UPGS) and the rise in inventories, is the company necessarily in possession/control of all of this, or could a significant proportion be in transit, perhaps closer to China than the company might like? No idea whether this is the case.
I see Headlam (LON:HEAD) has been drifting down, ex div next Thursday for 26p final and special divis.
Was expecting a nice rise in to next week, looks like i was wrong again! Markets may be up past couple of days, but most of my small caps treading water or dropping. Just no volume or liquidity out there for most...
Same boat John, the FTSE rise defies my portfolio.. down 2.5 percent this week, and as you say poor liquidity.
I see a few other sensible comments on Begbies Traynor (LON:BEG) to add to Paul's, and there was an ED note published on Begbies a few days ago - it covers the UK Govnt insolvency stats and keeps a fair value of 165p/share. Here if you missed it: https://www.equitydevelopment....
Agree with you Roland and Paul about Ao World (LON:AO.) I wouldn’t touch it. Besides the facts that the ceo is selling and that the business model is poor where the only time it has managed to make a profit was because of lockdowns due to covid, the retail sector is bound to take a knock in the coming years as people start to tighten their belts due to a recession coming.
Thanks Paul for the analysis on Ao World (LON:AO.) (I hold)
I highly recommend the analysis of them by Gary Channon on page 3 of the latest Aurora Investment Trust factsheet: https://www.aurorainvestmenttr...
This prompted me to look at John Robert's a little closer. I found listening to this recent interview persuasive that John Roberts is somebody I would want at the helm of a company I had shares in.
Hi harrymunro,
The Ao World (LON:AO.) section today was from Roland, not me. If I'd written it, my conclusion would have been similar to Roland's, that the share is now uninvestable, although I'd have expressed it more emphatically I think!
It's a terrible update, and it looks to me as if the business could be heading for serious trouble. So I would definitely not want to hold this share, it looks to me like something to get out of, whilst you can.
You commented -
John Roberts is somebody I would want at the helm of a company I had shares in.
I assume you're being serious? My view is the complete opposite - over the years I've followed AO he's struck me as delusional, and now with a terrible track record. In my view, the whole business could need a restructuring, to strip out a lot of costs, and maybe a refinancing, so equity dilution probably.
Definitely not one for me!
Regards, Paul.
Entirely serious from my end - good to hear your perspective :)
£UPGS
Their negative operating cash-flow due to receivables is not a negative indicator (assuming credit risk remains low - which reasonable given customer base). It may even be a positive indicator in that it shows an increase in run rate demand from customers.
The lower positive contribution from payables may be an interesting point to pick up on. Through covid period UPGS working capital and so short term cash flow benefited from Chinese manufacturers being generous on payment terms and timing. Given what's going on in China at the moment maybe their manufacturers are looking for the favour to be returned?
The dividend raise hints that there is no credit concern...obvs you need to trust management to make that inference (I believe mgt have shown themselves to be straight).
Valuation looks cheap relative to what they have proven over time. It seems to me that UPGS is a stock where many are quick to price macro risks through it...definitely has some, but the risks are quite priced in whereas for other stocks they are not (meaning that if the macro risks come to fruition downside may be greater elsewhere).
Hi mojomogoz,
Good points! As you suggest, sometimes there are good reasons for companies to increase working capital, it's not necessarily a bearish sign. I worry more when companies report negative cashflow, year after year.
Paying its Chinese suppliers more quickly looks very sensible, as factories will almost certainly priritise faster paying customers, in hard times, as you say.
The other thing is that the acquisitions will have only contributed part of the year, but the full balance sheet values are reported. That can distort things too.
Regards, Paul.
Yeah. In some respects its return to normal pattern with trade related finance being used again -> £11m invoice discounting from zero H1 last year and import loans up to £7m from £4m -> this explains the debt increase.
In general, when trade finance goes up for Up Global Sourcing Holdings (LON:UPGS) it's an indication that business is growing. (Note I believe they insure near 100% of this too) though in current environment it could also be due to rise in shipping times.
I believe the concerns expressed in comments above re debt by some are missing the point particularly with trade linked finance. The risk to UPGS is an economic softening that sees retailers stop ordering. The post IPO hiatus was linked to this (and that they had a lot of channel stuffing in discount retailers who had been growing like a weed so UPGS stocking store openings and then paused eg B&m European Value Retail Sa (LON:BME) ).
Agreed. I think the net debt increase on receivables is explained well and should reverse fairly quickly in H2: "Increased trade receivables are attributable to higher overall revenues, the later timing of these revenues with December 2021 being a particularly strong month compared to normal, and higher debtor days due to the increased mix of supermarket business, where payment terms are typically longer." The business is highly cash generative, so with the Salter deal done, net debt should fall quite quckly. I think the CEO is fantastic here and he's built a great business and team. Lots of potential still on numerous fronts. Petra sounds very promising in Germany.
Yes. I like mgt and the model they've made. I think its quality/durability and 'category killer'-ness is underestimated. The world just thinks they are a dressed up market stall trader ;)
There's going to be some volatility to revenue (no forward purchase agreements from customers but the upside of that is it protects their margin as they are not squashed into the margin demands of retailers) -> so price will have volatility too.
But I HODL on in the belief that this business will grow meaningfully over time and mgt/founders are entrepreneurial and young enough to have many years of drive and hunger.
Bank Holiday viewing/listening! The latest Sell it to The City. Who sells their stock pick to the panel of Fund Managers: Andy Brough, Schroders, Judith MacKenzie, Downing and Stephen English, Stellar Asset Management? Excellent pitches of Integrated Diagnostics Holdings (LON:IDHC) Fonix Mobile (LON:FNX) and £XAR. Two companies will get a call from the Fund Managers. Who wins? To be honest, I think all 3 deserved to win. The Fund Managers were really impressed. (Richard Crow/Cockney Rebel knows more about Xaar than Andy does ... Andy owns 28%!) We loved it because it shows the capability of retail investors, which is sometimes this is overlooked. Compelling , fun and educational, for any investors. Video & podcast.
We have a few webinars coming up in May, here is the first for income seekers (more to follow next week): Allia /RBC: RBC is a platform, created by Allia, to connect responsible investors with social enterprise borrowers. They offer bonds yielding 3-5% with the investment going to organisations that provide a clear social benefit, such as helping to provide care for the elderly, supported housing for people with a learning disability, affordable homes, places of beauty, etc. Various speakers include RBC, the issuer and an institutional investor to give a perspective from each.
Date: Tuesday 17th May 2022, 3pm. To attend register here.
Anglo-eastern Plantations (LON:AEP) rns out today at 9am for FY 21, £340m mkt cap, £173m cash, no debt, rev $433m, profit before tax $133m. Divi of 5 cents! Share price 861p.
Anglo-eastern Plantations (LON:AEP) rns out today at 9am for FY 21, £340m mkt cap, £173m cash, no debt, rev $433m, profit before tax $133m. Divi of 5 cents! Share price 861p.
Market is currenyly spooked by the Indonesian government banning palm oil exports, as noted today by M P Evans (LON:MPE):
https://www.investegate.co.uk/...
You'd think this is probably temporary, and the price of palm oil has soared due to the restrictions around Russia and the problems around Ukrainian agricultural production. There's a risk is that these companies get dragged into the government's price fixing inquiry, but that's a complete unknown,
timarr
Timarr, I wonder if as global raw materials becoming tighter, we run the risk of countries, particularly in the developing world banning exports more generally?
I do understand its going to become very difficult for countries to watch their own population pay elevated prices or go without while the rich west takes it away.
Maybe a sign of things to come....
Thanks for your comment on Begbies Traynor Paul. Useful note. I really like the Company but have never bought them because Govts rise and fall on jobs and therefore they provide a lot of support for failing businesses, or that has been my experience certainly in recent years. So whilst it is a contracyclical play it has a wind blowing against it. Certainly their commentary suggests good times (for them!!) ahead but they also note the Govt options to help out. It might be this time as ever I am not clever enough to know.
Well the government can't support these zombie, loss making companies forever. The treasury itself is now facing massive pressure due to the rising deficit, slowing growth and higher borrowing costs - they are painfully aware that if they don't take some tougher measures then things could really get out of control - that's why they are pushing ahead with painful measures such as tax and interest rate rises, and the resumption of the normal insolvency processes. Begbies Traynor (LON:BEG) and Manolete Partners (LON:MANO) both should do well in this environment unfortunately.
£UPGS
Well both profit and negative cash can be true. The problem seems to be obvious from a closer look at the balance sheet, this shows that both stock and debtors have increased significantly. I guess overstocking in face of supply chain difficulties is sensible and I don't know if carrying nearly 1.5 months sales as stock is right, but I am a bit alarmed by the increase in receivables, which is getting up towards 3 months sales. I see creditors has not moved. So it seems to me that the cash has gone on stock and extending credit.
Interested for views on Ao World (LON:AO.) and £ROT. The former is getting pasted in the markets this morning. The CEO is selling a small number of shares but I suspect this is to support his charitable work rather than wanting to get out of the company. They are experiencing coming off the COVID high and the market hates it.
Nice little acquisition at Rotala.
I hold both and will be topping up Ao World (LON:AO.) now.
Also one thing I have learned recently to get an insight into some companies' performance: if they use automated Trustpilot reviews you can go into their page on Trustpilot and look at how many reviews they are getting through that system. Given review requests are automated and assuming a fairly fixed response rate (not sure how solid an assumption that is) I think this services as a nice proxy for how well their sales are doing.
Take AO as an example - their review numbers are basically flat or even slightly higher compared to the same time last year:
Compare that to a different online retailer Gear4music Holdings (LON:G4M) and you can see their online reviews are 30% lower than the same time last year, and the historical trend going into Summer is further decreased numbers, which was a big red flag for me.
You can access these by clicking on the see all button here on a company's Trustpilot page:
I have been shorting AO. for a while now and even I think that 19% down seems an overaction to the RNS which I thought was no worse than expected (if anything slightly better). It will be interesting to see if some of the short positions are removed from AO. currently at 4.05%. Would I buy AO. now? No, I see it getting squeezed with consumer spending, too many headwinds and debt IMO.
i agree - where do you see the current % of short positions ?
ADVFN - Top lists..but I think you can google for a current short position on a company.
The top lists on ADVFN are good. Show 'Most Shorted', 'Most Increased' and 'Most Decreased'
thank you
shorttracker.co.uk
thank you
Interested for views on Ao World (LON:AO.) and £ROT. The former is getting pasted in the markets this morning. The CEO is selling a small number of shares but I suspect this is to support his charitable work rather than wanting to get out of the company.
The trading update is the issue, I think. 6% YoY revenue decline and a vaguely downbeat outlook:
In view of the volatile market conditions, inflationary cost pressures and logistical challenges in the supply chain, together with the escalating cost of living for consumers, we remain cautious about our revenue and profit outlook in the near term.
https://www.investegate.co.uk/...
There doesn't seem to be anything surpising here, but the market is not forgiving at the moment. And perhaps there's a read across to the results at Amazon last night.
timarr
Ao World (LON:AO.) It's probably this bit that's spooked everyone:
While the picture has subsequently improved, data received subsequent to this trading update and prior to the Full Year Results announcement scheduled for later this summer could result in a reassessment of the carrying value of the contract asset, which could lead to a material impact on FY22 profits.
That is a very useful tool, and would have flagged the slowdown in Gear4music Holdings (LON:G4M) (although in hindsight it should have been fairly obvious given the consumer backdrop and the earlier spike in sales).
Morning Paul/Roland,
Hopefully the red flag report from Begbies Traynor (LON:BEG) will have a positive read across for K3 Capital (LON:K3C), whose share price has continually dripped lower these past few weeks, for some inane reason! Like a lot of small caps i guess!
I agree, I bought a small opening stake in K3C yesterday..seem very cheap to me. Although to be fair many of the recent gains made across the board have been wiped out, so see many a share looking cheap ATM.
I suspect that there is not a positive read across for K3 Capital (LON:K3C) from £BEG (I hold both). K3C are not insolvency practitioners, they make their money from M&A involving healthy growing companies. The volume and value of M&A has historically been correlated with economic expansion, easy credit and strong stock markets, not the climate we are entering. I can see lots of good reasons why K3's share price should be correlated with the small cap market and I don't think any of those reasons are inane. K3 may be good enough to buck the trend, but it is a trend that's likely to be hurting them, not helping them.
"I suspect that there is not a positive read across for K3 Capital (LON:K3C) from £BEG" (I hold both) - not sure I agree, although holding both is a safe option!
K3 Capital (LON:K3C) I wonder what the future economic outlook will do for the restructuring division which is the biggest in terms of size and growth? H1 2022 : GDP 16.6m (H1 2021 : GDP 9.5M)
As margins are squeezed companies will look to become more efficient and streamline which often means cutting staff.
Their last RNS states - 'Restructuring Division is pleased to see that the insolvency market is showing signs of recovery following the withdrawal of government support and the unwinding of legislative change'.
Perhaps K3 Capital (LON:K3C) portfolio gives them more balance, but they currently appear weighted towards restructuring which could be a tail wind from current lows?
Time will tell.
I agree with much of that, but one reason for my original comment was that their restructuring division relies on the ultimate success of their clients e.g. K3 provides funding to them. In contrast, with BEG it's a question of the more basket cases the better. With restructuring in a downturn, there may be more potential customers but there may equally be more risk. Personally, if I was taking on a troubled company as a customer, I would rather do it in a growing economy than a shrinking one. How this translates for K3 probably depends on how they select their customers and how they secure payment.
Are you not missing out that K3 Capital (LON:K3C) own Quantuma?
Source: Begbies FY20 Results Presentation.
I'm confused on your K3 Capital (LON:K3C) comments....there is not a great difference between Begbies Traynor (LON:BEG) and Quantum and both have countercyclical properties. In addition, both Quantuma and BEG broker finance to companies but neither do it directly on book (its purely part of advisory services). Quantuma has shown great growth in a tough environment too. Simplistically it looks a superior operator to the big legacy BEG. IMO BEG is over liked for its 'countercyclical' properties but it always seem a touch mañana waiting for the good times -> I know its been decent operational and stock price performer in recent years but the expectations seem to always run ahead of it a bit IMO. And now with earning estimates high based on 'tough times' being here the stock is a clear buy the idea sell the fact risk as it needs to be in a cycle of beating estimates to sustain multiple and push into the teens on p/e.
By comparison, the restructuring biz of K3C is not highly priced despite its very impressive underlying growth (and they have invested in that growth so short term deflating margin) and then the tax and corporate finance divisions are higher margin and both growing. The rating on these high margin growing businesses is very low. Maybe this reflects expected cyclical headwinds? For tax they are likely to be very muted at most to likely non existent (policy around R&D tax breaks more important and that is likely to be supportive). For corporate finance its harder to predict but a combo of brexit and covid has acted as a long term hinderance already and there is probably a decent supply of people wanting to sell small businesses (very different dynamic for listed M&A). K3C management say they think they can have good environment for corporate finance and restructuring going forward and I think this is a reasonable expectation.
The thing that probably weighs on K3C shares is that they have acquired quite a lot in recent years and they have ambitions for more. I believe management have shown they can do this well and that it is a good strategy for this business....but it's a short term environment where scepticism wins. I've got a hunch that they are going to expand overseas in near future and I see this as a good thing as I believe their financial services model to be a category killer.
I own and have bought on weakness. I might wear some more short term pain if they go for a big acquisition and dilute to do so (paying dividends and share issuance to finance acquisitions really does irritate me -> British disease!...plus a couple of founders own a lot of stock and no doubt like the big pay day). Regardless of negatives and short term market volatility I feel confident that I will have meaningful gain on my holding.
Stocko comparison between two is interesting and I believe understanding the underlying dynamics shows K3C to be far superior prospective investment
https://www.stockopedia.com/co...
Nightcap (LON:NGHT)
This company certainly looks like it has "potential" - probably hard to justify on anything other than "growth potential" but they certainly seem to be trending very nicely with regard to sales - q3 sales of £9.6 mill . can we use that as an ARR figure if we do they are possibly already at £40 mill - with expectations for next year of only £44 mill looks like they could blow that number out of the water if they keep growing. To me there is plenty of potential at present for "pop up type" drinking places that can be very profitable - take an empty pub car park turn this into large outside drining area - charge £6 quid a pint and 2 cocktails for £12 quid and the masses will come pouring in. Compare that to some like revolution with expensive long term leases and expensive refurbs. Not sure exactly what thne mix is here but they have £7 mill cash in the bank and are expecteds to turn profits next year. Note they only have 1/3 of the turnover of reolution but if they can make the same profit as revolution from 1/3 of the sales which will be the better business?
Not fully sold on the story at present - am sitting on the sidelines but it does look interesting if they can deliver numbers "ahead" of current expectations - that would be the sign to me that management are doing well.
Nightcap (LON:NGHT): certainly interesting that all bar stocks are doing well except for £RBG. Think Paul has a large holding, perhaps he can enlighten us.
Hi rmillaree,
Just to pull you up on one point -
Compare that to some like revolution with expensive long term leases and expensive refurbs.
Actually, Revolution Bars (LON:RBG) (I hold) got out of all problem sites by negotiations, finished off with a CVA. So they don't have any problem leases now.
The refurbs are not expensive. Typically £200k (compared with £1m full fit out), and produce a strong upturn in profits. RBG is doing something like 19 refurbs this financial year, about a quarter of the estate, which should enable it to produce a good performance, even as consumers retrench. I don't think its younger customer is likely to be impacted much by inflation, because their wages are probably rising fast enough to offset inflation in that age group. But we'll see!
Nightcap (LON:NGHT) looks appealing in some ways, but it has a premium for newness, and in time its new fit outs will deteriorate, and LFLs turn negative, then it will probably be the laggard in a few years' time.
Must admit, I'm very much cooling on the whole hospitality sector.
Regards, Paul.
Revolution Bars (LON:RBG)
Cheers Paul - cretainly you are right ref your specfic highlighted items ref what Revolution are paying at present - that cretainly seems reasonably good value what they are doing there with regard to payback times. I would also agree at present its also a bit (more than a bit?) "uncertain" ref hospitality - i suspect the well oiled and run ones will be just fine but it may be tough going if peeps have less money and may be tempted to spend that money overseas rather than here. I have my long term holding in Wetherspoons and Marstons which are really performing poorly anyway - so perhaps i don;t need any more sector exposure here.
Nightcap (LON:NGHT) has char grilled £1.8m in just 14 weeks. Also the Q3 LFL rev up 28% on 2019 is not adjusted for the 5% VAT rate which has now ended.
Nightcap (LON:NGHT) has char grilled £1.8m in just 14 weeks. Also the Q3 LFL rev up 28% on 2019 is not adjusted for the 5% VAT rate which has now ended.
Sales are up 52% on the 2019 comparatives - fast growth costs money - so i dont think anyone should be surprised they are burning through the cash at a fast lick at specific times of the year - opening up new sites costs wonga. They have £7 mill cash in the bank and expect to be profitable this year and next if stocky is to be believed (keep an eye out for exceptionals !!) - to me they seem reasonably adequately funded to keep pushing forward. The great thing about pubs is that once they are up and runing the cashflow will likely be better than the reported profits medium term (presuming its not fake ifrs profits that exclude lease costs)!!
Adjusting for lower vat rate or not 28% LFL growth aint too shabby !
Alphawave Ip (LON:AWE)
bit off topic this one as its over the normal market cap limit but it is friday and thss one has been of interest to some - including me.
Company continues to release very positive vibes - "talk" of $1 bill of revenues and over 30% EBITDA margins - compared to market cap of just over £1 bill. Ok its a given that they talk the talk - can they walk the walk too ? lets look at the q1 trading update
q1 trading update forgets to mention revenues - is that an accident ? are they runing/walking/sitting/lying or sleeping - aint got the fogiest as this must be the fisrt trading update i have ever seen that does not mention revenues - apologies if its there and i missed it?
they do mention "bookings" - note booking aint revenues - note bookings include "management's estimates of future royalties" - so this number seems glass possibly more than 100% full
Bookings total is $30.7 mill up 20% qoq
However they say this number includes $5.7 that has already previously been booked ? now i am getting really confused - seems to me they can book stuff again and agin when they want ? - not sure if they bok it perhaps un book it then book it again danno ?
Also $5.5 mill of the total is the "estimate of future royalties"
all very entertaining stuff
Per the company
"Of the US$30.7m in bookings, US$5.7m was through VeriSilicon
previously booked as part of the US$54m multi-year reseller transaction signed
in Q1 2021,"
and US$5.6m were
management's estimates of future royalties
rmillaree - not a great use of words by the company but it's not the same. A booking is a contracted / legally binding / non cancellable order where the revenue appears later. The $5.7m included in the VeriSilicon deal they signed was not previously a booking as it wasn't contracted on the other side by a buyer.
This is predominantly a royalty company so "estimate of future royalties" is exactly what you expect. The main revenue currently is in design wins with customers where the product gets incorporated into a product due to go into manufacture by the client at a forward point in time....ie a year or two later. The company then also receives a royalty on each product the client sells. They will know from the clients roughly how many units they plan on shipping so this can be approximated. They can't ignore that from the numbers as it is contracted future revenue. It is "unknown" but can be reasonably estimated. ie it is not just a finger in the air.
Actually ebitda margins are around 50%. They bought a new business that when completes will bring margins into the 30's but once it is fully digested expects to be back medium term to around 50%.
The market clearly doesn't get or believe the story despite the audited revenues and profitability that came through. I guess most people don't really understand it.
Edit : note guidance for this FY is $325-360m of revenues at a 32-36% ebitda margin. So we can expect an ebitda profit of $100m+ (they are net cash so no interest). Given the net cash position, growth rates and type of business a £1bn valuation seems very light.
I guess most people don't really understand it.
It’s not easy for market participants to find relevant listed comparisons. Alphawave Ip (LON:AWE) isn’t a chip designer nor is it a capital equipment maker, nor a provider of EDA software. The most relevant comparison with Synopsys which at least has a meaningful element of IP in its offerings.
Edit : note guidance for this FY is $325-360m of revenues at a 32-36% ebitda margin. So we can expect an ebitda profit of $100m+ (they are net cash so no interest). Given the net cash position, growth rates and type of business a £1bn valuation seems very light.
The discount to Synopsys, if we can take that as a valid comparison, is very significant. Albeit justified to an extent by the early stage in the company’s evolution. I hope we’re both right, although my position size is suitably cautious.
yeah mine too - market just doesn't believe it and persistently shorted as quite illiquid. Started the day up 20% and now down 5%....bizarre really
I think Alphawave Ip (LON:AWE) is a cleverly traded / shorted stock, so I'm probably wrong to be in it at all short term despite the value and growth I see in the business. Looking at the price action before KPMG decided they needed an extra week due to covid absences the stock was trading at 190p. The 1 week delay allowed the traders to smack it 30%, on the basis that something was very wrong, which clearly it wasn't. The results came out on the revised 1 week delayed schedule and the price went up early back to 185p. Since then the short traders have jumped back in and driven it down 25%!
This is all on a £1bn market cap so clearly there is no liquidity and a small herd of short traders are making out like bandits. Makes any investment seem a bit futile really.
Alphawave Ip (LON:AWE)
A booking is a contracted / legally binding / non cancellable order where the revenue appears later
Thats half right - the company themselves confirm that these are "largely" such items - so its clear that some of sales are cancellable. Note whether legally binding or not if chinese company or similar cancels their bookings or chooses not to pay for said bookings there is probably not much they can do.
They are also clear that the royalties are partly "estimated amounts" - so its clear there is no certainty that the bookings that are royalties will ever exist
Why no mention of actual revenue ?
With such lack of presentational skills i can see why the market is skeptical - on the flip side the prospects look amazingly good if they just hit their targets - so if they do deliver i suspect shareholders will do very well - interesting company if nowt else
Up Global Sourcing Holdings (LON:UPGS) interim FY2022 results show a company that is creating shareholder value through its core activities. Sustainable sales growth, higher margins, positive cash flow and a 50% dividend pay-out should combine to generate earnings accretion and multiple expansion. UPGS is a brand-driven, international business, which is reinvesting in its operating practices. In our view, the share price does not reflect this and clearly lags our revised 250p fair value.
At 250p, UPGS would trade on an EV/sales ratio of 1.6x and 13.4x EV/EBITDA. Both multiples look appropriate for a branded consumer goods company with visible organic growth and a clear competence in acquiring and accelerating brands.
https://www.equitydevelopment.co.uk/research/upgs-shareholder-value-at-its-core
they didn't actually make any money though and they have borrowed £11m to pay the running costs and the dividend...
Up Global Sourcing Holdings (LON:UPGS)
trueagent
they didn't actually make any money though
Huh are you talking about Up Global Sourcing Holdings (LON:UPGS)? they made £7.2 mill net profit per the figures announced today !
No, they lost £6.5m. And they have had to borrow to pay for everything. Look at the cash !
Free cash flow was affected by borrowing to purchase an acquisition. That acquisition seems to be growing. Some of the future fee cash flow could be used to pay down debt. Taking Paul's general worries about Company's with large amounts of debt, that seems to be a future area to watch if as forecast the Company performs well. Bear in mind the relatively good performance was hampered by shipping costs which they are hoping will unwind.
No it wasn't, that was last year. The acquisition was £30m and they borrowed £16m and did a placing for the other £14m. Last year.
This year (well its only the interims so far...) they have simply burned 6.5m of cash in operations, paid nearly £3m in divs and borrowed another £12m to cover it all, using the rest to pay off another mill of another debt, and half a mill in interest in remaining debt.
Im not saying its one to avoid, its a good company. But those are the facts regarding cash flow & debt. Maybe by the year they will have made enough cash to pay off this debt...but right now its not great and for me not worth anywhere near a premium p/e. Around 14x is about right for me which given current forecast EPS of 14p gives a SP of around 195p...
but that's just me !
When a chief exec buys more shares in their company and this is announced as with Eqtec today does that mean the company is unlikely to announce winning a new contract etc for a while or could big news follow swiftly anyway? He did wait until after final results were issued on 25th April and has bought after the price surge that followed.
COO has now also bought shares at 95p. Really feels like an interesting company to look at again. they only need to land a contract with Europe - France ideally and Eqtec could really fly again.