Small Cap Value Report (Fri 30 April 2021) - PCIP, CARD, FA., UPGS, SLP, ELCO

Good morning, it's Paul & Jack here with the SCVR for Friday.
Timing - early today, as I have my first city lunch of the year, on a breezy terrace next to Tower Bridge. I'm so excited, I feel like a convict (I imagine) might feel on being released from prison heading straight for the nearest Harvester! Today's report is now finished.
Agenda -
Paul:
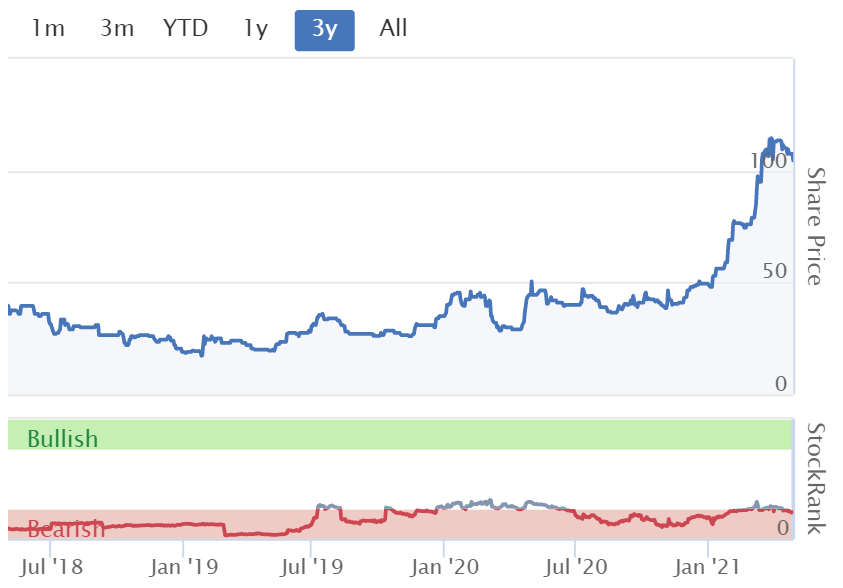
Pci- Pal (LON:PCIP) (I hold) - I review its small placing, to raise funds for expansion into new territories. I'm all for small caps strengthening their balance sheets, after big rises in share price - that's the ideal time to do it, not in a crisis. Under 10% dilution is fine by me, in return for a much stronger balance sheet. Although this does likely push out breakeven further into the future, which some may not like.
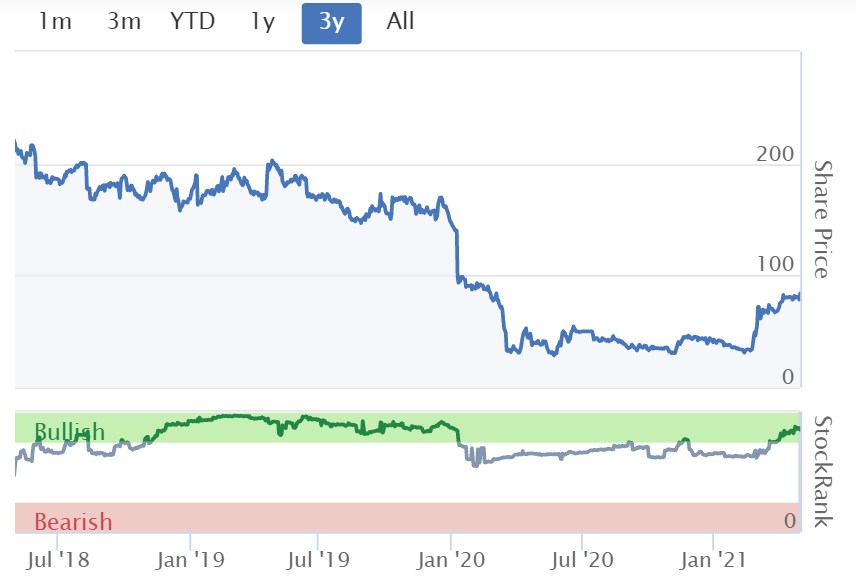
Card Factory (LON:CARD) - the usual end of month bank waiver is granted. However, the better news is that a longer-term bank refinancing looks to have been agreed, but not yet documented. The balance sheet is shot to bits, so a big equity fundraising is likely to follow, or be part of the bank refinancing. Re-opening of the shops is said to have been better than expected, but no numbers given. High risk, but so far, so good.
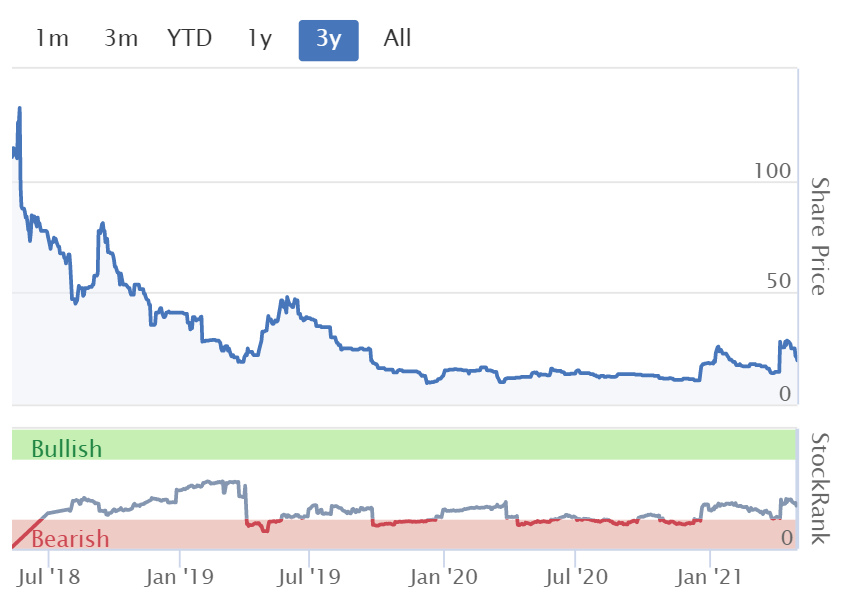
Fireangel Safety Technology (LON:FA.) - awful 2020 results are out. Another equity fundraising to raise £9.0m at 18p per share is announced, so at least the company's finances are now shored up. It's too accident-prone for me, but good luck to holders - who knows, it might be a turnaround in the making, if you're an optimist.
Jack:
Up Global Sourcing Holdings (LON:UPGS) - another upside surprise from this owner and manager of small domestic appliances.
Sylvania Platinum (LON:SLP) - a couple of operational issues in Q3 at the platinum group metals (PGM) producer, but strong basket prices are driving eye-catching quarter-on-quarter growth.
Eleco (LON:ELCO) - in line Q1 update from architectural SaaS business that, while pricey, looks deserving of its 99 Q Rank.
Paul’s Section
Pci- Pal (LON:PCIP)
(I hold)
104.5p - mkt cap £62m
Proposed Placing to raise £5.5m
I last reviewed PCIP here on 8 March 2021, on publication of its interim results. My view at the time was that the cash position looked adequate, but that given the big rise in share price, a small placing of say 10% dilution, would not concern me.
My crystal ball was working well on that day, because such a small placing has just been announced.
I like to scrutinise fundraisings for companies of interest, to inspect the terms, and make sure they’re OK. Also, these announcements often provide useful information about strategy, and current trading.
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, today announces its intention to conduct a fundraising to raise gross proceeds of up to approximately £5.5 million through a placing to new and existing institutional investors ...
Main points -
- Quantity - 5.79m new shares to be issued, a 9.7% expansion of the share count - modest dilution
- Price - 95p, a 9% discount, slightly disappointing
- Amount raised - c.£5.5m before fees, so maybe £5.2m after fees?
- Method - accelerated book build, as is usual. When the ABB is announced, it’s usually already a done deal
- No EGM needed, as the company has existing authorities
- Finncap arranged the deal
- No open offer unfortunately - I feel that, where a discount is offered, then existing shareholders should also get the opportunity to participate, and not just a fig leaf tiny open offer, but maybe the same amount again, as any placing
- Purpose - expansion into new territories - mainland Europe, Canada, and Australia
My opinion - when a share has roared upwards, as many have, this is the ideal time to strengthen the finances with an equity fundraising. I wish more companies would follow suit. Look at how many companies ran their balance sheets too thin, then had to raise money near the bottom in April 2020, causing often large & unnecessary dilution. If only they had fixed the roof when the sun was shining. The future is always uncertain, hence why having some cash reserves is good.
PCIP is generating tremendous organic growth, in a niche where it has an enviable position. Therefore it makes sense to maximise the opportunity by expanding faster.
The downside is that extra up-front costs are needed for expansion, so this pushes out the timing of breakeven. Does that matter? Probably not in a bull market, as investors are likely to prefer faster growth, and grabbing the opportunity that PCIP has before it.
The historic figures look bad, but if you watch PCIP's investor presentations on InvestorMeetCompany, the upside case is explained very well - in a nutshell, it’s all about rapidly growing, high margin, sticky, recurring revenues. Providing growth continues, then profitability is easy to forecast.
The shares have had a great run recently, so I imagine it might need time to consolidate. This one is a coffee can share for me, so I don’t really care about the short term share price. It’s rare to find such strong organic growth, at high margins, which then leads to a leveraged positive boost to the bottom line. This is one of the best small cap software companies out there, in my opinion, because customers are lining up to use its product, with the USA being its prime market. Maybe a takeover target too?
As you can see below, the StockRank system doesn't like it at all ... yet! It will, in a couple of years' time, when the profits are flowing hopefully.
.
.
Card Factory (LON:CARD)
83.8p (up 7%, at 09:25) - mkt cap £287m
It’s the last day of the month, so as usual this is when we get an update from CARD, saying that its banks have given it another month's stay of execution on its banking covenants.
Sure enough, the usual wording appears today, about another month’s grace -
... the banking syndicate has extended waivers in respect of anticipated covenant breaches to 31 May 2021, taking account of the Company's cash flow projections, subject to certain conditions.
However, today’s update also contains much more positive news about a refinancing deal having been agreed with its banks, this is new & positive information -
The Company has agreed headline terms for refinancing of the Group with its current syndicate of commercial lending banks and will issue a further update, over the coming weeks, once terms are documented.
That’s excellent news for shareholders, who were/are taking a helluva risk on this one - solvency risk, and equity dilution risk (which still exists - the balance sheet will need to be repaired with a placing, and debt reduced).
Trading following re-opening - good, but no figures provided -
The Company is pleased to report that its performance following the reopening of stores in England and Wales from 12 April 2021 has exceeded its expectations.
The only other update I can think of, following the recent re-opening, was from Fulham Shore (LON:FUL) which also said things have gone well. The big difference now (compared with last year’s summer re-opening) is that so many people have been vaccinated. Hence I would expect the public to be more confident about returning to something nearer to normal.
Although, anecdotally, a lot of people I know have expressed caution, even fear, of going out again - there seems a degree of inertia, even agoraphobia, with some people, so this is a complex situation where the public seem to be in clear categories about their attitude to re-opening. I think we’ll need to see what happens over time. The direction of travel (getting back to normal) seems fairly clear to me, but I don’t know how long it’s likely to take. The risk of setbacks has to be taken into account also. Nobody knows for sure what the future holds, hence why I recoil when people talk with false certainty, saying this “will” happen. They’re often/usually wrong, so why don’t people moderate it to “might”, or “could”?
My opinion - the market cap of £287m, for a retailer which went into the crisis with a balance sheet already groaning with debt, and which must by now look atrocious, doesn’t make any sense to me.
However, bulls obviously see things differently, so good luck to them.
.
.
Fireangel Safety Technology (LON:FA.)
20p (down 11%, at 10:02) - mkt cap £25m
Results FY 2020 -
I’ve quickly reviewed the figures, and rapidly lost interest - FireAngel had a really poor year - an underlying loss before tax of £(5.7)m.
Capitalised development spend was £2.5m.
Net debt £3.7m, and a weak balance sheet once you write off the intangible assets.
Fundraising of £6.1m in April 2020. That money’s effectively gone, so they’re coming back for more.
Placing of £9.0m announced today, looks a done deal, at a 20% discount, 18p.
There’s a decent-sized Open Offer too, 10 for 33 shares, which seems to be done on a clawback from the placing shares, which I like a lot, that does respect pre-emption rights, unlike many other placings without a proper open offer.
Current trading - says 2021 has started well.
My opinion - it’s been so accident prone in the last few years, and performed so badly, that I personally wouldn’t believe any assurances that things have been turned around.
Good luck to more optimistic investors, if you do decide to give the company the benefit of the doubt. The institutions are clearly prepared to give it another chance, with the £9.0m placing today, so there must be a decent story attached to the new products being developed, and management must retain some credibility. Either that, or the brokers maybe pulled in some favours to get this fundraising away?
With a decent fundraising now done, the risk of insolvency looks to have gone away, so this share is a much safer proposition today, than it was yesterday, having been refinanced. A lot more shares in issue though, so the upside % is diminishing with each fundraise.
We’re in a bull market, so who knows, this could be a nice little speculative trade? Too speculative for me though, and my view is tainted by past serial disappointments. I’d want to see a decisive turnaround in the future numbers, before being willing to have a punt on this.
.
.
Jack’s section
UP Global Sourcing (LON:UPGS)
Share price: 160.6.5p (+2.6%)
Shares in issue: 82,169,600
Market cap: £128.6m
Up Global Sourcing Holdings (LON:UPGS) is a distributor of its own and licensed value-focused consumer household goods brands. Licences include Russell Hobbs and Slater.
It sources parts and products from China (it also has a showroom in Guangzhou) and is headquartered in Oldham.
This kind of model is often afforded a lower valuation multiple, but UPGS looks like it is well run with able management, and its share price has performed very well over the past few months in particular. It seems the market has revised its perception of this company.

Trading at 14.6x forecast earnings, UPGS is not as obviously cheap as it has been in the past, but it’s earning returns on capital employed of some 55.9% and has built up double-digit compound annual growth rates (CAGRs) over time.
Some might think the easy money has been made here but the fact remains that UPGS stacks up very well in terms of Ranks and it qualifies for two Guru Screens (O’Shaughnessy Cornerstone Growth and Lakonishok Momentum), so it is still getting flagged across a range of data points.

Others might argue that the business model is prone to shocks, but we’ve just had the mother of all exogenous shocks and UPGS has managed to navigate its way through, so I’m sure it's looking to the future with confidence.
I don’t see why the company can’t continue to grow from here, ably led as it is by ambitious management.
A strong performance with favourable long-term consumer trends
The outlook statement is found quite far through the update but is worth quoting here for emphasis:
The Board anticipates that its performance in FY 21 will be ahead of current expectations, with revenues forecast to be in excess of £135 m (FY 20 - £115.7 m). While the Group has seen an increase in shipping rates, as noted above, the Board nevertheless currently expects that underlying EBITDA for FY 21 will be in excess of £13.0 m (FY 20 - £10.4 m) with underlying profit before tax in excess of £10.8 m (FY 20 - £8.2 m).
Interim highlights:
- Revenue +11.4% to £75.4m; online platforms revenue +53.6% to 15.6% of total,
- International revenue +0.5% to £23.6m,
- Underlying EBITDA +20.8% to £8.8m,
- Underlying profit before tax (PBT) +24.4% to £7.7m; PBT +18.9% to £7.2m,
- Interim dividend +45.7% to 1.69p.
This looks like continued good execution from a company that is building up a fine track record. FY21 PBT of £10.8m is a notable upgrade and, frankly, the valuation still looks reasonable given the growth.
UPGS has made a purchase post-period: Petra, the Germany electrical kitchen brand. This stock is well followed by Equity Development so you can find a note on that acquisition here (in fact, I’ve just seen that there’s one out already for today’s results here).
International - revenue was ahead of last year by 0.5 % (£0.1 m) to £23.6 m, with Germany performing particularly well, +25.7 % (£1.5 m). This is where UPGS’s most recent acquisition is presumably focused and Germany is ‘a particularly exciting opportunity.’
Supermarkets - good performance in both the UK and, increasingly, in Europe. H1 FY 21 revenue +27.6 % to £20.4 m thanks to its Beldray, Salter and Russell Hobbs brands. The supermarket segment accounted for 27.1 % of revenue in the period (H1 FY 20 - 23.7 %).
Online - grew substantially, with revenue +53.6 % to £11.8 m and 15.6 % of overall revenue (against a newly increased long-term target of over 30%).
The group notes that:
COVID‑19 lockdowns are likely to have accelerated the consumer switch to online shopping by several years. We believe that this changed behaviour is here to stay and have seen particularly strong sales in kitchen electrical, cookware, cleaning and laundry products. In only a few years, online has gone from a start-up to a substantial contributor to overall revenue and a key driver of growth.
Group operating margins declined year-on-year from 23.6% to 22.8% as a result of online marketing spend increasing by £0.2m.
Discounters - sales +0.6 % to £28.4m after a decline in FY20 caused by lockdowns. So this should bounce back in the months and years ahead.
Net cash from operations for the period was level at £6.8m. Net bank debt is down from £11.2m in January 2020 and £3.8m in July 2020 as a result of strong profitability, reduced stock levels, improved supplier terms, and online demand.
This takes the net bank debt/underlying EBITDA ratio to just 0.1x.
Conclusion
UPGS is good at what it does (in fact, it’s probably best-in-class). I wonder if, even now, we are sleeping on the potential here? Increased home working could prove to be a longer term tailwind, and the company is investing in its Head Office.
This investment is ‘an important step in the curation of our talent, providing a workplace that will promote training, collaboration and the interchange of ideas between colleagues.’
There may prove to be a natural ceiling for this kind of business model but for now it seems as though UPGS is making the required investments to become a bigger business in time. There is organic and acquisitive growth potential, along with a clear strategy.
UPGS 'intends to develop its portfolio of brands for mass-market, value-led, consumer goods for the home focused on international retailers, supermarkets, online platforms, and discounters' - given the track record, I’m not about to bet against it.
Sylvania Platinum (LON:SLP)
Share price: 116.8p (-2.67%)
Shares in issue: 272,570,115
Market cap: £318.4m
(I hold)
Sylvania Platinum (LON:SLP) is a producer of PGM metals. One of the main drivers of demand here is from the car industry for catalytic converters, where these metals can help clean up emissions. It’s a Stockopedia Investment Club holding - in fact one of it’s best performers so far - and you can read a much more detailed Pitch on the company here.
Rhodium in particular is expected to remain in deficit for a couple of years but the outlook for all of these metals looks promising at the moment and basket prices at the likes of SLP have been steadily rising.
SLP is not actually a miner - the Sylvania Dump Operations (SDO) comprises six chrome beneficiation and PGM processing plants focusing on the retreatment of PGM-rich chrome tailings materials from mines in the Bushveld Igneous Complex. It’s the largest PGM producer from chrome tailings re-treatment in the industry.
Aside from that, Sylvania also holds mining rights for PGM projects and a chrome prospect in the Northern Limb of the Bushveld Complex, along with some other exploration assets.
Highlights:
- SDO delivered 17,420 4E PGM ounces in Q3 (Q2: 18,363 ounces),
- SDO Q3 net revenue of $74.2m net revenue (Q2: $43.7m),
- EBITDA of $58.7m (Q2: $29.1m),
- Net profit of $41.3m (Q2: $20.3m),
- Cash balance of $102.1m (Q2: $67.1m). Post period end, SLP paid a one-off Windfall Dividend of $14.3m.
The group is experiencing a couple of operational challenges. It’s seeing a higher degree of oxidation in current feed sources, resulting in lower than anticipated PGM recovery efficiencies. Also an inconsistent supply of RoM material to the Lannex milling plant has impacted processing efficiencies and operating costs.
But SLP also notes opportunities:
- Mooinooi chrome proprietary processing modifications and optimisation project should be completed during Q4,
- Lesedi MF2 project on track and commissioning estimated to commence towards the end of Q2 FY2022, and
- Strong cash reserves and no debt means the company can fund further optimisation and exploration projects.
The company’s operations are in South Africa (as is the majority of global PGM production). Covid is still an issue here, and SLP unfortunately lost an employee during the country’s second wave. South Africa remains at a further revised Level-3 status as of the beginning of March 2021, so it’s a live situation.
The mineral royalty tax (calculated as a percentage of PGM revenue) remains a significant cost arising from the higher PGM basket prices.
Conclusion
SLP is always fairly upfront about operational challenges and Q3 is historically a lower production quarter. The group says it remains on track to produce c70k ounces for the current year.
The real driver at the moment is the strong PGM basket price, boosted by the high rhodium price, as well as the recent performance of both iridium and ruthenium.
On that note, the financial results are striking: net revenue up 70%, EBITDA up 105%, net profit up 103% (with a net profit margin of 56%), and net cash reserves up 52%. And these are all quarter-on-quarter growth rates, not year-on-year.
SLP says this is a historically quiet quarter, but if you annualise that net profit figure you come to a run rate of c$165m or £119m. Compared to a market cap of £318.4m, shares still look attractive even after the strong performance. There is always commodity price risk here though. Profits could fall just as fast if the basket price declines.
That aside, these results would make for about 44p of run rate earnings and a PE ratio of just 2.7x (but note that the basket price has been increasing throughout the year and so the actual FY results will likely be less than this).
If you knock off the $102.1m (£73.5m) of net cash you have an enterprise value of £244.9m. Annualised EBITDA of $234.8m (£169m) suggests a potential EV/EBITDA ratio of just 1.45x. So if anything, the share price performance has lagged the basket price performance.
Clearly the market remains skeptical as to the sustainability of these earnings, so as ever we come back to whether or not the PGM prices are in a bubble that will quickly pop. At some point the market fundamentals may change but for now, all the indicators suggest current prices are broadly sustainable for at least 1-2 years and likely longer.
Eleco (LON:ELCO)
Share price: 125.84p (+8.48%)
Shares in issue: 83,079,650
Market cap: £105.4m
Eleco (LON:ELCO) is an AIM-listed specialist international provider of software and related services to the Architectural, Engineering, Construction and Owner/Operator (AECO) industries and interior furnishing industries.
Its market-leading Elecosoft software solutions are developed by teams in the United Kingdom, Sweden and Germany, and include project management, estimating, timber engineering, CAD and visualisation, asset and facility management and cloud-based digital marketing solutions.
These software solutions are sold directly in ELCO’s core markets of the UK, Sweden, Germany, the Netherlands and USA, and indirectly through its international reseller partner channel.
There are more pricey SaaS-based, recurring revenue software stocks than you can shake a stick at these days. What’s immediately a little more interesting about Eleco is that it was actually founded in 1895 and listed on the London Stock Exchange in 1939.
Obviously it wasn’t a SaaS stock at the time, but it sounds like Eleco is building on some real heritage and evolving its model with the times, having originally been called the Engineering and Lighting Equipment Company.
What’s more, Eleco’s valuation is not quite as expensive as other tech stocks (it’s still not cheap though):

Its divisions are:
Building Lifecycle - Comprised of Eleco’s Project Management, Estimating, Property Management and Maintenance Management products. These solutions complement each other and can be adopted into core customer segments. The market for these solutions is c£8bn with an 8-15% CAGR.
CAD and Visualisation - Includes niche products with minimal synergies between customer segments of the Building Lifecycle portfolio. Eleco’s ESIGN and Active Online products are key players in a £450m market.
The group’s growth trends over time look quite promising, so this company is actually starting to tick a few boxes. See the diluted normalised EPS:

Highlights:
- Revenue +9% year-on-year to £7m; recurring revenue up 9% to £3.7m,
- Profit before tax +21%,
- Net cash up from £6.2m to £7.9m
It looks like a solid start to the new financial year. This is just a Q1 update so there’s not much to go on just yet but trading is in line.
Eleco notes a ‘compelling’ market opportunity and a new, focussed growth strategy, which is probably worth looking at in more detail in the most recent annual report, or any investor presentations if they can be tracked down.
Conclusion
This looks quite good actually, and I’ll probably do some more work into it.
You have to be wary of valuation when it comes to SaaS recurring revenue tech stocks. Some of these current ‘nosebleed’ valuations will prove in time to have been cheap. Others may struggle to generate the requisite organic growth.
Regarding Eleco specifically, the stock is not quite as pricey as some other software plays and the outlook for the construction and built environment sector is looking positive at present. A recent report from Glenigan anticipates a sustained recovery over the coming years.
Alongside that, rising material costs and increased regulation are anticipated to squeeze the industry’s margins, making Eleco’s technologies, which use automation and data to improve margins, ever more critical to potential customers.
Margins, returns on capital, and free cash flow per share are all increasing steadily, and the Quality Rank is 99, so I do think this is worth spending some more time on. Early days though, and we could always find something in the due diligence that puts us off.
It looks like broker forecasts were recently revised down - and we do want to see good forecast growth given the valuation - so that’s something to check.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Paul and Jack - many thanks for all your hard work as always it’s most appreciated. Did I read a week or two back that there was a plan to put out a post just on coffee can ideas? Sorry if I picked it up wrong but if there was a post would you mind pointing me in the direction in case I missed it! Always good for research these! Many thanks. Sam
Eleco (LON:ELCO) (I Hold) Thank you Jack for your excellent summary of Eleco.
The company was under the radar and cheap for quite a while. Not so cheap now - but also not expensive in respect of its products and rate the construction and building maintenance industry is digitising.
The company appears to have held together well during the pandemic - despite a lot of its major clients being severely disrupted during the first wave. The company did well to switch to remote working swiftly and efficiently and move quickly to provide its clients with on-line training, launch cloud based updates just in the nick of time and provide for remote working licences and freebies aimed specifically at furloughed staff. Which I think will stand the company in good stead as the recovery progresses.
There is always a however. As the old Eleco left behind is own construction heritage to focus upon its fledging software business - it has been very acquisitive. There is criticism that organic growth has been low, and cross-selling has not delivered, particularly in markets like the US and that most of the growth has been by acquisition. Moving to a Software-as-a-service model often exacerbates this as we see at other companies moving in the same direction eg Vianet (LON:VNET) (I hold) and D4t4 Solutions (LON:D4T4) (I hold).
It may be that ELCO is now in a position to deliver on the organic growth - I will be delighted - and the Q1 statement does look like terrific profit growth (21%) in comparison to good, if not exciting Saas revenue growth of 9% and impressive cash balance, demonstating the reality of the profits.
But, Is this growth expected to continue?
And. Something is afoot with the board. Two large shareholders have just submitted a requisition for a GM at which the executive chair and the NED chair of the remuneration committee are to be 're-elected' and the remuneration policy 'approved'. Or not perhaps?
This should be seen in the context of the longterm visionary executive chairman of the company retiring (I think he was in his mid-70's) in the middle of the pandemic and without, apparently a proper succession plan in place to appoint a CEO. The NED recently installed as deputy chair and as chair of the remuneration committee then stepped up to executive chairman temporarily whilst the process of appointing a CEO commenced. There having been no CEO previously - but the internal candidate, the COO has now appointed as the CEO, whilst the executive chair has yet to step back to non-executive.
That's probably not the way I would have gone about it -but it has to remembered that this was in the midst of the pandemic. And may have been necessitated for health reasons?
It does appear that some large shareholders - with whom there may be history? - are seriously irate? It does look as if the board has been slow to buy a sizeable shareholding (the previous Chairman still owns a large chunk of the co) and the remuneration policy does look tied to 'trivial' targets and healthy dollops of share options in comparison to what the shareholders may be looking for? Current board not well aligned to shareholders?
The board has been very quick to rush to the defensives with the NED under threat stepping up immediately to buy 90,000 for around 100k - and spout his defence of the board. Followed almost immediately by the gushingly positive Q1 statement.
Provided this does not affect the operations of the company I don't have a problem with this - and I do intensely dislike the entitled attitude of many board members in comparison with their treatment of the teams that actually deliver the riches they like to guzzle.
At the moment I don't think it does interfere - provided it works out quickly one way or the other - and at the moment it seems to have the effect of popping the shareprice as the board rushes to justify its self-enrichment.
I do hope it does not get out of hand - ideally these two characters will reach a deal with the shareholders and disappear of their own accord in time ? These kinds of companies producing software selling well in markets that are huge and rapidly moving towards digitisation are hard enough to find as it is!!
cheers
Mark
Eleco (LON:ELCO) is far cheaper than Swedish large cap Hexagon although they have similar FCF margins eg FCF/EV = Eleco 6%, Hexagon 3%. If you re-gear both companies ND/Ebitda to 0.5*, the PE is 22* vs 29*. Using similar future growth (+5% for a few years then fade to +3%) but higher WACC for Eleco (8% vs 6%), Eleco's upside is 29% vs Hexagon +7%.
You make a very good point about the SaaS model. Eleco ELCO was a family business that suffered badly in the past and was taken over and transformed by what looks like an innovative team. It bears further study though I am unsure if there is much coverage available to the private investor. At just below £100mn market cap this could be an inflection point if progress can be maintained. (I do not hold!).
Don't know if anyone is interested in Trackwise Designs (LON:TWD) but there's a company presentation on a Shares webinar 11th May 6 pm (trackwise scheduled for 6.30). You can register here
https://www.sharesmagazine.co.uk/events/event/shares-investor-evening--webinar-110521 This is one of my largest holdings and I don't expect to be selling it any time soon.
Interesting that the H & T (LON:HAT) CFO is leaving now. Just before the FCA investigation is due to conclude this summer! Albeit of course the investigation is focused on the sales & marketing of those loans, so he would not have been responsible for that in the organisation.
Sylvania Platinum (LON:SLP) Liberum note.
"Given the stellar performance of PGM prices, it is no surprise that Sylvania have achieved another record quarter with EBITDA of $58.7m and cash balance increasing 52% to $102.1m. Annualising this past quarter, the stock trades on a ridiculously cheap EV/EBITDA of 1.5x. Production of 17.4koz was inline with expectations and guidance of 70koz for the year remains in place. We remain very comfortable on rhodium on a five-year view (see here) and expect the abnormal cashflows to continue (30% FY22 FCF yield)......"
Target price still £2.00.
Hi Paul
It seems you hold a quite eclectic mix of stocks, predominantly in the small cap space, and we know you have a great deal of experience and interest in retail fashion. We also know you use a few investment/trading vehicles.
I would be fascinated to understand how you manage position sizes, risk and vehicle selection.
It's a big ask, with undoubtedly a lot of effort to produce, I'm sure many readers would find it a valuable and insightful read, if you ever find the time to put pen to paper.
Cheers
Mike
Thanks for the update on Sylvania Platinum (LON:SLP) .Having done some more research on the EV boom, it's going to be at least 2040 and £££ of investment in the grid, to get to c 33% penetration in US and 38% in Europe (source: MS Research). It's going to take a LOT longer to get anywhere near those penetration levels in Asia.
So we're FAR FAR away from EVs taking over as the mainstream choice. This does not mean countries will forego their emissions target either, so they will have to ensure the 'dirty' diesels/petrols are replaced with cleaner variants, which again is a tailwind.
Despite palladium prices soaring, the price rise back in '19/20 was much steeper and the macro environment wasn't as conducive as it is today either IMO.
Personally, I cannot see a better 2-10 year period for the PGM basket - but I'm happy to be proven wrong.
Eleco is really interesting - I wonder which other tech companies have such heritage? Nintendo was also founded in the 19th century!
Nokia's history dates from 1865, when Finnish-Swede mining engineer Fredrik Idestam established a pulp mill near the town of Tampere, Finland (then in the Russian Empire).
Hi Paul.
Thanks for commenting on the accident prone Fireangel Safety Technology (LON:FA.) Accident prone indeed but some things are self inflicted. Who changes the name of an albeit unpronounceable Sprue Aegis into something with the Ticker „FA.“? (Presumably the same board that renamed a perfectly respectable fund manager „Abrdn“ or whatever!)
I was in and out of this share a few years ago making some reasonable money when the share price was around the 200p level. I had used their products which were quite good (apart from some battery issues) and post the likes of the terrible Grenfell fire it seemed they were in a good space with their smoke alarm products. The old Sprue were also something of a favourite of your fellow small cap commentator Richard Bedderd who usually has a good eye for a decent small cap.
Anyhow, wind the clock on and they got in a terrible muddle with their key Far East supplier that was also a major shareholder among several other well documented issues and the whole thing t**ts up to a bottomed out share price around the 11p level. Share price picked up a bit when they recently announced a new initiative with a German partner which management claimed to be „transformative“ (a case of trust but verify methinks here) and today‘s well supported placement seems to put the finances back on a stable platform for the time being. Might think about a dabble as a speculative Turnaround punt although put off by the usurious 9% bid/ask spread. FA - really!?
Gus.
Sylvania Platinum (LON:SLP) (I hold) is in a really interesting point at the moment.
On the one hand the PGM prices have shot up due to the legislation requiring additional restrictions with Rhodium being and the massive supply deficit suggests further (large) price rises to come. As discussed on the Sylvania Platinum (LON:SLP) discussion board this implies very large share price upside from here.
Longer term: EV's will continue to eat into ICE market share, taking a majority share of new sales (which is what we care about from a Rhodium supply/demand perspective) from later this decade. There will of course still be ICE cars produced far into the 2030's but they will become a continually smaller part of the market.
One thing keeping the Rhodium price from rising higher right now is the chip shortage stunting the demand that would otherwise be hitting the market. There have been quite a few articles in the press about this but from what I can tell when Covid hit there was a massive drop in demand for cars, so the chip manufacturers making the chips required for cars invested to switch production to the chips required for higher tech home working (also higher margin for them) and now are of course very reluctant to invest cash to switch their production lines back to lower margin chips when they are at full capacity on higher margin chips.
In terms of risk I believe that EV's replacing ICE demand in cars will slowly reduce demand for PGM's & Rhodium in particular however the higher legislative requirements will keep demand high for quite a while. The chip problem means: 1. The Rhodium prices not go so high so fast as some plants are forced to reduce production & 2. Car manufacturers will see this as an additional problem of ICE vehicles and increase the speed of conversion to EV, shortening the time at which Rhodium prices would continue at these high levels.
Personally as long as Rhodium is at these levels Sylvania Platinum (LON:SLP) looks very cheap, but I hope that management focus on distributing these windfall profits rather than gathering more PGM producing assets unless they are developed or purchased at very good prices. There is a time limit for these super high prices, but I think they will last for a good few years yet.
Peter
Which board? Any quality analysis about?
Up Global Sourcing Holdings (LON:UPGS) view
2nd half traditionally lower earnings but broker fy guidance of c.10.3p on back of hy 7.2p probably lowball unless there's slowdown in demand caused by broader social re-opening in UK plus little positive impact from European retailers they supply re-opening. Always some factors causing a bit of period on period unpredictability at UPGS but balance of probability strongly favours an upside surprise IMO for fy21. The natural variance plus strong covid period performance means I wouldn't say nailed-on as has been case elsewhere.
Guidance since their post IPO slip up (driven by trading environment out of their control and an over ambitious valuation) has been very conservative by UPGS and so I take the ‘at least’ re earnings expectations and ‘remain confident in the future prospects’ wording of CEO outlook statement at time when 3 months into 2nd half trading as information that they have pretty much bagged those earnings half to date leaving room for the upside. Of course, this is traditionally their quietest point of trading and there are some uncertainties caused by the covid awakening here and Europe so the rest of half could still stutter.
Below is copy and paste (sorry not updated but covid messes trends anyway) from this post late 2020 - https://www.stockopedia.com/co... It shows the underlying growth dynamics for product areas. IMO there's a decent chance that the rise in their brand sales and fall in non-core or non-brand stuff over the years has reached a tipping point that could (ie maybe!) see sales on accelerated path from here:
Some summary stats on underlying revenue growth patterns are interesting:
Cumulative revenue growth CAGRs by category (reporting year first broken out in data) + [2020 %age of total revenue]:
Total 14.0% (2014) [100%]
UK 9.2% (2015) [64.0%]
Europe 30.9% (2015) [35.2%]
Germany 99.1% (2016) [9.5%]
Europe ex Germany 15.7% (2016) [25.7%]
Supermarkets 51.7% (2016) [24.3%]
Discount retailers 3.7% (2016) [38.6%]
Online 56.3% (2016) [14.4%]
Premier brands 27.6% (2014) [69.9%]
Other key brands 8.6% (2014) [14.3%]
Other (lesser) brands and own label -4.5% (2014) [15.7% -> from 45.5%]
I think the comment about the market having a question mark on the sustainability of the pricing of PGM's is very pertinent. Personally, I don't see pricing collapsing especially with inflation looming- which makes this share cheap if performance can be maintained
Sylvania Platinum (LON:SLP)
My concern around PGM's is that car catalysts for ICE vehicles are a major market - the move to electric cars may well reduce need for Platinum.........
Sylvania Platinum (LON:SLP) - I totally agree Nick.
Except electric cars cost twice as much for the same functionality as an ICE equivalent and current market numbers of electric cars show that there is a gap still to bridge.
I'll wager that for now, contrary to what The BBC / Guardian writes and says, The Public don't care about Greta, they only care about:-
How much does it cost?
How fast does it go?
Will I pull?
the point at which electric cars cost the same to make as ICE cars is fast approaching (<1 year probably) - the traditional car manufacturers are using the premium prices to help pay for the switch in manufacturing and new equipment / plants. This is where Tesla have as advantage by not having ICE manufacturing (and not having value for ICE manufacturing on their books)......Tesla has lowered the price of many models by c 15% this year and can keep lowering the prices as their operational margins are circa 30% (compared to traditional manufacturers of circa 4%).........it is an interesting economics experiment in supply/demand and technology disruption........
Have you seen the YouTube videos/blogs on repairing electric cars?
Tesla's corrode if you live near the sea. Battery packs are not designed or engineered for repair. A couple of bad cells can ruin a battery pack and the repair bills are $$$$s.
It is a very depressing picture from the environmental and owner's point of view.
I'd love to stop murdering bunny wabbits but my share portfolio is going to have do considerably better before I burn my hard-earned and taxed on zero-carbon!
I am staying with a bicycle for now. A carbon bicycle.
an ICE engine change on a BMW or Mercedes would be $$$$'s
Bikes are the best without doubt
Yes, but an engine shouldn't need to be changed! If it is engineered correctly, it should be functional for 100,000 miles.
Bikes - Love'em. As long as you don't get murdered, killed, splattered by some psychopath, has to be a great way to travel locally and keep fit.
UK_Investor-8888
Tesla's corrode if you live near the sea. Battery packs are not designed or engineered for repair. A couple of bad cells can ruin a battery pack and the repair bills are $$$$s.
It is a very depressing picture from the environmental and owner's point of view.
I don't think any technology is perfect and we have alot to learn when it comes to finding the sweet spot ref the "full cycle" for these batery components. Having said that most of the comments i have seen ref Tesla battery performance have been encouraging and if you buy a Model 3 you get the following warranty in the uk.
Model 3 Standard Range - 8 years or 100,000 miles, whichever comes first, with minimum 70% retention of Battery capacity over the warranty period.
So if it was me i wouldn't be worrying my flapjacks about what what could possibly happen safe in the knowledge that practicably speaking you are sorted for 100k miles or 8 years ? is that not enough of acomforty blanket ? - particularly if you have your own limited company the government is paying a very decent wad of the price you would pay to make the swap.
I have not seen any evidence that Tesla's depreciate in value faster than other cars either - if there were major issues i would expect to see this fact reflected in lower resale values than the average new car. We certainly have plenty of peeps living near the sea in the UK :)
With regard to the environmental point of view ref end of life - i would be 100% confident that the infrastructure will be in place come the time to dismantle the uk/eu end of life batteries in a fashion that is acceptable to the environment and hopefully all done on "our patch too". I for one am impressed with how far we have come from 5 years ago when i think they had the first leaf that probably struggled to do 75 miles on a damp sodden day.
rmillaree
You make some excellent points. I must acknowledge that I was referring to Tesla vehicles, particularly the oldest vehicles, outside of service/warranty.
It has not sunk in to me yet that I'm rich. I still spend and think like I'm on £10K a year and never pay over-the-top. Fix and Upgrade rather than buy "new".
I really hope we will see all manufacturers committing to full lifecycle and full component recycling.
.
The real question is: will it be Tesla or the traditional car companies that solve all the problems with EVs first?
I can see the big German car cos setting up a road block for Tesla.
And the Japanese will set up another.
In the meantime, we watch ... this is a spectator sport.
.
The real question is: will it be Tesla or the traditional car companies that solve all the problems with EVs first? I can see the big German car cos setting up a road block for Tesla. And the Japanese will set up another.
They'd better hurry up. Share price movements in the last ten years:
While that's been going on:
I think, as an investor, I'd rather have been wrong with Tesla than right with the rest of them.
timarr
Tesla has lowered the price of many models by c 15% this year
Really? I don't follow these things but perhaps this has something to do with lower duty rates in the UK, now we are out of Brexit and the recent strength of GB£ against the US$...
PGM metals still relevant for EV revolution - for hydrogen fuelled cell batteries vehicles - https://www.miningreview.com/e...
yes but that change is going to take years and years, so in the meantime...$. Also platinum is seen as a major requirement for hydrogen fuel dynamics long term. The bottom line is that there are millions of diesel vans and trucks in India and China which now have to follow strict emissions rules. They are not going electric any time soon and so they have to have a cat converter fitted using Rh and there isn't enough of the stuff. SLP will by then have a ridiculous amount of cash so could then reinvest or simple be taken over imo.
Personally I see Hydrogen as a niche solution not mass market cars or house heating......good for trucks / buses, perhaps ships, perhaps planes (volume is a problem as is the weight of the pressurised tank needed).
Major issue (1) to make Hydrogen (using electricity) , transport, use it to power something takes 60% more electricity than just using electricity
Major issue (2) No national grid for Hydrogen or distribution mechanism other than pressurised tanker
Major issue (3) There are virtually no hydrogen "filling stations" and the unconfirmed reports I have seem indicates that the cost of a hydrogen "pump" is 10x to 100x times the cost of an electricity charger (even the very high power ones now available)
Re Sylvania Platinum (LON:SLP) there is a new market opening up for PGM catalysts in hydrogen fuel cells.
XLMedia (LON:XLM) - Grant of share awards RNS
Current price 50p and dropping hard and fast from its high of 66p last week.
https://www.stockopedia.com/share-prices/xlmedia-LON:XLM/news/xlmedia-plc-grant-of-share-awards-urn:newsml:reuters.com:20210430:nRSd2194Xa/
Summary:
Average Share price has to hit £1.50 between 01/01/2021 to 31/12/2024
for the two Fuhrers at the top to get 0.746% of the share capital.
This tells me that there is a concerted probability that the business will be steered to achieve £1.50 or more by half way 01/01/23. 3 x upside from here.
@ £1.20, the bosses get no award.
Have a nice day!
Sylvania Platinum (LON:SLP) There has to be strong case for a substantial share buy back given the level of cash and exceptionally low valuation
The Sylvania Platinum (LON:SLP) report also says
"The Group remains debt free and continues to maintain strong cash reserves to allow for funding of capital expansion and process optimisation projects; the safeguarding of employees during these times of uncertainty; upgrading the Group's exploration and evaluation assets; and returning value to all stakeholders."
I think it as likely that they will invest operationally.
You may well be correct. The case for a buy back: they are sitting on cash that will be something like a third of market value by the end of the next quarter on current run rate and shares at a conservative P/E of 2.7 (source Jack B - haven't done my own maths). No indication that the need for capital is anything like the amount on the balance sheet.
Latest piworld interview with Andy Brough. He comments on the last Stockopedia/piworld StockSlam. He gives his own 3 mins StockSlam. Plus loads of investing gems as he reflects on learnings from his fund management career. Superb watching - he's just a class act.
https://www.piworld.co.uk/2021/04/30/piworld-andy-broughs-3-minute-stockslam-other-gems/
https://www.piworld.co.uk/2021/04/30/piworld-andy-broughs-3-minute-stockslam-other-gems
Many thanks Tamzin for yet another excellent offering. Andy Brough on top form and definitely worth 40 minutes of anyone's time.
Andy Brough is always great value, but today's interview with Tamzin was especially good.
That's because I bought yesterday.
Figures look good to me. Happy to sit this out.
I must of missed the warning of what to sell?
Or did this one bounce?
What is the £???
Tommy
Regarding Futura Medical (LON:FUM)
This wording in today’s announcement is a little odd
“ Futura's breakthrough, fast acting topical gel formulation MED3000, is the
first clinically proven, pan-European topical treatment for adult men with
erectile dysfunction ("ED") available without a doctor's prescription ("OTC").”
It makes it sound like there are other treatments that are available without a doctor’s prescription but only in some European countries (which I don’t think is what they mean). I’m not going to make any sniggering wisecracks about this product as there are no doubt many men who cannot take the existing ED treatments due to excessive side effects or being on incompatible medication. So, great news for them. For others, I sense, particularly as this will be available OTC, a new recreational product that may use from time to time to even if they don’t really need it clinically. I’m going to resist the urge for hyperbole, but it is difficult not to get excited about the future for this. They need to do one more trial before US approval I believe but I think it is actually advantageous not to have too many markets to focus on at the same Tim for the launch.
It is not a forgone conclusion that Futura Medical (LON:FUM) won’t mess up the commercial launch of this now that the regulatory part is completed in Europe, but one would think that is unlikely.
I bought in a relatively short while ago when the regulatory approval looked like it was in the bag. I expect that the price is going to be highly volatile from here on but it’s going to be a great, wild ride to be on.
Looking at the Futura Medical (LON:FUM) SP chart gives one vertigo. Sold in 2012 and it's been on a fair few gyrations since!
.
Cash at end of 2020 was only £1m.
R&D in 2020 was £3m (2019: £11m).
Did it raise a further £1.5m in April 2021?
A business with no turnover make me nervous.
What does it make you?
.
Equity Developments have issued a Research note on £ UPGS ( I hold ) giving the shares a fair value of 200 p ( yesterday 152 ) . I would be fascinated to know if Paul agrees with their assessment .
Here’s a link to the Up Global Sourcing Holdings (LON:UPGS) report - hot off the press:-
https://www.equitydevelopment....
Sylvania Platinum (LON:SLP) (I hold), many of us hold came up with a Q3 report, even with less operation doubled the EBITDA and doubled the net profit - PGM prices still great.
"Sylvania Platinum Limited, Third Quarter Report to 31 March 2021
Sylvania Dump Operations ("SDO") delivered 17,420 4E PGM ounces in Q3 (Q2: 18,363 ounces);SDO recorded $74.2 million net revenue for the quarter (Q2: $43.7 million);
EBITDA of $58.7 million (Q2: $29.1 million);
Net profit of $41.3 million (Q2: $20.3 million);"
SP dropped 3% in the first 5 minutes of trading.
"SP dropped 3% in the first 5 minutes of trading."
Sylvania Platinum (LON:SLP) Well they did release the RNS @ 7:52am
Yes, it was just a little hint if anyone wanna join the club... ;)
I just don't understand the market with £SLP. The sp declined all week on the run-up of the results and then - no surprise - started to track up again once the interim results were released.
Why the market pre-results uncertainty? You can just track the PGM prices and figure out that, bearing some disaster, revenues & profits are are going to be up significantly. Combine that with their comparatively low PE ratio, isn't SLP (famous last words) about as close to a sure thing in the short-term at least?
What does the market know, that I don't?
Solid Q3 update from Bangladeshi generic drugs manufacturer/distributor Beximco Pharmaceuticals (LON:BXP) this morning. Arguably more of an Industrial than a Pharma company.
https://www.investegate.co.uk/...
Decent (>11%) growth in Q3 sales and even sharper increase (>61%) profit after tax suggesting improved margins. Q3 suggests accelerating trend in profitability from previous two quarters. Recent hiccup in the share price attributable in part to understandable delays in receipt of Covid vaccines previously sourced in India but as ever the London listed shares continue to trade at a healthy discount to those traded locally. Unique play on the the Indian sub continent mass healthcare market? (I hold).
Gus.
Regards Arix Bioscience (LON:ARIX) the update looks to have cleared out most of the old Board and bought in a number of people, some of which are at the behest of Acacia Research who prompted the strategic review having identified a lack of direction, poor returns and a failure to invest in its key people to lead in its bio-science research and investment arm - which to be honest is what the company does.
Acacia Research (a Californian based research & investment company) are;
Acacia Research seeks to acquire undervalued businesses with a primary focus on mature technology, life sciences, industrial and certain financial services segments, and pursues opportunities for value creation that leverage Acacia’s significant capital resources as well as its expertise in corporate governance and operational restructuring.
As a shareholder I support Accacia - lets face it they have the same long-term interests as the rest of us ie. to ensure the company makes sound investments and creates value for us shareholders. A decent bit of shareholder power to refocus the Boards mind should be viewed as positive.
Lets hope the new strategy and Board changes now deliver some good returns.
This was originally highlighted as one of Simon Thompsons (IC) picks for his 2021 portfolio.
Tekcapital (LON:TEK) results were out today and they announced a 45% increase in Net Assets with NAV remaining at $0.35 from last year despite a number of placings. For those that don't know they have four interesting companies namely
1. Salarius® Limited ("Salarius") (97.2% ownership) Salarius Ltd manufactures Microsalt®, a new, patented, all natural, non-GMO, Kosher, low-sodium salt that tastes great and has half of the sodium of regular table salt.
2.Lucyd® Limited ("Lucyd") (100% ownership) Lucyd is seeking to Upgrade Your Eyewear® by developing and selling designer prescription eyewear with smart features at affordable prices. Lucyd was the first company to deliver prescription glasses with Bluetooth® technology in 2019. Their frames help you stay connected safely and conveniently, by enabling many common smartphone tasks to be performed handsfree via voice assistants.
3.Guident Limited ("Guident") (100% ownership) Guident is developing remote monitoring and control software to improve the safety of autonomous vehicles and land-based delivery devices. Guident's software will incorporate artificial intelligence and advanced network technologies to minimize signal latency and improve reliability.
4. Belluscura® Plc (17.8% ownership) Respiratory medical device company that has developed an improved portable oxygen concentrator (POC) to provide on-the-go supplemental O2. The company believes its product is the first FDA cleared, modular POC with a user-replaceable filter cartridge. Belluscura aims to make POC's more affordable to those who need them.
All of them are in interesting areas with Belluscura mooted to be doing an IPO at some point in the future. I am long on this and see it as a nice entry point, there's clearly risk but for me I have 4 opportunities with this one for the price of one and with a large discount it covers most the downside risk.
My morning smallcap tweet:
Synairgen (LON:SNG) Restore (LON:RST) Sensyne Health (LON:SENS) Driver (LON:DRV) Omega Diagnostics (LON:ODX) Futura Medical (LON:FUM) Headlam (LON:HEAD) Genedrive (LON:GDR) Card Factory (LON:CARD) Westminster (LON:WSG) UP Global Sourcing Holdings (LON:UPGS) Arix Bioscience (LON:ARIX) Fireangel Safety Technology (LON:FA.) H & T (LON:HAT) PCI- PAL (LON:PCIP), Eleco (LON:ELCO)
Synairgen (SNG) good result from combined data from the Hospital and Home Cohorts in inhaled interferon beta trial. "The study results reinforce confidence in ongoing Phase III study, with data readout on track for H2 2021." [SP=147.7 Cap=295m]
Restore (RST) £40m placing at 365p, a 5% discount, to fund £61m acquisition of EDM Group, a UK based information management company offering solutions to large and medium-sized enterprises. It's immediately accretive to underlying EPS. [SP=385 Cap=484m]
Sensyne Health (SENS) 5 year non-exclusive Strategic Research Agreement with an NHS Foundation Trust. "The agreement will enable the ethical application of clinical AI research to improve patient care and accelerate research into new medicines." The Trust will get 0.87% of share cap. [SP=165 Cap=272m]
Driver (DRV) guides H1(Mar) pretax (before share based payment charges) down only slightly. Outlook encouraging. "Meaningful progress has already been made in implementing the five year strategic plan." [SP=56 Cap=29m]
Omega Diagnostics (ODX) launches rapid covid test. Talking to distributors. Waiting for confirmation on which test has successfully passed Govt performance evaluations. "Once a suitable test has been approved the DHSC will license the test for Omega to manufacture." [SP=73.5 Cap=134m]
Futura Medical (FUM) gets EU Quality Management Certificate for erectile disfunction gel. [Insert your own double-entendre here]. [SP=45 Cap=115m]
Headlam (HEAD) sells Swiss floorcoverings distribution business for c. £12m. [SP=462 Cap=393m]
Genedrive (GDR) covid lab test approved in India. Price is controlled but co "believes however that formal performance evaluation data and ICMR approval will contribute positively to commercial efforts and premium products such as gendrive's can play a part in the need for COVID-19 testing." [SP=72.5 Cap=46m]
Card Factory (CARD) performance following reopening has exceeded its expectations. Also agrees refinancing. Covenant waivers extended. [SP=78.5 Cap=268m]
Westminster Group (WSG) FY20 in line. Guides FY21 in line. [SP=4.1 Cap=12m]
UP Global Sourcing (UPGS) H1 rev up 11%. Guides FY rev over £135m and U/L pretax over £10.8m, ahead of current expectations. [SP=158.33 Cap=130m]
Arix Bioscience (ARIX) Outcome of Strategic Implementation Review: director changes and "the Board now has a clear understanding of shareholder views, enabling it to implement its strategy more effectively." Is that it? [SP=189 Cap=252m]
FireAngel (FA.) £2.9m placing and £6.9m OO at 18p, a 20% discount, for R&D and efficiency improvements. Also FY with rev in line. [SP=22.3 Cap=28m]
H&T (HAT) CFO leaves to pursue a project outside the group. He is thanked. [SP=289.5 Cap=115m]
PCI-PAL (PCIP) £5.5m placing at 95p, a 9% discount, to fund overseas expansion. [SP=104.18 Cap=62m]
In line: Eleco (LON:ELCO)
Interims from Up Global Sourcing Holdings (LON:UPGS) look good this morning showing very promising growth in online sales.
Yes, more detailed guidance as well
CURRENT TRADING AND OUTLOOK
The Board anticipates that its performance in FY 21 will be ahead of current expectations, with revenues forecast to be in excess of GBP135 m (FY 20 - GBP115.7 m). While the Group has seen an increase in shipping rates, as noted above, the Board nevertheless currently expects that underlying EBITDA for FY 21 will be in excess of GBP13.0 m (FY 20 - GBP10.4 m) with underlying profit before tax in excess of GBP10.8 m (FY 20 - GBP8.2 m).