Small Cap Value Report (Fri 5 Feb 2021) - VTU, ALU, FCCN, CTG

Good morning, it’s Paul here with the SCVR for Friday.
Timing - update at 12:02 - sorry, I've been massively distracted by the big news on FCCN, it's now one of my largest holdings, so needed time to properly think everything through. I'm about to start writing the next section on Christie (LON:CTG) which should be up by about 13:30 . Today's report is now finished.
Agenda -
Vertu Motors (LON:VTU) - Trading Update from yesterday
Alumasc (LON:ALU) - Interim results, H1 to 31 Dec 2020.
French Connection (LON:FCCN) (I hold) - Two potential cash bid approaches
Christie (LON:CTG) - Trading update for FY 12/2020 issued yesterday.
.
Vertu Motors (LON:VTU)
33.8p (up 2% at 11:22) - mkt cap £124m
This is a chain of car dealerships. I’ve previously been quite positive on this share, as it has a nice mix of reasonable valuation, and strong balance sheet, with tons of freehold property. So you’re really getting a hybrid of a property company, and a car dealer (3 profit streams from new car sales, secondhand, and service/repair/warranty work). That’s true of most other listed car dealers, and there’s not a lot in it between them, they’re all quite similar in my view. Although Lookers (LON:LOOK) had all that previous trouble with accounting misstatements, so that one doesn’t interest me.
The current financial year is FY 02/2021, so only a month left to run.
The latest update sounds encouraging -
Group's trading performance ahead of prior year and Analysts' forecasts
The Group announced in early December that trading performance in the nine months ended 30 November was ahead of prior year and original budget levels.
Despite the impact of regional lockdowns throughout December and the national lockdown from 4 January, strong marketing activity, maximisation of the Group's omni-channel retailing functionality and cost control have meant that trading performance in the two-month period to 31 January 2021 continued this positive trend. Overall profit performance also benefited from the previously announced cost reduction programme and the continued business rates holiday on showrooms.
Current trading - February & beyond are being & likely to be impacted by covid restrictions.
Overall -
… the Board now expect that the trading result for the year ending 28 February 2021, at an adjusted profit before tax level, will exceed the current Analysts' forecasts of around £18m.
Broker updates - many thanks to Zeus and Liberum, as both have made available update notes on Research Tree, that’s very helpful.
Zeus has increased EPS forecast by 29%, a big move coming at the end of the year, to 4.9p. Remember that this year will have benefited a lot from business rates relief, and furlough support. Hence we can’t assume profits will necessarily rise next year, even if revenues recover (which are down 12% this year). That’s a PER of only 6.9
Liberum goes higher still, to 5.1p this year (upped from 3.9p), but is also cautious for next year, at 3.9p.
Balance sheet - from the recent interim results, as at 31 Aug 2020. Scary, huge numbers, as with all car dealers - they have a ton of working capital, financed mainly by trade creditors. But there’s £165m of NTAV backing. With a big pile of freeholds, this is a sound balance sheet, nothing to worry about. I’ve been saying it for years, but I could see this sector being ripe for takeovers - consolidation, or private equity interested in gearing up the freeholds maybe?
My opinion - looks really good value to me. Asset backing from the freeholds.
I like the way Vertu is embracing online marketing & sales. Everyone is adapting to the new world, and a lot of these changes are likely to be permanent I reckon.
Downside risk is that people are talking about electric cars taking over in the coming years, and not needing as much servicing, maintenance or repairs. True, but there’s still plenty to go wrong, and people still have bumps & scrapes.
Even if car dealers have to slowly close down, who cares? They can close freehold sites any time they like, and sell the freehold to Aldi or Lidl! So shareholder value should be protected whatever happens.
Vertu gets a thumbs up from me, as a decent value share.
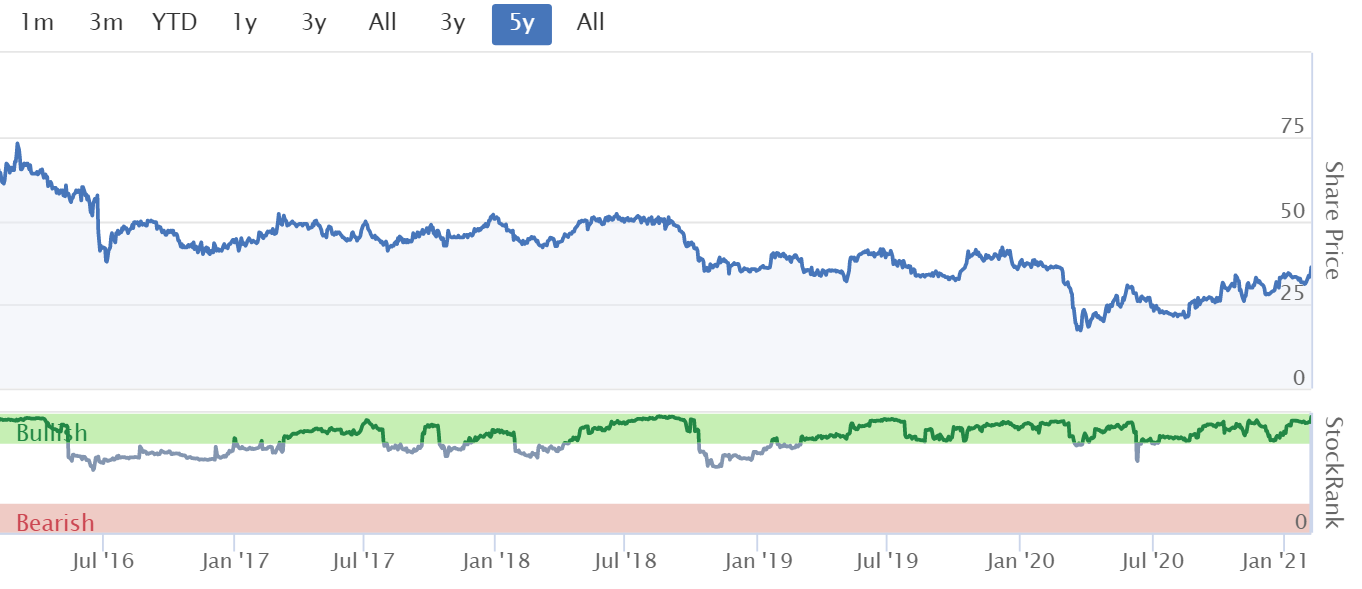
Looking at the 5-year chart below, it's not been a good buy & hold share. Although it's paid about 7p in divis over this period, so the total return has been about zero! That doesn't necessarily mean it won't generate a return in future of course. I'm wondering whether it might be sensible to pencil in a 50p selling price target, if it does rise from the current 34p? That would be a tidy 50% gain, so not to be sniffed at.
.
.
Alumasc (LON:ALU)
143.5p (up 1% yesterday) - mkt cap £52m
Interim Results
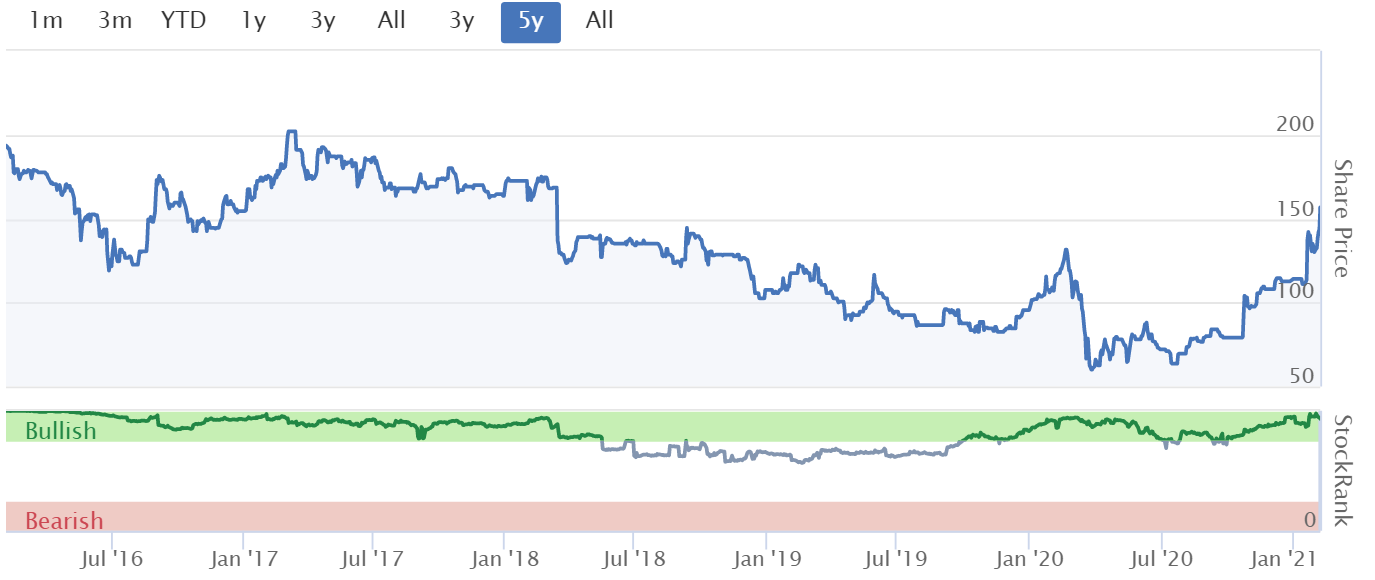
I reviewed its H1 trading update recently, here. It was excellent, and triggered a 21% share price rise on 19 Jan 2021. Big cash outflows for the pension deficit are a key factor as to why the PER is so low, so make sure you factor that into your calculations. We’ve been guided to expect £6.0m underlying PBT for H1, a record result.
Alumasc (ALU.L) the sustainable building products, systems and solutions Group today announces results for the six months ended 31 December 2020.
Results in line - it reports £6.0m u/l PBT as expected - an impressive margin of 13% of revenues.
Underlying EPS 13.4p
... successful execution of our repositioning strategy launched in 2019.
Pension deficit (accounting, not actuarial) down to £12.8m (was £19.3m 6 months earlier, boosted by good investment returns)
Strong ESG (environmental, social & governance) credentials (see narrative)
Interim divi of 3.25p proposed
Balance sheet - adequate, not strong. NTAV is about £5.6m. If you ignore the pension deficit (which looks a manageable-sized problem), then the rest of the balance sheet looks fine to me.
Forecasts - thanks to Finncap for an update note. They’ve pencilled in 19.9p adj EPS this year FY 06/2021, which doesn’t look demanding, given that two thirds of that has already been achieved in H1.
Next year they estimate 22.2p
That gives PERs of 7.2 and 6.5 - even allowing for the pension deficit, that strikes me as cheap. Also there could be further upside on the forecasts maybe?
My opinion - A|umasc gets a thumbs up from me. With the business performing this well, and the PER this low, I can live with the pension deficit. Looks a quite nice value share.
.
.
French Connection (LON:FCCN)
Share price: 15.6p (last night’s close, likely to rise today)
No. shares: 96.6m
Market cap: £15.1m
(I hold)
Statement re share price movement - two separate takeover approaches received
The share price has been going bananas in the last few days, and it wasn’t clear to me whether this was something significant happening, or just muppets chasing up the price on momentum, which is happening a lot at the moment.
I was expecting a we know of no reason for the share price movement type of announcement this morning, when I saw the RNS headed “Statement re share price movement”.
However, there was a pleasant surprise served up. There have been two separate, early stage approaches from potential cash bidders -
Spotlight Brands (with Gordon Brothers International LLC) - this article says Spotlight was set up by Strand Equity Partners (an American consumer growth equity firm) in July 2020, with $500m, to target fast-growing brands, in deals between $50-100m.
Gordon Brothers seems to be an investment & services company, which includes special situation lending. Projects noted on its website include some brands that I recognise including Antler, Laura Ashley, Albemarle & Bond.
Go Global Retail (with HMJ International Services Ltd)
Go Global calls itself a brand investment platform. It seems to be a California-based private equity firm. I cannot find anything on HMJ.
My opinion - Founder/CEO Stephen Marks is 75 years old in May, so clearly one imagines is probably not keen to carry on working forever. Therefore it’s sensible to assume he’ll want to maximise the value of the business, and sell up in the not-too-distant future.
I particularly like retirement sales, and remember we made a killing on a group called Avesco a few years ago on that basis - the founder sold or restructured the loss-making bits to maximise profits, then sold it for about 5 times my entry price. It paid divs along the way too. I wish I could find more situations like that!
FCCN is a valuable brand, and I think it could fetch £40-50m in a sale. The downside risk is that Marks might turn away bidders again, as he did last time, for not meeting his price expectations. It must be frustrating for him, having spent almost 50 years building up the company, but its value now is only a fraction of what it would have been in its heyday.
So we could soldier on for another x years. Although would that be such a bad thing? The problem retail sites are disappearing gradually, and we’ll end up with a profitable wholesale & brand licensing business eventually.
Personally, I’m in for the duration here, so am intending sitting tight on my shares. The current price of c.20p is nowhere near the level where I would be prepared to sell at. Although I quite understand other investors have different time horizons to mine, so might be happy to top slice or bank their profits in full.
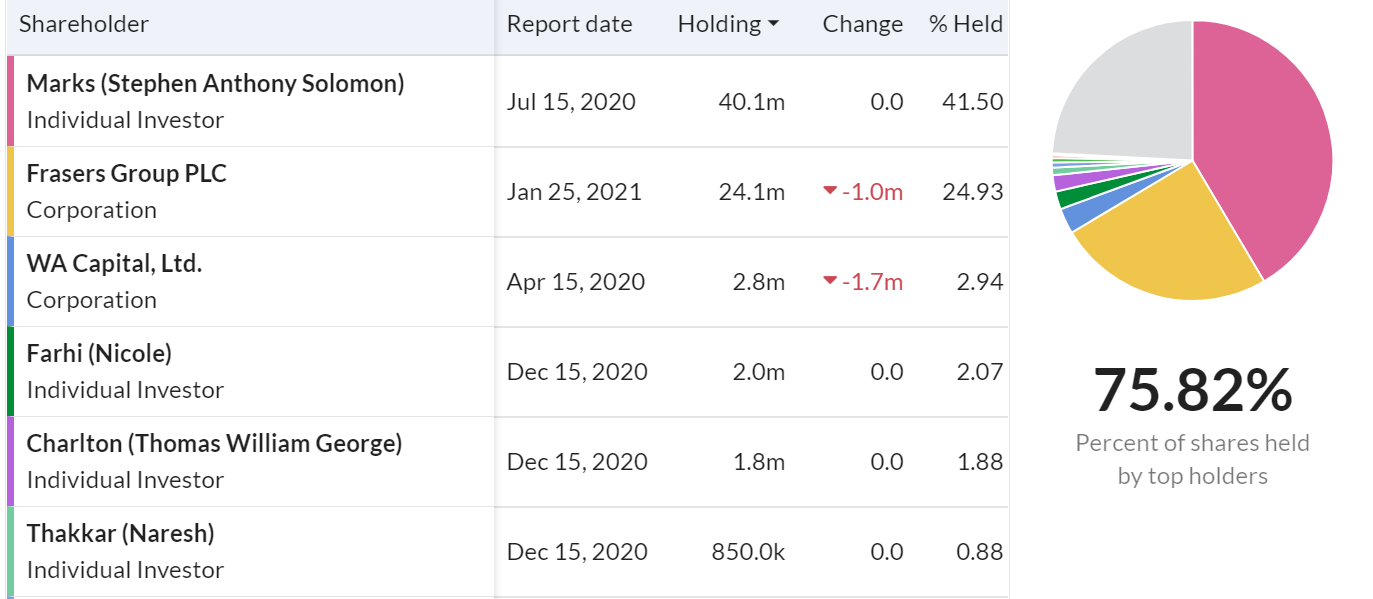
EDIT: Thanks to a subscriber who points out that the shareholdings are very concentrated here. So any sale of the business would require the support of founder Stephen Marks, as he has a blocking stake of 41.5%, and is legendary for his stubbornness, so nobody will be getting this on the cheap.
After that, Mike Ashley's Frasers (LON:FRAS) owns 25%, who is also a legend in his own right! What is it with retailers, why does it attract or create such flamboyant figures?! All part of the fun though. End of edit.
.
.
Christie (LON:CTG)
95.5p (up 10% yesterday) - mkt cap £25m
Christie Group plc (CTG.L), the leading provider of Professional & Financial Services and Stock & Inventory Systems & Services to the hospitality, leisure, healthcare, medical, childcare & education and retail sectors...
To get up to speed, here are my notes from the interim results to 06/2020, issued on 29 Oct 2020.
Bringing us up-to-date, here are the main points from yesterday’s year end update for FY 12/2020 -
- Stronger trading & increased revenue, has resulted in a profit for H2 (not quantified)
- This is after taking into account restructuring costs (again not quantified)
- Cost-cutting done, should benefit 2021
- Stocktaking business is on hold, staff furloughed, as should be expected
- Agency & Advisory business - increased demand from insolvency practitioners, and business buyers (very strong)
- Outlook for 2021 - H2 weighted due to lockdowns (understandable)
- Cash - above expectation (no figures provided)
Well they don’t come more vague than that! There are no figures provided at all in this update.
H1 was heavily loss-making, so it’s good to hear H2 recovered into profits.
Lord Lee has been on the blower this morning, and very helpfully talked me through the bull case for Christies, which goes like this;
- Cheap for a professional services business, which should be valued at around 1x revenues, which would imply a share price c.3 times current level
- Recovery should happen as covid recedes and things get back to normal, hence operational geared upside
- Christie is market leader in its sectors & has a very good reputation
- Lots of work likely, as hospitality & leisure sectors under so much pressure, which should drive deals & insolvencies, valuations, all of which is good for Christie
- Stocktaking business can resume when lockdown lifted. Likely to be less business from the High Street, but more from online
- Financially strong, but pension deficit (not sure I completely agree with this, but it’s fair to say that CTG is not financially distressed, as the pension is a long-term issue, not pressing)
- Big management & family shareholdings
- Also has a ticketing solutions business, that should benefit from economy unlocking
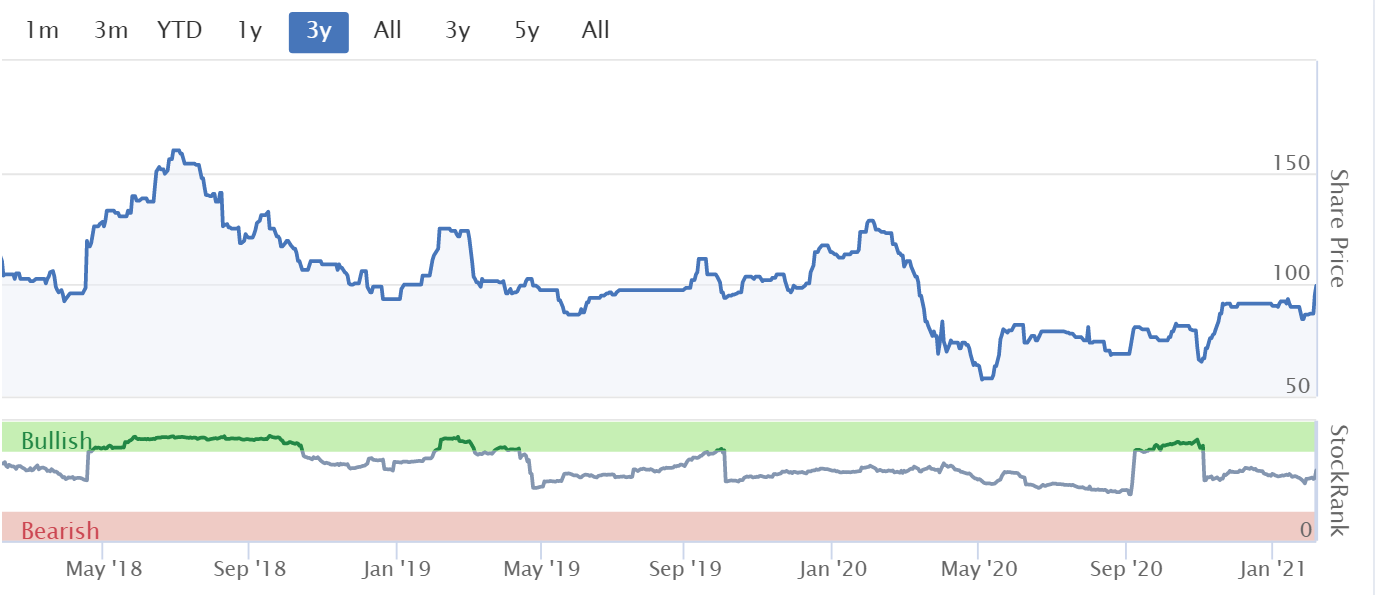
My opinion - the bull case does sound quite good, in terms of recovery potential. Although looking at the chart, it’s back to where it was most of last year, pre-covid, at around 100p.
Maybe there could be some upside on that? Also possibly at some stage it might attract bidding interest. Begbies Traynor (LON:BEG) (I hold) bought a valuation business as a nice bolt on a few years ago, although I don’t think they paid much for it!
Overall, I’m probably neutral on this one.
.
.
All done for today & the week.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Couple of weekend random items
There is current consultations going on ref potentilaly limiting gambling stakes online + potentially ghaving to provide proof of funds to bet - my mates who work in the industry say this could be potentially penal for oerators - i havent looked at the detail here - may be worth DYOR for those invested in such companies - it may be amountain over a molehill.
https://www.gamblingcommission.gov.uk/news-action-and-statistics/Consultations/remote-customer-interaction-consultation-and-call-for-evidence
The other one is slightly bizarre in that the FCA are looking into the buy now pay later interst free )providing you pay on time ) operators.
Not sure who would be impacted here and whether there there could be a read across to the wider industry ??- i probably shouldnt worry about companies like next as i am not presuming there is any read across - but they make a fortune on offering finance for people to buy clothes - all legal but could they come onto the radar soon?. It doesnt quite sit right that people should be buying clothers on tick and paying through the nose for it.
https://www.thisismoney.co.uk/money/news/article-9215121/At-Klarna-clampdown-begins-not-moment-soon.html
BNPL: N Brown (LON:BWNG) operates in this space, but they seem to be one of the few that is already fully FCA regulated, and maybe a beneficiary if their competitors need to newly comply with FCA? The target of the FCA investigation are the likes of Klarna, Clearpay, and Paypal Credit. Note that Boohoo (LON:BOO) uses Clearpay.
The target of the FCA investigation are the likes of Klarna, Clearpay, and Paypal Credit. Note that Boohoo (LON:BOO) uses Clearpay.
Boohoo uses all of them, as do all of the other online companies (including Next). However, Boohoo appears to be the major user in line with the demographics - more 18-25 year olds use BNPL than older people.
N Brown are more a finance company rather than a fashion company, but in any case the companies aren't interchangeable. You won't find a 19 year old instagrammer buying a frock from N Brown no matter what the BNPL issues are. In fact, if BNPL users can't get access to funds then they won't buy anything.
Research here for those interested in detail rather than headlines:
https://www.money.co.uk/guides...
timarr
CTG has gone nowhere in years. I purchased almost 10 years ago it kind of doubled before falling back down again. Quality ranks are very low suggests if it is best in market it can’t make much margin even on that basis.
Fair point. Lord Lee did chuckle that the only people who think Christie (LON:CTG) is undervalued are him (holding for about 20 years!) and the CEO.
Tremor International (LON:TRMR) Now this is interesting. Magnite (US listed peer) has just bought SpotX (connected TV -same area as Tremor) for c10* revenues. Finncap have a good note out on it on Research Tree.
Extrapolated to Tremor International (LON:TRMR) that implies over 1000p valuation compared to the 550p currently. If this space is consolidating you have to wonder if Tremor International (LON:TRMR) might be next?
Interesting announcement by the Canadian Government yesterday which maybe of interest to investors in Cruise ship companies:
https://www.canada.ca/en/trans...
Not sure if other governments will start taking the same approach.
All the best, Si
Wow that is a pretty strong control from the Canucks.
Essentially foreign cruise ships (carrying more than 100) are barred from operating in Canadian waters until February 2022.
I can only guess that they are worried that if a ship encountered difficulties whilst in their territorial waters, then they might be obliged to intervene.
More directly an issue for Carnival (LON:CCL) than for Saga (LON:SAGA) , but as Si says it could be a signal for what other countries choose to do.
Does not appear to have had much impact on the share price of Carnival (LON:CCL) Doubt if many will take this position once the vaccine role out is over 50% in the countries to be visited. Agreed there is unlikely to be many cruises stopping in Africa and South America for a year or so.
National waters are 12 miles offshore. Outside that that they’d still likely to be called on to provide aid, though outside coastal areas there’s significantly less chance of the cruise ship needing aid
I am in Saga's target demographic, I am also a doctor, and there's no way on this earth that you'll get me on a cruise ship. The operators can take all the precautions in the world but if covid (or any other infectious disease) breaks out then you're trapped in a gigantic petrie dish. Just my opinion mind.
Hasn't that always been so with cruise ships? Saga are playing a clever game, making Covid vaccination mandatory turns it (bearing in mind their demographic) into a marketing advantage. Saga's USP will effectively be "this will be safer than staying home". Whether it is or not will be another matter!
anothersaxman58 - Indeed I'm also now one of their target demographic and I am probably a little more cautious than average at this time.
However, probably the most important investing lessons I have learned over the years when assessing companies that I think I understand from the customer perspective is that I may not be representative of my 'peers'.
The enquiries and bookings seem to send the very clear message that cruise ship companies are not going to struggle to fill whatever capacity they are allowed to offer.
It is going to be SUPPLY (controlled by 'regulation' etc. ) that is the limiting factor in the near term, imho.
You're right of course!
But Saga (LON:SAGA) has gamed the KPI.
They offered cancelled cruisers two choices:
Of course if you do this you get lots of rebookings later. The proof in the pudding is, when we get to 1-2 months out from the first cruises in May and June, how many further changes and cancellations do we get.
SAGA (LON:SAGA)
It will only take one bad news story of a coronavirus infected cruise ship that nobody wants docking in their port for confidence to evaporate: a high risk share I pass on.
Bonitabeach
I want to know when "pulling" comes back.
Things change rapidly.
UK_Investor_8888's week:
The rally in XLMedia (LON:XLM) -6% today and Plus500 (LON:PLUS) -2% today fizzles out for now.
Apax Global Alpha (LON:APAX) tests 215p +6.88% on an RNS today listing December's funds valuation. Clearly The Market is pleased with 729,642 share volume. Apax Global Alpha (LON:APAX) is one my StockRank heroes doing exactly what StockRank is meant to predict.
International Personal Finance (LON:IPF) closes @93p on trivial volume. However even if you take the day low of 86.4p, IPF is stirring, up 7.5% on the week, as its Earnings Update day approaches around about 24th Feb. We tested 99p in the November/December rally
I bought £10K SCS (LON:SCS) for my ISA today @205p. If God and Paul himself own SCS, that is a sign from on high for me. Possibly an 8% dividend if/when they resume...
Get your ISA's in, Stock Pickers, 2 months to go.
The French Connection (LON:FCCN) situation is why rule changes are needed when it comes to takeovers. It's a tricky one to get right but here's hoping Lord Lee's campaign is a successful one.
Paul, also strongly support the proposals you listed in yesterday's SCVR and if there's anything we can do to help push it along then that would be of great interest. It's only right that we all get a fair go.
Have a great weekend everyone :)
Open Orphan (LON:ORPH) - to holders (I hold) - appears that the Ethics Committee have approved the clinical trials - news out in last 1-2 hours. Seems to have stirred PI's interest in last hour.
If there is one stock I am extremely bullish on this year it is Open Orphan (LON:ORPH) as the potential is enormous. I hold from 6p and don't expect to sell for a long time.
In my view the current share price is supported by the core business and quarantine units. Covid accounts for a bit of that capacity but not major. This isn't a one off Covid story. They are booked out and potentially introducing another 100 bed quarantine unit soon. I think cash profit is expected to exceed £1m p/m already so valuation doesn't look too rich.
However, there are 4 businesses that will likely get spun out, a couple of which could be worth as much as the current business in their own right, so that leaves plenty of scope for upside effectively in the price for free.
The wearables business though has the potential to be enormous. Open Orphan (LON:ORPH) is the only place in the world any of the wearables can get this data apparently. If that is the case then there is a high quality tech business tat probably should be spun out providing data to all of the wearables on long term recurring revenue contracts. Imagine the valuation the US would place on that! And talk about Moat - you'd have to spend a decade investing to even compete.
I am trying to temper my enthusiasm as I appreciate that sometimes one can get blinded by opportunity and not see the risks inherent but so far the management have done pretty much everything they said they would.
I've got no useful view on Open Orphan (LON:ORPH) and I don't intend to generate one as I could not get to trusting the CEO.
Cathal is almost cartoon time in his relentless promotional approach to communication...everything is always going to be huge and he's all too happy to talk about where the share price should be.
I remember seeing him speak in person 18 mths ago and being struck by just how promotional he is. At that time he made it clear to those in the room (20ish people at Mello) that he'd have flipped the company for loads of money by approx now...and that huge value would be coming from their pan-European genomics database which would be the only thing of its kind...that seems to have back burnered for now with loads of new avenues and promises.
So everything has gone differently....but its all worked out okay with a lot of ducking and diving?!...yet now there are super valuable long term franchised and 4 non core pieces to be spun off for pure shareholder gain....ummm, I'd feel a bit queasy or perhaps assess whether I'd struck inordinately lucky and cash in.
I'll probably be wrong and my spidey-sense wonky and Cathal's baby is merely taking off...but can't catch every rocketship.
IMO in general I believe investors should avoid stocks where the CEO is so flagrantly promotional and inappropriate in his communications (not meant in legal sense TBC!)
Best wishes
Got to correct you a bit there Mojo
The genomics database hasn't been back burnered. It is part of the Disease in Motion patented platform that they are currently in the process of licensing to the wearables market. Apparently it is the only one in the world and they are negotiating with all the major wearable manufacturers. Fairly obvious who they are.
Similarly the Imutex universal Flu vaccine and PrEP hasn't come out of nowhere. It was always an asset designed to be spun off as not core to the services business. There are valuations precedent in the recent market for this too and they support the assertion of worth.
Has Cathal got very lucky with what he bought - yes yes and yes! Did he realise - I doubt it. Is he capable of monetising it - I suspect so. Are his communications a bit over promotional - definitely in my view. Not a style I prefer so I have to look behind the hype to see what's really there.......and I still like it.
We will see - maybe I'm wrong : don't they always say the things you get most excited about are the things that never make you money........but I've been in since 6p and I'm very happy with progress. Can't argue with a 4-5* return to date.
David, can you explain briefly how a genomics database can be related to wearables? There seems to be a quite considerable information and measurement gap in between the idea and the application. Thanks
(I may just lack imagination and/or understanding)
The database they've built up has all sorts of genomics and infectious disease data in it. By way of a single example : a wearable can now do an ECG or measure heart rate constantly. The data Open Orphan (LON:ORPH) has collected knows how the heart rate is likely to behave in a given type of infectious disease and thus gives the wearable a marker to look out for. This marker combined with others (that the wearable also measures) can tell you what you're likely to have. That's what the wearables are working on - but you can only do it if you have the data to support the markers and the only database in the world that has this is Open Orphan (LON:ORPH)
Apparently Open Orphan (LON:ORPH) could have done a large exclusive deal a while back with one of the wearable manufacturers but realised that it made more sense to licence it on a non exclusive basis to all of them and as I understand it they are in negotiations with pretty much all of them.
Now - I will grant you that we are expected to believe management in this regard and if you don't then fair enough. No-one is forcing anyone to buy shares. I can definitely see why Cathal isn't everyones cup of tea but I've been a shareholder a while and most of what he has said he has done, probably taking a bit longer than he says it will and sometimes changing direction a bit, but any good businessman will, and should, pivot or tilt strategy towards the best value. They said they would be profitable and say they are generating £1m of cash now each month with £20m in the bank. That means £12m p/a of cash profit and growing on a cash adjusted market cap of £160m = 13* earnings. That looks ok to me as a core business. Everything else is upside - the wearables, Imutex etc.
Thanks for the response David. Excuse my late response....we rolled into another week.
I know someone seeking funding and development for a somewhat related periphary monitoring/indicative medical technology that has been around a while and 'proven by users' but not verified by regulators sort of thing. That creates limits on who will engage with you and what you are allowed to do.
Its not the same as wearables and probably is less scientifically aligned in that it doesn't have scientifically significant the database you reference.
I don't have direct medical knowledge but I do have some (old) medtech related knowledge and the medical second hand knowledge that gave (electronics degree at university that was big on medtech research). I think using heart rate and blood oxygenation levels for anything but the most basic signal will be difficult without using it 'unethically'...ie rough and ready diagnosis. A watch could tell you to go to the doctor...but it couldn't say why...it may provide data to your doctor but its hard to see that the doctor would want/need this.
I'm probably just wrong
Ciao for now
So yes Cathal isn't everyone's cup of tea. But I have found him worth listening to. He freely admits to being very lucky to pick up Open Orphan (LON:ORPH) when he did from the wreckage of the Woodford empire. Hearing him tell the story made me wonder if there were any other neglected gems left over from that and I bought a stake in the inheritor fund £SUPP. I'm now up 30% in that after a 10% rise today based on the IPO pricing of their holding Immunicore. I was early and vocal in my criticisms of Woodford but not everything he backed was rubbish and there were definitely opportunities there post his fall.
I have built a modest position in Open Orphan over the past little while. There do seem to be a number of really good opportunities within the business, even if the overly bullish approach of the CEO is counterproductive. He would remind one of his (and my) fellow countryman Michael O'Leary. Just too noisy for most tastes, but as with O'Leary, there may be an astute entrepreneur behind the bluster. I thought about adding a few more shares but I'm trying to avoid the temptation until the words turn into money a bit more.
If you could buy one share today, which would it be?
I wonder if there is a way of getting a collective poll going and whether that would be of value.
Sounds like a 'wisdom of the crowds' approach... Stockopedia did publish a "Top stocks for 2021" report, detailing the stock picks of 3000 investors I believe.
Worth a look, its a good document.
This was done a few weeks ago, if you do a search you may find the thread. All different shares were put forward, don't think there was an overall winner but I did not see any results.
There was the competition as well but that included non subscribers.
Shares change all the time so difficult to say, I'm considering several to buy at the moment, depends on price, but there are others I already hold, that if I did not hold, I would be buying. A few weeks ago I picked MPAC (LON:MPAC) but price has gone up since then. But last share I bought was Ferrexpo (LON:FXPO).
Here are the top picks: https://www.stockopedia.com/ch...
The top stocks report is great and I have studied at length but even since then there have been price movements, trading updates and analyst updates. So there are a number of shares which I suspect a lot of us have in common as buy on dip. I have added Sylvania Platinum (LON:SLP) today but it could just have easily been Ferrexpo (LON:FXPO) or Evraz (LON:EVR) on another day. All good mining choices imo and I hold them all but the latter 2 are up today already. Where I find it more difficult is comparing companies across sectors, regions, volatilities and I know it is all down to DYOR and personal choice. Saga (LON:SAGA) or £FXPO or Boohoo (LON:BOO) for that matter is a much more challenging comparison I think.
I was contemplating my own portfolio in the light of the recent discussion on 'When to sell' . Re your there are others I already hold, that if I did not hold, I would be buying above I find myself asking the question about stocks I hold that this is not the case for because it leads on to the question; if that is the case, why am I not selling to invest in better opportunities. I think I am morphing into a hold only on strong conviction investor but could easily descend into trader territory if not careful.
There are quite a few I'm looking to buy at the moment but want the prices to drop back a bit more, Sylvania Platinum (LON:SLP) is close to my target, £G4M, Reach (LON:RCH), Somero Enterprises Inc (LON:SOM), Johnson Matthey (LON:JMAT) are some others. I hold Saga (LON:SAGA) and Boohoo (LON:BOO) already.
I don't have any really strong conviction buys at the moment. I sold my silver shares recently thanks to the sharp rise.
Selling to buy something else I find is tricky, I prefer to have a pot of cash, so I can buy what and when I want rather than having to sell to buy. Knowing my luck the one I sell will shoot up and the the one I buy will go down. When to sell can be difficult.
Hi Herbie - yes, I did a Top Stocks 2021 with some rules. Have been discussing with the Stockopedia team how to show the results but it looks like I am going to have to just update the title to bring it back up the list and add a table. Still I will try and do that this weekend. Some interesting 1st month results
I've most recently added to my Open Orphan (LON:ORPH) holding. Sometimes the best ideas are already in your portfolio etc. At least that's where my money has gone this week.
Lookers (LON:LOOK) I hold. Paul, I'm really surprised you dismiss £Look so quickly. Yes they had accounting issues, but they have come out the other side of a massive accounting investigation which means they probably have the most squeaky clean accounts of any motor dealer in the UK. And I suspect there are a few competitors under the spotlight to check they didn't follow the same accounting principles.
Also they:
1. Outperformed the UK new car sales recently
2. Sold 27 loss making sites, the cost savings of which will come through in FY21 accounts
3. Paid down / reduced net debt to £11M
4. Have a share price which is less than half the value of their OWNED dealerships
5. Have a new highly experience management team and a clear strategy to follow.
6. Are investing in further digital sales / marketing.
An extract from their recent announcement: "Despite the impact of the second national lockdown in November, performance in the second half of the year is expected to be ahead of last year, largely offsetting H1 underlying loss before tax of £36.1m"
Overall, I'm an fan of £Look and think there is significant upside to come. Can you reconsider or tell me where I've gone wrong?
Many thanks.
Hi 55555,
Good points, well made, on Lookers (LON:LOOK) , thank you!
For me, it's more about time available than anything. I'm trying to cover c.500 companies here, mostly single-handedly, and wasted a lot of time on LOOK in the past, ploughing through all the detail, which took hours each time I looked at it. I came to realise that it's not something I'd be interested in buying personally, having decided a while ago to avoid companies with accounting problems. Therefore, it's not a good use of my limited time to unpick all the moving parts.
It could be very good now, and you make a good case for it. I'm not saying it's good or bad, I have no view. But would rather spend the limited time available on other companies that are quicker & easier to report on.
Hope that clarifies, and good luck with your LOOK shares.
Regards, Paul.
https://www.stockopedia.com/sh...
Regarding Vertu Motors (VTU),
I have just completed a check on my Portfolio and Watch Lists (over300 Shares) for potential Bankruptcy Risk. Stocko is showing at Vertu Motors is at 'serious risk of financial distress'. it has a Z score of only 0.46. So I sold it yesterday for a small profit ( along with four other shares.
So I am a bit confused about Paul's enthusiastic write-up today. I would like to ask (politely) if anyone could explain the apparent contradiction.
20 years trading and I am still trying to learn.
My personal view is that the Z-Score is not a good predictor at all and the Stocko description is hyperbolic.
A poor Z-Score can be a useful warning sign but in the majority of cases I reject after due consideration.
Vertu Motors (LON:VTU) 's Z-Score has two "fails".
Working Capital/Total Assets = -0.008"
What Stocko calls Working Capital here is what I would call net current assets (current assets less current liabilities).
Vertu has negative working capital (both definitions) it always has - it is part of their business model that customers pay them, before they pay the suppliers. That can be a problem if revenues stop abruptly - but if that were going to happen it would have been last year.
Market Value of Equity/Book Value of Total Liabilities = 0.15
Basically the share price is so low that if they had to issue new shares to raise cash to pay the bills, the probably could not do so.
Fortunately it is unlikely they would need to do and besides the free hold property means they could probably raise debt rather than issue equity if they needed to.
I notice they run on a very scary margin?
I notice they [ Vertu Motors (LON:VTU) ]run on a very scary margin?
This is true (not a component of the Z-Score though), but it somewhat comes with the territory.
They are selling big ticket items at fairly thin margins.
Sales of new and used cars 92% of their revenue at 6.8% gross margin, delivering 57% of the Gross profits.
The other 8% of the revenue comes from Aftersales at a gross margin of 56% delivering therefore 43% of GP.
You could almost consider the COGS associated with new vehicle sales (51% of total revenues) as "pass through" as they don't really control the price and I don't think they have the credit risk.
NB this split is slightly distorted by the fact that the "Aftersales" profits include margins on work done to support the vehicle sales segment. (It doesn't material change the argument).
Agreed - it is a structural issue. But the great thing with new cars is that they don't need to hold stock, tie up working capital in inventory, etc. All the cars are made to order. And they are very big ticket items - AOV is huge.
I think a more relevant comparison would be to compare their margins to their peers - Pendragon, Inchcape, etc
Diesel cars are dead and huge stocks just for the crusher. And what do you do with bits of land which nobody wants and too small to build houses on. A mega warehouse somewhere and car gets delivered to your house on a trailer with all the 'add ons' - covid clean, diamond polish, service check etc. Big Motoring World around my way so no 'moat'. More modern areas to explore, leasing, short term hire, sharing - dunno but these day they are a changing. Live in London so have congestion charge and low emissions charge on a 2014 Audi, which will be worth 20p by year end.
My diesel is not dead. It has done 23000 miles and does 600 miles to a full tank. I won’t be changing to an electric car until this one drops or is banned. Many people think like this and will not be changing in a hurry!
NEW diesel purchases are almost dead - most people buy diesel to do lots of miles in so running cost saving from electric is big if you can charge easily /cheaply at home or work and do less than 200miles/day. Witness Amazon/UPS changing vans over so fast. Only if range between charges is frequently an issue is a large tank a big benefit (600miles = 12+ hours of driving!)
OLD diesel with only 23000 on the clock - probably environmentally good run for another 100,000 to avoid scrapping too soon....but expect your fuel costs to rise and to replace with electric.
Hi Gromley
Thank for the reply, oh by the way are you a holder?
Thanks Terry,
And yes I should have added a disclaimer as of Thursday I do have a small long position in Vertu Motors (LON:VTU)
It's not what I would call a "conviction holding"; but to be honest I'm not sure I even do those anymore.
I was thinking the same.
Yes Tony, I'm in the same camp as you. I pay Nil road tax on my diesel car which has 57,000 miles on the clock (diesels are generally good for at least 150,000). Furthermore, it does 66 miles to the gallon. I also won’t be changing to an electric or hydrogen car until this one drops or is banned.
Stephen Marks is 4 years younger than good old Jo Biden who is all set to spend 8 years in the White house : maybe unwise to anticipate SM will wheeze into a twilight home for rich geriatrics anytime soon!
Yet more bids this week. Marston's (LON:MARS) after three "quiet" bids the company finally admitted the offers earlier this week. Paul has covered the latest one today. So what is going on? It seems to me the ton of "free" money around (negative interest rates anyone?) is looking for a home. With vaccination powering ahead in the UK to over ten million now and summer approaching, funds seem itching to pile in to the bombed out sectors. My guess is they will take some of the companies private and then launch them again in a couple of years at many times the price paid.
I have been adding to City Pub (LON:CPC) (excellent recent statement) Foxtons (LON:FOXT) and old favorite Revolution Bars (LON:RBG) The latter turned down a bid of 200p a couple of years ago. I wonder if shareholders would now take 50 pence or so? A fantastic deal for someone if they would. To say young people are desperate to pile in to the pubs and clubs....I have a soon to be 19 year old who has never been to a nightclub. So much catching up to do! For all of us I guess.
My outside riskiest punt is Comptoir (LON:COM) owner operator of 24 Lebanese and Eastern Mediterranean restaurants. I am sure there are loads of possible targets that are at amazing "sale" prices....but perhaps not for long as soon as the "open" signs appear again. What a joy that will be!!
So how many of these "quiet" offers have been made? My guess is "a lot" and Paul has talked about why directors need to declare them in his columns recently. No recommendations intended by me of course.
May I add £QUIZ to that list? Floated at 161p just under 4 years ago. Now 9p. Must be some value here at that price for someone. Risky punt of course. Would a 25p to 30p offer look realistic?
I thought Quiz (LON:QUIZ) was a bargain value too. But upon digging further, they were struggling as a brand already pre-COVID. Their online operations are also sub-par compared to ASOS, Boohoo, etc.
Therefore, my view is while they will see an uplift once restrictions are lifted, soon they will be back to treading water or negative growth as the better players in cheap partywear outgun them in online. The one consolation is that they will have much less competition on the high street...
So for that reason, unlike strong brands like Joules (LON:JOUL) that will definitely thrive after lockdown, I am sitting on the sidelines with Quiz (LON:QUIZ) for now
Nice breakout on Vertu Motors (LON:VTU) off the back of the positive update, pushing through the buy zone.
Initial target for me would be the recent highs, giving +25% from the breakout level.
Today's volume is not seen on the chart (will be visible later), I'd be looking for volume to confirm the move has legs.
Red flag would be a reversal below the breakout level.
Update on £VTU.
Volume has come in, with a noticeable increase on previous days. Price accelerated up to hit the initial target in just 3 days. However, this is on the 'ask' (buy) price.
The 'bid' (sell) is still lower, peaking at around 41p.
Personally, I'm in the trade, and I'll be looking for momentum to continue, using the 21EMA as a trailing stop.
Paul’s advice on here, specs and face masks...... I appreciate this post may be deleted, but Paul a while ago suggested tape on face masks to prevent specs steaming up. Well in the supermarket this morning, I realised if you place face mask top rim, under the bottom of your spectacles lenses. They do not steam up. Sorry.
Pip.
Thanks for the tip, I'll have to try that.
Paul, I tried rubbing washing up liquid directly onto the glasses last week. just a fingerdrop - rubbed it to the inside (don't need outside since it's the inside that condenses). Then wipe off to remove smears. Worked very nicely - no condensing - used if for 3 hrs. Saves me the hassle of using tape.
my brother in law is an optician and says NEVER clean with washing up liquid as it has an additive which can remove coatings on lenses. Use standard bar soap to clean them as there is no additive in soap
Snorkel would work.;)
Used to use tiny spot of toothpaste on ski mask then rinse off. Works well but you do need to wash off well otherwise you end up with minty eyes.
FCCN would seem a fairly standard move for Boohoo, right? I'm surprised neither they or Mike Ashley are involved, after all Sports Direct must be one of the larger retailers of it now.
The brand I think could be a nice fit; I think it is a nice straddle between the teens to young man age categories.
Don't think it has the positioning it used to, but maybe it could be revitalised.
Re share placings - is it now beyond the wit of man to design and implement an electronic auction system for share placement that makes capital the same as other commodities ie bought/sold at best price the buyer/seller can get factoring in price/order size/quality of capital etc.
Clearly, a placing with institutions who buy 10Mn shares is cheaper than with a single investor who buys 100 (though not by much in a digital world where everything is pre-registered is automated like a credit card !!) Thus "insider" deals to big buyers could set a floor price for a menu of price blocks that could be offered to all and reflected cost; regulated competition would squeeze the small order premium very small over time. Companies would thus get slightly more from taking on the complexity of smaller shareholders and thus be taken seriously. As PI's, we may not like this but it is economically fair - and better than often being excluded.
Total system cost over time would also be much less (fewer costly bankers/brokers and intermediaries.....which is why change will need to come from an aggressive outsider within rules set up by and led by govt regulation (although principled & effective, thought-through regulations have not been a noticeable strength of the current mob!)
I think the problem with opening up to PIs is the very practical one of just how much money is available from the active private investor market ( ie excluding the amount in trackers, investment trusts, fund managers).
I have no hard evidence (does anyone?) as to what pool of funds any offerings are being made to, but I rather suspect that it is not deep enough to be reliable target for those seeking funds.. I would like to proved wrong but I suspect we are just too small.
Re PI investment pool being too small to warrant being a reliable target for those seeking funds comment - I probably agree, especially if you think about traded money (vs PI money locked up in Unilever-like shares for 20 years).....which is why the playing field will not/cannot/should not be level........but if things were digitalised they could be very slowly sloping and at least accessible :)
Good idea but so much of finance continues to be done the 'traditional' way. Having just switched my ISA from AJBell to IG I phoned yesterday to ask when the cash element (the shares having been transferred about 10 days ago) would be moved across and was told it would take several days while the cheque was being processed!?
piworld have just published Reg Hoare's Investment Trusts: An Investing Panacea for Pandemics Update. Reg spoke to us last May, giving a very comprehensive overview of ITs, what they are, selection criteria, what he held, the current market (then), etc, here (well worth a look if you haven't seen it). We've had numerous requests to follow-up with him. Here's the update, how 2020 played out for Reg; what he's been top-slicing, what he's been buying, and his #1 pick. Video & podcast. This is best watched with the original interview, which gives more insight to ITs.
Coventry shopping centre sells for knockdown £4.9m
https://www.thetimes.co.uk/article/18c524f4-6705-11eb-ab68-123bacbc1c7b?shareToken=aa9903e2b63d1430c1c38c422e37e977
Perhaps which extremely wise person gave me negative feedback for posting a relevant link could have the guts to explain why.
Or you could just ignore it, what's the point of screaming into the void?
I suspect whoever it was saw a link to the Times and thought it was no good for them because it was behind a paywall not realising that it was a guest link from a subscriber (evidenced by 'sharetoken' in URL).
I for one am grateful to you for using one of your tokens on us and gave you a thumbs up.
As an aside, does anyone know why LAs were encouraged to borrow to invest in commercial property, often hundreds of miles from their local patch? No doubt the property agents told them it was a good idea (at the time), and there's a strong herd mentality to LAs (witness the Icelandic banks fiasco), but even pre-covid rent crisis there were suggestions they may have acted hastily without proper risk assessment, eg https://www.getsurrey.co.uk/ne...
I expect central gov't money will bale them out. The council's policy statement says :
Why can't the money be spent directly on services?
The property investments are funded by money borrowed from the Public Works Loan Board. The law says Councils can only spend borrowed money on assets with a life of more than one year and where it is going to make a profit or save on existing costs. This means some of the money generated or saved can be used to meet borrowing costs. It would be illegal for Mole Valley to spend this money on day-to-day services.
The following comment is lifted from Sharecast's press summary this morning:
"...A shopping centre in Coventry that eight years ago was valued at £37
million was sold this week for only £4.9 million, setting alarm bells
ringing among lenders, landlords and local authorities nationwide..."
The original article is from the Times, which I assume is behind their paywall so I haven't tried to locate it, but it makes me very wary of buying REITs, even when they are available at a big discount to last reported NAV.
(Edit: Please note that my comment wasn't intended as a reply to Honey Badger's post re Warehouse Reit (LON:WHR) . Obviously, different REITs have differing types of estates, and research can still turn up some good value among REITs holding property less related to the analogue shopping experience).
Hi gtrdave,
Very interesting thanks.
I agree, I've decided not to go anywhere near any property companies that own retailing & similar properties. The actual value of some of these properties could be a small fraction of book value. Some might even have little to no value, and end up being pulled down, as we were discussing here the other day.
Warehousing is the place to invest, in property, in my view. And residential. I would look at those areas for investment. But definitely not retail space.
Regards, Paul.
bmmagazine.co.uk have an article on this, free to view
Morning Paul,
You've commented positively in the recent past Warehouse Reit (LON:WHR) (I hold) who have today announced another acquisition - two warehouses in Harlow for £14m at what looks like a very attractive yield and lots of room for growth. There is a separate announcement of an institution-only placing at 4% below yesterday's close (no pre-emptions) and plans to move from AIM to the main list. The placing is to fund a pipeline of new acquisitions.
I really like the sector: cheap-to-construct, simple boxes beside motorways, servicing the new doorstep delivery economy. Effectively, the new high street. I bought in the last placing about a year ago and its delivered a total return around 20%. What's not to like?
The question is, why exclude existing shareholders from the placing? Does it keep costs down - or are there other reasons? And do you see the shift from AIM to main list as an advantage? They cite putting themselves on a par with similar companies - does that mean they expect to get more institutional interest?
Grateful for any insight.
I'm a big fan of this sector and have shares in £WHR and £EBOX as its clearly a demand sector and they will give a nice return of 10-20% a year. My only concern medium to longer term is that given the returns some other companies are going to knock down their worthless shopping malls and convert them into warehouse space. This is not an easy thing to do as the infrastructure to the building would need to be very different (roads etc.) and thats why I see it more medium term.
I believe that placings are much cheaper when going out to institutions and to be fair the discount is tiny so I am not that bothered.
i think 20% a year would be a bit optimistic for Warehouse Reit (LON:WHR) with the share price having gone from 100 in January 2018 to a high of around 124 now. Add to that the current dividend of just over 5% and it's a healthy 13% for what should be a safe business. I know these warehouses are needed but there are so many companies both public and private building them right now that they must eventually catch up with demand. I did hold WHR but got out just below 118 when it appeared that after becoming directors two of the main men had formed another company, bought I think two warehouses and perhaps two years later sold them to WHR for many millions profit. Nothing wrong with that if WHR got good value, I am just getting a bit cynical (or envious) in my old age!
It depends. I hold Tritax Big Box Reit (LON:BBOX) and for the purchase in '16 got ~7%pa + divis and for another purchase in '19 got about 19% pa + divis (so far)
The current price feels a little full to me right now. It will never 'go to da moon' - equally as long as there is amazon prime etc, it is unlikely to halve.
On unused retail parks being converted to warehouses, possibly at the margin, but imo the higher probability is they get converted to houses / flats - more money in that, less planning resistance compared to a greenfield site, and a lot of infrastructure / transport links are in place.
I thought of Tritax EuroBox (LON:EBOX) but europe is big and empty compared to the UK and I know France supports new build so the barriers to entry are different there.
If you want to be more adventurous you could look at Russian warehouses at a large discount to NAV ,partly caused by a very large placing....Raven Property (LON:RAV)
Strange thing ms afoot at French Connection. big move up yesterday on nothing much.
Strange thing ms afoot at French Connection. big move up yesterday on nothing much.
To be precise, big move up on insider dealing:
The Board of French Connection Group Plc notes the recent share price movement and confirms that it has received separate approaches from each of Spotlight Brands in conjunction with Gordon Brothers International LLC ("Spotlight") and Go Global Retail in conjunction with HMJ International Services Ltd ("Go Global") as potential offerors for French Connection Group Plc, each of which may or may not result in an offer for the Company.
https://www.londonstockexchang...
Not that there'll be an investigation, much less any action, of course.
timarr
Thanks timarr. There was one suggestion that it was a short squeeze in FCCN but I cant see any shorts particularly, at least on research tree. Ive only held FCCN for about 4 billion years so wondering if I should count my chickens and jettison my holding..
My morning smallcap tweet:
Distribution Finance Capital Holdings (LON:DFCH) French Connection (LON:FCCN) Hargreaves Services (LON:HSP) Myanmar Investments International (LON:MIL) Falanx (LON:FLX) Sportech (LON:SPO) On The Beach (LON:OTB)
Distribution Finance Capital (DFCH) £40m placing at 55p, a 23% discount. Used to accelerate business plan and loan book growth [SP=70 Cap=78m]
French Connection (FCCN) re SP rise: bid approaches. Will Stephen Marks let go this time? [SP=16.5 Cap=16m]
Hargreaves Services (HSP) sells more land at Blindwells fro £9.3m min. [SP=280 Cap=90m]
Myanmar Investments (MIL) unsuspended. Was suspended after the coup. "The Company's two investments in the microfinance sector and mobile phone communication towers have so far not been directly affected by the recent events however it is too early to forecast the future impact on these investments." [SP=0.7 Cap=27m]
Falanx (FLX) £700k contract wins, £400k before Dec. Seeking CBIL loan for acquisitions and growth. [SP=1.21 Cap=6m]
Sportech (SPO) guides FY(Dec) adj EBITDA in line and cash at hand cash (excluding customer balances) ahead of expectations at c.£10.2m. Expects to raise £36.1m aggregate net cash from business sales and acquisitions. [SP=29 Cap=55m]
On the Beach (OTB) cash at hand end Jan £39m. Guidance still suspended [SP=355 Cap=559m]
Regarding the French Connection (LON:FCCN) news. After a quick search:
Spotlight Brands: Investment firm, Launched Aug 2020 with $500 million. Expected to back 10 to 20 companies with deals ranging from 50mill to 100mill.
Please find below a discussion on rules being considered by UK/Greece for foreign holidays this year. Sounds like two jabs plus a recent negative Covid test may be sufficient.
Obviously not ideal if you are near the back of the queue for Covid tests or have children you would like to go away with, who are currently even further back in the queue. But quite positive for Saga (LON:SAGA) and other companies generally targeting an older demographic.
"Government plans Covid vaccine passports to allow foreign holidays"
https://www.thetimes.co.uk/article/a9f62526-672e-11eb-908c-00b0fcb974f6?shareToken=1286cc4f4668a56f97da6df52c8283e4
Please find below a discussion on rules being considered by UK/Greece for foreign holidays this year. Sounds like two jabs plus a recent negative Covid test may be sufficient.
Rather downbeat update from On The Beach (LON:OTB) (I hold) as well this morning:
The first four months of our financial year have seen differing tiering levels across the UK, followed by the current nationwide lockdown and ban on international leisure travel. Clearly this has and continues to impact booking volumes and the Board believes that booking volumes will remain weak through H1 and into H2.
https://www.londonstockexchang...
I think working out when overseas holidays will kick off again and what the demand will be when it does is a bit of a guess, frankly.
timarr
Yes. It only takes the market to open up mid-August rather than say 6 weeks earlier at the start of July and a large chunk of the most profitable part of the summer season has gone.
It also remains to be seen whether there are changes to the school year, may be shorter summer holidays to try and catch up on the lost time.
So I do think that holiday companies focused on a customer base that is not too family oriented are likely to be the initial winners in the sector but the sector seems to still be very risky. It could all be derailed by shortages of vaccines or proliferation of variants that the vaccines are much less effective against.
Yeah, it's downbeat, but on the plus side, they're only burning £2m per month and have over a year of no sales in cash.
Pick 'em up cheap and tuck 'em away is my plan.
There may be a clear plan of the rules to get onto cruise ships like Saga (LON:SAGA)
But people take cruises so they can also stop at ports along the way. Those rules have not been clarified yet in Spain, Portugal, Italy, Greece, etc... can cruise passengers nip into busy ports for a day trip?
Especially with S.A. variant spreading in the UK. Especially with the UK variant taking on similar mutations to the S.A. variant. British tourists might be bargepoled for yet a while longer. Vaccines don't prevent you from getting the virus or spreading it - they just lessen the chance of severe or deadly symptoms.
If not - the appeal of a 10-14 days "cruise to nowhere" - anyone knows if people are still desperate enough to cruise to do that?